
 UAE Organic Food Market | 2026-2036
UAE Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Organic Food Market Insights
Single-serve and meal-kit bundling is repositioning how UAE households purchase organic produce, replacing bulk buying with portion-controlled freshness. Carrefour leverages its hypermarket footprint to anchor bundled organic vegetable boxes in Dubai and Sharjah. LuLu Group International competes through aggressive private-label pricing on organic grains and dairy. Organic Foods and Café sustains its premium positioning by controlling specialty store locations in high-income Emirates neighborhoods.
Organic food comprises agricultural products cultivated without synthetic pesticides, genetically modified organisms, or artificial fertilizers, relying instead on natural soil amendments and biological pest management to meet certified purity standards. The primary commercial purpose centers on delivering verified chemical-free nutrition to consumers prioritizing traceability and environmental stewardship. Fruits and vegetables occupy the dominant product category due to perishable replenishment cycles and visible freshness cues at retail. Supermarkets capture the largest distribution channel share by merging one-stop convenience with expanding organic shelf space. The food service end-use segment shows the steepest growth trajectory as hotel chains and restaurant groups mandate certified organic ingredients for sustainability commitments.
MOHAP enforces organic health claims and labeling standards for all food products sold within the UAE, while the Emirates Authority for Standardization and Metrology administers the UAE Organic Farming Scheme aligning local certification with international equivalency. These frameworks elevate compliance costs for importers but simultaneously strengthen consumer trust in logo-bearing products. Stakeholders must monitor whether MOHAP expands mandatory origin disclosure beyond current voluntary protocols, as this would reshape supplier qualification requirements across the Emirates.
Market Dynamics
Certification tightening by the Emirates Authority for Standardization and Metrology is restructuring supplier qualification requirements, forcing importers to absorb compliance costs while domestic farms scale organic acreage to capture premium positioning.
Growth Catalysts
- MOHAP Labeling Enforcement:Mandatory organic health claim verification strengthens consumer trust in logo-bearing products, reducing search friction for certified produce across Dubai and Abu Dhabi retail corridors.
- Hotel Chain Sustainability Mandates:Food service procurement teams at luxury properties now require certified organic ingredients for menu sourcing, creating institutional demand pull independent of retail cycles.
- Vertical Farming Adoption:Controlled-environment agriculture in Sharjah and Al Ain is shortening supply chains for leafy greens, enabling same-day harvest-to-shelf freshness that differentiates against imported organic produce.
Market Restraints
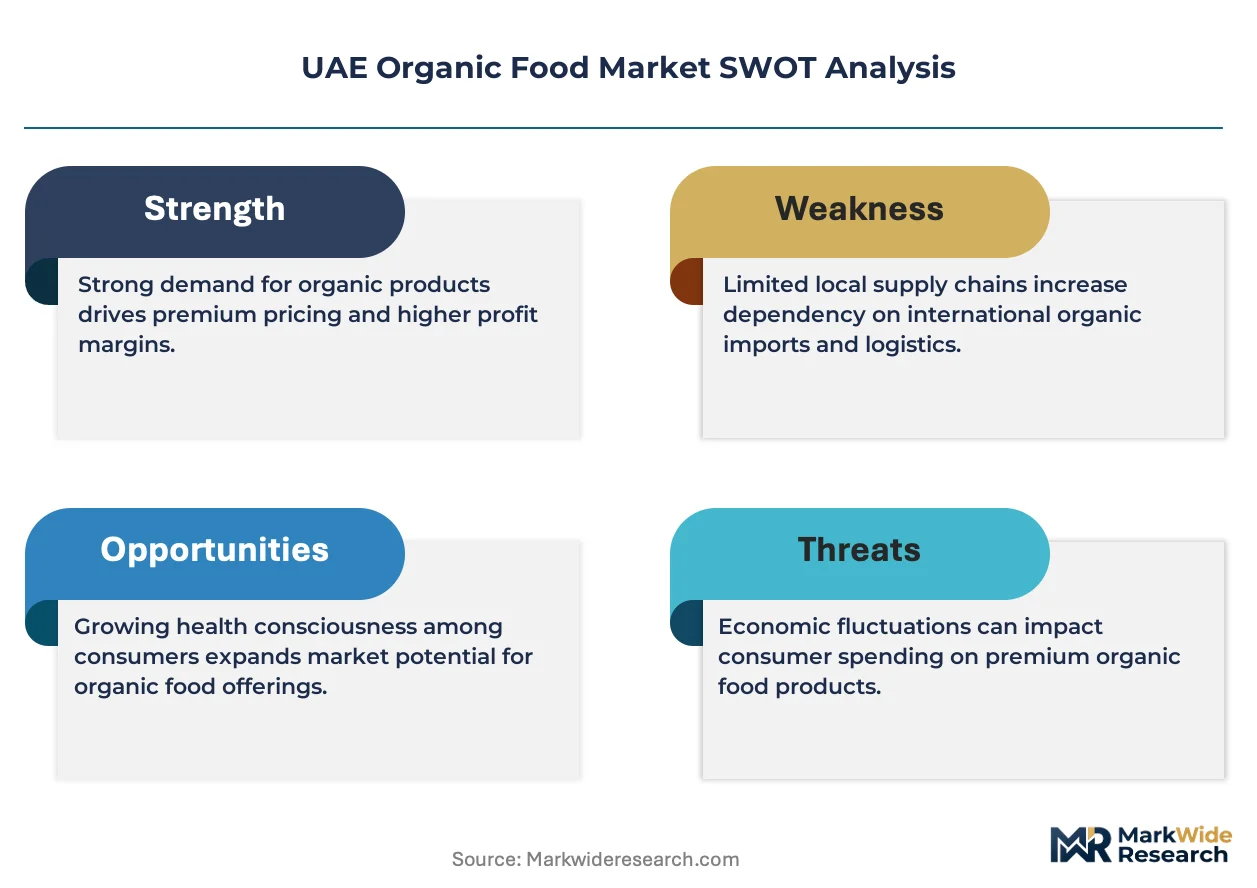
- Import Dependency Concentration:Over 80% of organic grains and dairy originate from European and Australian suppliers, exposing distributors to freight rate volatility and currency fluctuation risk.
- Arid Climate Water Constraints:Organic cultivation in the Emirates requires desalinated water inputs at 3-4x the cost of conventional farming, compressing margins for domestic producers competing against subsidized imports.
- Certification Timeline Friction:The UAE Organic Farming Scheme mandates 24-36 month conversion periods for conventional land, blocking rapid supply response to demand surges in premium retail segments.
Strategic Opportunities
- Meal-Kit Channel Expansion:Bundled organic vegetable boxes through subscription platforms target time-constrained expatriate households in Dubai Marina and Downtown Dubai, capturing recurring revenue streams beyond supermarket foot traffic.
- Al Ain Agricultural Zone Development:Government-backed organic farming clusters in the Eastern Region offer subsidized land and water allocations for producers seeking to reduce import dependency.
- Blockchain Traceability Integration:QR-code enabled provenance tracking is converging with retail loyalty programs, enabling supermarkets to command shelf space premiums through verified supply chain transparency.
Industry Challenges
- Certification Auditor Scarcity:The Emirates Authority for Standardization and Metrology maintains a limited roster of accredited inspectors, creating 6-9 month backlog delays for new farm certifications and product line extensions.
- Cold Chain Integrity Gaps:Temperature excursions during last-mile delivery in summer months degrade organic produce quality, forcing retailers to absorb spoilage costs or invest in refrigerated fleet expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Organic Food Market |
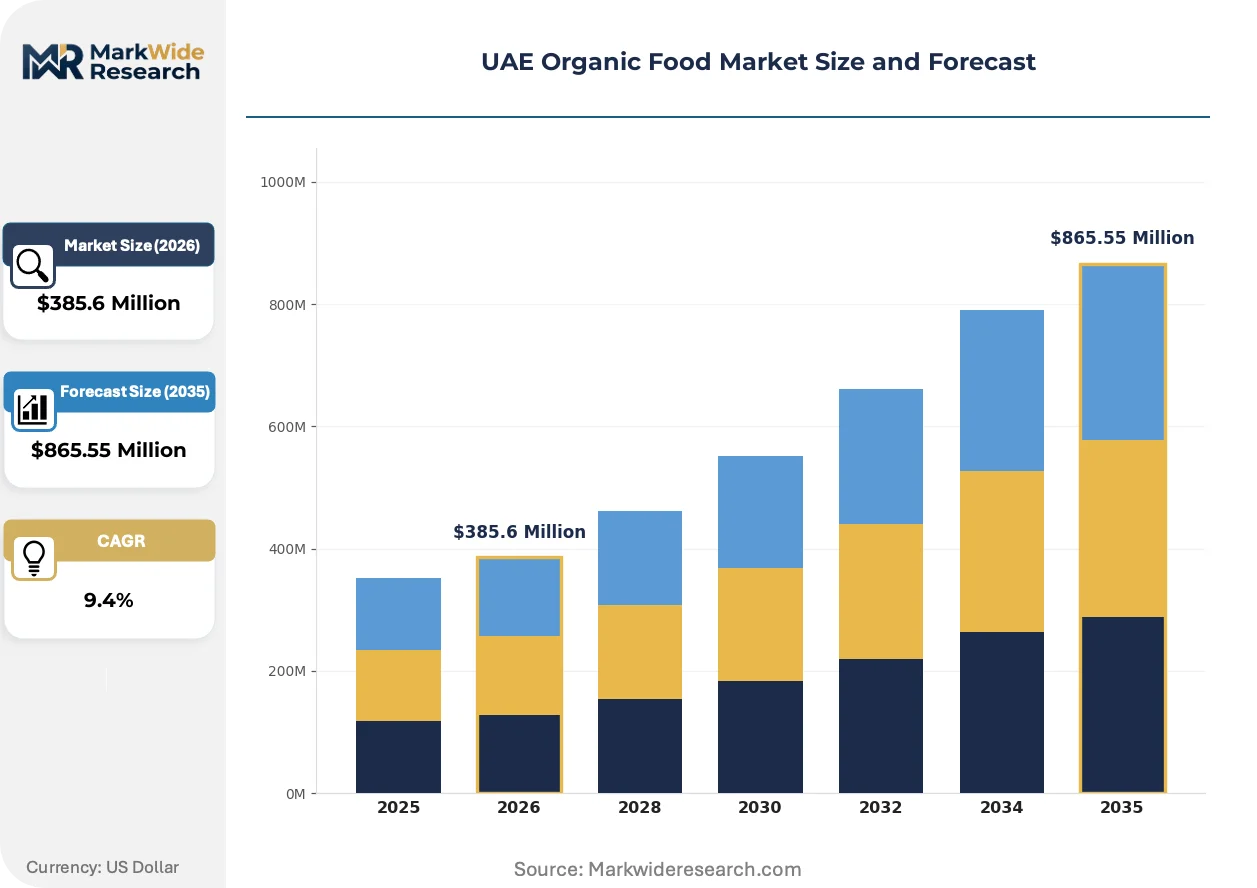
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $865.55 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy, Grains Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farmers' Markets Customer Type: Health-Conscious Consumers, Families, Vegetarians, Vegan End Use Industry: Retail, Food Service, Hospitality, Catering |
| Companies Covered | Green Heart UAE, Carrefour, Organic Foods and Café, Organic Valley, Gulf Organic Food General Trading LLC, LuLu Group International, NRTC Trading Company, Al Ain Farms, Union Coop, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Organic Food Market Trends and Innovations
Digital traceability infrastructure and controlled-environment agriculture are compressing traditional supply chain layers, while regulatory harmonization with European organic standards is opening export pathways for Emirates-certified producers.
Hydroponic and aeroponic cultivation systems are converging with solar-powered desalination units to enable year-round organic production in the Emirates' desert climate. Commercial operators in Dubai Industrial City and Ras Al Khaimah are deploying these integrated systems to supply hotels and hypermarkets with locally-grown leafy greens and herbs. The technology is converging with automated nutrient dosing to reduce labor intensity and standardize output quality for certification compliance.
MOHAP's alignment of organic labeling requirements with EU Regulation 2018/848 is streamlining import documentation for European suppliers while raising barriers for non-equivalent certification schemes. Food manufacturers reformulating for the Emirates market must now submit third-party audit reports to the national regulator. Dairy and processed food segments face the steepest compliance adjustments as origin disclosure rules tighten beyond voluntary protocols.
Subscription-based organic produce boxes are displacing traditional bulk purchasing among high-income expatriate households in Abu Dhabi's Al Reem Island and Dubai's Arabian Ranches. Portion-controlled freshness and recipe-guided bundling reduce household food waste while locking in recurring revenue for platform operators. This behavioral shift is most pronounced among dual-income families with limited time for traditional supermarket trips.
UAE Organic Food Market Segmentation
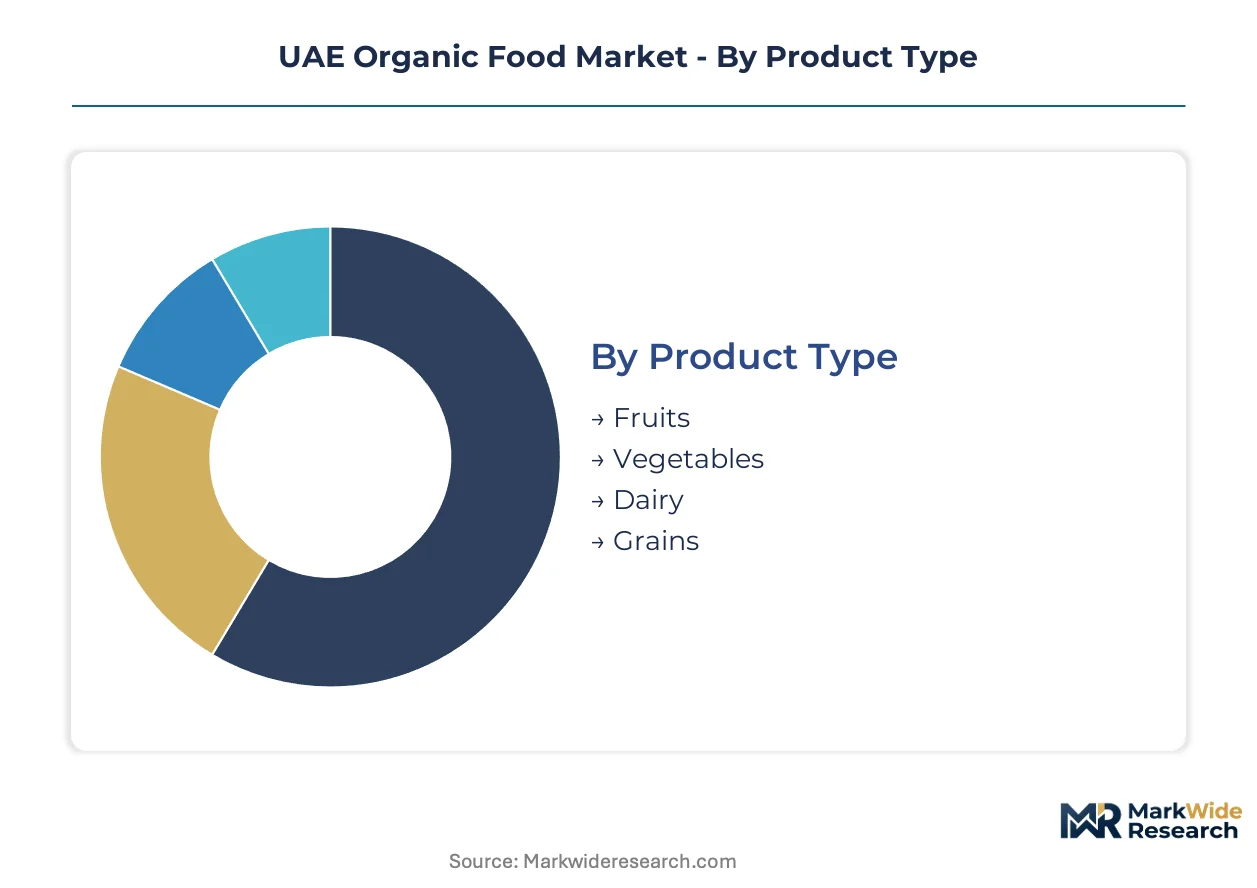
Organic food segmentation in the Emirates reveals how certification requirements, retail format economics, and end-use procurement standards create distinct commercial battlegrounds. Each category isolates a different dimension of buyer behavior—from household health priorities to institutional sustainability mandates.
Product Type:
Freshness tolerance and perishability windows separate buyer willingness-to-pay across organic categories.
- Fruits:Certified organic dates, citrus, and pome fruits dominate UAE retail shelves due to visible quality differentiation and shorter supply chains from regional growers. Demand clusters in Dubai's premium supermarkets where expatriate households prioritize pesticide-free produce for children.
- Vegetables:Leafy greens and cruciferous vegetables command the highest price premiums per kilogram, driven by hotel and restaurant procurement teams seeking same-day harvest freshness from Sharjah vertical farms.
- Dairy:Organic milk and yogurt face 80% import dependency from European and Australian suppliers, exposing distributors to freight volatility and extended cold chain requirements.
- Grains:Rice, quinoa, and ancient wheat varieties attract niche health-conscious buyers through specialty stores, though volume remains constrained by price sensitivity among mass-market households.
Volume sits with Vegetables; growth tilts toward Fruits as domestic cultivation expands.
Distribution Channel:
Convenience trade-offs against assortment depth and certification verification determine channel selection patterns.
- Supermarkets:Carrefour and LuLu anchor organic category development through dedicated shelf space and private-label expansion, capturing one-stop shoppers in Dubai and Sharjah. Their hypermarket footprint enables bundled vegetable boxes that reduce per-unit procurement costs for households.
- Specialty Stores:Organic Foods and Café sustains premium positioning through controlled locations in high-income Emirates neighborhoods, offering curated assortments and staff-assisted certification verification that justifies price markups.
- Online Retail:Subscription platforms target time-constrained expatriate households in Dubai Marina with portion-controlled meal kits, locking in recurring revenue beyond traditional foot traffic.
- Farmers' Markets:Weekend bazaas in Al Ain and Abu Dhabi provide direct farm-to-consumer traceability for certified produce, though scale remains limited by seasonal availability and logistics fragmentation.
Supermarkets capture transaction volume; Online Retail climbs the fastest as subscription models displace bulk purchasing.
Customer Type:
Dietary restriction severity and household composition drive frequency and basket size differentiation.
- Health-Conscious Consumers:Affluent expatriates in Arabian Ranches and Al Reem Island prioritize traceability and chemical-free nutrition, accepting 40-60% price premiums for certified products with MOHAP verification logos.
- Families:Dual-income households with children represent the core repeat-purchase segment, gravitating toward bundled organic boxes that reduce food waste through portion-controlled freshness.
- Vegetarians:Plant-forward buyers concentrate organic demand in protein alternatives and dairy substitutes, though this segment overlaps substantially with health-conscious positioning.
- Vegan:Strict plant-based consumers drive specialized demand for certified organic processed foods and ingredient inputs, requiring stricter supply chain audits than general organic standards.
Families dominate purchase frequency; Vegan buyers gain share fastest as restaurant menu expansion creates ingredient pull-through.
End Use Industry:
Procurement scale and certification mandate stringency separate institutional buyers from consumer-directed channels.
- Food Service:Hotel chains and restaurant groups now mandate certified organic ingredients for sustainability commitments, creating institutional demand independent of retail price sensitivity. Procurement teams at luxury Dubai properties source directly from Emirates Authority for Standardization and Metrology-certified farms.
- Hospitality:Resort properties in Ras Al Khaimah and beachfront hotels integrate organic menus into wellness tourism positioning, requiring consistent supply volumes that domestic vertical farming operations are scaling to meet.
- Retail:Supermarket and specialty store channels remain the volume foundation, though margin pressure intensifies as private-label expansion commoditizes basic organic categories.
- Catering:Corporate and event catering operators lag in organic adoption due to cost-plus pricing constraints and large-batch preparation requirements that complicate certified ingredient sourcing.
Retail holds volume concentration; Food Service shows the steepest expansion trajectory as procurement mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE's organic food market operates with a pronounced production-consumption gap, where domestic cultivation covers less than 20% of demand and import dependency shapes regional supply strategies across the Emirates.
Dubai
Expatriate households in Dubai Marina and Downtown Dubai drive premium organic demand through subscription meal kits and hypermarket bundled boxes. MOHAP labeling enforcement concentrates certified product verification in Dubai's retail corridors. Vertical farming clusters in Dubai Industrial City supply hotels with same-day harvest leafy greens.
Abu Dhabi
Al Reem Island dual-income families represent the core repeat-purchase segment for portion-controlled organic freshness. The Emirates Authority for Standardization and Metrology maintains its certification auditor roster in Abu Dhabi, creating processing backlogs for new farm approvals. Yas Island resort properties integrate organic menus into wellness tourism positioning.
Sharjah
Controlled-environment agriculture in Sharjah shortens supply chains for cruciferous vegetables targeting restaurant procurement teams. Government-backed organic farming zones offer subsidized land allocations to reduce import dependency. Sharjah's hypermarket footprint anchors Carrefour's private-label organic grain expansion.
Al Ain
The Eastern Region agricultural zone hosts domestic organic acreage scaling efforts with desalinated water inputs at premium cost structures. Al Ain Farms operates within this cluster, supplying certified dairy to Abu Dhabi retail channels. Weekend farmers' markets here provide direct farm-to-consumer traceability bypassing supermarket intermediaries.
Northern Emirates
Ras Al Khaimah beachfront hotels source organic ingredients for sustainability commitments, creating institutional demand independent of retail price sensitivity. Solar-powered desalination units enable year-round cultivation in this lower-cost land environment. Logistics fragmentation limits scale compared to Dubai and Abu Dhabi corridors.
UAE Organic Food Market Competitive Landscape
The competitive structure tilts toward retail-led consolidation with hypermarket chains and specialty store operators controlling shelf access and consumer trust mechanisms. Two strategic archetypes dominate: multinational hypermarket operators leveraging private-label expansion, and domestic specialty retailers sustaining premium positioning through controlled location strategies. Competitive moves concentrate on bundled product innovation and certification compliance speed rather than price warfare.
Within the retail operator tier, Carrefour and LuLu Group International exemplify scale-driven consolidation, while Organic Foods and Café occupies a position in the premium specialty segment. Green Heart UAE and Al Ain Farms represent domestic production-side anchors attempting to reduce import dependency through local certification. Gulf Organic Food General Trading LLC sits within the import-distributor archetype managing European and Australian supply relationships.
| Leading Market Players |
|---|
| Green Heart UAE |
| Carrefour |
| Organic Foods and Café |
| Organic Valley |
| Gulf Organic Food General Trading LLC |
| LuLu Group International |
| NRTC Trading Company |
| Al Ain Farms |
| Union Coop |
| Others |
Pricing and Supply Chain Analysis
Hotel procurement teams in Dubai and Abu Dhabi concentrate demand for certified organic ingredients, anchoring a contract-based pricing model where sustainability mandates override spot-market sensitivity. This buyer concentration compresses margins for distributors while rewarding domestic producers who achieve Emirates Authority for Standardization and Metrology certification.
Pricing Analysis
Margin tightening in the import-dependent tier reflects freight rate volatility and currency fluctuation exposure. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and harvest freshness window. Cost-down pressure on domestic producers accelerates because desalinated water inputs run 3-4x conventional farming costs. Food service buyers show least price sensitivity; mass-market households in Sharjah hypermarkets exhibit highest.
Supply Chain Analysis
Certification gating through the UAE Organic Farming Scheme creates 24-36 month conversion timelines that block rapid supply response. Geographic concentration draws from European and Australian suppliers for organic grains and dairy, with domestic vertical farms in Sharjah and Al Ain scaling for leafy greens. Raw material dependencies center on desalinated water, organic feedstock, and approved soil amendments. Single-source vulnerability runs through European dairy import channels. Distribution runs through hypermarket chains and subscription platforms serving expatriate corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE organic food sector sits in a controlled-environment agriculture transition, with hydroponic and aeroponic systems displacing open-field desert cultivation.
For Market Incumbents: Anchor shelf space control through exclusive supply partnerships with Emirates Authority for Standardization and Metrology-certified vertical farms in Dubai Industrial City. Invest in blockchain traceability infrastructure to defend against private-label commoditization from LuLu and Carrefour. Certification investment represents the priority lever for margin protection.
For New Entrants and Emerging Players: Enter via meal-kit subscription channels targeting dual-income families in Dubai Marina and Al Reem Island, the most penetrable segment given time-constrained purchasing patterns. White-space targets include organic infant nutrition and specialized vegan protein alternatives. A direct-to-consumer go-to-market angle bypasses hypermarket slotting fee barriers.
For Investors and Strategic Acquirers: The window for entry favors domestic production assets with active certification pipelines and secured water allocations. Long-term viability hinges on reducing import dependency as freight volatility persists. Acquisition targets should display integrated farming-processing capabilities. Watch for MOHAP expansion of mandatory origin disclosure as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Farm Capacity Expansion | Sharjah controlled-environment clusters shorten harvest-to-shelf cycles for hotel procurement. |
| Blockchain Traceability Integration | QR-code provenance tracking converges with Carrefour loyalty programs to command shelf premiums. |
| Private-Label Organic Line Extension | LuLu Group International leverages hypermarket footprint to capture price-sensitive mass-market households. |
| Meal-Kit Subscription Platform Launch | Portion-controlled freshness reduces food waste while locking recurring revenue from expatriate families. |
| Organic Certification Fast-Track Investment | Accelerated auditor engagement with Emirates Authority for Standardization and Metrology clears 6-9 month backlogs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hotel procurement directors, hypermarket category managers, vertical farm operations heads, and Emirates Authority for Standardization and Metrology certification officers combined with MOHAP labeling guidance documents, EU Regulation 2018/848 equivalency protocols, and import customs databases. Bottom-up farm-level production estimates triangulated against top-down retail channel revenue assessments.
Granularity-level modeling operated at product type, distribution channel, and end-use industry dimensions across the analysis window. CAGRs derived from segmented growth rate reconciliation with macroeconomic consumption indicators. Industry-specific forecast inputs included desalinated water cost trajectories and hotel chain sustainability mandate adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MOHAP regulatory expansion or sustained freight rate spikes. Model outputs reflect documented assumptions on certification timeline friction and import dependency persistence. A model refresh is warranted upon material change in Emirates Authority for Standardization and Metrology auditor capacity or vertical farm yield scalability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Japan Organic Food Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
Scandinavia Organic Packaged Food and Beverages Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Non-GMO Food Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Saudi Arabia Organic Food Market