
 Organic Maple Syrup Market | 2026-2036
Organic Maple Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Maple Syrup Market Insights
USDA Organic certification is collapsing the supplier pool as small-scale tappers exit rather than absorb compliance costs. Coombs Family Farms leverages multi-generational woodland holdings to sustain year-round organic inventory. Butternut Mountain Farms anchors its position through temperature-controlled bulk storage infrastructure across northern Vermont. Les Industries Bernard & Fils competes via Quebec's integrated federation grading system that standardizes density and color classification.
Organic maple syrup denotes sap harvested from Acer saccharum trees without synthetic pesticides or fertilizers, then boiled to 66.0–68.5 percent soluble solids content for shelf-stable viscosity. Its primary commercial purpose centers on clean-label sweetening for food manufacturers seeking non-cane alternatives. Pure Maple Syrup dominates value capture given premium positioning in specialty retail channels, while Maple Sugar extends fastest as powdered formats penetrate bakery ingredient supply chains. Glass Bottles concentrate margin pools in gift and export segments, though Pouches gain traction in foodservice portion-control applications.
USDA National Organic Program standards govern sap collection and processing protocols for US producers, while Quebec's Ministry of Agriculture enforces provincial grading under federal Canadian Organic Regime equivalency. FDA food labeling rules and CFIA organic integrity verification shape cross-border trade access and consumer transparency requirements. Stakeholders must monitor climate-driven sap flow variability and federation quota allocation shifts that threaten supply predictability regardless of demand trajectory.
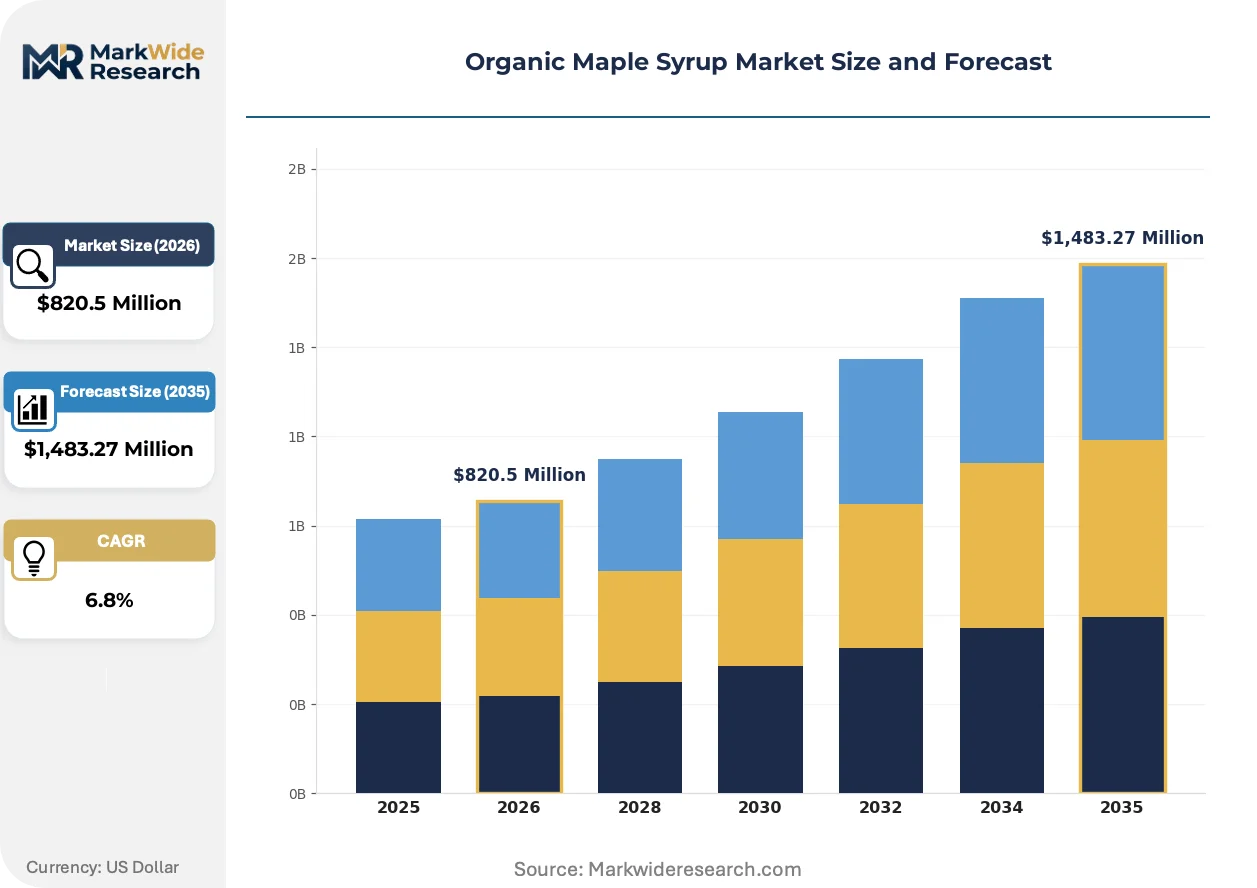
Market Dynamics
USDA Organic certification timelines are compressing the supplier base as small-scale tappers abandon operations rather than absorb compliance infrastructure costs. This structural force is redistributing production volume toward multi-generational woodland holders with existing organic inventory buffers.
Growth Catalysts
- Quebec Federation Grading Integration:The province's unified density and color classification system is accelerating cross-border export velocity by eliminating buyer uncertainty over quality variance.
- Clean-Label Bakery Reformulation:Food manufacturers seeking non-cane sweetener alternatives are pulling organic maple syrup into industrial ingredient supply chains at contract volumes previously reserved for commodity sugars.
- Vermont Sugaring Belt Infrastructure:Temperature-controlled bulk storage investments across northern Vermont are extending viable production windows and reducing seasonal inventory volatility.
Market Restraints
- Climate-Driven Sap Flow Variability:Warming winters and erratic freeze-thaw cycles are compressing viable tapping seasons and introducing yield unpredictability regardless of demand trajectory.
- Input Cost Concentration:Vacuum tubing and reverse osmosis equipment dependency creates capital intensity barriers that exclude small woodland operators from efficiency gains.
- Substitution by Coconut Sugar:Lower glycemic index positioning and tropical supply scalability are capturing clean-label bakery contracts that maple syrup once dominated.
Strategic Opportunities
- Pouch Format Foodservice Penetration:Single-serve flexible packaging is displacing traditional glass jug distribution in quick-service restaurant condiment programs.
- Maple Sugar Powder Bakery Integration:Dehydrated formats are penetrating industrial ingredient supply chains as direct replacements for refined cane sugar in cookie and pastry applications.
- Canadian Organic Regime Equivalency:CFIA-USDA mutual recognition agreements are reducing dual-certification burdens for Quebec exporters accessing US retail channels.
Industry Challenges
- USDA Organic Compliance Timeline Compression:Three-year land conversion requirements and documentation burdens are forcing operational restructuring before revenue recovery.
- Multi-Generational Knowledge Transfer:Traditional gravity-fed collection expertise is eroding as automated vacuum systems displace manual tapping practices.
- Cross-Border Label Integrity Verification:FDA and CFIA divergent organic claim enforcement creates recall exposure for dual-market distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Maple Syrup Market |
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,483.27 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Maple Syrup, Maple Cream, Maple Sugar, Maple Extract Packaging Type: Glass Bottles, Plastic Jars, Tins, Pouches Distribution Channel: Supermarkets, Online Retail, Farmers' Markets, Specialty Stores End User: Households, Restaurants, Food Manufacturers, Bakeries |
| Companies Covered | Coombs Family Farms, Butternut Mountain Farms, Les Industries Bernard & Fils, Maple Joe, Ferguson Farm Vermont Maple Syrup, Vermont Pleasant Valley Maples, Golden Dog Farm LLC, Canadian Organic Maple Co. Ltd., Branon Family Maple Orchards, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Maple Syrup Market Trends and Innovations
Processing technology and packaging format evolution are fragmenting traditional supply relationships while regulatory harmonization attempts create new compliance architectures. These forces are compressing legacy competitive advantages rooted in woodland scale alone.
Micro-scale reverse osmosis concentration units are fragmenting the historical dominance of centralized evaporator cooperatives. Small woodland operators in Vermont and Quebec are adopting skid-mounted RO systems that reduce boiling fuel costs by sixty percent before syrup enters finishing pans. This technology is fragmenting volume aggregation patterns that once favored federation-aligned producers.
CFIA organic integrity verification protocols are tightening cross-border documentation requirements for Quebec exporters. The federal regulator's blockchain-traceability pilot for maple products is forcing cooperative investment in sap-source tagging infrastructure. Bulk syrup importers in the US Northeast are responding by demanding batch-level certification affidavits that extend liability upstream.
Foodservice procurement is consolidating around portion-controlled pouch formats that reduce waste and labor in quick-service kitchen environments. Distributors are replacing multi-gallon jug programs with single-serve flexible packaging that eliminates open-container spoilage. This shift is most visible in US Northeast institutional feeding contracts where maple syrup competes directly with artificial pancake syrup on unit-economics grounds.
Organic Maple Syrup Market Segmentation
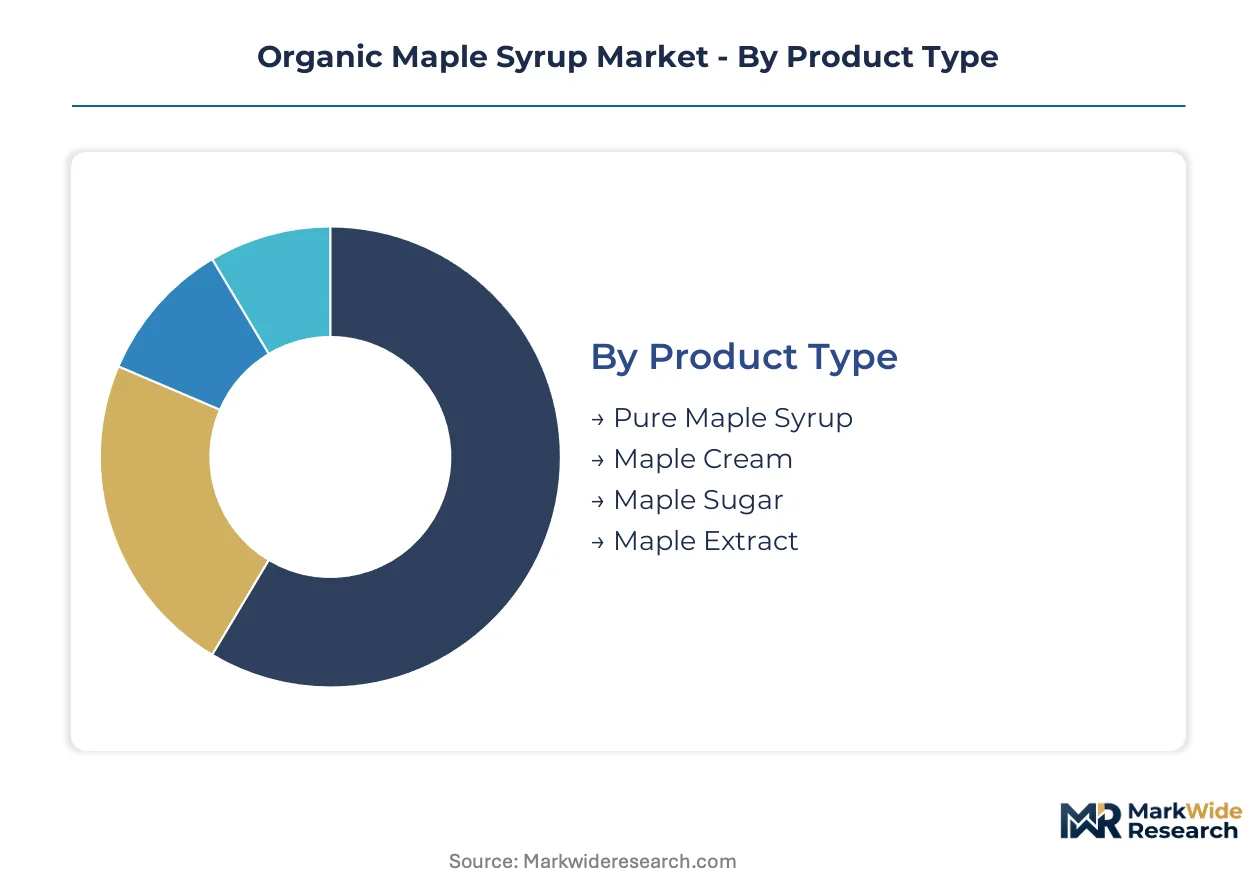
Organic maple syrup demand fragments across product formats, packaging economics, channel access, and end-user specifications. Each segmentation layer carries distinct substitution vulnerabilities and margin profiles that reshape competitive positioning.
Product Type:
Coconut sugar and agave nectar pressure liquid formats most intensely, while powdered and concentrated derivatives face milder substitute threats.
- Pure Maple Syrup:Unadulterated boiled sap meeting 66.0–68.5 percent soluble solids specification. Retail shelf placement in Vermont co-ops and Quebec dépanneurs sustains premium positioning despite cane sugar price undercutting.
- Maple Sugar:Dehydrated crystalline format produced through controlled evaporation to sub-4 percent moisture. Industrial bakery ingredient contracts in Montreal and Boston drive fastest expansion as clean-label cane replacements.
- Maple Cream:Soft spreadable emulsion of syrup and butterfat. Specialty gift markets in New England sustain niche volume.
- Maple Extract:Concentrated flavoring compound for processed food applications. Natural flavoring regulatory thresholds under FDA 21 CFR 101.22 govern permissible labeling claims.
Pure Maple Syrup retains volume leadership; Maple Sugar holds the steepest expansion curve.
Packaging Type:
Cost-to-weight ratios and breakage liability stratify format selection across channel tiers.
- Glass Bottles:Traditional molded containers with metal lug caps. Gift segment concentration in duty-free Quebec border outlets and Vermont agritourism retail sustains margin premiums despite freight cost penalties.
- Pouches:Flexible laminated film with spout fitments. Quick-service restaurant condiment programs across US Northeast institutional feeding contracts are displacing rigid jug formats.
- Plastic Jars:PET or HDPE containers with tamper-evident closures. Mass-market supermarket penetration in Ontario and upstate New York balances durability against shelf aesthetics.
- Tins:Rolled steel containers with lever-lock lids. Export markets to Japan and Germany favor extended shelf stability and shipping resilience.
Glass Bottles command premium positioning; Pouches gain share fastest in foodservice conversion.
Distribution Channel:
Direct producer access versus intermediary control shapes price realization and certification verification burden.
- Supermarkets:Conventional grocery retail with centralized distribution. USDA Organic and Canadian Organic Regime dual-certification requirements dominate shelf entry protocols.
- Specialty Stores:Natural food retailers and gourmet provisions. Quebec federation grading seals and Vermont maple law compliance function as category gatekeepers.
- Online Retail:Direct-to-consumer and third-party marketplace fulfillment. Temperature-controlled logistics requirements constrain ambient shipping economics.
- Farmers' Markets:Producer-direct seasonal vending. Vermont's mandatory maple product labeling law and Quebec's provincial grading enforcement apply variably by jurisdiction.
Supermarkets aggregate largest volume; Specialty Stores expand most quickly on clean-label curation.
End User:
Ingredient specification stringency and contract scale separate industrial procurement from discretionary household purchase.
- Food Manufacturers:Industrial ingredient buyers for processed food and beverage reformulation. Bulk tanker deliveries with batch-level organic certification affidavits dominate procurement protocols.
- Bakeries:Artisan and commercial baking operations. Maple sugar powder integration into cookie and pastry applications displaces refined cane in premium product lines.
- Restaurants:Foodservice operators from quick-service to fine dining. Pouch format portion control reduces open-container spoilage in high-volume pancake and breakfast segments.
- Households:Consumer retail purchasers for home culinary use. Seasonal purchasing patterns concentrate in Vermont sugaring season and Quebec spring harvest marketing windows.
Food Manufacturers capture contract volume leadership; Bakeries climb fastest on ingredient substitution trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Saint Lawrence Seaway's deep-water ports at Montreal and Quebec City anchor North American organic maple syrup export logistics, while Interstate 89's refrigerated trucking corridor threads Vermont's sugaring belt to Boston and New York distribution hubs.
United States
Vermont's sugaring belt generates the bulk of domestic certified organic supply. USDA National Organic Program land conversion timelines compress small-operator participation. Temperature-controlled bulk storage infrastructure across Franklin and Lamoille counties extends viable production windows beyond traditional March-April harvest peaks.
Canada
Quebec's Saint-Lawrence Valley cluster dominates global organic maple syrup volume. The province's Ministry of Agriculture enforces grading standards under Canadian Organic Regime equivalency with USDA. Federation-aligned producers in Montérégie and Centre-du-Québec standardize density and color classification for cross-border export velocity.
Japan
Premium gift market demand concentrates in Tokyo and Osaka metropolitan retail channels. METI import standards govern food additive thresholds and organic claim verification. Specialty department stores in Ginza and Shinsaibashi stock glass-bottle formats for seasonal gifting cycles.
Germany
Natural food retail chains in Bavaria and Baden-Württemberg drive continental European organic maple syrup distribution. EFSA organic labeling requirements and BVL import inspection protocols shape market access. Munich-based distributors aggregate volume for re-export to Austria and Switzerland.
United Kingdom
Clean-label bakery reformulation trends in London and Southeast England pull organic maple sugar into industrial ingredient supply chains. FSA organic integrity verification and post-Brexit UKCA marking requirements complicate Quebec exporter documentation. Specialty retailers in Borough Market and Shoreditch curate premium single-origin formats.
Organic Maple Syrup Market Competitive Landscape
Listed leaders compete with private specialists across multi-generational woodland holdings and federation-aligned cooperative structures. The supplier base concentrates around family-owned operations with existing organic inventory buffers rather than consolidated corporate platforms. Two strategic archetypes dominate: multi-generational woodland holders leveraging contiguous forest parcels for year-round organic certification maintenance, and federation-integrated Quebec producers utilizing provincial grading standardization for export scale. Competitive moves center on temperature-controlled storage infrastructure deployment and reverse osmosis technology licensing to fragment traditional cooperative aggregation patterns.
Among multi-generational woodland holders, Coombs Family Farms and Butternut Mountain Farms exemplify the archetype of contiguous forest parcel operators sustaining organic certification across decades-long land management cycles. Les Industries Bernard & Fils occupies a position within Quebec's federation-integrated tier, representing the provincial grading standardization model that eliminates buyer uncertainty over density and color variance. These three anchors illustrate the geographic bifurcation between Vermont's sugaring belt infrastructure investments and Quebec's centralized federation governance systems.
| Leading Market Players |
|---|
| Coombs Family Farms |
| Butternut Mountain Farms |
| Les Industries Bernard & Fils |
| Maple Joe |
| Ferguson Farm Vermont Maple Syrup |
| Vermont Pleasant Valley Maples |
| Golden Dog Farm LLC |
| Canadian Organic Maple Co. Ltd. |
| Branon Family Maple Orchards |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Quebec federation-aligned producers and US Northeast bulk distributors lock in both supply access and price visibility across multi-season production cycles. These arrangements insulate buyers from climate-driven yield volatility while securing predictable revenue streams for woodland operators facing USDA Organic certification conversion timelines.
Pricing Analysis
Volume-discount tiering structures separate USDA Organic-certified syrup from conventional grades and further stratify by Quebec federation density classifications. Glass-bottle gift formats command the widest premiums in Tokyo department stores and Vermont agritourism retail. Pricing pressure stems from coconut sugar substitution in clean-label bakery contracts. Food manufacturers exhibit the highest price sensitivity due to ingredient cost benchmarking against cane sugar, while Japanese gift buyers show the lowest.
Supply Chain Analysis
Canada and the United States anchor global organic maple syrup production, with Quebec's Saint-Lawrence Valley cluster and Vermont's sugaring belt generating the dominant share of certified volume. Sap collection draws from Acer saccharum stands requiring vacuum tubing and reverse osmosis equipment inputs. Single-source vulnerability concentrates in climate-sensitive March-April harvest windows. Distribution runs through Montreal and Quebec City deep-water ports for Asian and European export, with Interstate 89 refrigerated corridors feeding US Northeast retail and foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as clean-label bakery reformulation splinters procurement requirements across ingredient specification tiers. Small woodland operators with existing organic buffers can capture niche contract volumes that federation-aligned cooperatives overlook.
For Market Incumbents: Secure temperature-controlled bulk storage capacity across northern Vermont and eastern Quebec to extend viable production windows beyond traditional harvest peaks. Invest in blockchain-traceability infrastructure to preempt CFIA organic integrity verification requirements. Vertical integration into reverse osmosis equipment licensing fragments cooperative aggregation patterns that historically concentrated volume. For New Entrants and Emerging Players: Lead with maple sugar powder formats targeting industrial bakery ingredient supply chains in Boston and Montreal where clean-label cane replacement demand concentrates. Pouch-format foodservice contracts in US Northeast quick-service restaurant programs offer the most penetrable white space. Direct-to-producer online retail bypasses supermarket dual-certification barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among multi-generational woodland holders with contiguous forest parcels sustaining decades-long organic certification cycles. Long-term viability hinges on climate adaptation infrastructure rather than yield expansion. Target acquisition archetypes include federation-integrated Quebec producers with established export grading protocols. The signal to watch is CFIA-USDA mutual recognition agreement implementation reducing dual-certification burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Traceability Infrastructure Investment | CFIA organic integrity verification pilots force cooperative sap-source tagging compliance. |
| Reverse Osmosis Technology Licensing | Skid-mounted concentration units fragment historical evaporator cooperative dominance. |
| Pouch Format Foodservice Expansion | Single-serve packaging displaces rigid jugs in quick-service restaurant condiment programs. |
| Maple Sugar Powder Capacity Addition | Dehydrated formats penetrate industrial bakery supply chains as clean-label cane replacements. |
| Temperature-Controlled Storage Deployment | Bulk infrastructure across Vermont extends production windows beyond March-April peaks. |
Research Methodology
A spread of perspectives from federation procurement officers, USDA Organic certification auditors, food manufacturer ingredient buyers, and Quebec woodland operators converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from Canadian Organic Regime documentation, FDA food labeling filings, USDA National Organic Program standards, and Quebec Ministry of Agriculture grading protocols. Bottom-up volume estimates from producer-reported tap counts and top-down demand calibration from foodservice distributor procurement data generated convergent projections.
Segmentation dimensions modeled include product format, packaging economics, distribution channel access, and end-user specification stringency across the analysis window. CAGRs derived from historical price-realization trends and forward contract volume commitments. Climate-driven sap flow variability and federation quota allocation shifts factored as supply-side constraints.
Forecasts assume regulatory continuity in USDA National Organic Program and Canadian Organic Regime equivalency arrangements; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in climate adaptation infrastructure deployment and cross-border organic integrity verification protocol harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
Organic Fruit Powder Market
Organic Food and Beverages
Organic Juice Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Spain Organic Food Market
Organic Food and Beverages
Australia Organic Food Market
Organic Food and Beverages
Organic Fast Food Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
Italy Organic Food Market
Organic Food and Beverages
Global Organic Packaged Food Market
Organic Food and Beverages
Organic Superfood Market