
 Organic Yeast Market | 2026-2036
Organic Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Yeast Market Outlook
Asset-light contract fermentation is rewriting competitive economics for mid-tier entrants who lack capital for certified organic bioreactor networks. Lesaffre leverages its integrated strain banks and global distribution to sustain premium positioning across European and North American bakeries. Angel Yeast anchors volume production in Asia through captive molasses supply and state-controlled organic feedstock quotas. Lallemand competes on R&D intensity, maintaining active dry yeast viability patents that extend shelf-life advantages for export logistics.
Organic yeast comprises Saccharomyces cerevisiae strains cultivated on certified organic substrates—typically beet molasses or grain-derived feedstocks—under conditions prohibiting synthetic fertilizers, pesticides, or genetically modified inputs, yielding viable cell counts exceeding 10 billion CFU per gram in active dry formats. Its primary commercial purpose centers on leavening baked goods, fermenting beverages, and fortifying nutritional products with B-complex vitamins and complete proteins. Baker's yeast occupies the dominant margin pool given scale economies in artisan and industrial bakery supply chains, while nutritional yeast segments into the fastest-expanding category as plant-based dietary supplement formulators seek organic-certified flavor and fortification inputs. Brewer's yeast retains mature demand tied to craft beer proliferation, though organic certification premiums compress margins relative to conventional malt fermentation inputs.
USDA organic certification and EU Regulation 2018/848 govern substrate sourcing and processing integrity, with FDA oversight applying to nutritional yeast label claims in the United States. The EU Green Deal's pesticide reduction targets tighten organic yeast substrate availability, elevating input costs for non-vertically integrated producers. Stakeholders must monitor Farm to Fork implementation timelines and substrate substitution research to secure supply continuity.
Market Dynamics
EU Regulation 2018/848 substrate traceability mandates are compressing supply options for non-integrated organic yeast producers while accelerating backward integration investments across European fermentation facilities.
Growth Catalysts
- EU Green Deal Farm to Fork:Pesticide reduction targets tighten organic feedstock availability, advantaging producers with captive beet molasses supply chains in Germany and France.
- Clean-label bakery demand:European artisan and industrial bakeries are reformulating recipes to eliminate synthetic additives, pulling certified organic yeast volumes upward in bread and pastry applications.
- Plant-based nutrition expansion:Nutritional yeast formulators seek organic-certified B-complex fortification inputs for vegan dietary supplements and savory flavor alternatives.
Market Restraints
- Organic substrate cost volatility:Certified beet molasses and grain-derived feedstock prices fluctuate with weather-dependent harvests and organic acreage constraints.
- Supply concentration in EU processing:Germany and France host the majority of certified organic bioreactor capacity, creating geographic vulnerability for North American and Asian buyers.
- Genetic modification prohibitions:USDA organic and EU organic standards ban GM strain optimization, limiting yield improvements available to conventional yeast producers.
Strategic Opportunities
- US nutritional yeast underpenetration:American plant-based supplement and functional food brands show accelerating demand for organic-certified savory flavor and protein fortification inputs.
- Contract fermentation services:Asset-light toll manufacturing models allow mid-tier entrants to access certified organic capacity without capital deployment into bioreactor networks.
- Active dry yeast shelf-life extension:Viability preservation technologies enable longer export logistics chains, opening distant markets to European and North American production origins.
Industry Challenges
- Certification timeline compression:USDA organic and EU organic approval cycles for new substrate sources and processing facilities extend 18-36 months, delaying product launches.
- Strain bank IP complexity:Proprietary Saccharomyces cerevisiae lineages developed for organic stress tolerance require licensing negotiations or independent R&D investment.
- Bioreactor sterilization without synthetic inputs:Organic-compliant clean-in-place protocols demand heat and mechanical methods that reduce batch throughput versus chemical sanitization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Yeast Market |
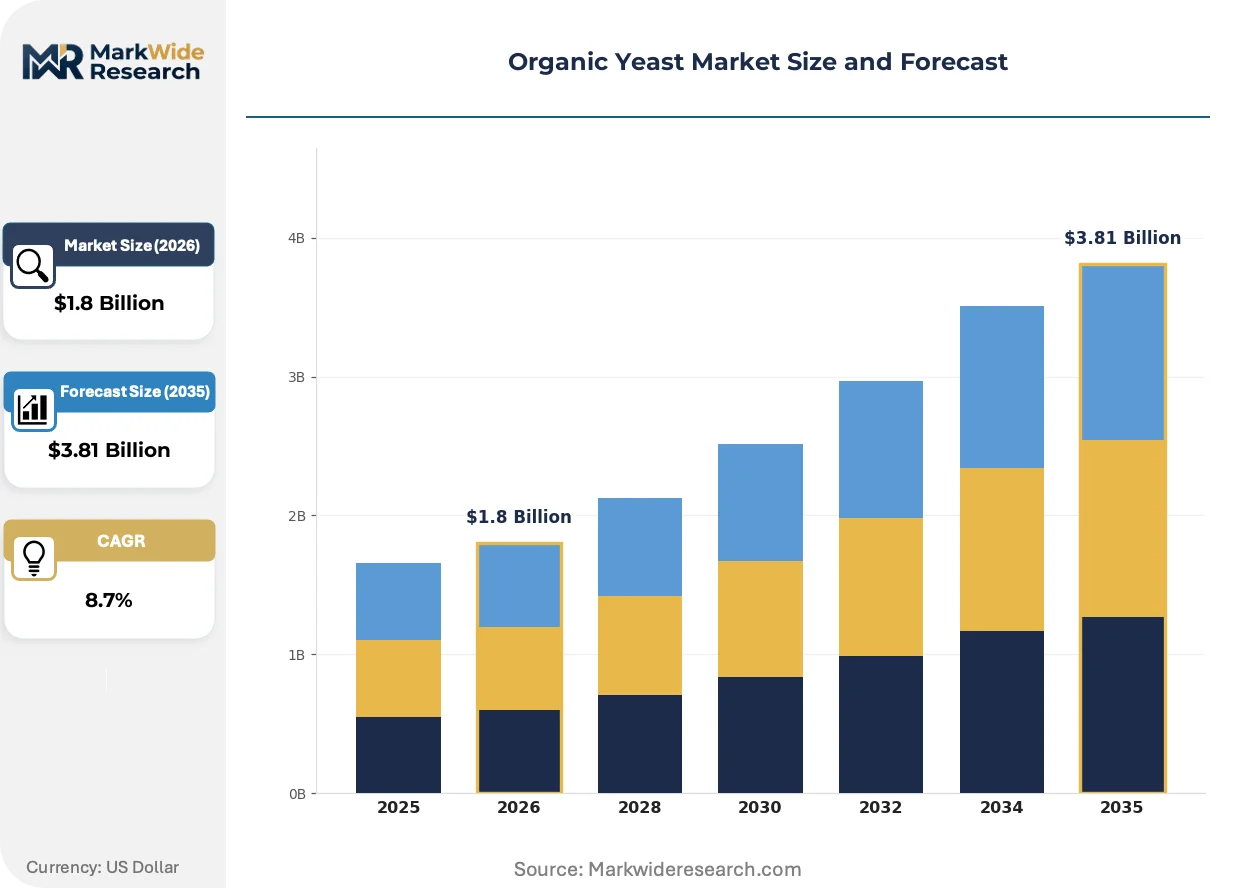
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baker's Yeast, Nutritional Yeast, Brewer's Yeast, Wine Yeast End User: Bakeries, Breweries, Food Manufacturers, Nutraceutical Companies Form: Dry, Liquid, Active Dry, Instant Application: Baking, Fermentation, Dietary Supplements, Brewing |
| Companies Covered | Lesaffre, Lallemand, Angel Yeast, Biospringer, Ohly, Leiber GmbH, Koninklijke DSM, Biorigin, Red Star Yeast Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Yeast Market Strategic Shifts
Digital monitoring systems and regulatory data architectures are restructuring how organic yeast producers demonstrate compliance and optimize fermentation yields across distributed supply chains.
Inline spectroscopy and IoT sensor arrays are digitizing real-time biomass density and viability tracking during organic fermentation runs. Mid-scale European producers are deploying these systems fastest to minimize batch failure rates given organic substrate cost premiums. The technology is digitizing quality assurance documentation for EU organic certification audits, compressing compliance labor hours.
EU Regulation 2018/848 electronic traceability databases will mandate substrate origin documentation from farm to fermentation vessel. This forces ingredient suppliers to adopt blockchain or centralized ledger systems for organic molasses and grain feedstock certification. German yeast processors are investing earliest to avoid supply disqualification under tightened Farm to Fork implementation timelines.
Bakery procurement teams now specify organic yeast with attached carbon intensity disclosures and regenerative agriculture credentials. Industrial bread manufacturers in France and artisan cooperatives in Italy are qualifying suppliers through sustainability scorecards rather than price-only tenders. This behavioral shift concentrates contract volumes with vertically integrated producers controlling organic substrate sourcing.
Organic Yeast Market Segmentation
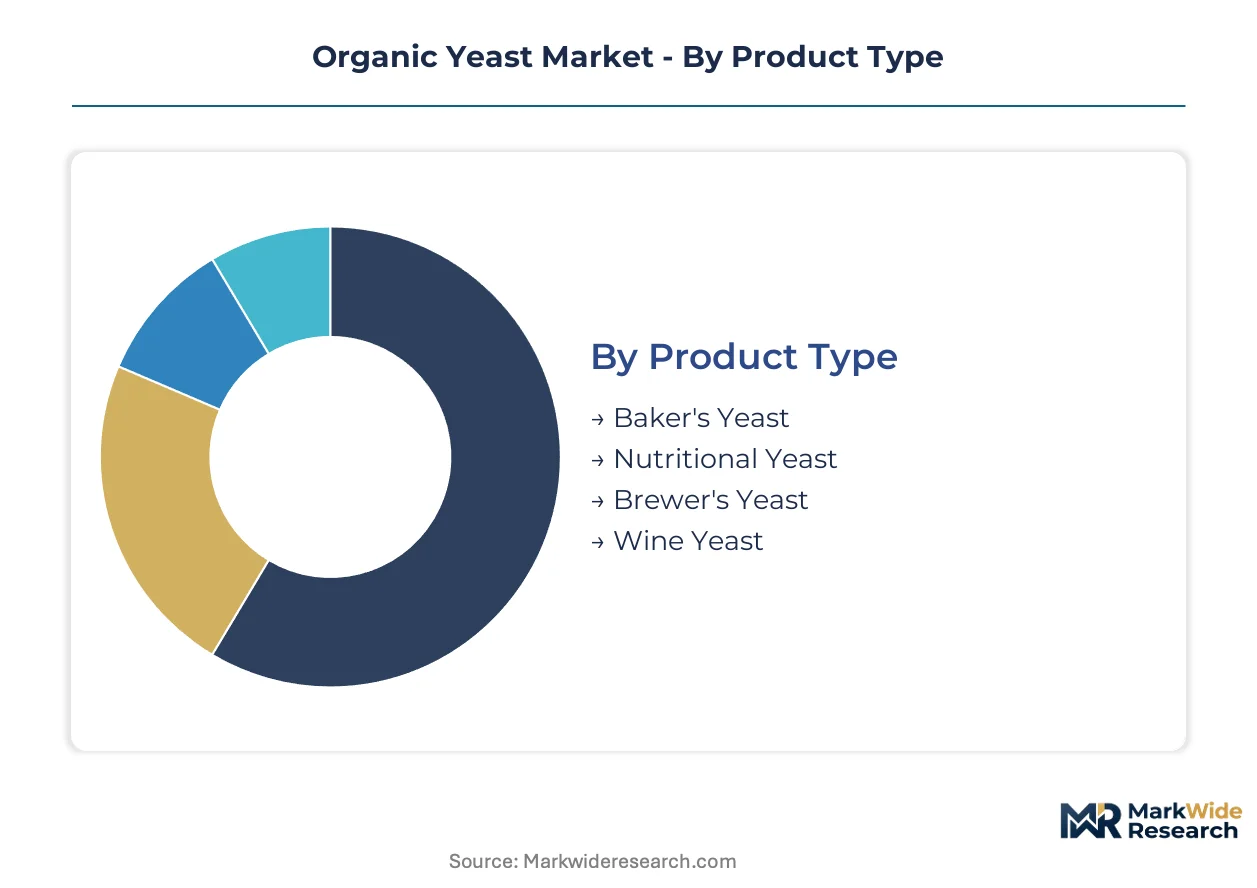
Organic yeast segmentation reveals how substrate certification requirements and end-use performance specifications fragment production economics. Each dimension—product chemistry, customer procurement scale, physical format, and application environment—imposes distinct compliance and logistics constraints on suppliers.
Product Type:
Cost tiers separate commodity-grade fermentation inputs from premium-certified nutritional fortification strains.
- Baker's Yeast:Saccharomyces cerevisiae strains selected for rapid CO2 production in dough matrices, with organic certification commanding price premiums in German and French industrial bakery supply chains where clean-label reformulation is mandatory. Margin pools concentrate here due to volume scale in artisan and industrial bread production.
- Nutritional Yeast:Inactive dried yeast cultivated for complete protein and B-vitamin density, with demand accelerating among US plant-based supplement formulators seeking organic-certified savory flavor alternatives. This segment is gaining share fastest as vegan dietary fortification expands.
- Brewer's Yeast:Strains optimized for maltose metabolism in beer fermentation, retaining mature demand tied to craft brewery proliferation though organic certification premiums compress margins versus conventional inputs.
- Wine Yeast:Specialized Saccharomyces bayanus and cerevisiae lineages for alcohol tolerance in grape must, with organic certification requirements tightening under EU Farm to Fork substrate traceability mandates.
Baker's yeast holds installed capacity. Nutritional yeast is rotating up the share rankings.
End User:
Customer procurement scale and certification sophistication stratify supplier relationships from spot purchases to multi-year substrate traceability contracts.
- Bakeries:Ranging from Italian artisan cooperatives to French industrial bread manufacturers, these buyers now qualify suppliers through sustainability scorecards rather than price-only tenders, concentrating volumes with vertically integrated producers controlling organic molasses sourcing.
- Food Manufacturers:Processed organic baked goods and savory snack producers require consistent active dry yeast viability across extended supply chains, with FDA label claim compliance adding US regulatory complexity.
- Breweries:Craft beer producers in North America and Europe drive demand for organic-certified brewer's yeast, though smaller batch sizes limit contract negotiation leverage versus industrial bakery buyers.
- Nutraceutical Companies:Dietary supplement formulators specify organic yeast with attached carbon intensity disclosures, with procurement teams prioritizing regenerative agriculture credentials alongside certification.
Bakeries command the largest contract volumes. Nutraceutical companies are expanding most quickly as a customer class.
Form:
Physical state determines storage logistics, rehydration protocols, and viable cell count preservation across distribution distances.
- Active Dry:Dehydrated granules with 10 billion CFU per gram viability, dominating export logistics due to shelf-life advantages that Lallemand and competitors protect through patented preservation technologies.
- Instant:Finer particle size enabling direct dough incorporation without rehydration, preferred by high-throughput industrial bakeries in Germany where batch time reduction drives operational economics.
- Dry:Conventional dehydrated formats with longer fermentation activation times, retaining share in price-sensitive segments and developing market applications.
- Liquid:Cream yeast requiring refrigerated distribution chains, concentrated in regional European supply networks where proximity to production facilities enables viable logistics.
Active dry maintains the broadest geographic reach. Instant formats are climbing the fastest in industrial bakery adoption.
Application:
Functional environment—leavening chemistry, fermentation kinetics, or nutritional bioavailability—dictates strain selection and processing specifications.
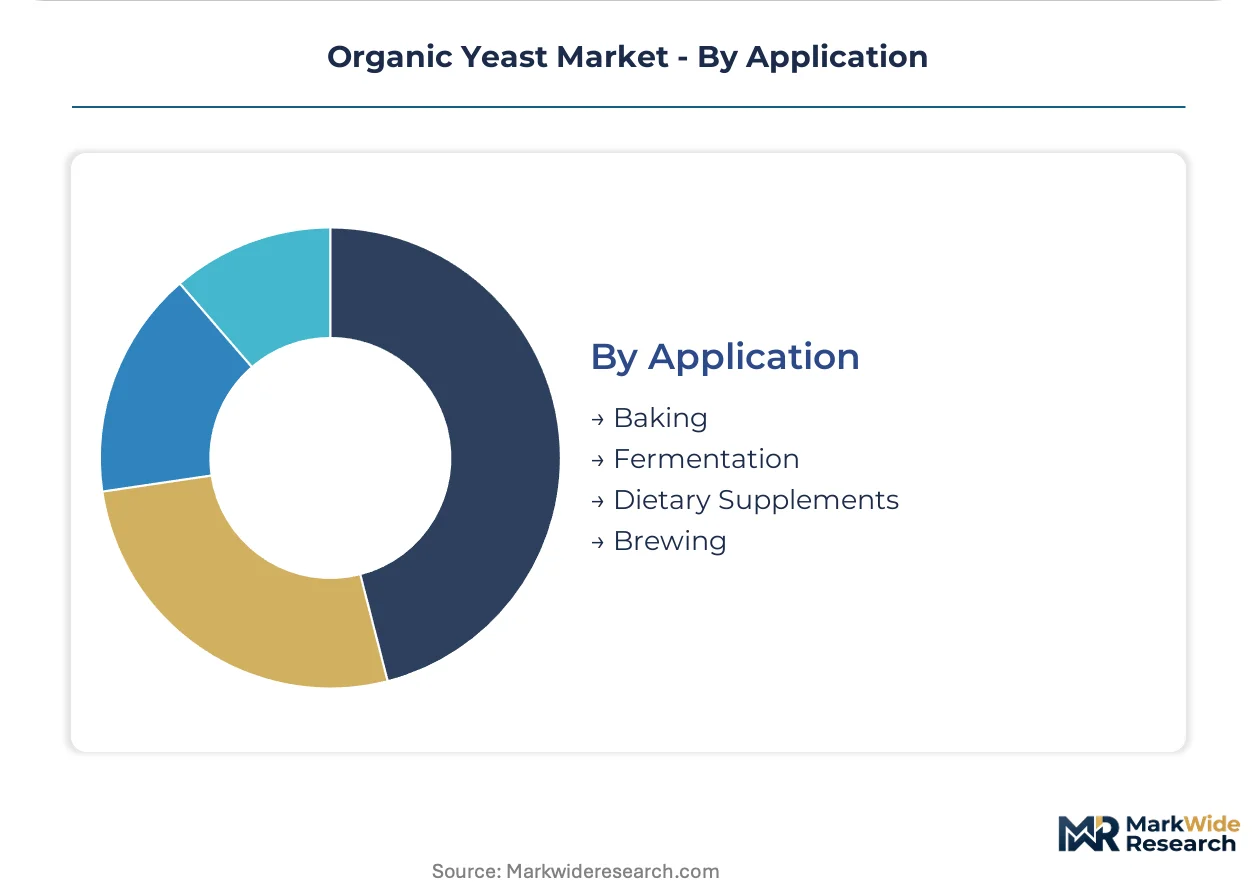
- Baking:Leavening applications in bread and pastry production represent the dominant volume use case, with EU Green Deal pesticide reduction targets tightening organic substrate availability for certified production.
- Fermentation:Beverage and food fermentation processes require strain tolerance to organic-compliant stress conditions, with USDA organic and EU Regulation 2018/848 prohibiting GM optimization that conventional producers exploit.
- Dietary Supplements:B-complex fortification and protein supplementation applications in vegan nutrition products, with FDA oversight applying to label claims in the United States.
- Brewing:Malt fermentation for beer production, where organic certification premiums face pressure from conventional malt input costs in competitive craft beer markets.
Baking anchors installed capacity. Dietary supplements are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic yeast trade flows reveal a structural deficit in North American and Asian markets against concentrated European export capacity, with substrate certification bottlenecks determining which origins can access premium-priced bakery and nutraceutical contracts.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia drive organic baker's yeast procurement at scale, with the EU Green Deal's Farm to Fork pesticide reduction targets tightening beet molasses availability. The Federal Office for Agriculture and Food enforces organic substrate traceability under EU Regulation 2018/848. Hamburg hosts bioreactor clusters where producers are securing captive organic molasses supply through backward integration into sugar beet cooperatives.
France
Parisian industrial bread manufacturers and artisan cooperatives in Provence-Alpes-Côte d'Azur specify organic yeast with regenerative agriculture credentials attached. ANSM and DGCCRF oversee nutritional label claims for yeast-derived supplements entering the French market. The Île-de-France fermentation corridor concentrates toll manufacturing capacity serving pan-European bakery chains reformulating for clean-label compliance.
United States
Plant-based supplement formulators in California and New York Metro accelerate demand for organic-certified nutritional yeast as vegan dietary fortification expands. USDA organic certification and FDA oversight govern substrate sourcing and B-complex label claims respectively. Pacific Northwest craft breweries in Oregon and Washington procure organic brewer's yeast despite certification premiums compressing margins versus conventional malt inputs.
China
Angel Yeast anchors volume production in Hubei province through state-controlled organic feedstock quotas and captive molasses supply chains. The National Health Commission and SAMR regulate yeast-derived nutritional products under food safety and labeling frameworks. Yangtze River Delta bakeries in Shanghai and Jiangsu province are absorbing rising organic yeast volumes as clean-label bakery demand penetrates urban retail channels.
India
Maharashtra and Karnataka food manufacturers are piloting organic yeast incorporation into processed baked goods for export to EU markets requiring certification compliance. FSSAI organic standards and DGFT export protocols create dual regulatory navigation for producers. Mumbai-Pune industrial corridors host emerging contract fermentation capacity targeting mid-tier bakery brands seeking asset-light organic certification access.
Organic Yeast Market Competitive Environment
On the supply side, the industry is consolidating around integrated substrate controllers and fragmenting among toll-manufacturing specialists, with three strategic archetypes defining competitive position: captive molasses owners, strain-bank licensors, and asset-light contract fermenters. Dominant competitive moves include backward integration into organic beet supply and patent-protected viability preservation technologies for active dry formats.
Within the integrated substrate tier, Lesaffre and Angel Yeast exemplify divergent geographic anchoring strategies, with the former leveraging European distribution density and the latter exploiting Asian feedstock cost structures. Lallemand occupies a specialist position defined by R&D intensity and intellectual property holdings in shelf-life extension. These three entities represent the primary competitive poles around which mid-tier toll manufacturers and regional specialists orbit.
| Leading Market Players |
|---|
| Lesaffre |
| Lallemand |
| Angel Yeast |
| Biospringer |
| Ohly |
| Leiber GmbH |
| Koninklijke DSM |
| Biorigin |
| Red Star Yeast Company |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in certified organic bioreactor networks across Germany and France is tightening supplier pricing power while compressing margin flexibility for non-integrated toll manufacturers competing on spot substrate purchases.
Pricing Analysis
Industrial bakery buyers anchor contract pricing structures across the organic yeast market. Three-tier pricing stratifies across EU organic-certified premium strains, standard organic baker's grades, and economy-tier conventional alternatives. Price differentiation rests on substrate traceability depth and active dry viability preservation technology. Cost compression in mid-tier organic segments is intensifying because beet molasses supply constraints elevate input costs for non-captive producers. Artisan cooperatives in Italy and Provence show highest price sensitivity, while pan-European industrial bread manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
EU Regulation 2018/848 substrate traceability mandates function as de facto export controls limiting organic yeast flows to uncertified destinations. Geographic supply concentrates in Germany, France, and China, with Hubei province bioreactor clusters drawing from state-controlled organic feedstock quotas. Raw material dependencies center on certified beet molasses, organic grain-derived substrates, and proprietary Saccharomyces cerevisiae strain banks. Single-source vulnerability runs through concentrated EU organic molasses processing. Distribution runs through long-term offtake contracts with industrial bakeries and toll-manufacturing arrangements for mid-tier nutraceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic yeast procurement is becoming a service-attach opportunity as substrate traceability documentation and carbon intensity auditing expand faster than commodity yeast volumes.
For Market Incumbents: Insulate margin pools through backward integration into organic beet cooperatives in Germany and France, securing captive molasses supply against Farm to Fork tightening. Deepen strain bank IP holdings targeting organic stress tolerance to block licensing revenue leakage to toll competitors. Prioritize digital traceability infrastructure investments ahead of EU electronic database mandates. For New Entrants and Emerging Players: US plant-based supplement formulators seeking organic-certified nutritional yeast represent the most penetrable entry point, with California and New York Metro buyers underserved on regenerative agriculture credentialing. Contract fermentation toll models bypass bioreactor capital requirements while accessing certified capacity. Lead with carbon intensity disclosure services bundled with organic certification to differentiate from commodity suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across organic substrate backward integration projects as EU pesticide reduction targets tighten feedstock availability. Five-to-ten year viability favors vertically integrated producers controlling molasses supply chains over asset-light toll manufacturers exposed to spot substrate volatility. Watch Farm to Fork implementation timelines as inflection signal for supply-constraint severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Beet Supply | Captive molasses sourcing under EU Regulation 2018/848 secures substrate continuity against Farm to Fork constraints. |
| Digital Traceability Platform Deployment | Blockchain-enabled substrate documentation compresses compliance labor for EU organic certification audits. |
| Active Dry Viability Patent Investment | Shelf-life extension technologies open export logistics chains to distant nutraceutical markets. |
| Contract Fermentation Capacity Expansion | Toll manufacturing models allow mid-tier entrants to access certified organic bioreactor networks without capital deployment. |
| Regenerative Agriculture Credentialing | Carbon intensity disclosures attached to organic yeast concentrates contract volumes with sustainability-scorecard buyers. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with fermentation facility managers, organic certification auditors, bakery procurement directors, and nutraceutical formulators; and secondary validation against EU organic certification databases, USDA National Organic Program filings, customs trade records, and SEC disclosures from publicly traded yeast producers. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, physical form, and application segments.
Forecast inputs span substrate availability projections under EU Green Deal implementation, organic acreage expansion trajectories, and clean-label bakery reformulation adoption curves across the analysis window. Segmentation dimensions modeled include product chemistry tier, customer procurement scale, physical format logistics constraints, and application environment specifications. CAGRs were derived from regression analysis of historical organic certification growth rates applied to substrate-constrained supply scenarios.
Practitioners should monitor EU Farm to Fork pesticide reduction timelines and organic beet harvest volatility for early signals of supply-constraint severity. Forecasts reflect assumptions on certification approval cycle durations and substrate substitution research progress. Material shifts in EU organic substrate traceability enforcement or breakthrough non-molasses feedstock commercialization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Non-GMO Food Market
Organic Food and Beverages
Organic Honey Market
Organic Food and Beverages
Organic Coconut Syrup Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Global Natural and Organic Food Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
Australia Organic Beverages Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
South Africa Organic Food Market