
 Scandinavia Organic Packaged Food and Beverages Market | 2026-2036
Scandinavia Organic Packaged Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Scandinavia Organic Packaged Food and Beverages Market Intelligence
Urban millennial households is unwinding traditional family-centric purchasing patterns across Scandinavian retail channels. Arla Foods leverages its cooperative dairy infrastructure to secure organic milk volumes across Denmark and Sweden. ICA anchors shelf-space negotiations in Swedish supermarkets through private-label organic expansion. Coop differentiates via KRAV-certified store-brand lines that command premium positioning in Norwegian and Danish outlets.
Scandinavia Organic Packaged Food and Beverages encompasses shelf-stable and chilled products manufactured without synthetic pesticides, genetically modified organisms, or artificial additives, with KRAV or EU Organic leaf certification mandatory for label claims. The category serves retail consumers, food service operators, and institutional buyers requiring verified supply chain documentation for procurement compliance. Beverages and dairy segments lead current revenue contribution due to high per-capita consumption of organic milk, plant-based drinks, and juices across Sweden, Denmark, and Norway. Flexible packaging and Tetra Packs are gaining fastest within the packaging dimension as brands navigate carbon footprint reduction targets and extended shelf-life requirements for export-bound production.
KRAV, the EU Organic Regulation, and national food safety agencies across Denmark, Sweden, and Norway enforce strict labeling, inspection, and import documentation standards that determine market access for non-Scandinavian suppliers. These frameworks elevate compliance costs for smaller importers while insulating domestic producers with established certification infrastructure. Stakeholders must monitor evolving EU Green Deal implementation timelines and potential harmonization gaps between national organic standards to anticipate sourcing and pricing adjustments.
Market Dynamics
EU Green Deal implementation timelines are compressing certification cycles across Scandinavian organic supply chains, forcing producers to accelerate traceability investments ahead of 2030 climate neutrality targets.
Growth Catalysts
- EU Green Deal carbon accounting mandates:Retailers in Denmark and Sweden now require Scope 3 emissions documentation from organic suppliers, creating procurement advantages for certified domestic producers.
- Plant-based beverage formulation advances:Oat and pea protein extraction technologies have improved mouthfeel parity with conventional dairy, expanding addressable markets among flexitarian households in Stockholm and Copenhagen.
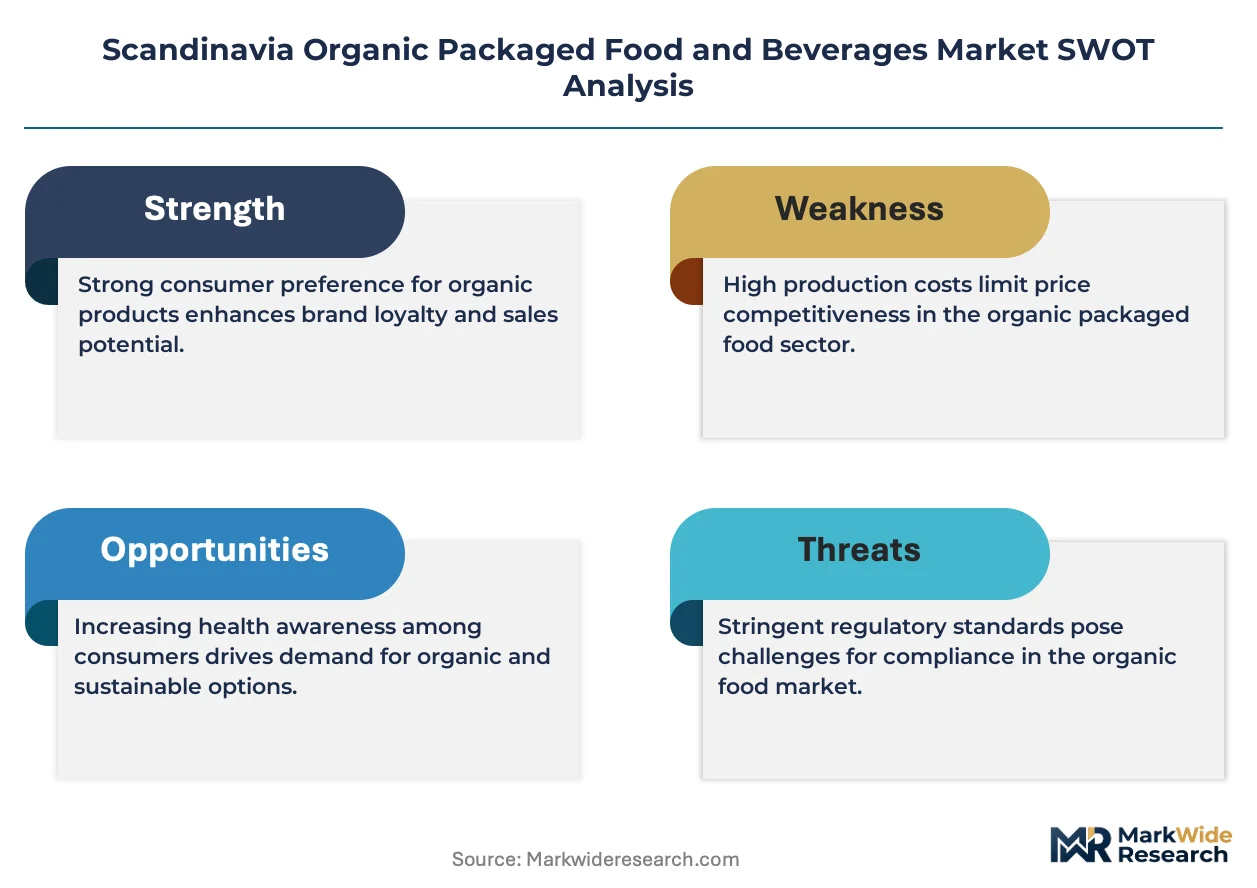
- KRAV certification infrastructure density:Norway's inspection body accreditation network reduces compliance friction for small-scale organic entrants compared to importers facing EU Organic equivalence negotiations.
Market Restraints
- Organic feed grain cost volatility:Swedish dairy cooperatives face margin pressure from Ukrainian sunflower and soybean supply disruptions affecting KRAV-compliant livestock nutrition.
- Domestic processing concentration:Denmark retains only three Tetra Pak-compatible aseptic filling facilities capable of organic juice export volumes, creating single-point bottlenecks.
- EU Organic-KRAV label divergence:Norwegian retailers must maintain dual inventory streams for products lacking harmonized certification, elevating working capital requirements.
Strategic Opportunities
- Finnish border retail corridors:Underdeveloped organic packaged food penetration in Tampere and Turku metropolitan zones offers first-mover positioning for Swedish private-label suppliers.
- Food service direct sourcing platforms:Copenhagen's restaurant cluster increasingly bypasses wholesale distributors for KRAV-certified ingredient contracts, enabling producer margin capture.
- Digital product passport integration:Blockchain-enabled batch tracking aligns with EU Green Deal circular economy requirements while supporting premium positioning in Norwegian supermarkets.
Industry Challenges
- KRAV inspector capacity constraints:Certification backlog periods now extend to fourteen weeks in rural Swedish production zones, delaying seasonal product launches.
- Legacy ERP traceability gaps:Mid-sized Danish organic processors struggle to retrofit batch-recall systems for EU Organic Regulation documentation requirements without full platform replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scandinavia Organic Packaged Food and Beverages Market |
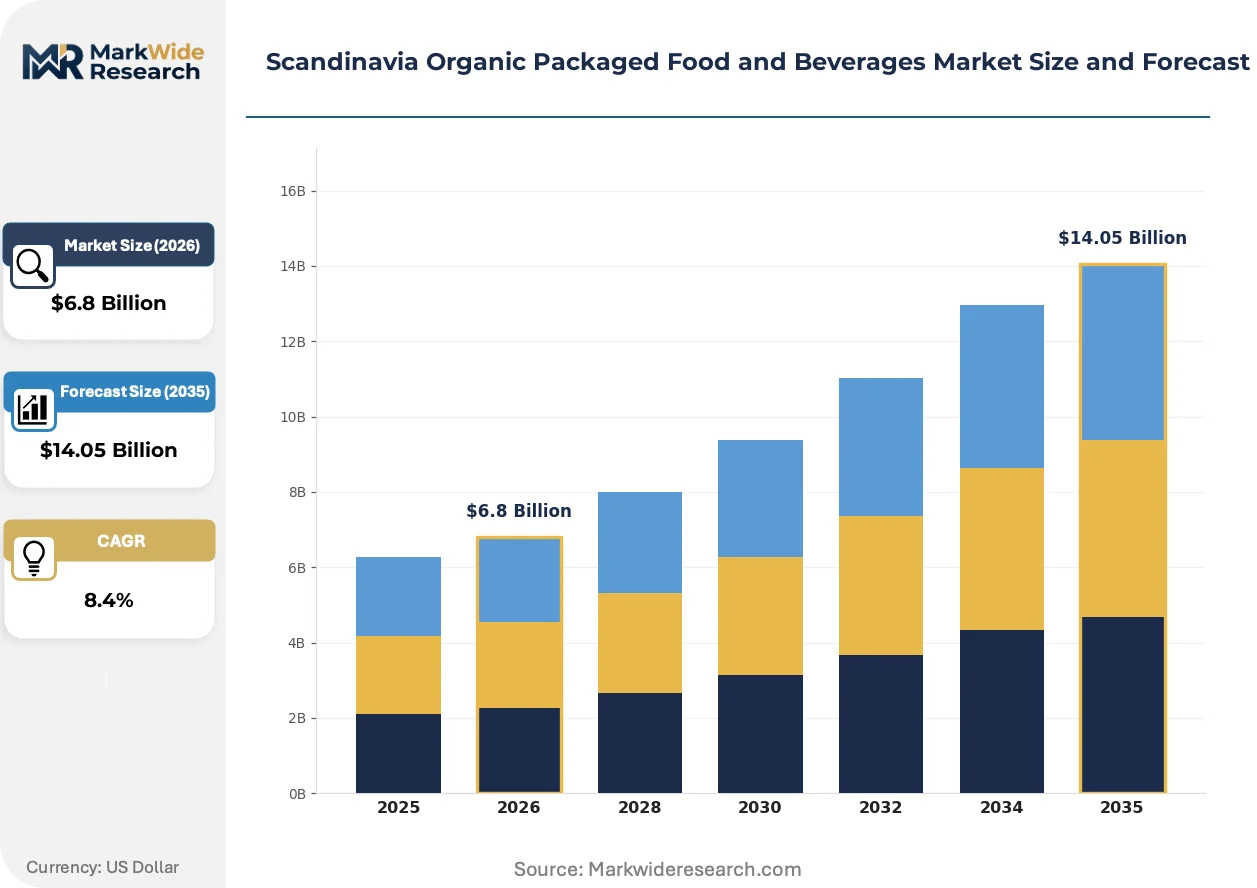
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snack Bars, Beverages, Sauces, Dairy End User: Retail Consumers, Food Service, B2B, Educational Institutions Packaging Type: Cartons, Glass, Flexible Packaging, Tetra Packs Ingredient Source: Local Farms, Organic Suppliers, Fair Trade, Imports |
| Companies Covered | Arla Foods, ICA, Coop, Axfood, Lantmännen, Nordquist & Söner, Änglamark, Systembolaget, Alko, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scandinavia Organic Packaged Food and Beverages Market Strategic Shifts & Innovations
Flexible packaging material substitution is accelerating across Scandinavian organic beverage lines as brands confront extended producer responsibility fees and export shelf-life demands.
Mono-material polyethylene films are fragmenting multilayer laminate dominance in organic juice and plant-based milk cartons. Swedish retailers including ICA are piloting these structures for private-label lines. The shift is fragmenting incumbent converter relationships as brands seek film suppliers with blow-molding and thermoforming capabilities beyond traditional liquid packaging board partnerships.
EU Green Deal Farm to Fork Strategy pesticide reduction targets are tightening residue testing protocols for imported organic ingredients. Danish border control laboratories have expanded chromatography capacity for third-country verification. The policy most affects berry and grain suppliers to Norwegian breakfast cereal producers, who are diversifying sourcing toward Baltic states with shorter documentation chains.
Subscription-based organic meal kit procurement is displacing conventional supermarket stocking patterns among urban millennial households in Oslo and Gothenburg. These platforms consolidate weekly purchasing into curated KRAV-certified bundles, reducing brand-switching frequency. The behavior is most visible in Stockholm's inner suburbs, where delivery density supports refrigerated last-mile economics that supermarket click-and-collect struggles to match.
Scandinavia Organic Packaged Food and Beverages Market Segmentation
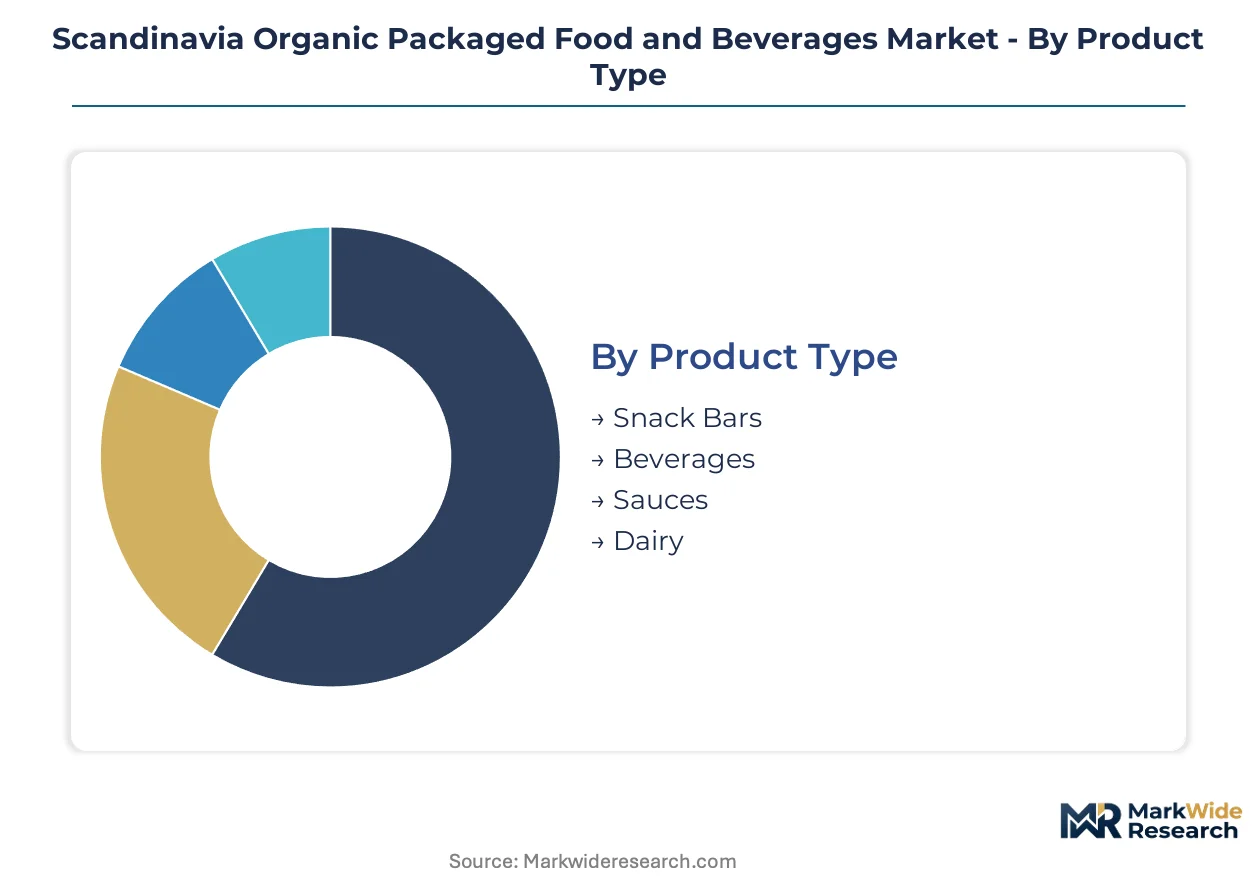
KRAV certification requirements and retail channel consolidation across Denmark, Sweden, and Norway create distinct segment performance profiles. Channel access determines which product configurations achieve scale versus which remain niche.
Product Type:
Retail channel mix varies sharply by product format, with chilled dairy dominating supermarket shelf negotiations while beverages secure broader distribution through convenience and food service.
- Dairy:Organic milk, yogurt, and cheese formulations account for the largest revenue concentration within Scandinavian retail. Swedish cooperatives anchor supply contracts with ICA and Coop through KRAV-certified cold chain infrastructure. Margin pressure from organic feed costs is compressing producer returns in Jutland and Skåne dairy belts.
- Beverages:Plant-based oat drinks and organic juices command premium positioning in Copenhagen and Stockholm metropolitan corridors. Oatly and smaller Nordic challengers leverage Tetra Pak aseptic filling for extended shelf-life exports to German and British markets.
- Snack Bars:Protein-enriched and raw fruit formulations target urban commuter channels in Oslo and Gothenburg. Limited cold chain requirements enable direct-to-consumer subscription penetration.
- Sauces:Condiments and cooking bases maintain steady institutional procurement from Danish food service distributors. Lower per-unit value constrains organic certification investment relative to dairy and beverages.
Dairy dominates installed base. Beverages is where expansion concentrates.
End User:
Customer type segmentation reveals divergent margin structures, with food service direct sourcing capturing value that retail intermediaries otherwise extract.
- Retail Consumers:Supermarket and hypermarket channels in Stockholm, Copenhagen, and Oslo metropolitan zones absorb the majority of organic packaged food volume. KRAV-certified private-label expansion by ICA and Coop is displacing branded shelf space in Swedish and Norwegian outlets.
- Food Service:Copenhagen's restaurant cluster and Oslo's hotel sector increasingly bypass wholesale distributors for direct KRAV-certified producer contracts. This channel offers the steepest expansion trajectory as procurement platforms consolidate ingredient sourcing.
- B2B:Corporate catering and workplace canteen procurement in Denmark and Sweden mandates organic certification for sustainability reporting compliance. Volume concentration with large facility management providers reduces supplier negotiation leverage.
- Educational Institutions:Municipal school procurement across Norway and Sweden follows national organic food percentage targets. KRAV compliance is mandatory for contract eligibility, creating insulated demand for certified domestic producers.
Retail Consumers anchor volume throughput. Food Service is where margin capture concentrates.
Packaging Type:
Material selection tracks carbon accounting mandates and export shelf-life requirements, with flexible formats gaining share against traditional liquid packaging board.
- Tetra Packs:Aseptic carton systems remain dominant for organic milk and plant-based beverages requiring ambient distribution. Denmark retains only three export-capable filling facilities, creating supply bottlenecks for juice volume expansion.
- Flexible Packaging:Mono-material polyethylene films are fragmenting multilayer laminate dominance in organic juice lines. Swedish retailers pilot these structures for private-label SKUs to meet extended producer responsibility fee reductions.
- Glass:Premium sauces and specialty beverages maintain glass bottle positioning for shelf differentiation in Norwegian and Danish gourmet retail. Weight and fragility constrain e-commerce penetration.
- Cartons:Chilled dairy and fresh juice applications use gable-top cartons with shorter shelf-life profiles. Regional distribution radius limits align with local farm sourcing strategies in southern Sweden.
Tetra Packs dominate installed filling infrastructure. Flexible Packaging is where material substitution concentrates.
Ingredient Source:
Provenance claims command price premiums in Scandinavian retail, with KRAV-certified domestic sourcing insulated from import documentation friction.
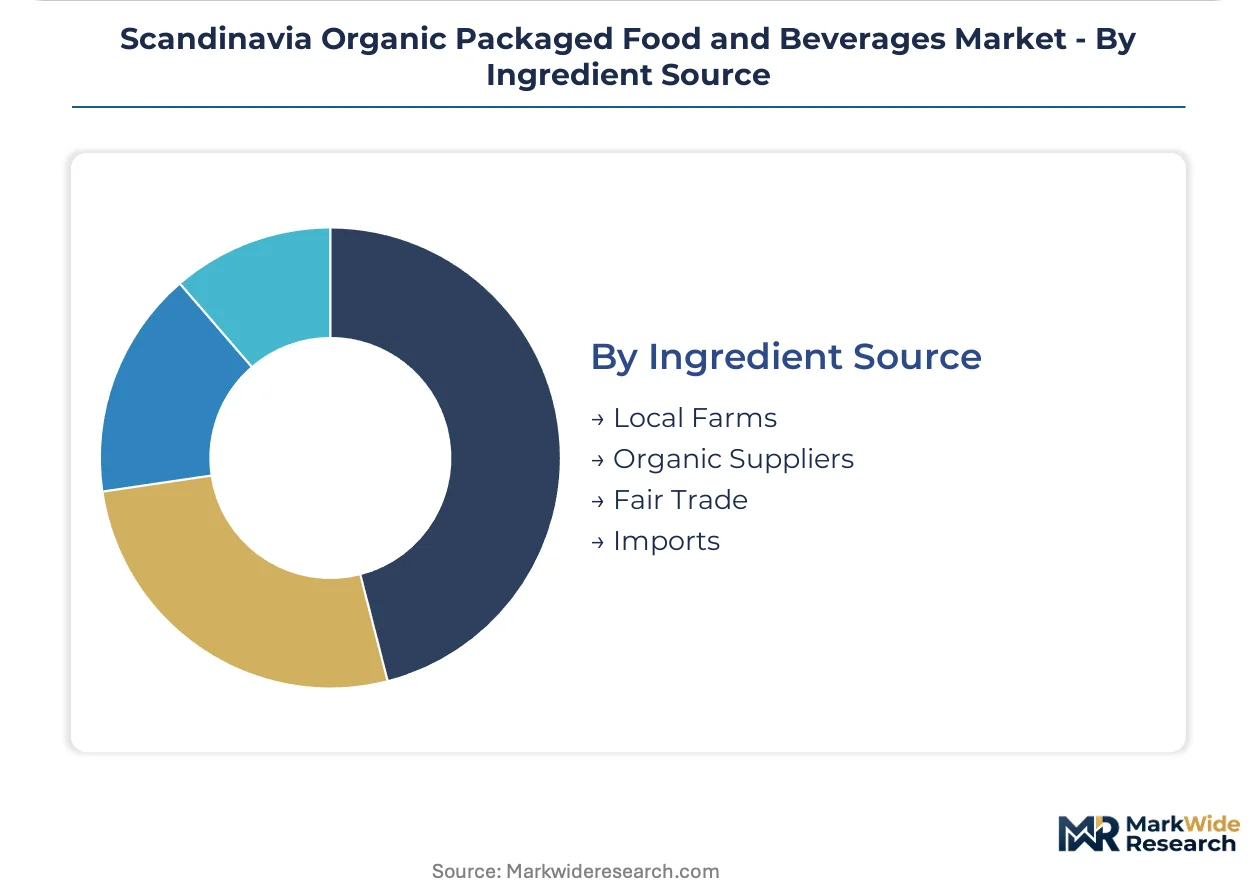
- Local Farms:KRAV-certified Swedish and Danish dairy cooperatives leverage cooperative infrastructure for traceable milk collection. Arla Foods anchors this segment through farmer-owned supply networks across Jutland and Skåne.
- Organic Suppliers:Baltic and Polish grain and berry suppliers serve Norwegian breakfast cereal and snack bar producers with shorter documentation chains than distant third-country alternatives.
- Fair Trade:Coffee, cocoa, and tropical fruit ingredients carry dual certification for ethical positioning in premium Swedish retail. Limited volume share constrains segment-wide margin contribution.
- Imports:Ukrainian sunflower and soybean organic feed inputs face supply disruption volatility affecting Swedish livestock producer costs. Danish border laboratories have expanded residue testing capacity for third-country verification.
Local Farms dominate certified volume base. Organic Suppliers is where sourcing diversification concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Øresund Bridge and tunnel system anchors Denmark's organic food distribution, connecting Copenhagen's processing cluster to Swedish retail corridors and enabling chilled cross-border logistics that underpin the region's integrated supply chain.
Denmark
Copenhagen's food cluster drives KRAV-certified dairy and beverage innovation, with Arla Foods leveraging cooperative infrastructure across Jutland. The Danish Veterinary and Food Administration enforces strict organic labeling compliance. Aarhus and Odense processing zones concentrate Tetra Pak-compatible filling capacity for export-bound organic juice volumes.
Sweden
Stockholm's metropolitan retail corridor absorbs the highest per-capita organic packaged food consumption in the region. The Swedish Food Agency administers KRAV certification alongside EU Organic standards. ICA and Coop anchor shelf-space negotiations through private-label expansion in Skåne and Västra Götaland dairy belts.
Norway
Oslo's urban millennial households accelerate plant-based beverage adoption through subscription platforms. The Norwegian Food Safety Authority maintains KRAV inspector accreditation networks that reduce compliance friction for domestic entrants. Bergen and Stavanger food service clusters increasingly bypass wholesale distributors for direct organic producer contracts.
Finland
Helsinki's underdeveloped organic penetration relative to Nordic peers creates expansion corridors for Swedish private-label suppliers. The Finnish Food Authority implements EU Organic Regulation with national adaptation for border retail zones. Tampere and Turku metropolitan areas show rising KRAV-certified product availability through cross-border sourcing from Stockholm.
Scandinavia Organic Packaged Food and Beverages Market Key Industry Players
Concentration sits with cooperative dairy structures and retail-owned private labels that control shelf access and certification infrastructure across Scandinavian markets. The vendor base fragments between large-scale processors with Tetra Pak filling capacity and specialized organic entrants lacking export-scale logistics. Two strategic archetypes dominate: farmer-owned cooperatives leveraging traceable supply networks, and retailer-controlled brands capturing margin through KRAV-certified store lines. Competitive moves center on backward integration into organic feed sourcing and strategic partnerships with last-mile delivery platforms serving urban subscription households.
Within the cooperative archetype, Arla Foods exemplifies farmer-owned scale advantages through its Jutland and Skåne milk collection networks. Among retail-controlled private labels, ICA and Coop occupy positions that leverage KRAV certification density to displace branded shelf space in Swedish and Norwegian outlets. These three entities anchor the competitive structure by controlling access points that determine which organic configurations achieve retail scale versus niche positioning.
| Leading Market Players |
|---|
| Arla Foods |
| ICA |
| Coop |
| Axfood |
| Lantmännen |
| Nordquist & Söner |
| Änglamark |
| Systembolaget |
| Alko |
| Others |
Cost & Logistics Intelligence
Tetra Pak-compatible aseptic filling capacity in Denmark anchors scale economies that compress per-unit costs for organic juice exporters while simultaneously elevating price floors for domestic entrants lacking equivalent throughput. This concentration of export-grade processing infrastructure across Jutland and Skåne dairy belts shapes procurement power dynamics between farmer-owned cooperatives and retail buyers.
Pricing Analysis
Volume-discount tiering structures separate KRAV-certified premium SKUs from EU Organic standard lines and conventional economy alternatives in Swedish and Norwegian retail. Price differentiation rests on certification grade and cold chain infrastructure investment, with Stockholm metropolitan buyers showing lowest sensitivity due to subscription platform consolidation. Cost compression in plant-based beverage tiers is intensifying because oat protein extraction technology licensing fees are spreading across multiple Nordic challengers.
Supply Chain Analysis
Inventory lead times for organic feed grains now stretch unpredictably as Ukrainian sunflower and soybean supply disruptions ripple through Swedish livestock producer networks. Geographic supply concentration centers on Denmark, Sweden, and Norway for dairy processing, with Baltic states and Poland feeding Norwegian cereal ingredient demand. Raw material dependencies include KRAV-certified organic grain, aseptic packaging film, and plant-based protein isolates. Single-source vulnerability sits with Denmark's three Tetra Pak filling facilities. Distribution runs through ICA and Coop controlled retail channels with direct food service bypass emerging in Copenhagen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of KRAV inspector capacity across rural Swedish production zones constrains seasonal product velocity, creating a bottleneck that rewards producers with established certification infrastructure and pre-qualified supply networks.
For Market Incumbents: Fortify backward integration into organic feed sourcing to offset Ukrainian grain supply volatility threatening Jutland dairy margins. Expand Tetra Pak filling partnerships in Aarhus and Odense to preempt export capacity bottlenecks. Channel control through ICA and Coop private-label negotiations remains the priority defensive lever against Oatly and emerging Nordic challengers. For New Entrants and Emerging Players: Food service direct sourcing platforms in Copenhagen and Oslo represent the most penetrable white-space where wholesale distributor bypass is accelerating. Finnish border retail corridors around Tampere and Turku offer geographic expansion with lower shelf-space competition than Stockholm saturation. A go-to-market angle anchored on blockchain-enabled batch tracking aligns with EU Green Deal circular economy requirements while supporting premium positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized organic entrants with captive KRAV certification infrastructure over undifferentiated commodity processors. Long-term viability across the projection horizon hinges on traceability technology integration and cold chain asset ownership. Acquisition target archetypes include mid-sized Danish processors with retrofit-ready ERP systems and established inspector relationships. The signal to watch is KRAV-EU Organic harmonization timeline acceleration affecting dual-inventory working capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feed | Captive supply of KRAV-certified grain insulates Swedish cooperatives from Ukrainian import volatility. |
| Blockchain Product Passport Deployment | Digital batch tracking satisfies EU Green Deal circular economy mandates for Norwegian retail compliance. |
| Flexible Packaging Material Transition | Mono-material polyethylene pilot programs with ICA reduce extended producer responsibility fee exposure. |
| Food Service Direct Sourcing Platform | Copenhagen restaurant cluster bypass of wholesale distributors enables producer margin capture. |
| Finnish Border Retail Expansion | Tampere and Turku metropolitan penetration offers first-mover positioning for Swedish private-label suppliers. |
Research Approach
A standing panel of KRAV certification officers, ICA and Coop category buyers, Arla Foods supply chain directors, and Danish Veterinary and Food Administration inspectors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against EU Organic Regulation implementation documents, Swedish Food Agency enforcement records, Norwegian Food Safety Authority accreditation databases, and customs trade data for organic grain imports. Bottom-up volume modeling and top-down value triangulation anchored segment-level outputs.
Consistency checks validated projections against external benchmarks including retail audit data from Nielsen and Circana, Tetra Pak filling capacity disclosures, and organic acreage statistics from national agricultural agencies. The analytical framework modeled product type, end user channel, packaging format, and ingredient provenance dimensions across the analysis window. CAGRs were derived from segment growth rate reconciliation with macroeconomic consumption elasticity assumptions, incorporating organic feed cost indices and certification backlog duration as industry-specific forecast inputs.
Underlying assumptions cover KRAV-EU Organic regulatory stability, continued Ukrainian grain supply disruption, and inspector capacity expansion timelines, with deviation risk concentrated in harmonization policy shifts and climate-induced organic crop yield variability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Organic Drinks Market
Organic Food and Beverages
Organic Coconut Syrup Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Canada Organic Food Market
Organic Food and Beverages
Australia Organic Food Market