
 Organic Pasta Market | 2026-2036
Organic Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Pasta Market Intelligence
Italian artisanal producers' capacity expansion is decoupling from traditional durum wheat sourcing, creating new opportunities for alternative grain suppliers. Large-scale manufacturers like Barilla Group leverage extensive distribution networks to maintain market share in conventional channels. Ebro Foods S.A. specializes in integrating diverse grain types into its product lines, from brown rice to quinoa. Smaller players such as Rummo S.p.A. compete on production methods and regional authenticity.
Organic pasta refers to pasta products manufactured from cereals, legumes, or other starches grown under certified organic farming protocols. These protocols prohibit the use of synthetic pesticides, herbicides, and fertilizers, ensuring ingredient purity from farm to finished good. While whole wheat remains a dominant ingredient source, pastas made from chickpea and quinoa are experiencing significant interest. Sales through online retailers and specialty health food stores are expanding more rapidly than traditional supermarket channels.
Market access and product labeling are governed by stringent certification standards, including the USDA National Organic Program in the United States and Regulation (EU) 2018/848 in Europe. These frameworks define the entire production chain, from soil management to processing. National regulations, such as Italy's historic pasta purity laws, further influence ingredient specifications. Producers must now balance the appeal of traditional recipes with consumer demand for novel, non-traditional grain sources.
Market Dynamics
The fundamental market dynamic is the conflict between historic pasta purity laws, particularly in Italy, and rising consumer demand for novel, non-traditional organic grain sources like chickpea and quinoa, forcing a re-evaluation of ingredient standards.
Growth Catalysts
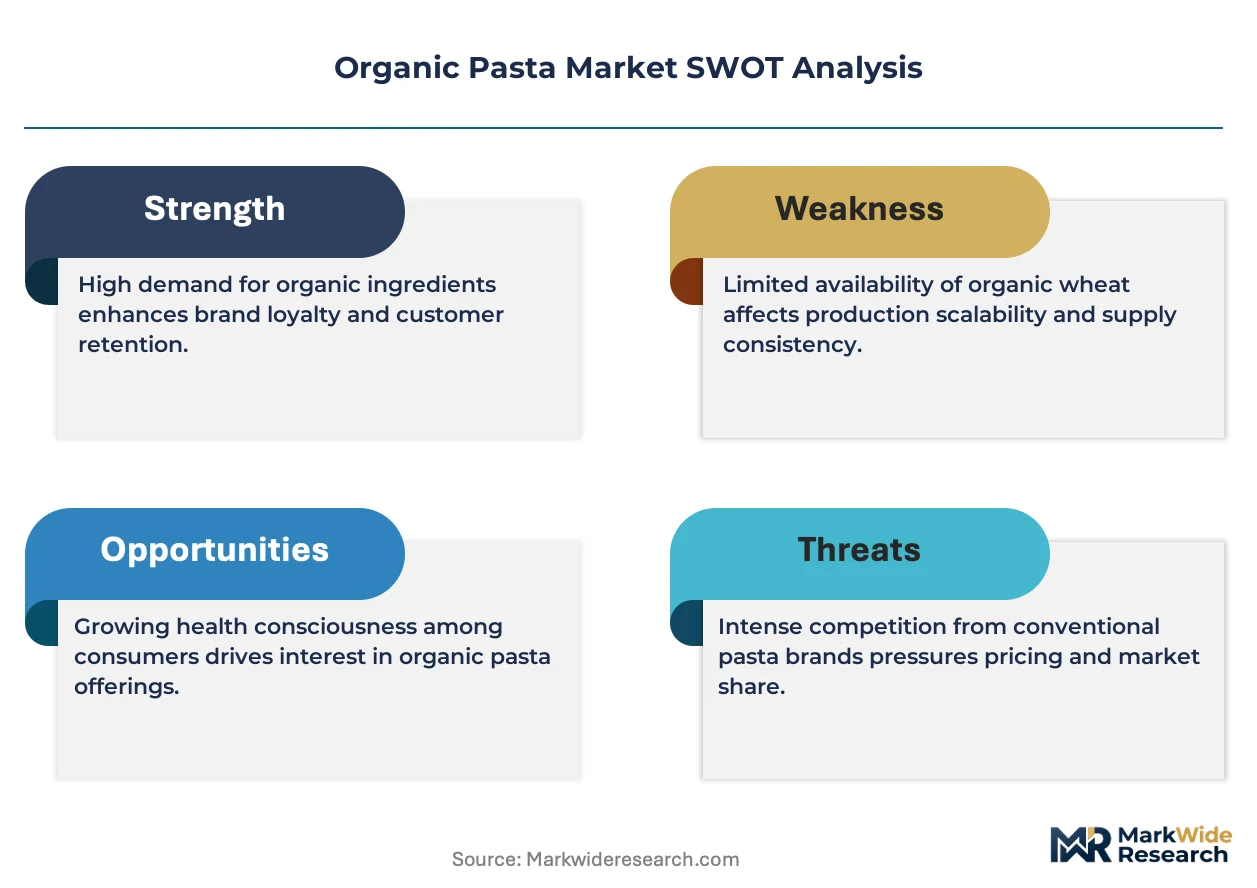
- Consumer Wellness Orientation:Heightened consumer focus on personal health and diet drives purchasing decisions toward foods with certified organic and clean-label attributes, directly benefiting the organic pasta category.
- EU Agricultural Policy:The European Union's Farm to Fork strategy provides direct support and incentives for farmers to convert to organic agriculture, expanding the reliable supply of certified raw materials for pasta manufacturing.
- Evolving Retail Channels:The rapid expansion of e-commerce platforms and specialized health food stores creates dedicated channels for organic products, improving access for consumers and visibility for niche brands.
Market Restraints
- Organic Grain Price Volatility:Prices for organic durum wheat and alternative grains exhibit significant volatility due to climate-dependent harvest yields and a smaller supply base compared to conventionally grown crops.
- Certification Barriers:The financial cost and administrative complexity of achieving and maintaining organic certification under frameworks like the USDA National Organic Program can be prohibitive for small-scale farmers and producers.
- Yield Discrepancies:Organic farming protocols, which prohibit synthetic fertilizers, often lead to lower crop yields per hectare, which inherently limits the total volume of available raw ingredients and puts upward pressure on costs.
Strategic Opportunities
- Functional Ingredient Integration:There is a significant opportunity to develop pasta products fortified with functional ingredients or based on high-protein legumes like lentils and fava beans, targeting health-conscious and athletic consumer demographics.
- Geographic Expansion in Asia-Pacific:Markets such as South Korea and Australia present untapped potential, where rising disposable incomes and a growing awareness of organic benefits are creating new demand for premium food products.
- Supply Chain Traceability:Implementing blockchain or similar digital ledger technologies offers a method to provide consumers with verifiable proof of origin and organic integrity, strengthening brand trust and justifying premium price points.
Industry Challenges
- Maintaining Authenticity at Scale:Artisanal and regional producers face significant operational challenges in scaling up production to meet demand from major retailers without compromising traditional methods or product quality.
- Cross-Contamination Risk Management:Processors must invest in separate storage, milling, and production lines to prevent cross-contamination from conventional grains, adding significant cost and logistical complexity to their operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Pasta Market |
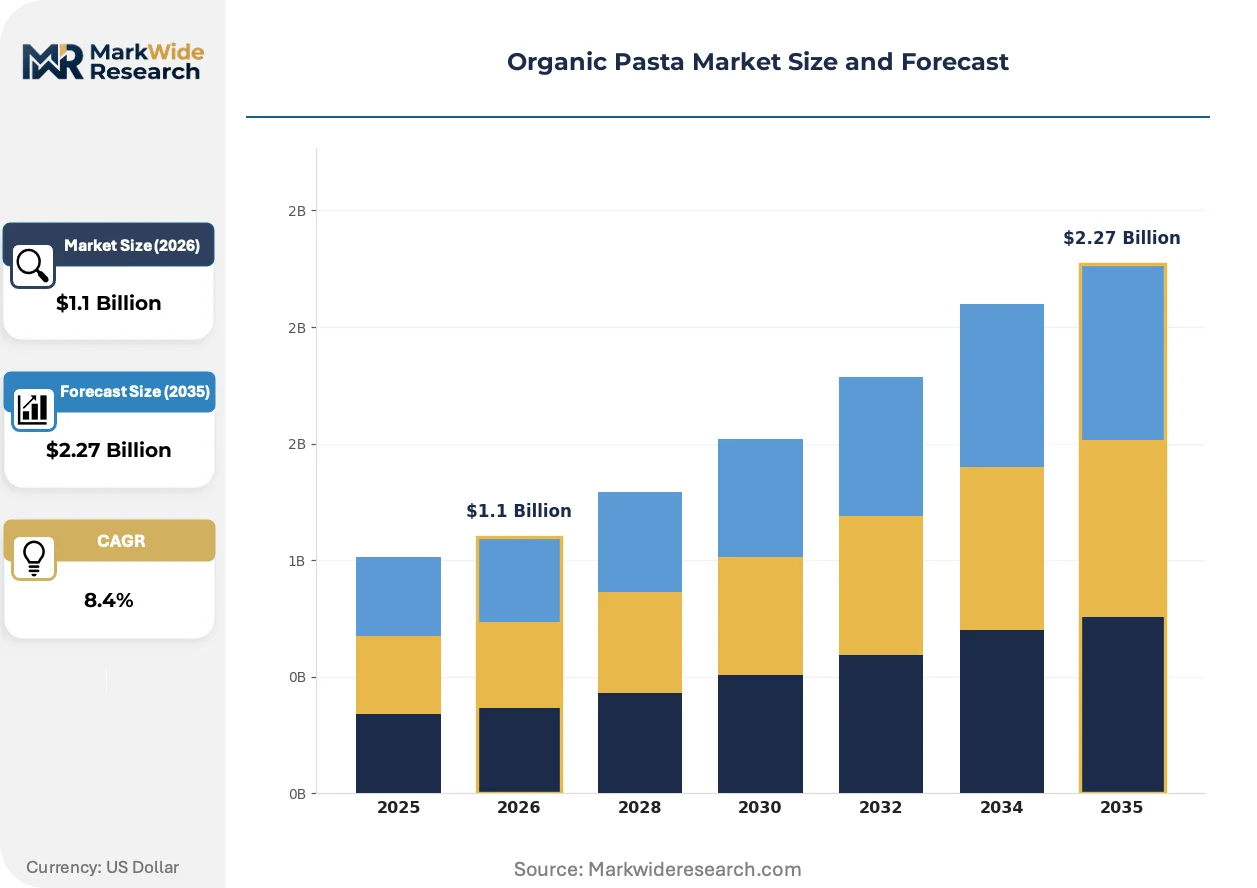
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $2.27 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spaghetti, Penne, Fusilli, Macaroni, Lasagna, Fettuccine Ingredient Source: Whole Wheat, Brown Rice, Quinoa, Chickpea, Buckwheat, Amaranth Packaging Type: Box, Pouch, Vacuum Pack, Bulk Bag, Plastic Wrap, Paper Bag Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Stores, Direct Sales |
| Companies Covered | Barilla Group, Nestlé S.A., Ebro Foods S.A., F.lli De Cecco di Filippo S.p.A., Conagra Brands, Inc., TreeHouse Foods, Inc., General Mills Inc., Danone SA, Rummo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Pasta Market Strategic Shifts & Innovations
Product formulation is rapidly diversifying beyond wheat to include a wide array of legumes and ancient grains. This ingredient diversification is occurring alongside technological advancements in processing and supply chain verification that reinforce the integrity of organic claims.
Advanced extrusion and milling technologies are being developed specifically for alternative flours like chickpea, lentil, and quinoa. Specialized food manufacturers and innovative brands are rapidly adopting these methods to create products with improved texture and cooking performance. This technological adoption is decentralizing the market's historic reliance on durum wheat, enabling product innovation from a much broader and more geographically varied agricultural base.
Regulation (EU) 2018/848 establishes a harmonized legal framework for organic production and labeling across the European Union. Its implementation mandates stricter controls on the entire supply chain, from soil management to final packaging, increasing compliance burdens. This affects non-EU exporters most acutely, as they must adapt their certification and documentation processes to maintain access to the critical European market, especially Germany.
Consumer demand for radical transparency is altering purchasing criteria in the premium segment. Shoppers are moving beyond simple on-package organic seals, using tools like QR codes to access detailed information on ingredient provenance and farming practices. This behavioral shift is most pronounced in specialty health food stores and online channels in North America and Western Europe.
Organic Pasta Market Segmentation
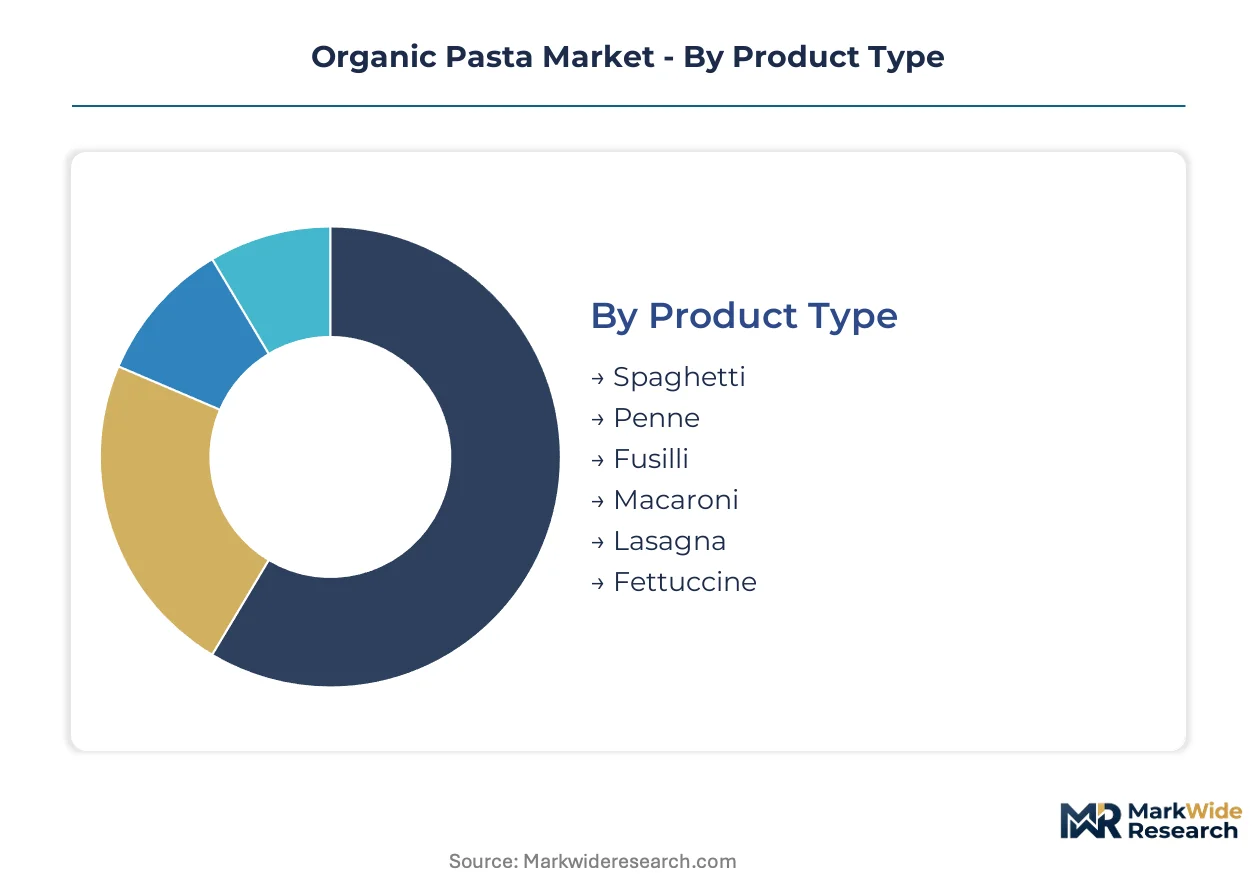
Organic pasta market segmentation reveals how diverse product offerings and consumer access points shape competitive strategies. Understanding these distinct categories helps producers tailor product development and distribution efforts. This granular view highlights areas of concentrated demand and emerging growth trajectories across different product attributes.
Product Type:
Buyers differentiate based on the culinary application and textural preferences for organic pasta shapes.
- Spaghetti:This long, thin, cylindrical pasta is a traditional staple, often made from durum wheat. Demand remains strong in European markets like Italy and Germany for classic pasta dishes, driven by established culinary traditions.
- Penne:Characterized by its short, cylinder shape with angled ends, penne offers versatility in absorbing sauces. Its popularity in North America and Western Europe stems from its suitability for baked dishes and robust sauces.
- Fusilli:Spiral-shaped pasta, ideal for holding thicker sauces.
- Macaroni:Small, curved tube pasta, frequently used in comfort food preparations.
- Lasagna:Wide, flat pasta sheets designed for layered baked dishes.
- Fettuccine:Flat, thick pasta strands, commonly paired with creamy sauces.
Volume sits with Spaghetti; growth tilts toward Penne.
Ingredient Source:
Consumer dietary preferences and health considerations significantly influence the choice of organic pasta ingredient sources.
- Whole Wheat:Made from the entire wheat kernel, whole wheat pasta offers higher fiber content and a distinct texture. Health-conscious consumers in Germany and the United States frequently choose this option for its nutritional benefits.
- Chickpea:This legume-based pasta provides a high-protein, gluten-free alternative, appealing to specific dietary needs. Demand for chickpea pasta is expanding across online retail channels in North America due to its functional properties.
- Brown Rice:A popular gluten-free alternative, offering a milder flavor profile.
- Quinoa:Valued for its complete protein and ancient grain status, attracting wellness-oriented buyers.
- Buckwheat:Offers an earthy flavor and is naturally gluten-free, favored in certain traditional cuisines.
- Amaranth:An ancient grain providing nutritional density and a unique texture in pasta formulations.
Whole Wheat maintains its market dominance, while chickpea-based varieties demonstrate the steepest expansion trajectory.
Packaging Type:
Packaging type reflects both the volume of product and consumer convenience requirements across retail environments.
- Box:Cardboard boxes are a traditional and widely used packaging format, offering structural integrity and shelf appeal. Supermarkets in the European Union and North America primarily stock boxed organic pasta for standard consumer purchases.
- Pouch:Flexible pouches provide convenience, lighter weight, and often resealable options for consumers. Online retailers increasingly utilize pouch packaging for its shipping efficiency and reduced material waste.
- Vacuum Pack:Extends shelf life and preserves freshness, often used for fresh or specialty organic pasta.
- Bulk Bag:Large format packaging, primarily for foodservice or institutional buyers.
- Plastic Wrap:Used for fresh pasta varieties, ensuring visibility and moisture retention.
- Paper Bag:An eco-friendly option gaining traction, particularly for dry organic pasta sold in health food stores.
Box packaging accounts for the largest share, with pouches gaining share fastest due to e-commerce growth.
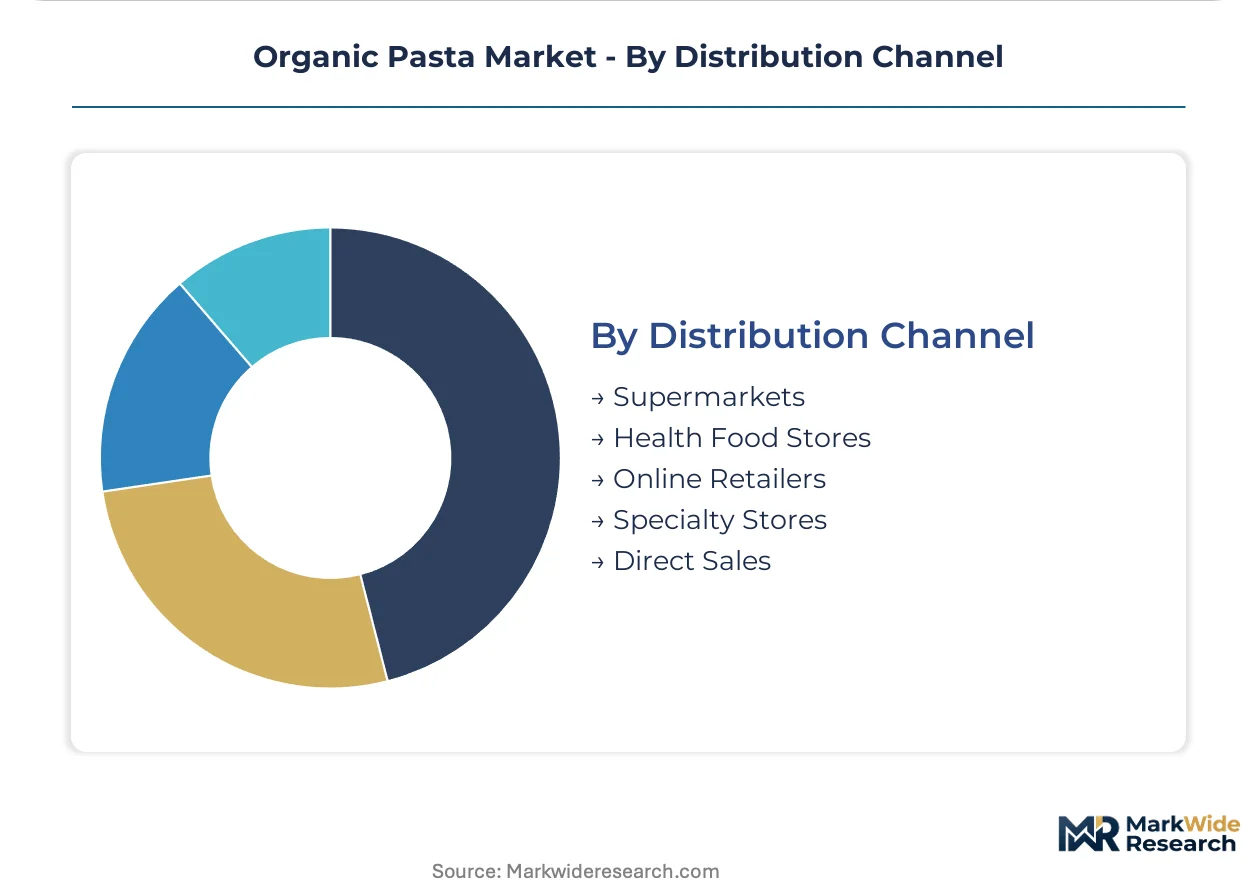
Distribution Channel:
Market access and brand visibility for organic pasta are critically determined by the chosen distribution channels.
- Supermarkets:These large retail chains provide broad market penetration and convenience for mainstream consumers. Barilla Group and other large manufacturers leverage extensive supermarket networks across Europe and North America to reach a wide customer base.
- Online Retailers:E-commerce platforms offer unparalleled product variety and direct-to-consumer delivery, catering to niche organic product seekers. Sales through online channels in the United States and Germany are expanding most quickly, driven by convenience and selection.
- Health Food Stores:Cater to wellness-oriented consumers seeking certified organic and natural products.
- Specialty Stores:Focus on premium, gourmet, or artisanal organic pasta, often emphasizing provenance.
- Direct Sales:Includes farm-to-consumer models or direct-from-producer websites, emphasizing authenticity.
Supermarkets remain the primary volume channel, but online retailers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The availability of organic durum wheat in Italy, a traditional pasta-producing nation, underpins regional market dynamics. Consumer demand for health-oriented foods drives expansion across various European and North American markets. Policy support for organic farming further shapes raw material sourcing.
Germany
Demand for certified organic foods remains consistently strong in Germany, with consumers seeking clean-label attributes. Regulation (EU) 2018/848 mandates strict organic certification across the entire supply chain within the European Union. Berlin and Hamburg represent key urban centers for specialized health food stores, driving niche product demand.
Italy
Italian consumers prioritize traditional recipes and regional authenticity, influencing ingredient choices. Italy's historic pasta purity laws significantly influence ingredient specifications for domestic producers. The Emilia-Romagna region maintains a strong hub for artisanal pasta production, focusing on traditional methods.
United States
Health-conscious consumers in the United States drive demand for fiber-rich whole wheat and protein-rich chickpea pastas. The USDA National Organic Program defines strict standards for organic ingredient sourcing and product labeling nationwide. California's diverse food scene supports innovation in alternative grain pasta products and distribution channels.
South Korea
Rising disposable incomes and wellness trends influence organic food purchases in South Korea, particularly for premium products. The MFDS oversees food safety and organic labeling standards for both domestic and imported food products. Seoul's urban population shows a growing interest in premium organic food offerings, expanding market reach.
France
French consumers show increasing interest in organic food products, including pasta, driven by health and environmental concerns. The EU Green Deal initiatives support organic agriculture conversion across France, impacting raw material availability. Provence-Alpes-Côte d'Azur features a growing number of organic food producers and specialized retailers.
Organic Pasta Market Key Industry Players
Global majors compete with regional champions across distribution network breadth and product diversification strategies. The market structure exhibits a tiered consolidation, with large-scale producers holding significant volume share in conventional channels. Strategic archetypes include conventional market leaders, specialized organic manufacturers, and artisanal producers focused on regional authenticity. Portfolio diversification into alternative grain varieties and geographic expansion into new markets represent dominant competitive moves.
Barilla Group, a large-scale manufacturer, leverages extensive distribution networks to maintain market share across conventional channels, offering a wide range of pasta products globally. Ebro Foods S.A. exemplifies a company specializing in integrating diverse grain types into its product lines, from brown rice to quinoa, catering to evolving dietary preferences and health trends. Smaller players such as Rummo S.p.A. represent artisanal producers competing on traditional production methods and regional authenticity within specific geographic segments, appealing to premium consumers seeking provenance.
| Leading Market Players |
|---|
| Barilla Group |
| Nestlé S.A. |
| Ebro Foods S.A. |
| F.lli De Cecco di Filippo S.p.A. |
| Conagra Brands, Inc. |
| TreeHouse Foods, Inc. |
| General Mills Inc. |
| Danone SA |
| Rummo S.p.A. |
| Others |
Cost & Logistics Intelligence
Supermarkets, as primary volume buyers, significantly influence organic pasta pricing, driving transactional models in conventional channels. Their purchasing power shapes pricing strategies for large-scale manufacturers.
Pricing Analysis
Certification and traceability features are implicitly bundled into organic pasta pricing, reflecting the product's integrity. The dominant pricing model is transactional, with premium-mid-economy pricing differentiation observed across channels. Quality grade, including specific organic certifications like USDA NOP, and novel ingredient sources like chickpea flour, drive price differentiation. Pricing pressure stems from organic grain price volatility and lower yield discrepancies in organic farming. Consumers purchasing through specialty health food stores exhibit lower price sensitivity compared to mainstream supermarket buyers.
Supply Chain Analysis
Compliance with stringent organic certification standards, such as Regulation (EU) 2018/848 and USDA NOP, gates market entry and raw material sourcing. Geographic supply concentration for traditional organic durum wheat remains strong in Italy, while alternative organic grains are sourced globally. The supply chain draws from organic durum wheat, chickpea, and quinoa. Commodity price volatility for organic grains represents a significant structural risk. Distribution runs through supermarkets, online retailers, and specialized health food stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic pasta market presents a supply-constrained growth story, with limited organic raw material availability creating a capacity bottleneck. This constraint inherently props up premium pricing for certified products.
For Market Incumbents:Lock in long-term supply contracts for organic durum wheat and alternative grains to mitigate price volatility. Large-scale manufacturers should invest in advanced extrusion and milling technologies for novel ingredients like chickpea and lentil, preventing market share erosion from specialized players. Enhance supply chain traceability using blockchain to reinforce brand trust against cross-contamination risks. Leverage existing extensive distribution networks to maintain market presence in conventional channels.
For New Entrants and Emerging Players:Advanced extrusion and milling technologies offer a primary wedge for new entrants to create novel organic pasta products. Target functional ingredient integration with high-protein legumes like lentils and fava beans, appealing to health-conscious consumers. South Korea represents a penetrable geography due to rising disposable incomes and organic awareness. Leverage online retail channels and specialty health food stores for direct market access and niche brand visibility.
For Investors and Strategic Acquirers:The window for entry favors specialized organic manufacturers with established certification and robust supply chain traceability. The market demonstrates long-term viability, supported by sustained consumer wellness orientation and policy support for organic agriculture. Identify acquisition targets among artisanal producers like Rummo S.p.A., known for regional authenticity or unique ingredient formulations. Increasing adoption of blockchain for ingredient provenance verification serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Alternative Grains | Increases raw material availability and reduces reliance on traditional durum wheat sources. |
| Integration of Diverse Grain Types | Broadens product portfolio to meet evolving consumer dietary preferences and health trends. |
| Blockchain-Enabled Supply Chain Traceability | Enhances consumer trust by providing verifiable proof of organic ingredient provenance. |
| Functional Ingredient Fortification | Attracts health-conscious and athletic demographics with high-protein legume-based pastas. |
| Asia-Pacific Market Entry | Captures new demand from rising disposable incomes and organic awareness in countries like South Korea. |
Research Approach
USDA National Organic Program guidelines, Regulation (EU) 2018/848, and specialized food trade publications formed the secondary backbone for this analysis. Industry stakeholders, including organic pasta production executives, retail buyers from health food stores, and organic grain suppliers, provided primary insights. This involved combining qualitative interviews with quantitative data validation. Bottom-up market sizing was triangulated with top-down validation across key segments.
A robust analytical framework combined bottom-up market sizing for product types and ingredient sources with top-down validation across distribution channels. Segmentation dimensions modeled included product type, ingredient source, packaging type, and key geographic regions. Compound annual growth rates were projected from historical expansion, key catalysts, and expert insights across the analysis window. Organic grain yields and evolving consumer wellness spending served as critical forecast inputs.
Several conditions sit outside the modeled scope, including specific regional trade agreements and unforeseen climate events impacting organic grain harvests. Forecasts reflect assumptions regarding stable regulatory frameworks and consistent consumer adoption. A model refresh is warranted upon material change in organic agriculture policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Global Organic Packaged Food Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
Spain Organic Food Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Germany Organic Food Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
Japan Organic Food Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Organic Ice Cream Market