
 Natural Food and Drinks Market | 2026-2036
Natural Food and Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Food and Drinks Market Foresight
A capital-intensity divergence between multinational conglomerates and agile specialty producers is rotating competitive dynamics across the natural food and drinks sector. Nestlé S.A. leverages its global procurement infrastructure to secure organic ingredient volumes at scale. Amy's Kitchen, Inc. differentiates through frozen natural entree specialization and family-owned operational autonomy. The Hain Celestial Group, Inc. anchors its position in organic pantry staples and personal care adjacencies.
Natural food and drinks encompass consumable products formulated without synthetic preservatives, artificial colors, genetically modified organisms, or chemical additives, typically certified through USDA Organic, EU Organic, or equivalent third-party verification systems requiring minimum organic ingredient thresholds. The primary commercial purpose centers on delivering transparency-assured nutrition to consumers seeking ingredient traceability and reduced processing intensity. Organic snacks and plant-based dairy command the largest revenue pools within product type segmentation, while cold-pressed juices represent the fastest-growing sub-category as refrigerated supply chain infrastructure expands. Biodegradable and recyclable packaging formats gain structural priority as retailer sustainability mandates tighten and consumer disposal preferences shift.
FDA enforcement of food labeling standards under the Food Safety Modernization Act intersects with USDA Organic certification requirements to define market access thresholds for domestic producers. EFSA and EU Organic regulations govern European import eligibility and formulation compliance, creating dual jurisdictional complexity for multinational portfolios. Stakeholders must monitor evolving definitions of "natural" across regulatory bodies, as pending standardization efforts threaten to invalidate existing brand positioning claims and force reformulation investments.
Market Dynamics
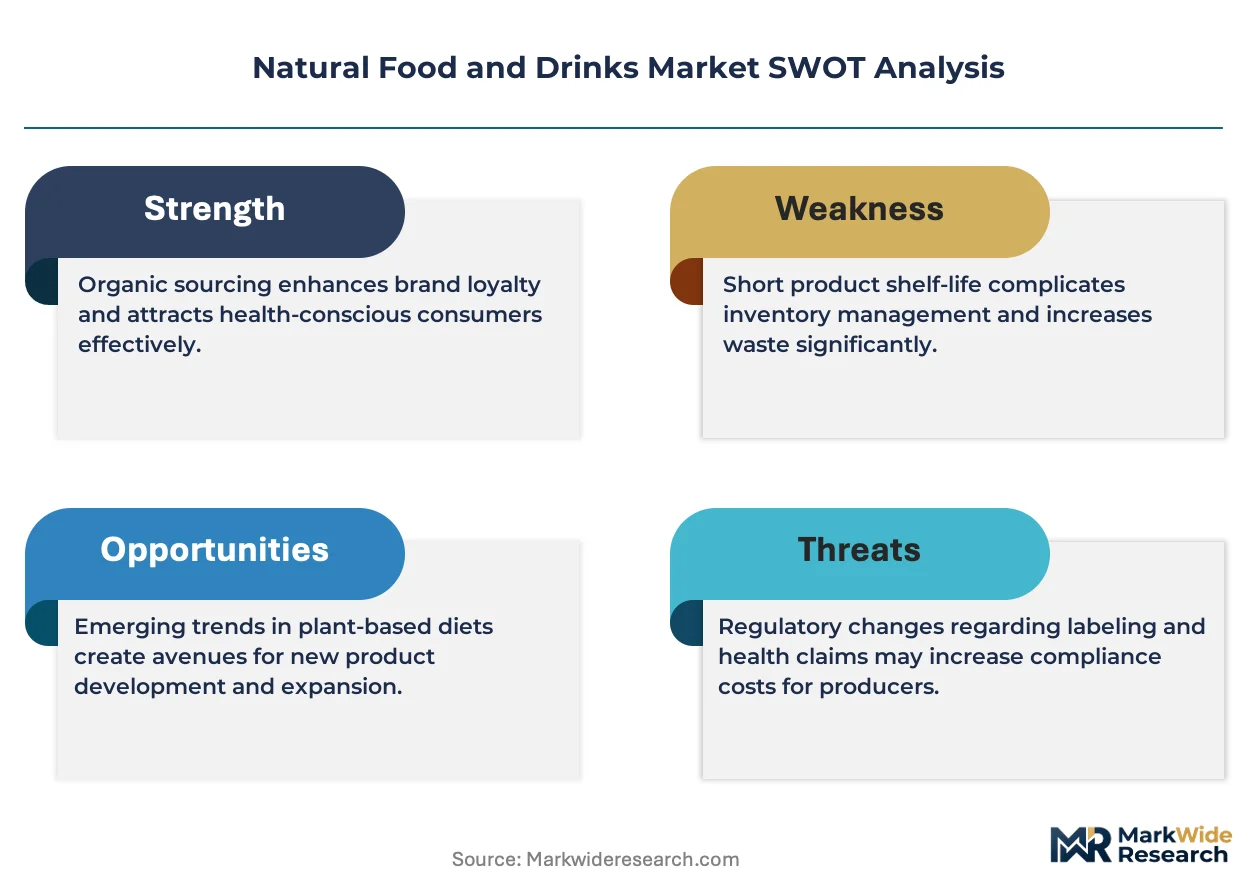
Clean-label regulatory tightening under FDA and EFSA scrutiny is forcing simultaneous reformulation across multinational portfolios, compressing margin structures while elevating compliance costs as the dominant market-shaping force.
Growth Catalysts
- USDA Organic certification thresholds:Federal enforcement of 95% organic ingredient minimums creates transparent procurement standards that specialty retailers leverage to command shelf placement premiums.
- Plant-based protein extraction technologies:Enzymatic and fermentation-based processes reduce input costs for oat, pea, and almond milk alternatives, accelerating substitution of conventional dairy in foodservice channels.
- Urban millennial concentration:Dense metropolitan clusters in New York, London, and Tokyo generate concentrated demand for grab-and-go organic snacks and cold-pressed juice formats.
Market Restraints
- Organic ingredient supply concentration:Certified organic acreage concentrates in California, Midwestern US grain belts, and select European cooperatives, creating procurement bottlenecks during weather disruptions.
- Refrigerated logistics cost structures:Cold-chain infrastructure requirements for raw, unpasteurized, and minimally processed products impose 40-60% distribution cost premiums versus ambient shelf-stable alternatives.
- EU Organic import equivalence barriers:Non-EU producers face multi-year approval timelines and inspection costs to achieve recognition under EC 834/2007, limiting market access for emerging suppliers.
Strategic Opportunities
- Regenerative agriculture certification layering:USDA Organic plus Regenerative Organic Certified dual-label products capture carbon-conscious consumers willing to pay tiered premiums for soil health verification.
- Direct-to-subscription channel expansion:Weekly or biweekly replenishment models for fresh meal kits and cold-pressed juices bypass traditional retail slotting fees while building recurring revenue visibility.
- Upcycled ingredient valorization:Fruit pomace, brewer's spent grain, and vegetable trim conversion into fiber-enriched snacks and beverages addresses food waste mandates while reducing input costs.
Industry Challenges
- Clean-label formulation expertise scarcity:Food scientists capable of replacing synthetic preservatives with natural alternatives (cultured dextrose, rosemary extract, high-pressure processing) command compensation premiums that strain R&D budgets.
- Multi-jurisdictional certification synchronization:Maintaining simultaneous USDA Organic, EU Organic, and JAS Organic compliance requires dedicated regulatory affairs staff and creates audit scheduling conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Food and Drinks Market |
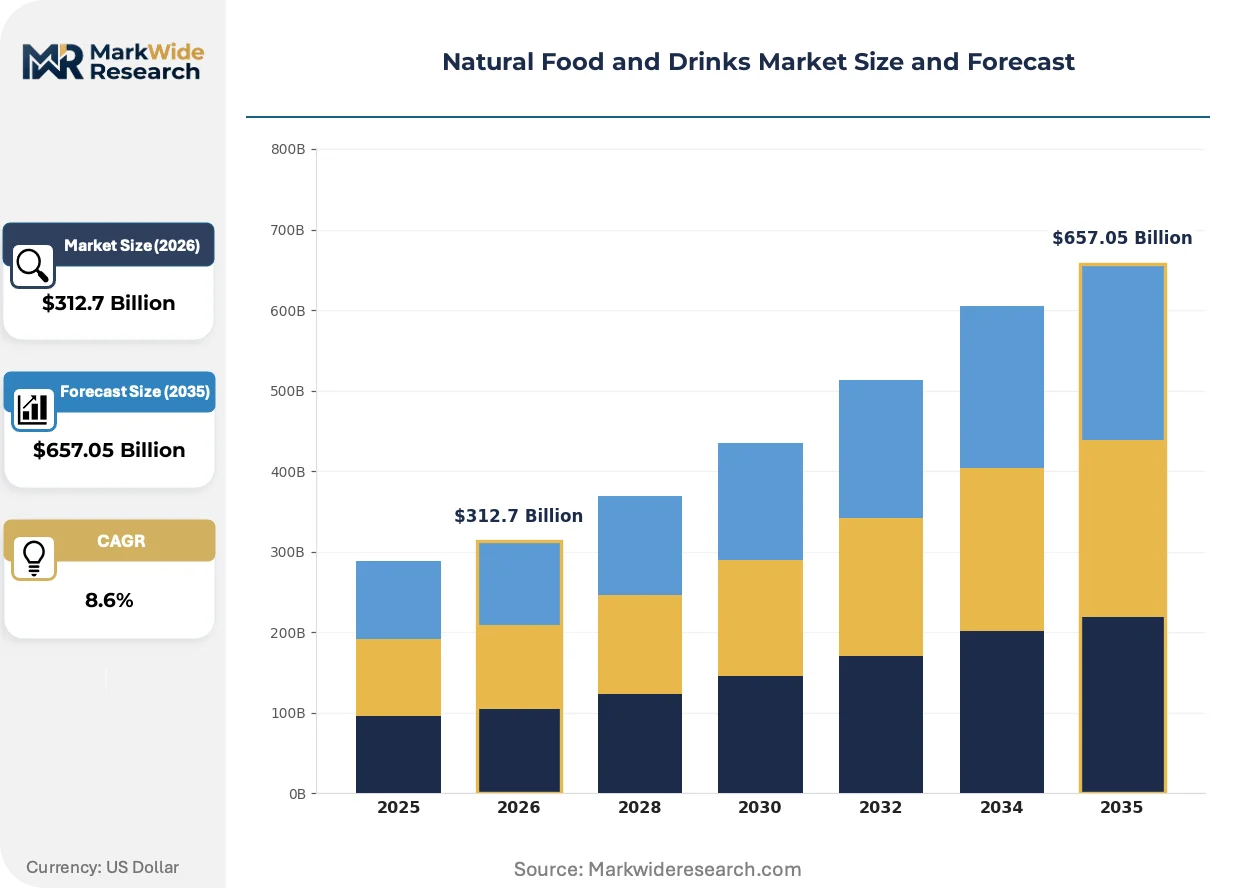
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Snacks, Cold-Pressed Juices, Plant-Based Dairy, Natural Sweeteners Ingredient Source: Herbs, Fruits, Vegetables, Grains Packaging Type: Biodegradable, Recyclable, Glass, Tetra Pak Distribution Channel: Online Retail, Supermarkets, Health Stores, Farmers' Markets |
| Companies Covered | Nestlé S.A., General Mills, Inc., Conagra Brands, Inc., Archer Daniels Midland Company, The Hain Celestial Group, Inc., Amy's Kitchen, Inc., Danone S.A., PepsiCo Inc., The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Food and Drinks Market Shifts & Advancements
Biodegradable packaging mandates and precision fermentation are restructuring how natural food products achieve shelf differentiation and cost parity with conventional alternatives.
High-pressure processing (HPP) technology is displacing thermal pasteurization in raw juice and ready-to-eat meal segments. Premium retailers and foodservice operators in coastal US markets and Japanese convenience chains adopt HPP at accelerating rates. This non-thermal pathogen reduction method preserves enzyme activity and vitamin content while extending refrigerated shelf life, compressing the freshness advantage gap between centralized production and local manufacturing.
EFSA's evolving position on novel food ingredients under Regulation (EU) 2015/2283 creates compliance uncertainty for precision-fermented proteins and cellular agriculture derivatives. European ingredient suppliers face extended safety assessment timelines that delay product launches versus US or Asian regulatory pathways. Plant-based dairy and alternative protein startups concentrate initial commercialization efforts in FDA-governed markets while awaiting EFSA clarity.
Retailers are consolidating supplier sustainability reporting requirements through proprietary scorecards that extend beyond organic certification to encompass water usage, regenerative practices, and packaging circularity. Natural product manufacturers must now maintain dual compliance with USDA Organic standards and retailer-specific ESG data portals. German and Dutch supermarket chains lead this procurement model evolution, forcing reformulation and packaging investments from international suppliers seeking shelf access.
Natural Food and Drinks Market Segmentation
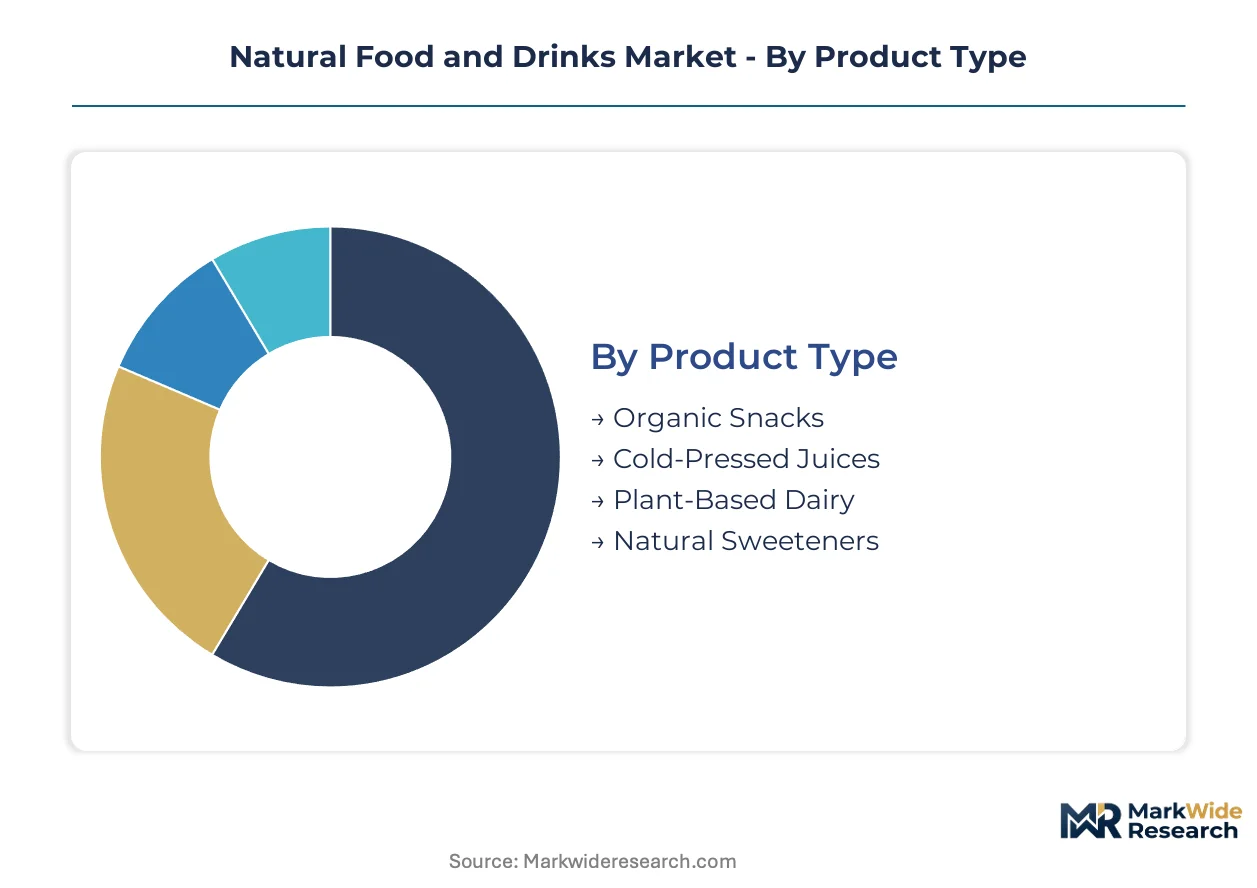
Segmentation in the natural food and drinks sector reveals how certification requirements, shelf-life constraints, and channel economics partition demand across distinct product-positioning strategies. Each dimension carries implications for procurement sourcing, cold-chain investment, and margin structure.
Product Type:
Channel-mix patterns diverge sharply across product categories, with refrigerated formats concentrating in premium supermarkets and direct-to-consumer models while shelf-stable variants penetrate conventional retail at scale.
- Organic Snacks:Shelf-stable formulations including puffed grains, dried fruit clusters, and seed-based bars rely on minimal processing and certified organic ingredient sourcing. Demand clusters in urban grab-and-go convenience formats across New York, London, and Tokyo, where millennial consumers prioritize portability and transparent ingredient panels.
- Cold-Pressed Juices:Raw vegetable and fruit blends processed through hydraulic pressing without thermal degradation retain enzyme activity and vitamin density. Expansion concentrates in subscription replenishment models and Japanese convenience chains, though refrigerated logistics impose 40-60% distribution cost premiums relative to ambient alternatives.
- Plant-Based Dairy:Oat, almond, and pea protein beverages formulated without synthetic stabilizers.
- Natural Sweeteners:Monk fruit, stevia, and coconut sugar derivatives replacing refined sucrose.
Organic Snacks dominates installed base. Cold-Pressed Juices is where expansion concentrates.
Ingredient Source:
Cost-tier stratification separates commodity-scale grain and vegetable inputs from premium herb and fruit concentrates commanding formulation premiums.
- Herbs:Botanical extracts including turmeric, ginger, and adaptogenic roots used in functional beverages and wellness shots. Procurement concentrates in certified organic cooperatives across India and select European growing regions, with supply bottlenecks during monsoon disruption cycles.
- Fruits:Berries, citrus, and tropical varieties processed into purees, concentrates, and freeze-dried inclusions. Demand is climbing the fastest in cold-pressed juice and natural snack applications, particularly acai and pomegranate variants with antioxidant positioning.
- Vegetables:Leafy greens, root vegetables, and cruciferous varieties.
- Grains:Oats, quinoa, and ancient wheat varieties.
Grains anchor volume throughput. Herbs capture margin expansion.
Packaging Type:
Retailer sustainability mandates and ESG reporting requirements are forcing alignment between packaging format selection and circularity verification standards.
- Biodegradable:Compostable films and molded fiber containers derived from plant starches and agricultural residues. German and Dutch supermarket chains mandate biodegradable formats for private-label natural products, creating procurement specifications that ripple through supplier tiers.
- Recyclable:Mono-material polyethylene and polypropylene structures compatible with existing municipal recycling streams. Adoption accelerates in US conventional retail channels where operational simplicity outweighs composting infrastructure gaps.
- Glass:Inert, infinitely recyclable containers for premium positioning.
- Tetra Pak:Aseptic carton formats for ambient-stable liquid products.
Recyclable formats dominate current shelf presence. Biodegradable is gaining share fastest as retailer mandates tighten.
Distribution Channel:
Customer-type stratification separates subscription-committed wellness consumers from transaction-oriented supermarket shoppers and relationship-driven farmers' market patrons.
- Online Retail:Direct-to-consumer platforms and third-party marketplaces enabling subscription replenishment and personalized curation. Cold-pressed juice startups and meal kit operators bypass slotting fees while building recurring revenue visibility through weekly delivery models.
- Supermarkets:Conventional and premium grocery chains with dedicated natural product sections. USDA Organic certification thresholds determine shelf placement premiums, with specialty retailers leveraging 95% organic minimums to justify price positioning.
- Health Stores:Independent and chain specialty retailers with educated staff and curated assortments.
- Farmers' Markets:Direct producer-to-consumer venues with minimal intermediation.
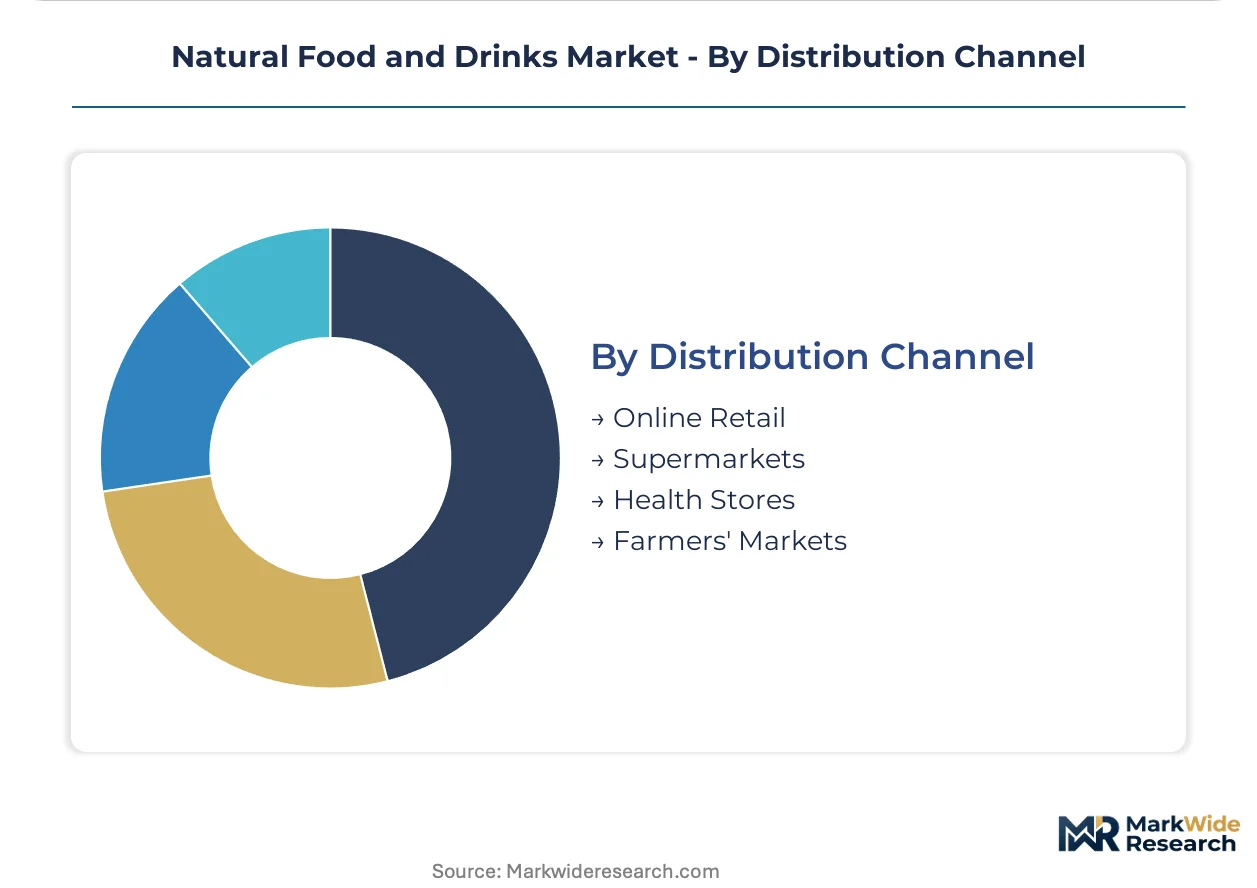
Supermarkets anchor volume scale. Online Retail is where customer acquisition economics are restructuring fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for organic raw materials shapes competitive positioning across major consuming markets, with procurement geography dictating formulation cost structures and certification complexity for multinational portfolios.
United States
Urban millennial clusters in New York, Los Angeles, and Chicago drive refrigerated format adoption for cold-pressed juices and plant-based dairy alternatives. FDA enforcement of the Food Safety Modernization Act intersects with USDA Organic certification thresholds, creating dual compliance burdens for domestic producers. California's Central Valley anchors organic vegetable and fruit concentrate supply, though drought cycles periodically constrain ingredient availability.
Germany
Discounter and supermarket chains mandate biodegradable packaging formats for private-label natural products, forcing supplier-tier investments in compostable film technologies. EFSA scrutiny of novel food ingredients under Regulation (EU) 2015/2283 creates extended approval timelines for precision-fermented proteins. The Rhine-Ruhr metropolitan corridor concentrates demand for organic pantry staples and regenerative agriculture-certified offerings.
Japan
JAS Organic certification requirements govern import eligibility for foreign suppliers, with multi-year equivalence negotiations limiting market access for emerging producers. METI guidelines on sustainable food systems accelerate retailer ESG reporting mandates beyond certification standards. Tokyo and Osaka convenience chains expand HPP-treated juice and ready-to-eat meal placements, compressing freshness gaps between centralized and local production.
United Kingdom
Post-Brexit divergence from EU Organic regulations creates parallel certification requirements for suppliers serving both British and continental European markets. Soil Association standards often exceed baseline EU Organic thresholds, enabling premium positioning in specialty retail channels. London's dense urban core sustains subscription-based cold-pressed juice replenishment models bypassing traditional retail slotting structures.
India
FSSAI enforcement of organic food labeling standards under the Food Safety and Standards (Organic Foods) Regulations creates domestic market access thresholds for certified producers. Export-oriented organic spice and herb processing clusters in Kerala and Karnataka supply ingredient inputs to European and North American formulators. Mumbai and Bangalore urban centers exhibit nascent demand for plant-based dairy alternatives among affluent consumer segments.
Natural Food and Drinks Market Competitive Landscape
Concentration sits with multinational conglomerates leveraging procurement scale against agile specialty producers defending margin through certification depth and format specialization. Tiered competitive dynamics separate volume-driven ambient shelf-stable portfolios from refrigerated premium-positioned offerings requiring cold-chain infrastructure. Three archetypes dominate: diversified food majors with organic line extensions, pure-play natural product specialists, and private-label manufacturers serving retailer sustainability mandates. M&A activity targets certified organic ingredient suppliers and regional cold-pressed juice brands, while portfolio diversification into regenerative agriculture certification layering captures carbon-conscious consumer premiums.
Within the diversified conglomerate tier, Nestlé S.A. and PepsiCo Inc. occupy positions exemplifying procurement infrastructure leverage across multiple certification jurisdictions. Among pure-play specialists, Amy's Kitchen, Inc. and The Hain Celestial Group, Inc. represent archetypes of family-owned operational autonomy and organic pantry staple anchoring respectively. These named entities serve as structural anchors for understanding how scale advantages intersect with certification authenticity positioning across the competitive map.
| Leading Market Players |
|---|
| Nestlé S.A. |
| General Mills, Inc. |
| Conagra Brands, Inc. |
| Archer Daniels Midland Company |
| The Hain Celestial Group, Inc. |
| Amy's Kitchen, Inc. |
| Danone S.A. |
| PepsiCo Inc. |
| The Coca-Cola Company |
| Others |
Supply & Pricing Matrix
Long-term organic ingredient offtake agreements between certified California cooperatives and multinational formulators lock in supply access while capping price volatility exposure across the refrigerated natural products segment. These contracts anchor procurement planning for plant-based dairy and cold-pressed juice operators facing margin compression from clean-label reformulation mandates.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the natural food sector. Premium tiers command shelf placement premiums through USDA Organic plus Regenerative Organic Certified dual-label positioning, while economy tiers compete on conventional retail penetration. Price erosion runs through the standard tier as private-label manufacturers replicate certification credentials without brand overhead. Foodservice channels exhibit lowest price sensitivity due to menu premiumization strategies, whereas mass-market retailers drive hardest bargain on slotting fee offsets.
Supply Chain Analysis
Strategic stockpiling of freeze-dried fruit concentrates and ancient grain inventories dominates procurement strategy over just-in-time models, buffering weather-driven supply interruptions. Certified organic acreage concentrates in California, Midwestern US grain belts, and select European cooperatives, creating geographic vulnerability to drought cycles. Raw material dependencies center on organic oats, pea protein isolates, and cold-pressed fruit purees. Tariff exposure on EU Organic equivalence recognition limits market access flexibility. Distribution runs through refrigerated logistics networks serving premium supermarket chains and direct-to-subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural food market fragmentation creates white-space opportunities as millennial demand splinters across regenerative certification, upcycled ingredients, and precision-fermented alternatives. Niche positioning now outperforms mass-market scale in margin capture.
For Market Incumbents: Consolidate procurement scale advantages through backward integration into certified organic ingredient production in California and Midwestern grain belts. Acquire regional cold-pressed juice brands to capture subscription-channel recurring revenue before specialty operators scale. Defend margin position by layering Regenerative Organic Certified credentials atop USDA Organic baselines, creating tiered premium capture that emerging competitors cannot replicate without multi-year soil health verification timelines. For New Entrants and Emerging Players: Direct-to-subscription replenishment gaps in fresh meal kits and cold-pressed juices expose incumbent underinvestment in recurring revenue infrastructure. Target Japanese convenience chains and German biodegradable packaging mandates as most penetrable demand pockets with explicit procurement specifications. Pursue upcycled ingredient valorization as differentiated go-to-market angle, converting fruit pomace and brewer's spent grain into fiber-enriched formats that address food waste mandates while reducing input cost structures. For Investors and Strategic Acquirers: Capital is best deployed toward certified organic ingredient suppliers with multi-jurisdictional compliance infrastructure and established retailer sustainability scorecard relationships. Long-term viability hinges on carbon-conscious consumer premium persistence and regulatory tightening trajectory. Watch EFSA novel food ingredient approval timelines as inflection signal—accelerated pathways for precision-fermented proteins would validate alternative protein platform investments, while extended delays would strand capital in pending regulatory queues.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Certification Layering | USDA Organic plus ROC dual-label products capture carbon-conscious consumer premiums in German and Dutch retail channels. |
| Direct-to-Subscription Channel Expansion | Weekly replenishment models for cold-pressed juices bypass supermarket slotting fees while building recurring revenue visibility. |
| Upcycled Ingredient Valorization | Fruit pomace conversion into fiber-enriched snacks addresses EU food waste mandates while reducing raw material input costs. |
| High-Pressure Processing Technology Adoption | HPP pathogen reduction preserves enzyme activity in raw juices, extending refrigerated shelf life for Japanese convenience chain placement. |
| Biodegradable Packaging Transition | Compostable film investments satisfy German supermarket chain mandates and unlock private-label natural product procurement specifications. |
Research Methodology
Desk research of FDA enforcement records, USDA Organic certification databases, EFSA novel food ingredient submissions, and retailer sustainability scorecard disclosures preceded structured interviews with natural product brand managers, category buyers at premium supermarket chains, cold-chain logistics operators, organic ingredient procurement leads, and regulatory affairs directors at multinational food conglomerates. Primary fieldwork combined with secondary validation through customs trade data and SEC 10-K segment disclosures enabled bottom-up and top-down triangulation across volume and value estimates.
Variance decomposition across product type, ingredient source, packaging format, distribution channel, and certification tier dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate blending weighted by revenue contribution, with cold-pressed juice expansion and plant-based dairy substitution rates as key forecast inputs alongside refrigerated logistics infrastructure buildout trajectories.
Underlying assumptions cover sustained clean-label regulatory tightening, organic ingredient supply elasticity, and millennial urban concentration patterns, with deviation risk concentrated in EU Organic import equivalence negotiations and precision-fermented protein approval timelines. Revision becomes warranted when EFSA novel food safety assessment durations cross threshold delays that compress European launch windows versus FDA-governed pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Germany Organic Food Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
Organic Yogurt Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Organic Juice Market
Organic Food and Beverages
Italy Organic Food Market
Organic Food and Beverages
Scandinavia Organic Packaged Food and Beverages Market
Organic Food and Beverages
Global Organic Packaged Food Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Organic Fast Food Market
Organic Food and Beverages
Global Organic Soup Market