
 Organic Honey Market | 2026-2036
Organic Honey Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Honey Market Outlook
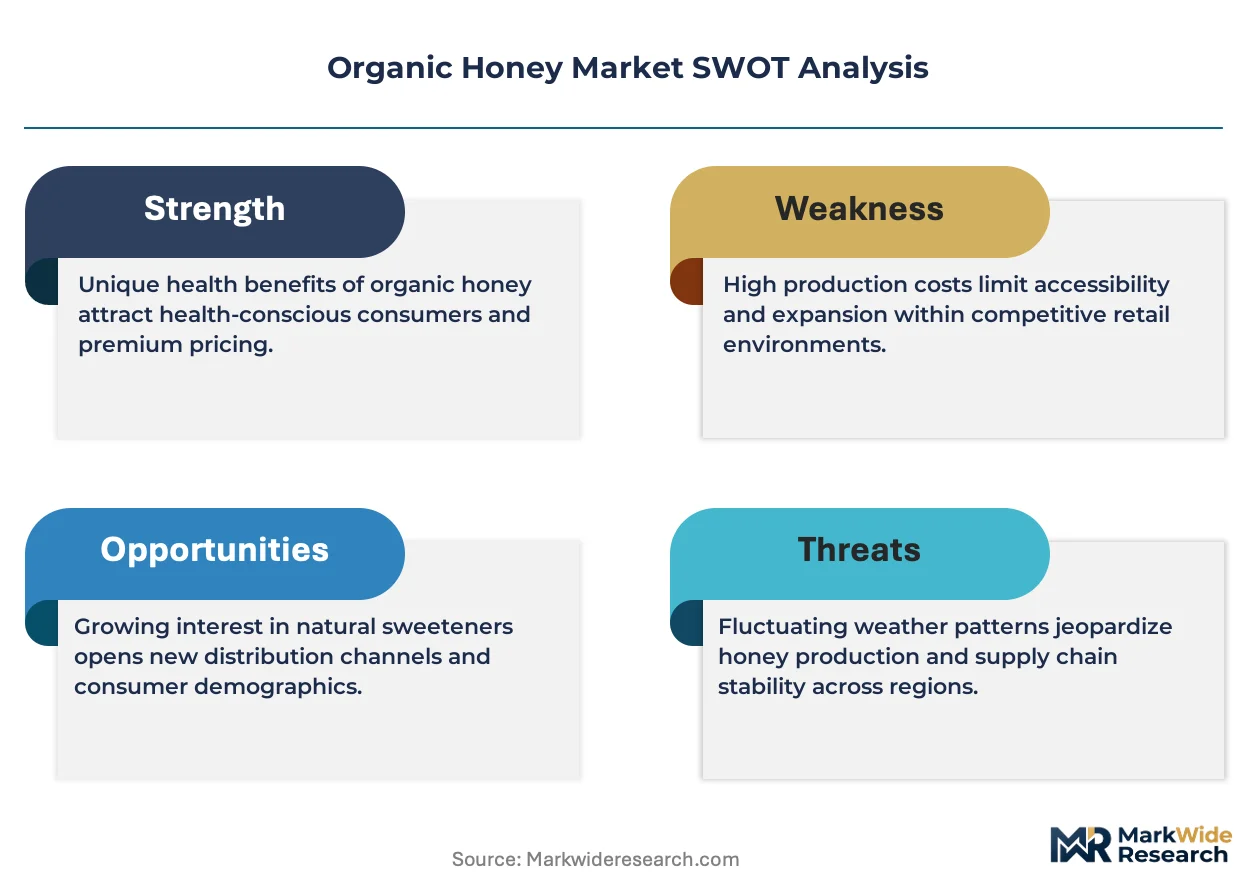
Specialty food retailers and direct-to-consumer channels are expanding their share of organic honey procurement, shifting volume away from conventional grocery consolidation. Heavenly Organics leverages long-term partnerships with Himalayan beekeeper cooperatives to secure multifloral supply chains. Nature Nate's sustains its position through vertically controlled U.S. bottling and third-party organic certification. Manuka Health dominates premium therapeutic-grade positioning with its New Zealand-sourced monofloral lines.
Organic honey is honey produced by Apis mellifera bees that forage on certified organic flora, with production governed by prohibitions on synthetic pesticides, antibiotics, and GMO crops in a defined radius around hives; it must carry residue levels below national organic thresholds and is valued for its enzymatic activity, antioxidant content, and clean-label appeal in food, wellness, and cosmetic applications. Raw honey commands the deepest margin pools among product types due to minimal processing and strong artisan positioning, while Manuka honey captures premium pricing through methylglyoxal-standardized therapeutic grades. Online retail represents the fastest-growing distribution channel, though supermarkets still move the largest absolute volumes through private-label and branded shelf placements.
USDA organic certification, EU organic regulation 2018/848, and New Zealand's MPI manuka honey definition standard collectively determine market access, with each framework imposing distinct traceability, testing, and labeling obligations that filter out non-compliant suppliers. EFSA pesticide residue limits and EPA-approved miticide restrictions for beekeeping operations further constrain allowable inputs and elevate compliance costs for producers. Stakeholders must monitor evolving pollinator health regulations and emerging blockchain traceability mandates that will reshape supplier qualification criteria and buyer risk assessment protocols.
Market Dynamics
EU Green Deal residue-testing protocols and EFSA tightening are forcing import compliance restructuring across the organic honey supply base. Producers must rebuild traceability systems to meet cascading documentary requirements.
Growth Catalysts
- EU organic regulation 2018/848:Harmonized certification standards reduce cross-border friction for certified producers, accelerating market access consolidation.
- Natural cosmetics formulators:Clean-label personal-care brands are expanding certified organic honey procurement as a functional emollient and humectant ingredient.
- German retail concentration:Premium monofloral demand from clean-label food and personal-care brands concentrates procurement power in specialized distribution channels.
Market Restraints
- Input cost volatility:Organic beekeeping labor and certified forage land scarcity elevate production costs relative to conventional honey operations.
- Supply concentration risk:Himalayan and New Zealand monofloral sourcing creates geographic dependency for premium therapeutic-grade supply.
- Regulatory friction:Divergent USDA organic, EU 2018/848, and New Zealand MPI standards force redundant certification investments for multi-market suppliers.
Strategic Opportunities
- Blockchain traceability mandates:Emerging supply chain transparency requirements create first-mover advantage for digitized provenance systems.
- Direct-to-consumer channels:Specialty food retailers and subscription models bypass conventional grocery consolidation, capturing margin expansion.
- API therapeutic applications:Methylglyoxal-standardized Manuka lines are penetrating wound-care and nutraceutical formulations beyond traditional food use.
Industry Challenges
- Certification timeline compression:EFSA residue-testing protocol updates demand accelerated laboratory turnaround without compromising accuracy.
- Apiary management skill scarcity:Organic beekeeping expertise lags demand growth, constraining qualified operator expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Honey Market |
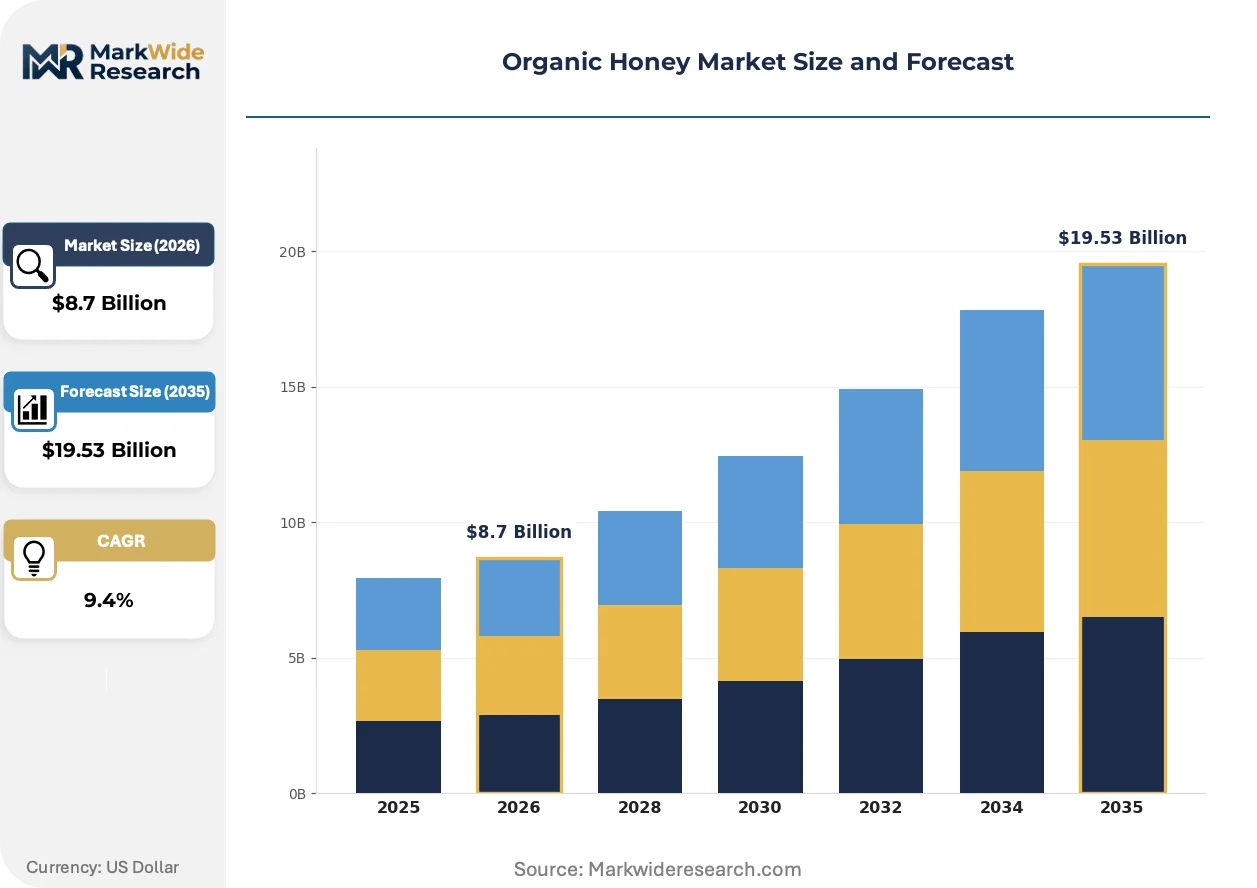
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Honey, Filtered Honey, Manuka Honey, Flavored Honey Packaging Type: Bottles, Jars, Pouches, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Farmers Markets End User: Households, Restaurants, Bakeries, Cosmetics Industry |
| Companies Covered | Heavenly Organics, Nature Nate's, YS Organics, Manuka Health, Barkman Honey, Wedderspoon Organic, Rowse Honey, Madhava, GloryBee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Honey Market Strategic Shifts
Traceability technology and therapeutic-grade standardization are restructuring how organic honey is sourced, certified, and positioned across food, wellness, and cosmetic verticals.
Blockchain-enabled hive-to-shelf tracking systems are expanding into premium organic honey segments. Retailers and brand owners in Germany and the United States are piloting immutable ledger documentation to satisfy EFSA and USDA audit requirements. This transparency infrastructure is compressing supplier qualification cycles and elevating documentation costs for non-compliant producers.
EU Green Deal pollinator health mandates are tightening allowable miticide inputs for organic-certified operations. The framework reduces synthetic pesticide proximity requirements around registered apiaries, forcing land-use adjustments. Balkan and Mediterranean producers face the steepest compliance reconfiguration as they serve German import demand.
Clean-label procurement criteria now prioritize enzymatic activity and antioxidant metrics over origin branding alone. Natural cosmetics manufacturers are displacing conventional emollients with certified organic honey in functional formulations. This specification shift concentrates in German and Austrian personal-care clusters where regulatory thresholds for residue content are most stringent.
Organic Honey Market Segmentation
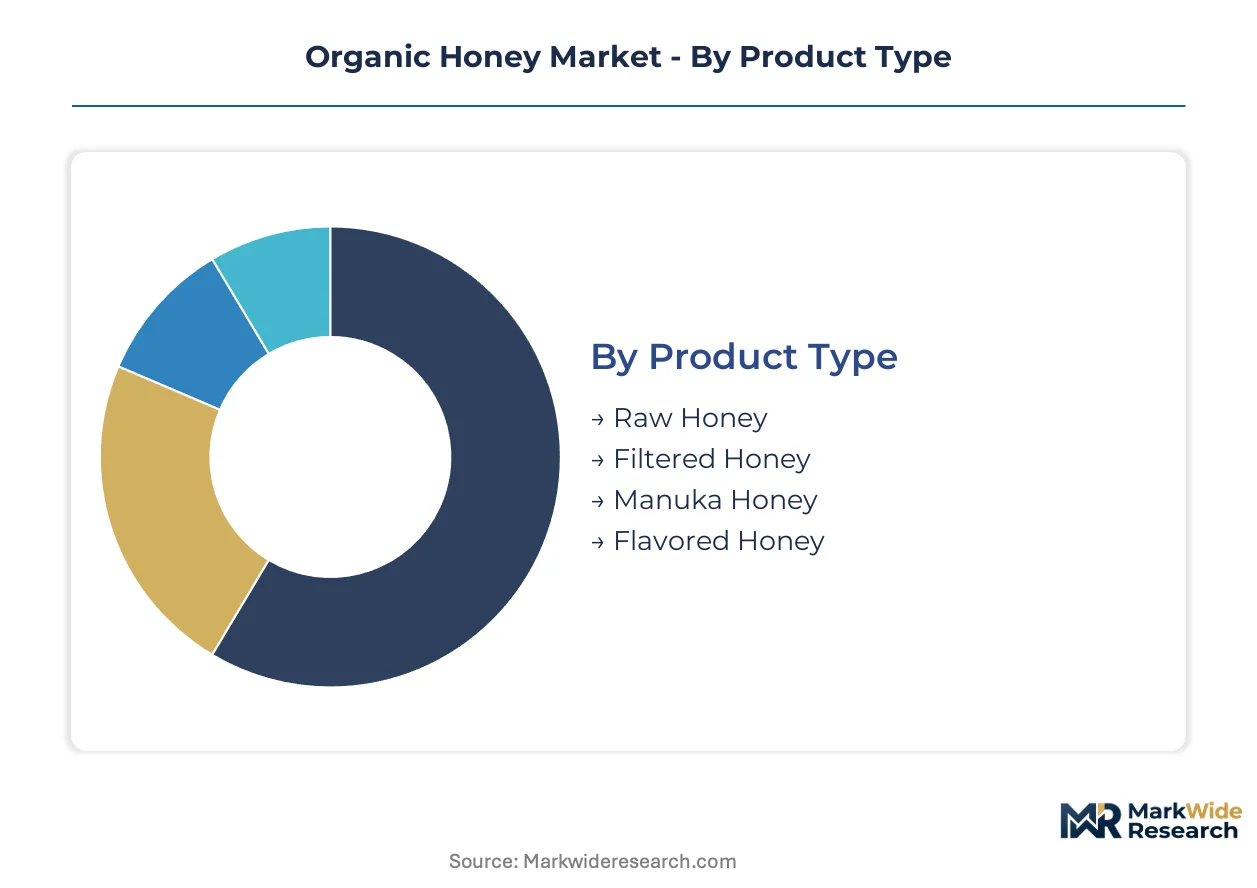
Organic honey segmentation reveals how certification tiers, processing intensity, and channel economics partition value capture across the supply chain. Each dimension carries distinct regulatory burdens and margin structures that determine supplier viability and buyer procurement strategies.
Product Type:
USDA organic and EU 2018/848 certifications apply universally, yet residue-testing stringency varies: raw and Manuka segments face elevated enzymatic activity verification, while filtered and flavored variants trigger additional processing-input disclosures under EFSA protocols.
- Raw Honey:Unheated and unfiltered product retaining native pollen, enzymes, and antioxidant compounds. German clean-label food manufacturers and Austrian natural cosmetics formulators concentrate procurement here, constrained by EU Green Deal forage-land proximity requirements that limit qualified apiary locations.
- Manuka Honey:Monofloral honey from Leptospermum scoparium with methylglyoxal-standardized therapeutic grading. New Zealand's MPI definition standard and UMF certification create dual compliance layers; wound-care and nutraceutical applications in North American and European markets drive premium positioning despite geographic supply concentration.
- Filtered Honey:Strained to remove particulates while maintaining organic certification; thermal limits apply.
- Flavored Honey:Infused with organic botanicals requiring additional input certification and flavor-component traceability.
Leading the category by volume: Raw Honey. Growing fastest: Manuka Honey.
Packaging Type:
Packaging economics stratify across production scale and channel destination, with unit cost and shelf-life requirements determining format selection.
- Bottles:PET and glass formats dominate retail shelf placement; German supermarkets specify recycled-content minimums under packaging waste regulations.
- Jars:Premium positioning vehicle for gift and specialty retail; higher unit economics support artisan brand margins.
- Pouches:Flexible packaging gaining traction in foodservice and travel retail; reduced shipping weight appeals to direct-to-consumer subscription models.
- Bulk Containers:Foodservice and cosmetics manufacturing procurement; drum and tote formats minimize per-kilogram packaging cost for high-volume buyers.
Format concentration tilts toward retail-ready units in Germany and the United States, while bulk formats dominate B2B procurement for natural cosmetics manufacturing clusters.
Distribution Channel:
Channel selection determines margin retention, certification documentation burden, and consumer education requirements.
- Online Retail:Fastest-expanding channel enabling direct hive-to-consumer traceability storytelling; subscription models capture recurring revenue with reduced intermediary certification handoffs.
- Supermarkets:Volume anchor requiring private-label and branded slotting fees; residue-testing documentation must satisfy multiple retailer audit protocols simultaneously.
- Health Food Stores:Specialty retail emphasizing origin narrative and enzymatic activity metrics; staff training on organic certification distinctions sustains premium pricing.
- Farmers Markets:Direct producer-to-consumer sales with reduced packaging and documentation overhead; limited scale constrains revenue contribution.
Supermarkets move the largest absolute volumes, yet online retail captures the steepest expansion trajectory as digital traceability infrastructure matures.
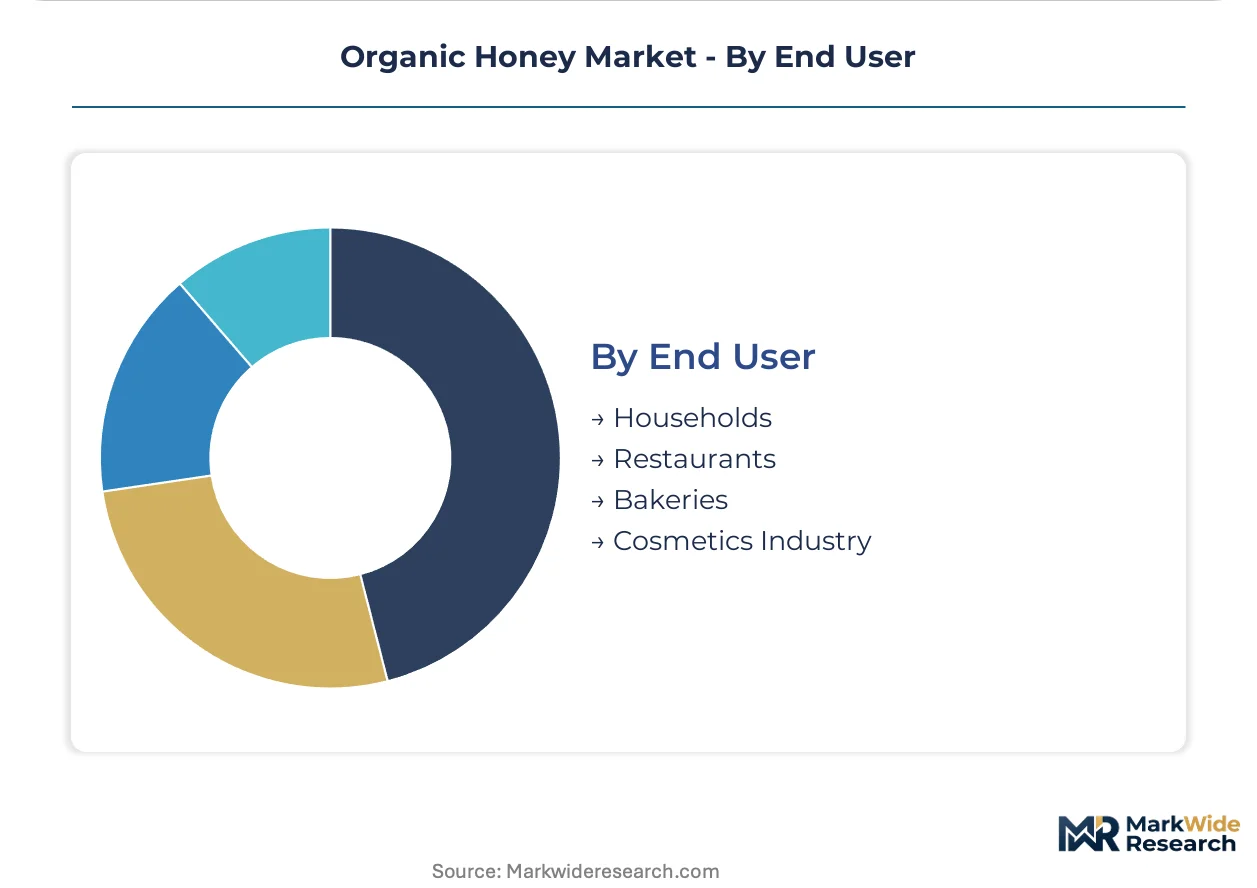
End User:
End-use specifications diverge sharply on residue thresholds, enzymatic activity minimums, and volume procurement patterns.
- Households:Fragmented demand across retail channels; clean-label prioritization drives organic certification recognition but limited technical specification knowledge.
- Restaurants:Foodservice procurement emphasizing consistent supply and cost stability; menu claims require verifiable organic documentation.
- Bakeries:Ingredient-scale buyers with moisture-content and crystallization specifications; bulk purchasing reduces per-unit certification overhead.
- Cosmetics Industry:Most stringent residue and enzymatic requirements; German and Austrian formulators displace conventional emollients with certified organic honey, requiring batch-level traceability and EFSA-compliant testing documentation.
Cosmetics Industry procurement commands the tightest certification standards, while Households represent the broadest addressable base with the shallowest technical engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German clean-label food manufacturers and Austrian cosmetics formulators concentrate premium organic honey procurement, while New Zealand monofloral supply chains anchor therapeutic-grade exports to North America and Asia.
Germany
Natural cosmetics manufacturers in Hamburg and Berlin expand certified organic honey sourcing for emollient formulations. EU regulation 2018/848 and EFSA residue-testing protocols filter import eligibility, forcing Balkan suppliers to rebuild traceability systems. Bavarian retail clusters drive monofloral premiumization through specialized health-food channels.
United States
Direct-to-consumer subscription models and specialty food retailers capture margin expansion from conventional grocery consolidation. USDA organic certification and EPA miticide restrictions constrain allowable beekeeping inputs, elevating compliance costs for domestic producers. Pacific Northwest apiary cooperatives supply raw varietals to West Coast clean-label brands.
New Zealand
Methylglyoxal-standardized Manuka lines penetrate North American wound-care and nutraceutical applications beyond traditional food use. MPI's manuka honey definition standard creates dual compliance layers with EU and US frameworks. North Island production clusters face geographic concentration risk for premium therapeutic-grade supply.
India
Himalayan beekeeper cooperatives supply multifloral organic honey through long-term partnership structures with international brand owners. FSSAI food safety standards and organic certification requirements under NPOP govern export eligibility. Uttarakhand and Himachal Pradesh apiary networks expand capacity to meet German and US import demand.
United Kingdom
Health-food retail chains emphasize origin narrative and enzymatic activity metrics to sustain premium positioning. Retained EU 2018/848 alignment post-Brexit maintains cross-border certification recognition for Irish and continental suppliers. London metropolitan demand concentrates procurement through direct-to-consumer digital channels.
Organic Honey Market Competitive Environment
New Zealand producers anchor premium therapeutic-grade supply; US bottlers and Himalayan cooperatives hold volume and specialty positions respectively. Market structure tilts toward geographic specialization rather than consolidated multinational control. Three archetypes dominate: monofloral standardization specialists, vertically integrated domestic bottlers, and cooperative-sourced multifloral aggregators. Competitive moves center on traceability technology deployment and direct-to-consumer channel bypass of retail intermediaries.
Within the cooperative-sourced tier, Heavenly Organics occupies a position anchored to Himalayan supply networks. Nature Nate's exemplifies the vertically integrated US bottler archetype with third-party organic certification. Manuka Health represents the monofloral standardization specialist segment with New Zealand origin positioning. These three entities collectively illustrate how geographic origin, certification depth, and channel strategy partition competitive space without consolidated market control.
| Leading Market Players |
|---|
| Heavenly Organics |
| Nature Nate's |
| YS Organics |
| Manuka Health |
| Barkman Honey |
| Wedderspoon Organic |
| Rowse Honey |
| Madhava |
| GloryBee |
| Others |
Value Chain & Pricing Dynamics
Certified organic forage land scarcity propagates through Himalayan and New Zealand supply bases into premium tier pricing, while German cosmetics manufacturers absorb elevated input costs through long-term contract structures that lock in monofloral access.
Pricing Analysis
Volume leadership in filtered and raw conventional tiers runs on thin margins, while methylglyoxal-standardized Manuka and certified organic monofloral variants capture substantial premium pools. Three-tier pricing structure across premium therapeutic-grade, standard organic-certified, and economy conventional levels stratifies buyer segments, with German natural cosmetics formulators and North American wound-care applications showing lowest price sensitivity. Pricing pressure stems from EU Green Deal compliance investments forcing Balkan suppliers to recertify traceability systems. Bulk procurement through foodservice and cosmetics manufacturing channels exhibits highest price elasticity.
Supply Chain Analysis
Single-source vulnerability sits with New Zealand's North Island for Manuka monofloral and Himalayan cooperatives for multifloral organic supply. Raw material flows draw from Leptospermum scoparium nectar zones, certified organic pasture networks, and migratory apiary corridors across Uttarakhand and Himachal Pradesh. Tariff exposure from EU 2018/848 residue-testing protocol updates threatens Balkan and Mediterranean supplier access to German import channels. Distribution runs through direct-to-consumer subscription platforms, specialty health-food retail, and bulk B2B procurement for natural cosmetics manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as EFSA residue-testing timeline compression and blockchain traceability mandates force sub-scale producers into exit or acquisition.
For Market Incumbents: Acquire digitized hive-to-shelf traceability infrastructure to preempt regulatory disqualification. Backward integration into certified organic forage land in Balkan and Mediterranean zones secures supply continuity under EU Green Deal proximity requirements. Manuka Health and Nature Nate's archetypes demonstrate how geographic origin control and domestic bottling capacity defend margin position against import compliance friction. For New Entrants and Emerging Players: Blockchain-enabled provenance platforms offer technology-first entry into premium organic segments underserved by legacy documentation systems. White-space concentration sits with Austrian cosmetics formulators seeking batch-level enzymatic activity verification and Pacific Northwest apiary cooperatives supplying West Coast clean-label subscription channels. Direct-to-consumer subscription models bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor Himalayan cooperative-sourced aggregators with established German retail relationships and incomplete traceability digitization. Long-term viability hinges on acquiring entities with locked organic forage access and existing EFSA-compliant laboratory partnerships. Monitor EU 2018/848 implementation enforcement variance across member states as inflection signal for import eligibility restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | Immutable ledger documentation satisfies EFSA and USDA audit requirements while compressing supplier qualification cycles. |
| Certified Organic Forage Land Acquisition | EU Green Deal proximity mandates force land-use adjustments that favor early movers in Balkan and Mediterranean zones. |
| Direct-to-Consumer Channel Launch | Subscription models capture recurring revenue with reduced intermediary certification handoffs and enhanced margin retention. |
| Methylglyoxal Standardization Investment | MPI-compliant therapeutic grading unlocks wound-care and nutraceutical applications beyond traditional food use. |
| Cooperative Partnership Structuring | Long-term agreements with Himalayan beekeeper networks secure multifloral supply chains against geographic concentration risk. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with organic certification officers, natural cosmetics formulators, apiary cooperative managers, and German health-food retail buyers. Bottom-up volume modeling triangulated against top-down expenditure analysis across product type, packaging format, distribution channel, and end-user segments. EFSA residue-testing protocols, USDA organic certification databases, and New Zealand MPI manuka honey definition standards provided regulatory boundary conditions.
Granularity-level modeling operated at SKU-equivalent resolution for raw, Manuka, filtered, and flavored product types, cross-tabulated against household, restaurant, bakery, and cosmetics industry end-use specifications. CAGRs derived from exponential curve fitting across the projection horizon, with enzymatic activity verification trends and pollinator health regulation trajectories informing segment-specific growth differentials. Supply-side constraints from certified forage land availability and apiary management skill scarcity informed capacity ceiling assumptions.
Several conditions sit outside the modeled scope, including extreme climate events affecting nectar flow patterns, abrupt shifts in EU-UK organic certification mutual recognition, and novel synthetic pesticide tolerance breakthroughs in beekeeping operations. Forecasts reflect documented assumptions about regulatory enforcement intensity and consumer clean-label preference stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Organic Fast Food Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
Global Natural and Organic Food Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
Organic Cocoa Market
Organic Food and Beverages
Germany Organic Food Market
Organic Food and Beverages
Spain Organic Food Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Organic Drinks Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Organic Acai Juice Market