
 Organic Food and Beverages Market | 2026-2036
Organic Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Food and Beverages Market Intelligence
The European Union's Green Deal, with its Farm to Fork strategy promoting organic farming, is restructuring supply chain requirements for food producers. Danone S.A. leverages its distribution network to launch organic dairy and plant-based products. Whole Foods Market anchors the premium retail segment with strict sourcing standards. Nestlé S.A. competes by integrating organic ingredients into its mainstream brands to reach a wider audience.
Organic food and beverages are products grown and processed without synthetic pesticides, fertilizers, or GMOs, verified through a certification process. Their primary purpose is to meet consumer demand for food produced with ecological balance and biodiversity conservation in mind. Within product types, organic fruits and vegetables command the largest share for home consumption. The organic beverages category is expanding rapidly, while certification like USDA Organic or EU Organic acts as a crucial market access tool.
The regulatory landscape is shaped by bodies like the USDA in the United States, the European Commission with its EU Organic logo, and Japan's MAFF through the JAS standard. These frameworks dictate production standards, labeling, and trade access, ensuring product authenticity. Producer success depends on navigating cross-border certification equivalencies and securing a consistent supply of certified ingredients.
Market Dynamics
A fundamental tension between constrained certified organic ingredient supply and escalating regulatory and consumer demand for transparency defines the market's structure. This friction creates significant price and access disparities between conventional and organic supply chains globally.
Growth Catalysts
- Policy Frameworks:The European Union's Farm to Fork strategy directly incentivizes the expansion of organic farming through subsidies and targets, creating a strong pull for producers to convert land and practices to meet new standards.
- Foodservice Sector Demand:Restaurant chains and institutional caterers are increasingly sourcing certified organic ingredients to meet menu transparency demands from consumers, particularly for produce, dairy, and grains.
- Developed Economy Consumption:Demand concentration within affluent consumer bases in countries like Germany and the United States provides a stable, high-value market for premium organic products, encouraging producer investment.
Market Restraints
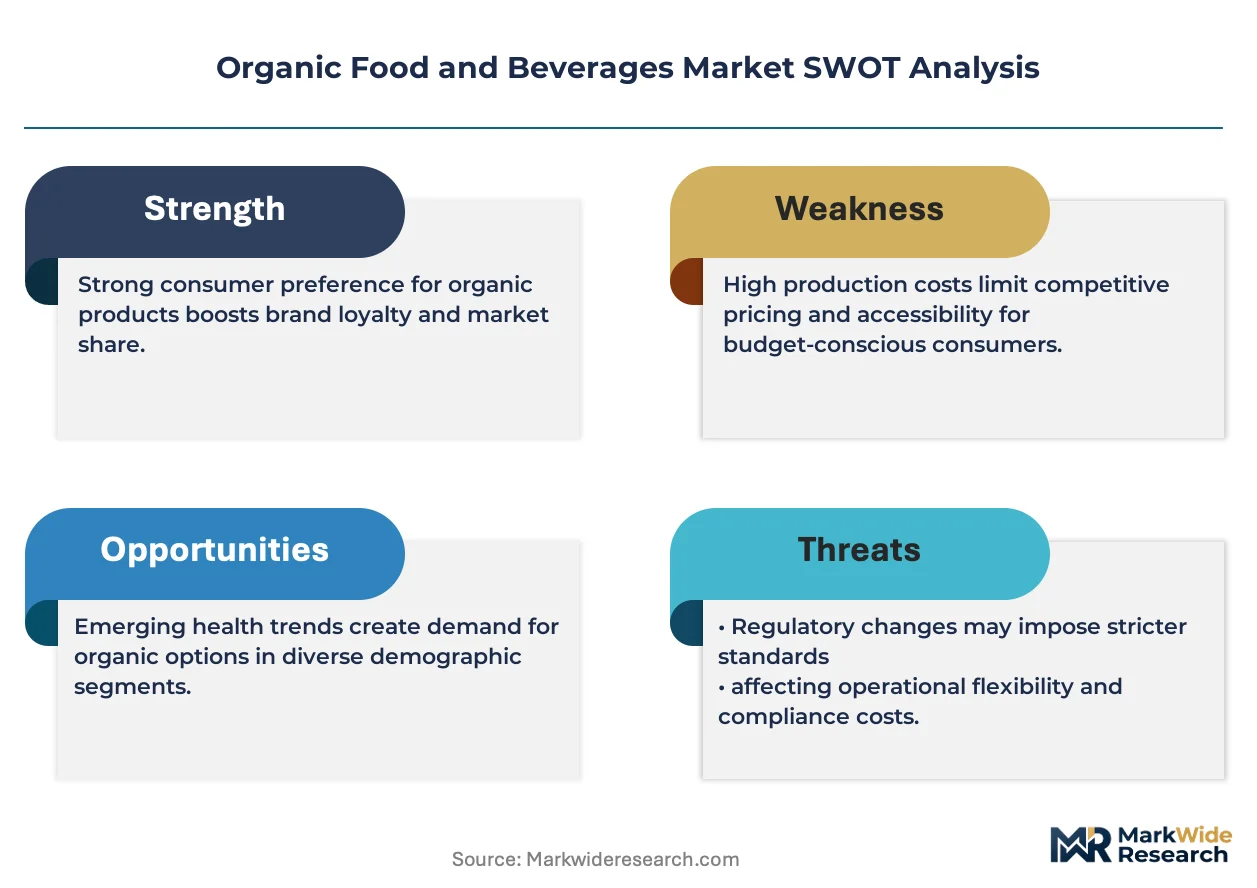
- Cost Structure Premiums:The high cost of certified organic animal feed and the multi-year transition period for converting conventional farmland to organic status create significant financial barriers for new entrants and existing farmers.
- Supply Chain Segregation:Maintaining separate storage, transportation, and processing facilities to prevent cross-contamination with non-organic products adds complexity and cost, particularly for smaller producers lacking scale.
- Certification Divergence:Navigating the differences and seeking equivalency between major regulatory frameworks, such as the USDA Organic standard and Japan's JAS standard, complicates international trade and market access.
Strategic Opportunities
- Geographic Expansion:There is significant white space for organic products in rapidly urbanizing Asian economies, where a growing middle class is developing a preference for certified and health-oriented foods.
- Specialized Nutrition Ingredients:Developing certified organic inputs for high-value categories like infant formula, clinical nutrition, and plant-based protein alternatives offers a path to higher margins and less commoditized market segments.
- Direct-to-Consumer Channels:The adoption of e-commerce platforms and subscription models allows organic farms and small brands to bypass traditional retail gatekeepers, build direct customer relationships, and capture more value.
Industry Challenges
- Compliance and Documentation Burden:Producers face an ongoing operational challenge in maintaining the extensive records required for annual audits and recertification under standards like the EU Organic logo, draining administrative resources.
- Ingredient Supply Volatility:Securing a consistent, year-round supply of specific organic raw materials, such as exotic fruits or specialty grains, remains a major hurdle that can lead to production delays and product shortages.
- Skilled Labor Scarcity:A shortage of farm managers and agricultural workers trained in the specific, often more labor-intensive, techniques of organic cultivation and pest management constrains production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Food and Beverages Market |
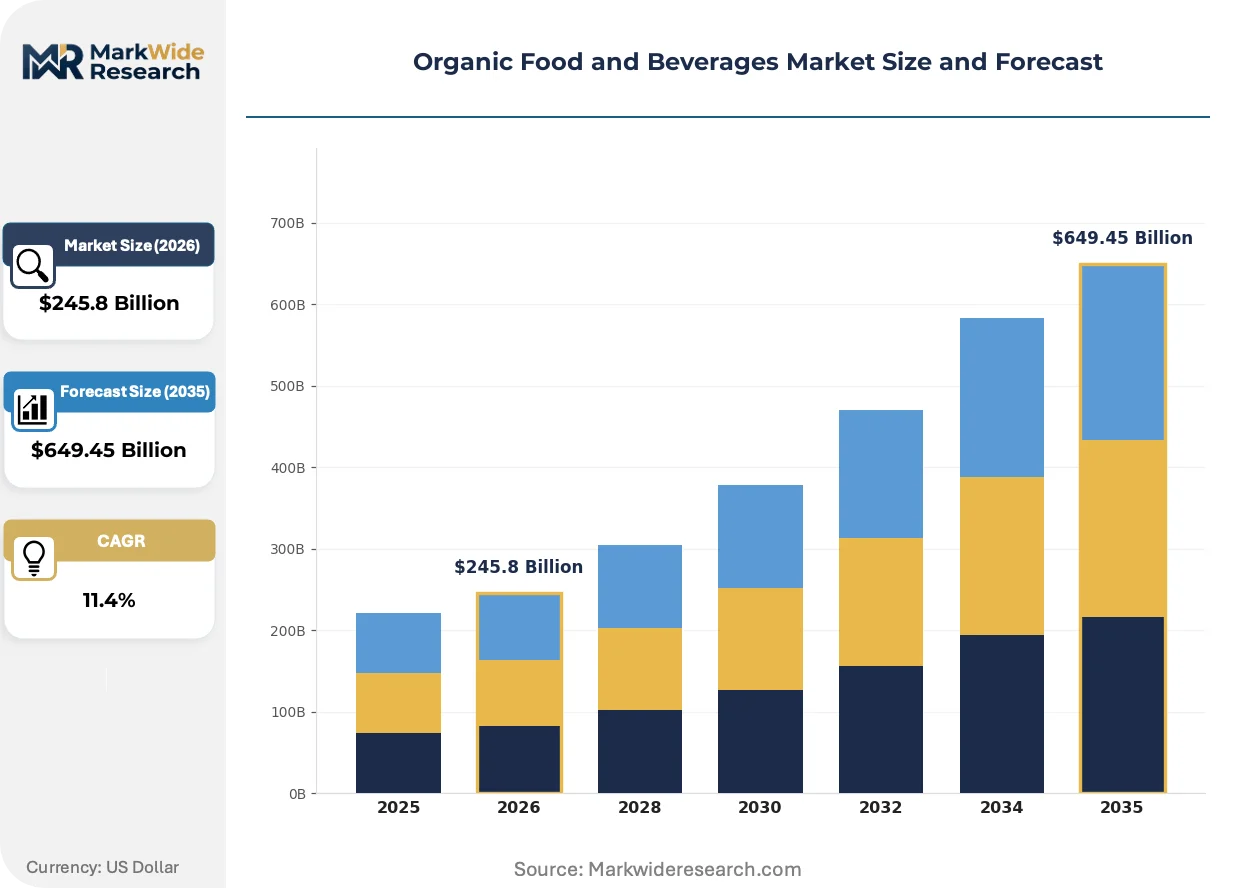
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $649.45 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Fruits, Organic Vegetables, Organic Dairy, Organic Snacks, Organic Beverages, Organic Grains Application: Home Consumption, Foodservice Providers, Specialty Stores, Online Retail, Health Clubs, Schools Certification: USDA Organic, EU Organic, JAS Organic, Soil Association, Ecocert, Pro-Cert Packaging Type: Glass Bottles, Biodegradable Containers, Paper Cartons, Recycled Plastic, Metal Cans, Compostable Wraps |
| Companies Covered | Danone S.A., Nestlé S.A., Hain Celestial Group, General Mills Inc., Whole Foods Market, Organic Valley, Amy's Kitchen, Inc., Conagra Brands, Inc., Dole Food Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Food and Beverages Market Strategic Shifts & Innovations
Technological advancements in supply chain verification and evolving consumer ethics are reshaping product development. The market is moving beyond a simple organic certification toward a more holistic definition of sustainable and transparent food production.
Traceability through Blockchain
Blockchain technology provides an immutable digital ledger for tracking food products from farm to shelf. Premium food manufacturers and retailers are adopting this system to verify the authenticity of organic claims. This innovation is consolidating consumer trust by offering transparent, unalterable proof of a product's origin, certification status, and handling, reducing fraud risk.
Regulatory Harmonization and Stringency
The European Union's Green Deal, particularly its Farm to Fork strategy, is a significant policy driver. It establishes ambitious targets for reducing pesticide use and increasing the percentage of agricultural land under organic cultivation. This policy directly impacts global food producers exporting to the EU, forcing alignment with stricter sustainability metrics to maintain market access.
Demand for "Organic-Plus" Attributes
Consumer expectations are shifting from a singular focus on the organic label to a broader set of ethical and environmental credentials. The premium retail channel is being disrupted as a USDA Organic seal becomes a baseline requirement, with differentiation now coming from attributes like regenerative agriculture, fair-trade certification, or hyper-local sourcing. This behavioral shift is most prominent in mature organic markets like the United States and Northern Europe.
Organic Food and Beverages Market Segmentation
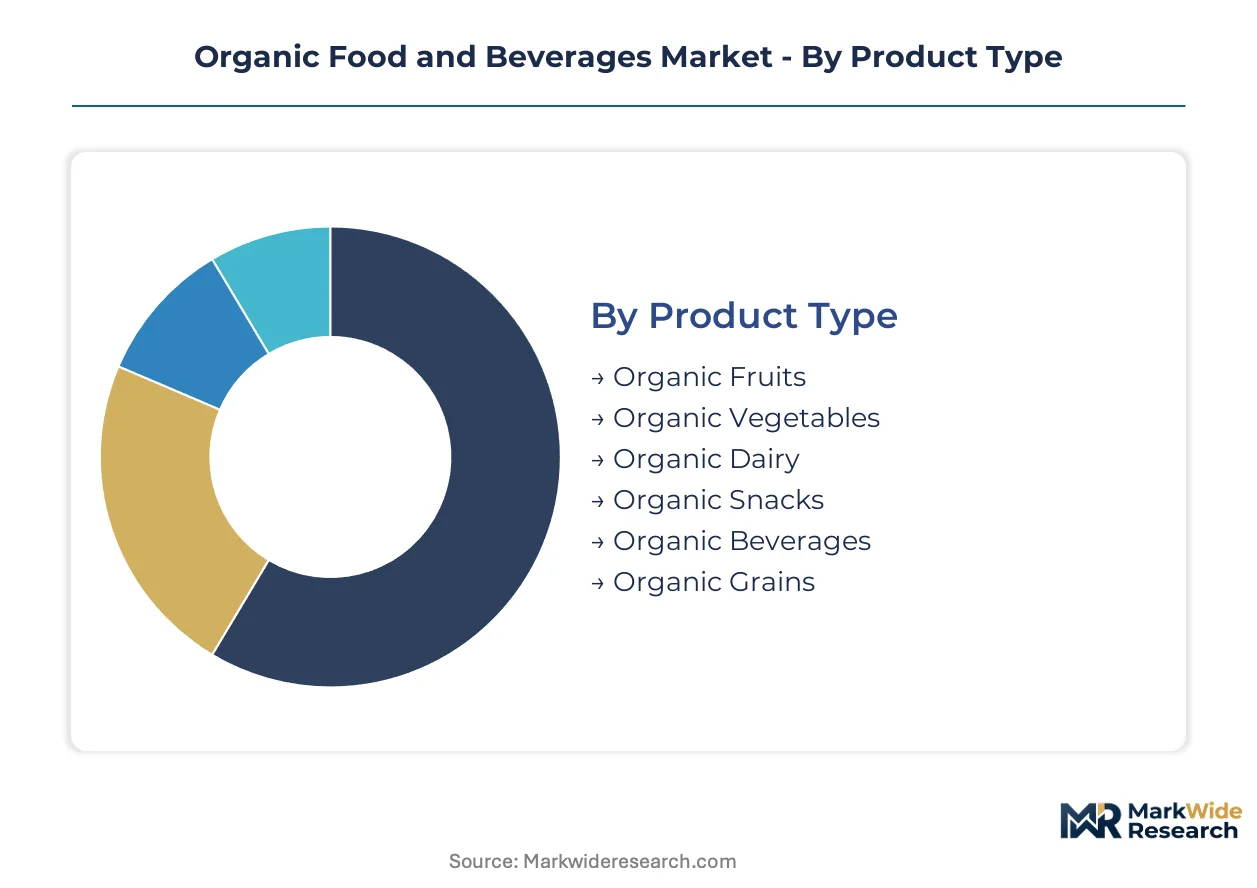
Market segmentation provides a granular view of demand drivers and supply dynamics within the organic food and beverages sector. This analysis dissects the market across product forms, end-use applications, regulatory certifications, and packaging innovations. Understanding these distinct categories informs strategic investment and market access priorities.
Product Type:
The product type axis delineates the core offerings available to consumers, reflecting diverse cultivation methods and processing requirements.
- Organic Fruits:These products are grown without synthetic pesticides or fertilizers, adhering to strict organic farming standards. Demand concentrates within developed economies, particularly in Germany, driven by consumer health consciousness and premium pricing.
- Organic Beverages:This category encompasses certified organic juices, milks, teas, and plant-based drinks processed from organic ingredients. The segment is expanding rapidly, with significant investment from companies like Danone S.A. leveraging existing distribution networks.
- Organic Vegetables:These include fresh and processed vegetables cultivated using ecological balance and biodiversity conservation principles.
- Organic Dairy:This segment covers milk, yogurt, and cheese from livestock raised on organic feed without hormones or antibiotics.
- Organic Snacks:This category features processed foods like chips, bars, and crackers made from certified organic components.
- Organic Grains:These are staple crops such as wheat, rice, and corn grown without genetically modified organisms or synthetic chemicals.
Mature deployment sits with Organic Fruits. Newer deployment is concentrated in Organic Beverages.
Application:
Volume distribution across various end-use applications defines consumption patterns and market accessibility.
- Home Consumption:This segment represents direct purchases by individual consumers for in-home preparation and eating. This application commands the largest market share, particularly for organic fruits and vegetables, driven by household health and wellness priorities.
- Foodservice Providers:This segment includes restaurants, cafes, and institutional caterers sourcing certified organic ingredients for menu offerings. Demand from this sector is a significant contributor, particularly for produce and dairy, to meet menu transparency demands.
- Specialty Stores:These retail outlets, like Whole Foods Market, focus on premium, often organic, products with strict sourcing standards.
- Online Retail:E-commerce platforms and subscription models allow direct sales of organic products, bypassing traditional retail channels.
- Health Clubs:These facilities increasingly offer organic food and beverage options to members, aligning with wellness lifestyles.
- Schools:Educational institutions integrate organic items into meal programs, often supported by local food initiatives.
The largest segment remains Home Consumption, while Online Retail demonstrates the steepest expansion trajectory.
Certification:
Supply concentration around specific regulatory frameworks dictates market access and consumer trust.
- USDA Organic:This certification verifies products meet U.S. Department of Agriculture standards for organic production, processing, and handling. It acts as a crucial market access tool within the United States, ensuring product authenticity for consumers.
- EU Organic:This standard, governed by the European Commission, signifies compliance with the European Union's stringent organic farming regulations. The EU Green Deal's Farm to Fork strategy directly incentivizes expansion of this certified land.
- JAS Organic:Japan's Ministry of Agriculture, Forestry and Fisheries (MAFF) provides this standard, dictating production and labeling for organic goods in Japan.
- Soil Association:This UK-based certification body sets high standards for organic food and farming, often exceeding national requirements.
- Ecocert:An international certification body, Ecocert inspects organic products across various categories globally, particularly in Europe.
- Pro-Cert:This Canadian certification body ensures organic integrity for products marketed within Canada and for international trade.
Regulatory compliance for EU Organic defines market access, with Ecocert gaining influence.
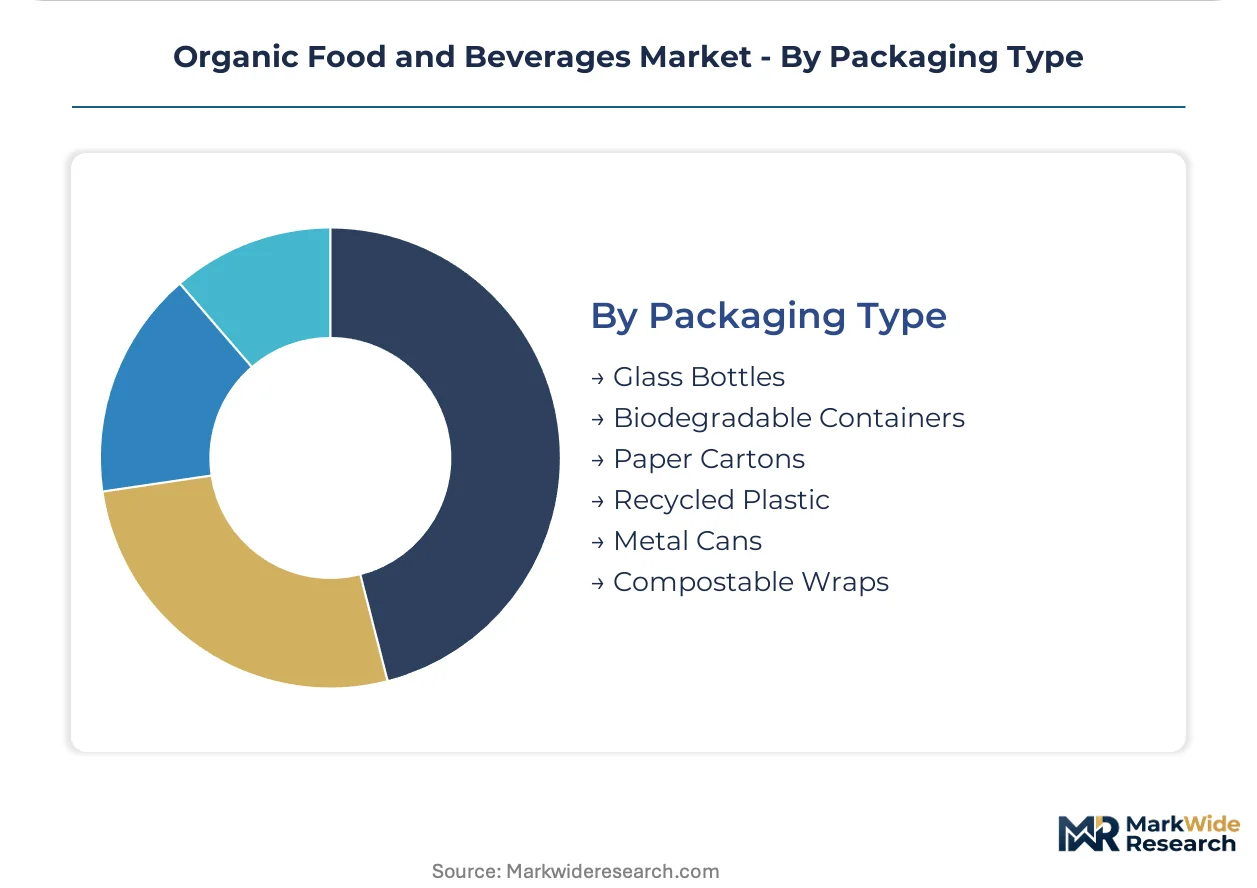
Packaging Type:
Maturity levels within packaging technologies influence both sustainability goals and product preservation.
- Glass Bottles:These traditional containers offer excellent product preservation and are widely recyclable, often associated with premium organic beverages. Their inert nature prevents chemical leaching, maintaining product purity.
- Biodegradable Containers:These innovative packaging solutions decompose naturally, reducing environmental impact compared to conventional plastics. Demand is rising from environmentally conscious consumers seeking sustainable alternatives across various product types.
- Paper Cartons:These lightweight, often recyclable, containers are common for organic dairy and plant-based milk alternatives.
- Recycled Plastic:Packaging made from post-consumer recycled content supports circular economy principles for organic products.
- Metal Cans:These provide robust protection and infinite recyclability, used for organic beverages and some processed foods.
- Compostable Wraps:These films break down into natural elements, offering sustainable options for fresh organic produce and snacks.
Traditional packaging forms like Glass Bottles maintain market share, as sustainable options such as Compostable Wraps drive innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A fundamental divide exists between regions with high organic food consumption and those with emerging production capabilities. Developed economies like Germany and the United States drive demand, while policy frameworks in the European Union aim to expand organic farming. This creates distinct market dynamics across various geographies.
Germany
Germany's affluent consumer base drives substantial demand for premium organic products. The European Commission's EU Organic logo ensures product authenticity and consumer trust in the German market. Munich and Berlin serve as key consumption hubs, demonstrating strong retail penetration for certified organic offerings.
United States
American consumers prioritize health and wellness, fueling consistent demand for organic fruits and vegetables. The USDA Organic standard governs production and labeling, providing a crucial market access tool for producers. California's central valley represents a significant organic farming cluster, supplying diverse organic produce nationwide.
China
Expanding middle-class populations in China are developing a preference for certified and health-oriented foods. The country's national food safety regulations are evolving to incorporate more stringent organic standards. Shanghai and Beijing metropolitan areas show increasing demand for imported organic goods, reflecting shifting dietary patterns.
France
French policy, influenced by the EU Green Deal's Farm to Fork strategy, actively incentivizes organic farming expansion. This framework supports producers in converting conventional land to organic status. The Loire Valley region, with its rich agricultural heritage, is witnessing significant growth in organic vineyard and vegetable cultivation.
Brazil
Brazil exhibits strong potential for organic agricultural expansion, driven by growing domestic and export demand. The Ministry of Agriculture, Livestock and Food Supply (MAPA) oversees organic certification, ensuring product integrity. The southern states, particularly Paraná and Rio Grande do Sul, are emerging as significant organic grain and fruit production centers.
Organic Food and Beverages Market Key Industry Players
The competitive structure tilts toward a tiered system, with established food conglomerates operating alongside specialized organic brands. This market features a mix of multinational players and niche producers focused on specific product categories. Strategic archetypes include diversified mainstream brands, premium organic specialists, and emerging plant-based innovators. Companies frequently engage in portfolio diversification and strategic partnerships to expand market reach.
On the scale-driven end, Danone S.A. and Nestlé S.A., both multinational food and beverage corporations, exemplify the strategy of integrating organic ingredients into mainstream product lines. These entities leverage extensive distribution networks to reach a broad consumer base, often through portfolio diversification. Whole Foods Market, a prominent retailer known for its strict sourcing standards, anchors the premium segment, catering to discerning consumers seeking certified organic and natural products. Other specialized organic brands, such as Hain Celestial Group, occupy a position focused on developing dedicated organic product portfolios across multiple categories.
| Leading Market Players |
|---|
| Danone S.A. |
| Nestlé S.A. |
| Hain Celestial Group |
| General Mills Inc. |
| Whole Foods Market |
| Organic Valley |
| Amy's Kitchen, Inc. |
| Conagra Brands, Inc. |
| Dole Food Company, Inc. |
| Others |
Cost & Logistics Intelligence
The European Union's Farm to Fork strategy gates access to certified organic supply and influences premium pricing for compliant products. This framework drives market value for ecologically balanced production.
Pricing Analysis
Consumer demand for ecological balance and biodiversity conservation anchors organic food and beverage pricing. Pricing reflects value-based models, driven by EU Organic certification and established brand premiums from players like Whole Foods Market. High cost structure premiums for organic animal feed and multi-year land conversion create upward pricing pressure. Foodservice providers exhibit higher price sensitivity compared to affluent consumers in developed economies.
Supply Chain Analysis
Skilled labor scarcity for organic cultivation techniques in regions like California and the Loire Valley impacts supply availability. The organic food supply chain sources heavily from organic fruits, vegetables, and grains. Ingredient supply volatility remains a significant structural risk, particularly for specialty items. Distribution primarily serves home consumption, with online retail channels demonstrating rapid expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic food and beverages market is a vertical-integration race, with players actively pursuing upstream control over certified organic ingredient supply. This strategy mitigates volatility and ensures product authenticity.
For Market Incumbents: Lock in long-term supply contracts for certified organic ingredients to counter ingredient supply volatility. Diversify existing product portfolios with new organic offerings, leveraging established distribution networks to reach a broader consumer base. This approach protects against margin pressure from rising input costs and strengthens market position. For New Entrants and Emerging Players: The premium pricing of certified organic products creates a significant price-point gap for value-oriented offerings. Target rapidly urbanizing Asian economies with health-oriented foods or specialized nutrition ingredients like organic plant-based proteins. Online retail platforms offer a highly penetrable segment, allowing direct-to-consumer sales and stronger brand narratives. For Investors and Strategic Acquirers: Regulatory harmonization and stringency is the leading indicator that certified organic products will sustain long-term viability over the coming decade. Prioritize acquisition targets that are mid-sized specialized organic brands with robust, localized supply chains. Watch for the expansion of EU Organic equivalency agreements as a key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Expand Certified Organic Farmland | This initiative increases the availability of raw materials, addressing supply constraints for organic food producers. |
| Implement Blockchain Traceability | Blockchain technology enhances consumer trust by verifying organic claims and product authenticity from farm to shelf. |
| Target Asian E-commerce Channels | This move captures demand from rapidly urbanizing middle-class populations in emerging markets like China. |
| Develop "Organic-Plus" Product Lines | Differentiation beyond basic organic certification meets evolving consumer ethics in mature markets like Northern Europe. |
| Secure Long-Term Foodservice Contracts | These agreements provide stable demand channels for organic produce and dairy from institutional caterers. |
Research Approach
Independent corroboration across USDA Organic reports, EU Commission agricultural statistics, and trade association publications underwrites the qualitative findings of this study. Primary interviews with organic farmers, food processors, retail buyers, and certification body representatives provided critical insights. This approach combined with extensive secondary validation ensures robust bottom-up and top-down triangulation.
Rate-of-change decomposition analyzed market dynamics across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, certification, packaging type, and regional policy frameworks. Compound annual growth rates were derived from historical data and projected shifts in consumer demand. Organic land conversion rates served as a key forecast input.
Inputs from regulatory body reports and industry association data were available through the study window; gaps in real-time organic ingredient pricing introduce uncertainty bands. Forecasts reflect assumptions on policy stability and consumer preference evolution. Material deviation in regulatory frameworks or supply chain stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Spain Organic Food Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
Organic Acai Juice Market
Organic Food and Beverages
Australia Organic Beverages Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
Global Organic Packaged Food Market
Organic Food and Beverages
Canada Organic Food Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Organic Cocoa Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Australia Organic Food Market