
 Organic Rice Syrup Market | 2026-2036
Organic Rice Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Rice Syrup Market Outlook
Asset-light contract manufacturing and toll-processing arrangements is narrowing the capital barrier for mid-tier entrants in organic rice syrup production. California Natural Products leverages its West Coast processing infrastructure to sustain organic certification across multi-step refining. Cargill Incorporated anchors global grain procurement networks that compete on input cost stability for brown rice feedstock. Axiom Foods Inc. differentiates through specialized protein and starch fractionation expertise that extends into co-product syrup recovery.
Organic rice syrup is a saccharified liquid sweetener produced by enzymatic hydrolysis of organic rice starch, typically yielding dextrose equivalents between 20 and 70 depending on the desired viscosity and sweetness profile. The syrup functions primarily as a clean-label bulking agent, humectant, and browning agent in baked goods, beverages, and infant nutrition formulations where corn syrup or refined sugar replacements are sought. Light Rice Syrup dominates commercial volumes due to its neutral color and flavor compatibility across dairy and beverage applications, while Brown Rice Syrup occupies premium positioning in personal care and specialty health food channels where darker caramel notes signal minimal processing. Bulk Containers lead packaging type demand from industrial food manufacturers, though Pouches are gaining fastest in direct-to-consumer channels through health food stores and online retail platforms.
USDA Organic certification governs feedstock integrity and processing inputs for US-bound product, while the EU Organic Regulation mandates full traceability from paddy to syrup for European market access. China's SAMR enforces GB standards for imported sweetener labeling and residue limits that shape exporter compliance costs. Stakeholders must monitor evolving infant nutrition safety thresholds from FDA and EMA, as rice-based ingredients face heightened scrutiny for inorganic arsenic content that could restrict formulation eligibility.
Market Dynamics
Clean-label carbohydrate substitution in infant nutrition and processed foods is compressing demand cycles for organic rice syrup, while EU organic certification requirements and F-Gas Regulation compliance costs are restructuring refiner economics across Western Europe.
Growth Catalysts
- EU Organic Regulation traceability mandates:Full-chain certification from paddy to syrup creates shelf-space advantages for compliant refiners in German and Dutch retail channels.
- Enzymatic hydrolysis optimization:Advanced saccharification control enables precise dextrose equivalent targeting for dairy and beverage formulators seeking viscosity-specific bulking agents.
- Western Europe demand concentration:Infant formula manufacturers in Germany and the Netherlands are expanding procurement volumes for clean-label carbohydrate sourcing.
Market Restraints
- Brown rice feedstock cost volatility:Organic paddy premiums fluctuate with climate-driven yield variations in major growing basins.
- Inorganic arsenic safety thresholds:FDA and EMA scrutiny of rice-based ingredients restricts formulation eligibility in infant nutrition segments.
- Energy-intensive refining:F-Gas Regulation disclosure requirements elevate compliance burdens for syrup processors dependent on conventional refrigeration cycles.
Strategic Opportunities
- Direct-to-consumer pouch packaging:Health food stores and online retail platforms are capturing margin previously held by bulk industrial channels.
- Personal care caramel notes positioning:Brown rice syrup variants command premium placement in specialty cosmetic and wellness applications.
- EU Green Deal processing incentives:Renewable energy transitions in syrup refining qualify for carbon-reduction credits in member-state industrial programs.
Industry Challenges
- Multi-step organic certification maintenance:USDA Organic and EU Organic Regulation audits require continuous documentation across enzymatic hydrolysis, filtration, and concentration stages.
- Co-product syrup recovery integration:Protein and starch fractionation expertise must align with syrup extraction economics to sustain margin in integrated processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Rice Syrup Market |
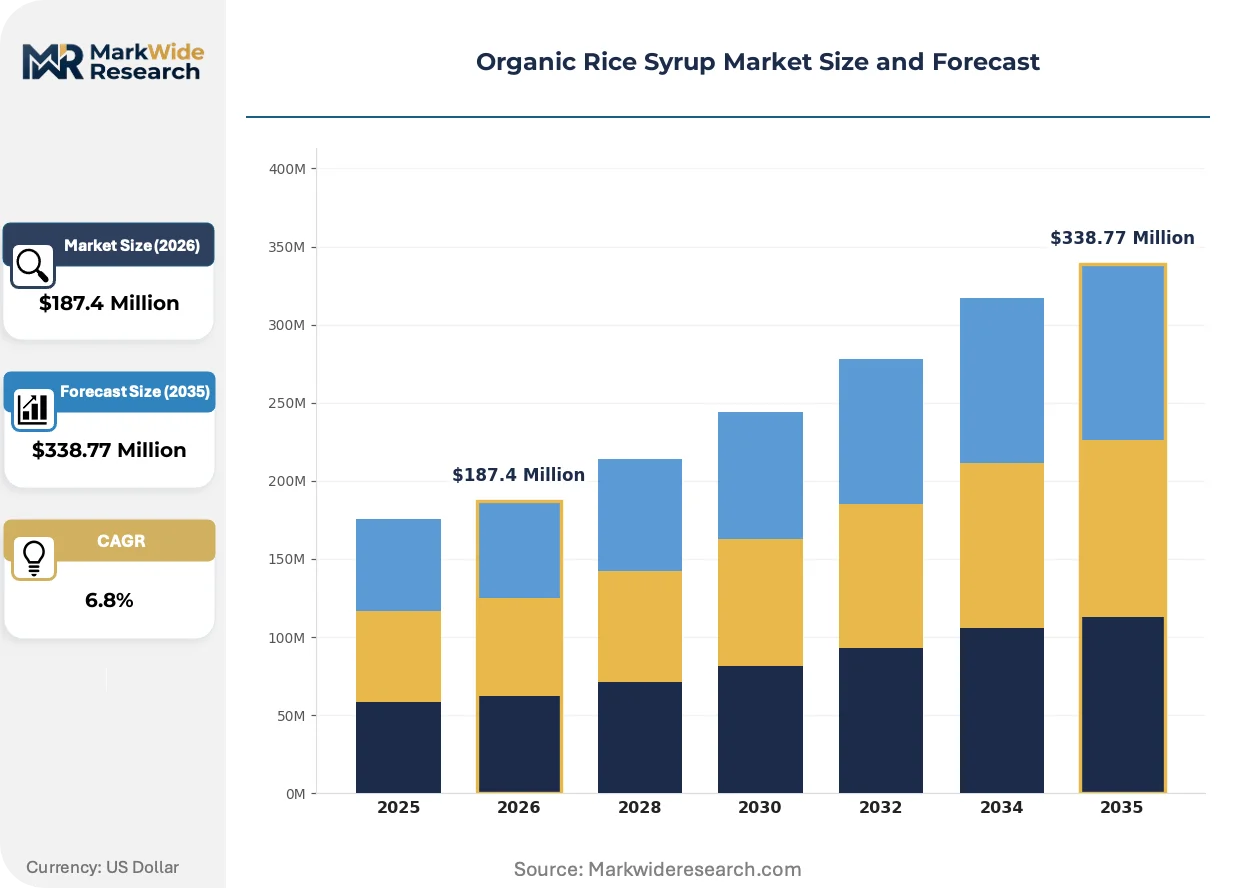
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Rice Syrup, Dark Rice Syrup, Brown Rice Syrup, Organic Rice Malt End User: Food & Beverage, Bakery, Dairy Products, Personal Care Packaging Type: Bottles, Tetra Packs, Bulk Containers, Pouches Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Axiom Foods Inc., California Natural Products, Cargill Incorporated, Archer Daniels Midland Company (ADM), Wuhu Deli Foods Co. Ltd., Suzanne’s Specialties, Nature’s One Inc., ABF Ingredients, Wuhu Haoyikuai Food Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Rice Syrup Market Strategic Shifts
Processing technology convergence and regulatory disclosure requirements are compressing traditional batch-refining timelines while opening differentiation pathways through energy transparency and co-product valorization.
Continuous enzymatic membrane filtration is collapsing residence times in saccharification tanks from hours to minutes. Beverage manufacturers in North America are piloting these systems for just-in-time syrup specification. The technology is collapsing capital intensity barriers for mid-tier entrants previously excluded by batch infrastructure requirements.
EU F-Gas Regulation phase-down schedules are forcing refrigerant transitions in syrup concentration and drying operations. Industrial gas suppliers are retrofitting ammonia and CO2 cascade systems for organic-certified refiners. German and Dutch processors face the steepest retrofit timelines given their concentration of infant formula supply contracts.
Certificate-of-analysis transparency is displacing traditional supplier qualification in infant nutrition procurement. Formulators now demand batch-level arsenic, heavy metal, and allergen documentation before contract execution. This shift is most pronounced in EU and North American dairy applications where clean-label claims require defensible chain-of-custody records.
Organic Rice Syrup Market Segmentation
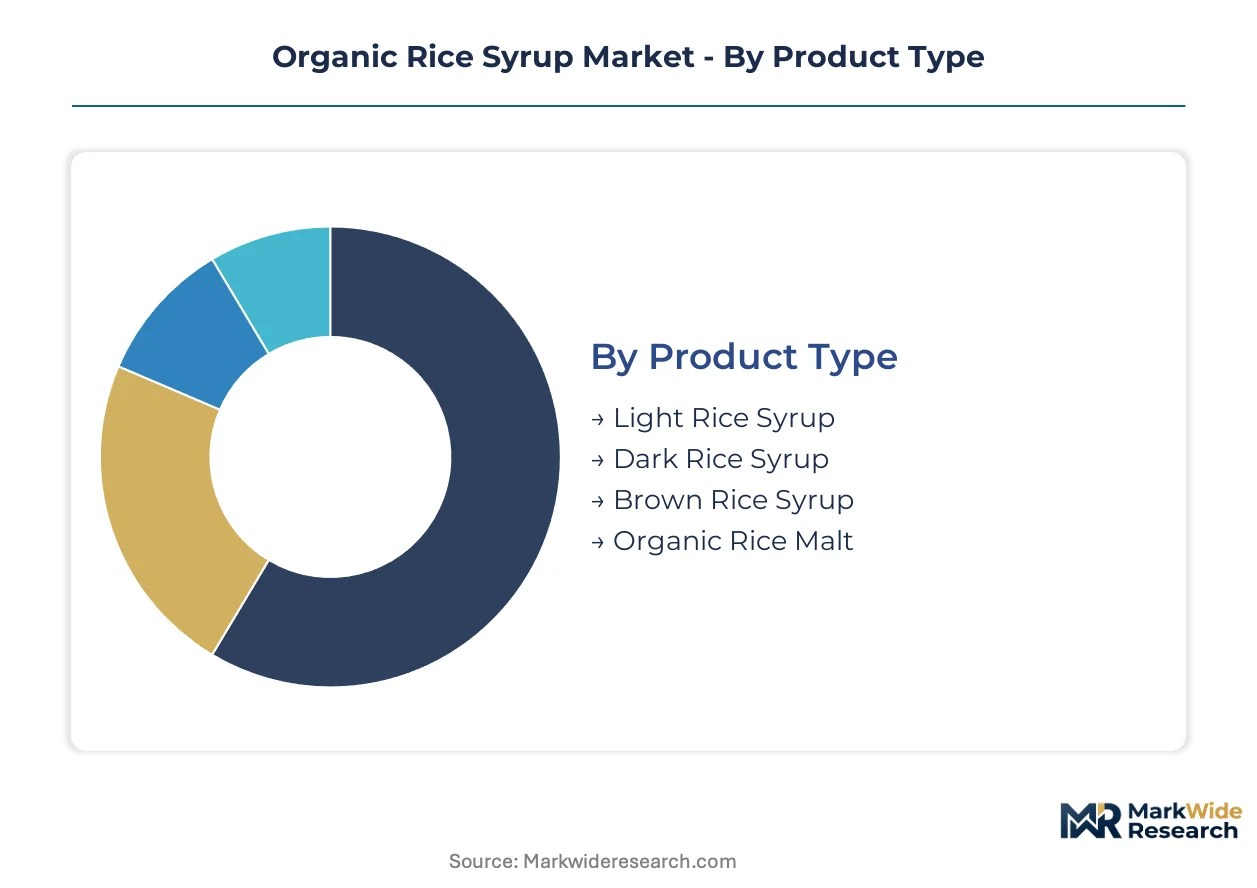
Segmentation in organic rice syrup reveals how enzymatic hydrolysis specifications, end-use formulation requirements, and channel economics partition value capture across the supply chain. Refiners configure dextrose equivalent profiles and certification tiers to match distinct buyer technical and margin expectations.
Product Type:
Light Rice Syrup turns inventory fastest through beverage and dairy bulk contracts, while Brown Rice Syrup and Organic Rice Malt move slower through premium health food and personal care channels with longer qualification cycles.
- Light Rice Syrup:Neutral color and flavor profile from controlled saccharification yields dextrose equivalents of 40-60, suplicating viscosity control in dairy alternatives and sports drinks. German infant formula manufacturers specify this grade for clean-label carbohydrate fortification where corn syrup exclusion is mandatory.
- Brown Rice Syrup:Minimal filtration preserves caramel color and nutty flavor notes from retained rice proteins and minerals. Dutch and German personal care formulators pay premiums for this grade in natural cosmetics where processing narrative supports shelf positioning.
- Dark Rice Syrup:Extended Maillard reaction during concentration produces robust molasses-like flavor for craft brewing and specialty baking applications.
- Organic Rice Malt:Lower dextrose equivalent (20-35) from partial saccharification supplies traditional Asian confectionery and fermentation feedstocks.
Light Rice Syrup dominates installed base. Brown Rice Syrup is where expansion concentrates.
End User:
Cost tier stratification separates commodity carbohydrate substitution in mass-market food manufacturing from premium positioning in clean-label personal care and specialty infant nutrition.
- Food & Beverage:Mass-volume absorption of standard dextrose equivalent syrups for sugar reduction and clean-label reformulation in conventional processed foods.
- Bakery:Humectancy and browning control in artisan and industrial bread, cookie, and granola applications where organic certification supports retail placement.
- Dairy Products:Viscosity-specific bulking in organic yogurt, ice cream, and plant-based alternatives commands technical qualification cycles of 12-18 months with major processors.
- Personal Care:Brown syrup variants with caramel notes and minimal-processing claims supply natural skincare and haircare formulations in Dutch and German wellness retail channels.
Dairy Products commands highest technical barriers. Personal Care delivers steepest margin expansion.
Packaging Type:
Volume scale and customer proximity determine packaging economics, with industrial bulk dominating throughput and direct-to-consumer pouches capturing margin recovery from channel disintermediation.
- Bulk Containers:Tote and drum shipments of 275-330 gallons supply North American and European food manufacturers with just-in-time syrup delivery against production schedules.
- Pouches:Stand-up flexible packaging with reseal features targets health-conscious households through online retail and specialty store channels.
- Bottles:Glass and PET formats serve small-batch food service and ingredient retail where visual inspection supports quality signaling.
- Tetra Packs:Aseptic cartons extend ambient shelf stability for export shipments and emergency stockholding by industrial buyers.
Bulk Containers dominate throughput volume. Pouches are climbing the fastest through channel shift.
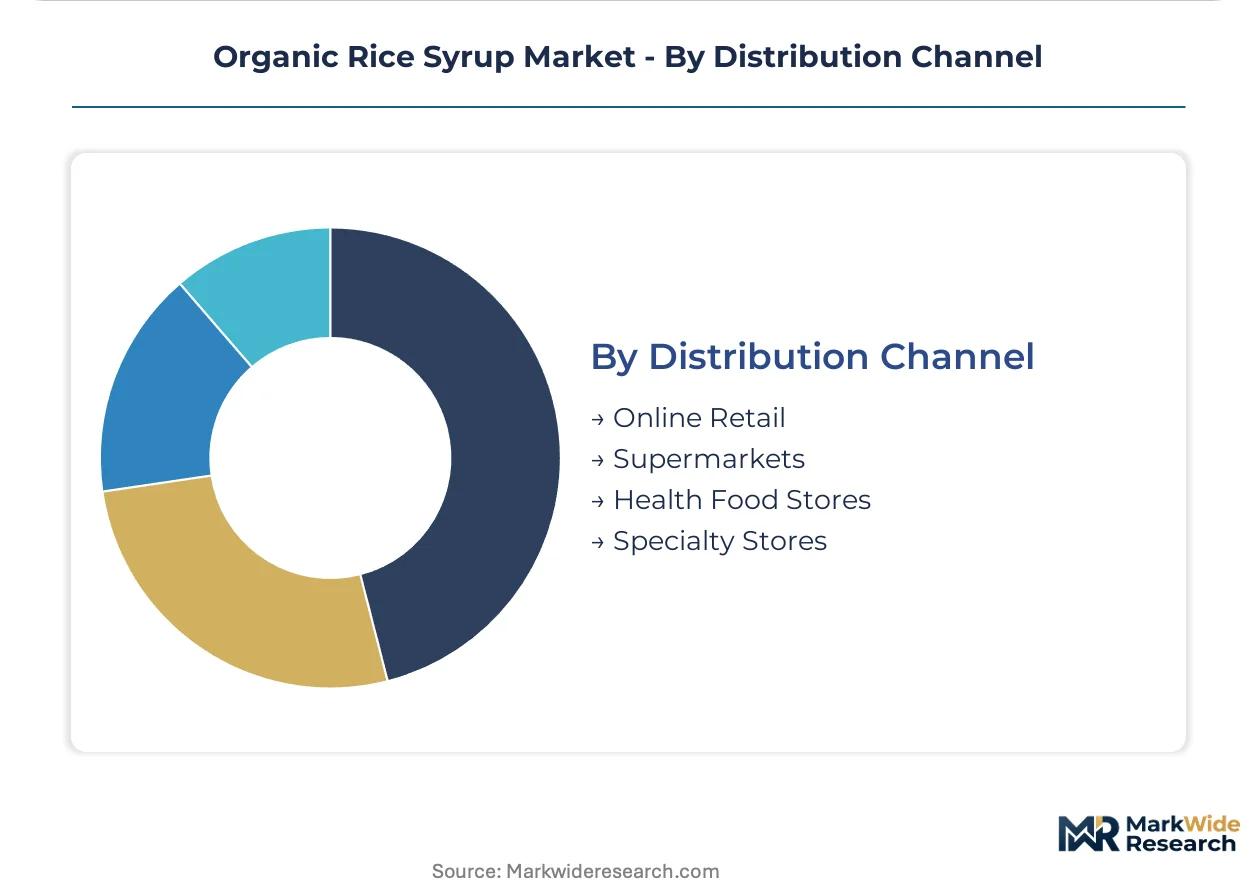
Distribution Channel:
Customer type and purchase frequency separate automated replenishment systems for industrial accounts from high-touch education requirements in emerging direct-to-consumer segments.
- Online Retail:Amazon, Thrive Market, and direct brand sites aggregate long-tail demand from home bakers, specialty food producers, and wellness consumers seeking certificate-of-analysis transparency.
- Health Food Stores:Staff-assisted selling in Sprouts, Whole Foods, and independent co-ops supports premium Brown Rice Syrup placement with narrative-driven merchandising.
- Supermarkets:Conventional grocery placement of Light Rice Syrup in baking aisles competes on shelf price against conventional corn syrup alternatives.
- Specialty Stores:Ethnic grocers and professional ingredient suppliers serve traditional Asian confectionery manufacturers and craft brewers seeking specific dextrose equivalent ranges.
Health Food Stores anchor premium positioning. Online Retail is gaining share fastest through demographic shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German infant formula manufacturers anchor procurement volumes for clean-label carbohydrate sourcing, while Dutch personal care formulators drive premium positioning for minimally processed variants. Channel concentration in Western Europe compresses qualification cycles for certified refiners.
Germany
Infant nutrition manufacturers in North Rhine-Westphalia and Bavaria specify Light Rice Syrup for corn syrup exclusion mandates in organic formulations. The EU Organic Regulation and F-Gas Regulation enforce full-chain traceability and refrigerant disclosure from paddy to syrup. Cologne-based processors face accelerated retrofit timelines for ammonia cascade cooling systems to maintain supply contracts with Dutch dairy formulators.
Netherlands
Personal care brands in Amsterdam and Utrecht command premium placement for Brown Rice Syrup variants with caramel notes in natural cosmetics. EFSA scrutiny of rice-based ingredients shapes formulation eligibility thresholds for skincare applications. Rotterdam port infrastructure facilitates bulk container imports from Asian refiners seeking EU Organic certification compliance.
United States
West Coast beverage manufacturers pilot continuous enzymatic membrane filtration for just-in-time syrup specification in dairy alternatives. USDA Organic certification governs feedstock integrity for domestic-bound product. California processors leverage existing organic certification infrastructure across multi-step refining to supply North American health food store channels.
China
Traditional Asian confectionery manufacturers in Jiangsu and Zhejiang provinces absorb lower dextrose equivalent grades for fermentation feedstocks. SAMR enforces GB standards for imported sweetener labeling and residue limits that elevate exporter compliance costs. Yangtze River Delta refiners balance domestic organic paddy premiums against export certification requirements for European infant nutrition contracts.
Organic Rice Syrup Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct capability tiers. Bulk industrial procurement gravitates toward refiners with sustained organic certification across enzymatic hydrolysis and concentration stages. Mid-tier entrants exploit toll-processing arrangements to narrow capital barriers. Dominant competitive moves include backward integration into brown rice feedstock procurement and technology licensing for continuous membrane filtration systems.
Within the integrated processing tier, California Natural Products exemplifies West Coast infrastructure leverage for multi-step organic certification maintenance. Cargill Incorporated anchors global grain procurement networks that compete on input cost stability. Axiom Foods Inc. occupies a specialist position extending protein and starch fractionation expertise into co-product syrup recovery economics.
| Leading Market Players |
|---|
| Axiom Foods Inc. |
| California Natural Products |
| Cargill Incorporated |
| Archer Daniels Midland Company (ADM) |
| Wuhu Deli Foods Co. Ltd. |
| Suzanne's Specialties |
| Nature's One Inc. |
| ABF Ingredients |
| Wuhu Haoyikuai Food Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in EU-certified refining infrastructure is concentrating pricing power among German and Dutch processors holding infant formula supply contracts, while idle capacity in Asian brown rice processing feeds cost-competitive spot pricing for non-certified grades.
Pricing Analysis
Certification level creates the primary spread between USDA Organic and EU Organic Regulation tiers, with the latter commanding premiums for full-chain traceability from paddy to syrup. Contract-based long-term offtake dominates procurement from infant formula manufacturers, while spot transactions serve craft brewers and specialty bakers. Price differentiation rests on dextrose equivalent precision and batch-level arsenic documentation. Cost compression in standard-grade Light Rice Syrup is intensifying because toll-processing entrants are narrowing capital barriers. Mass-market food manufacturers exhibit highest price sensitivity; Dutch personal care formulators show least.
Supply Chain Analysis
Brown rice feedstock draws from organic paddy basins in China, Thailand, and India, with climate-driven yield variations injecting volatility into input costs. Enzymatic hydrolysis enzymes, filtration membranes, and refrigerants for concentration stages constitute critical component dependencies. Single-source vulnerability concentrates in EU-certified refining capacity, where German and Dutch processors control qualification pathways for infant nutrition. Distribution runs through bulk container shipments to industrial food manufacturers, with pouch formats gaining share in direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: EU Organic Regulation compliance creates switching costs that lock infant formula manufacturers into qualified supplier relationships.
For Market Incumbents: Insulate margin position by deepening backward integration into organic brown rice procurement in Thai and Indian growing basins. Accelerate ammonia cascade cooling retrofits ahead of F-Gas Regulation phase-down deadlines to defend German and Dutch supply contracts against emerging Spanish and Italian refiners.
For New Entrants and Emerging Players: Pursue white-space opportunity in direct-to-consumer pouch packaging for North American health food channels, where certificate-of-analysis transparency is displacing traditional supplier qualification. Target online retail platforms with stand-up flexible formats featuring reseal features and batch-level arsenic disclosure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among EU-certified refiners with multi-year infant formula supply agreements. Long-term viability favors processors with integrated protein and starch fractionation capabilities that valorize co-product streams. Monitor EFSA inorganic arsenic threshold revisions as the critical inflection signal for formulation eligibility restrictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Paddy Procurement | Captive supply of Thai and Indian brown rice insulates margin from climate-driven yield volatility. |
| Ammonia Cascade Cooling Retrofit | F-Gas Regulation compliance preserves German and Dutch infant formula supply contract eligibility. |
| Continuous Enzymatic Membrane Filtration Licensing | Technology transfer narrows capital barriers for mid-tier entrants seeking just-in-time specification capability. |
| Direct-to-Consumer Pouch Launch | Channel disintermediation captures margin recovery from health food store and online retail platforms. |
| Certificate-of-Analysis Transparency Platform | Batch-level arsenic documentation meets infant nutrition procurement requirements from EMA-scrutinized formulators. |
Study Parameters
Desk research of EU Organic Regulation compliance databases, FDA infant nutrition guidance documents, and F-Gas refrigerant phase-down schedules preceded structured interviews with syrup refinery plant managers, infant formula procurement leads, and enzymatic hydrolysis technology suppliers. Secondary validation drew from customs trade data for organic sweetener flows, SEC filings of integrated grain processors, and EFSA scientific opinions on rice-based ingredient safety. Bottom-up capacity estimates across certified refining facilities were triangulated against top-down demand projections from organic food manufacturer associations.
Assumptions held fixed include EU Organic Regulation traceability mandates and F-Gas refrigerant disclosure requirements throughout the projection horizon; variables tested included organic paddy yield scenarios and infant nutrition safety threshold revisions. Segmentation dimensions modeled encompass product type by dextrose equivalent range, end-use application by formulation technical barrier, packaging format by channel economics, and regional regulatory cluster by certification tier. CAGRs were derived from slope analysis of segment-specific adoption curves calibrated against historical organic sweetener substitution patterns.
Macroeconomic conditions sit as an overlay; deviation in organic commodity price indices or energy cost trajectories would shift the trajectory of refiner margin sustainability. Forecasts reflect assumptions about regulatory stability and certification audit continuity. Quarterly review of EFSA scientific committee outputs and FDA infant formula guidance updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Non-GMO Food Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
Organic Fruit Powder Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
Australia Organic Food Market
Organic Food and Beverages
Italy Organic Food Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
South Korea Organic Food Market