
 Global Organic Dried Fruit Market | 2026-2036
Global Organic Dried Fruit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Dried Fruit Market Outlook
Multi-source procurement from certified organic orchards is realigning supply security for processors. Sun-Maid Growers of California leverages its cooperative structure to sustain year-round raisin availability across North American channels. Graceland Fruit Inc. specializes in infused and dried cherry technologies that differentiate its ingredient portfolio. Ocean Spray Cranberries Inc. dominates the organic dried cranberry segment through controlled cooperative sourcing from Massachusetts and Wisconsin growers.
Organic dried fruit consists of fresh fruit dehydrated through controlled thermal or solar processes to moisture levels typically below 20 percent, preserving shelf stability without synthetic preservatives for commercial food applications and direct consumption. The USDA National Organic Program and EU Organic Regulation mandate zero synthetic pesticide residues, governing every stage from orchard certification through final packaging. Raisins and dates anchor volume throughput due to established Mediterranean and Californian supply bases, while powdered forms capture expanding traction among bakery and nutraceutical manufacturers seeking clean-label ingredient integration. Whole and sliced formats retain retail consumer preference, though food manufacturers increasingly specify chopped and powdered variants for production-line efficiency.
The USDA National Organic Program, EU Organic Regulation, and California Department of Food and Agriculture collectively enforce traceability standards that determine market access for international suppliers. Compliance costs filter smaller orchards from export eligibility, concentrating certified supply among vertically integrated cooperatives and large-scale farming operations. Stakeholders must monitor evolving maximum residue limits and bilateral organic equivalency agreements that periodically reshape competitive supplier lists across destination markets.
Market Dynamics
EU Organic Regulation enforcement is compressing supplier qualification timelines while Mediterranean drought patterns concentrate raisin and date sourcing among irrigated Californian and Turkish cooperatives, forcing buyers to pre-commit volumes earlier in the harvest cycle.
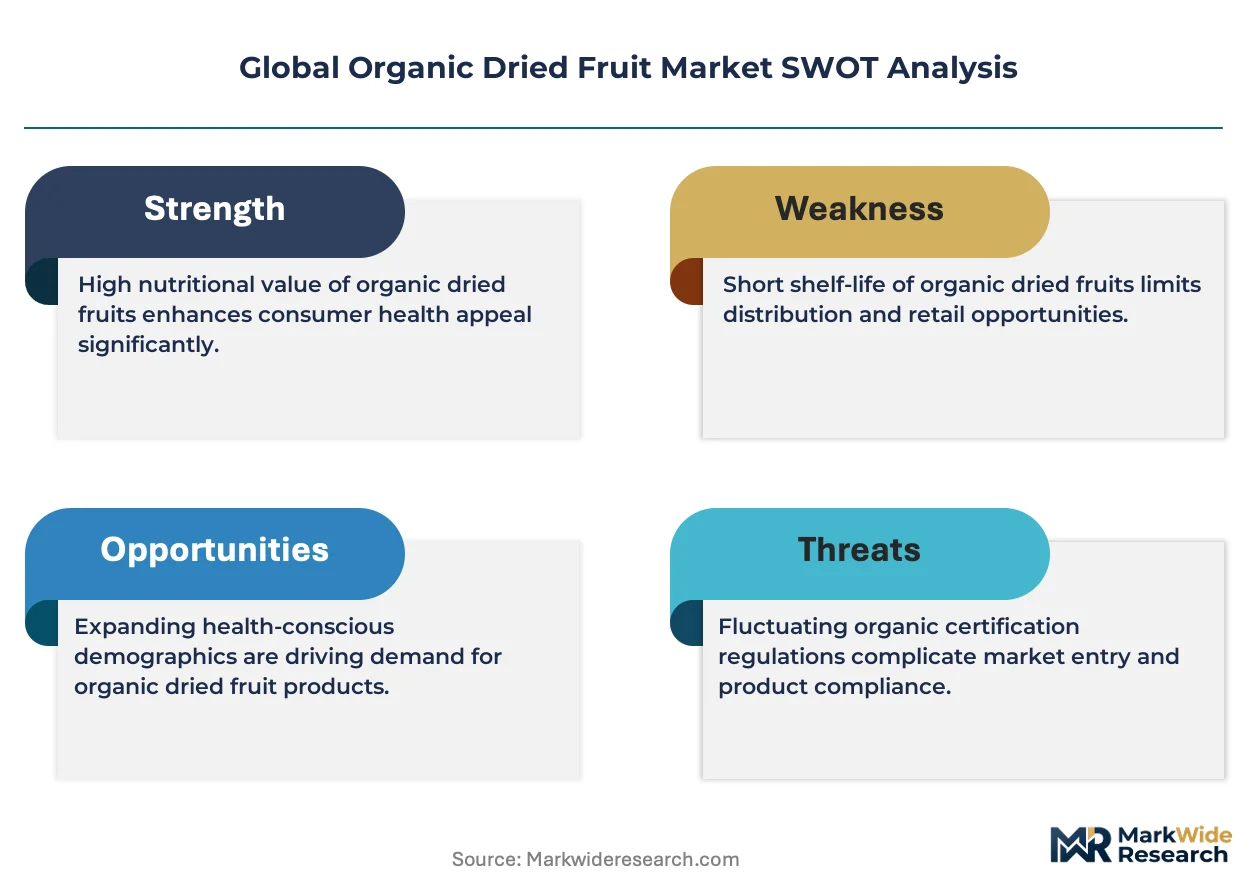
Growth Catalysts
- EU Green Deal agricultural incentives:The EU's Farm to Fork Strategy subsidizes organic orchard conversion across Spain and Italy, expanding certified apricot and fig supply bases for ingredient processors.
- Clean-label bakery reformulation:European food manufacturers specify organic dried fruit powders to replace synthetic flavor enhancers in gluten-free and reduced-sugar product lines.
- Solar tunnel drying adoption:Turkish and Iranian processors deploy photovoltaic-assisted dehydration to cut fossil fuel dependence and meet EU organic energy-use criteria.
Market Restraints
- Water input cost volatility:California's Central Valley groundwater restrictions raise irrigation expenses for organic raisin growers, compressing margins against conventional competitors.
- Single-origin supply concentration:Organic dried cranberry output clusters in Massachusetts and Wisconsin, creating weather-driven availability risk for North American buyers.
- Synthetic residue testing limitations:Current laboratory protocols cannot detect all novel pesticide metabolites, delaying EU Organic Regulation clearance for borderline shipments.
Strategic Opportunities
- India organic orchard development:Maharashtra and Karnataka mango and papaya growers seek export certification to supply European and Middle Eastern private-label programs.
- Functional snack bar integration:Sports nutrition formulators in Germany and the Netherlands specify protein-fortified organic date pastes as binders and natural sweeteners.
- EU AI Act supply chain transparency:Automated batch-tracking systems enable smaller Turkish cooperatives to demonstrate EU Organic Regulation compliance without legacy IT infrastructure.
Industry Challenges
- Organic certification timeline compression:Three-year conversion periods for conventional orchards delay revenue recognition while fixed costs accumulate.
- Cross-border equivalency negotiation friction:Pending USDA-EU organic recognition updates strand container shipments in Rotterdam customs for additional documentary review.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Dried Fruit Market |
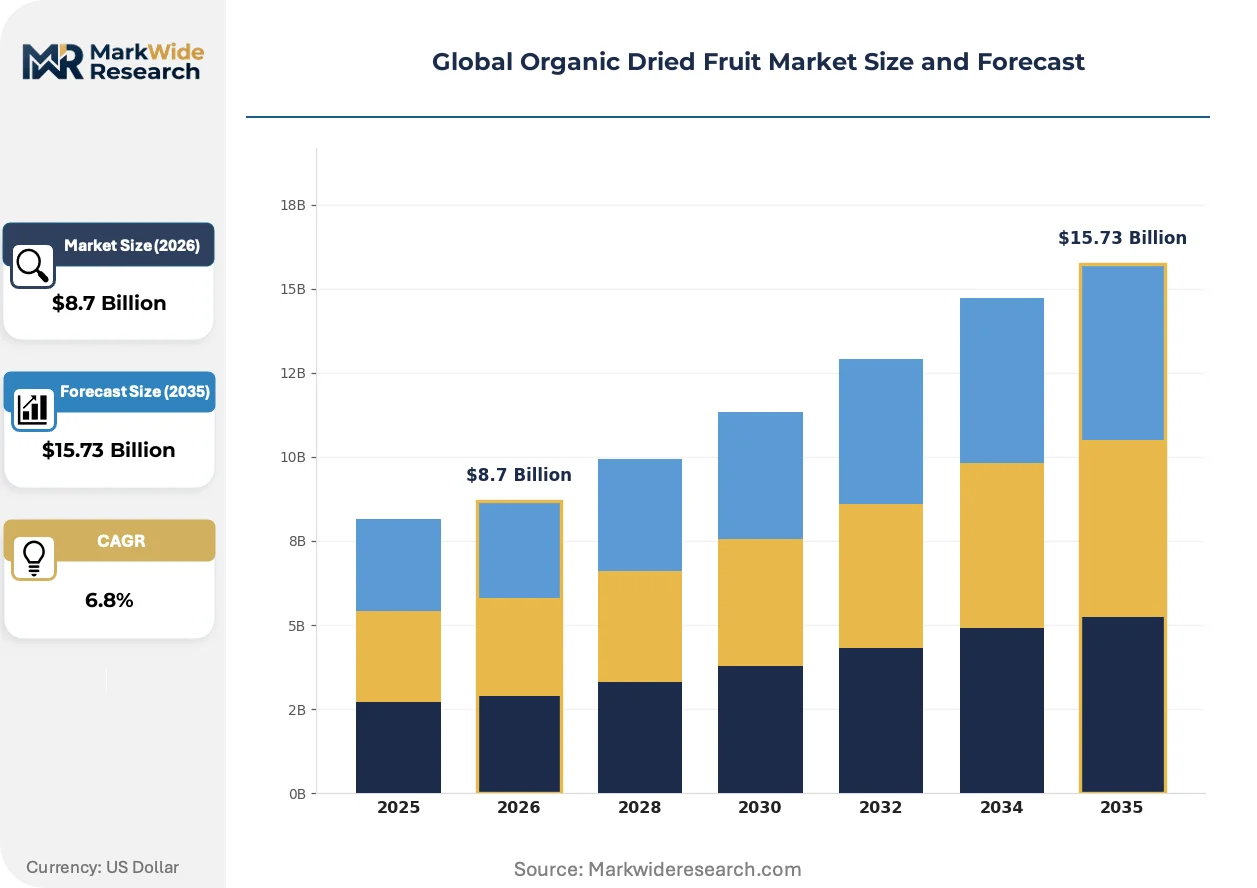
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apricots, Figs, Dates, Raisins Form: Whole, Sliced, Chopped, Powdered End User: Retail Consumers, Food Manufacturers, Restaurants, Bakeries Packaging Type: Bags, Jars, Pouches, Bulk |
| Companies Covered | Meduri Farms, Angas Park Fruit Co., Sun-Maid Growers of California, National Raisin Company, Naturz Organics, Sunsweet Growers Inc., Lion Raisins, Graceland Fruit Inc., Ocean Spray Cranberries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Dried Fruit Market Strategic Shifts
Controlled-atmosphere dehydration and blockchain traceability are restructuring how organic dried fruit moves from orchard to finished goods, compressing quality verification cycles while opening new ingredient specification tiers.
Radio-frequency identification tagging paired with moisture-sensor arrays is rewriting harvest-to-pack traceability for organic raisin cooperatives in California's San Joaquin Valley. German retail chains now mandate lot-level digital passports for private-label organic dried fruit, forcing upstream technology adoption. This sensor integration is compressing recall response windows from weeks to hours while raising capital barriers for non-compliant suppliers.
REACH chemical restriction updates are tightening packaging material specifications for organic dried fruit sold in EU member states. The European Chemicals Agency's expanded substance of very high concern list now covers certain mineral oil residues in recycled cardboard, forcing Turkish exporters to switch virgin fiber or coated alternatives. German organic retailers have accelerated compliance deadlines ahead of regulatory mandates, squeezing margin recovery timelines.
Direct-procurement contracts between European snack manufacturers and Turkish organic fig cooperatives are displacing traditional trader intermediaries. Dutch and Belgian ingredient buyers now station quality auditors at drying facilities in Aydın Province, compressing price discovery and specification negotiation into single-site visits. This channel consolidation is most visible in organic dried apricot procurement, where Rotterdam-based traders have lost volume share to vertically integrated German processors.
Global Organic Dried Fruit Market Segmentation
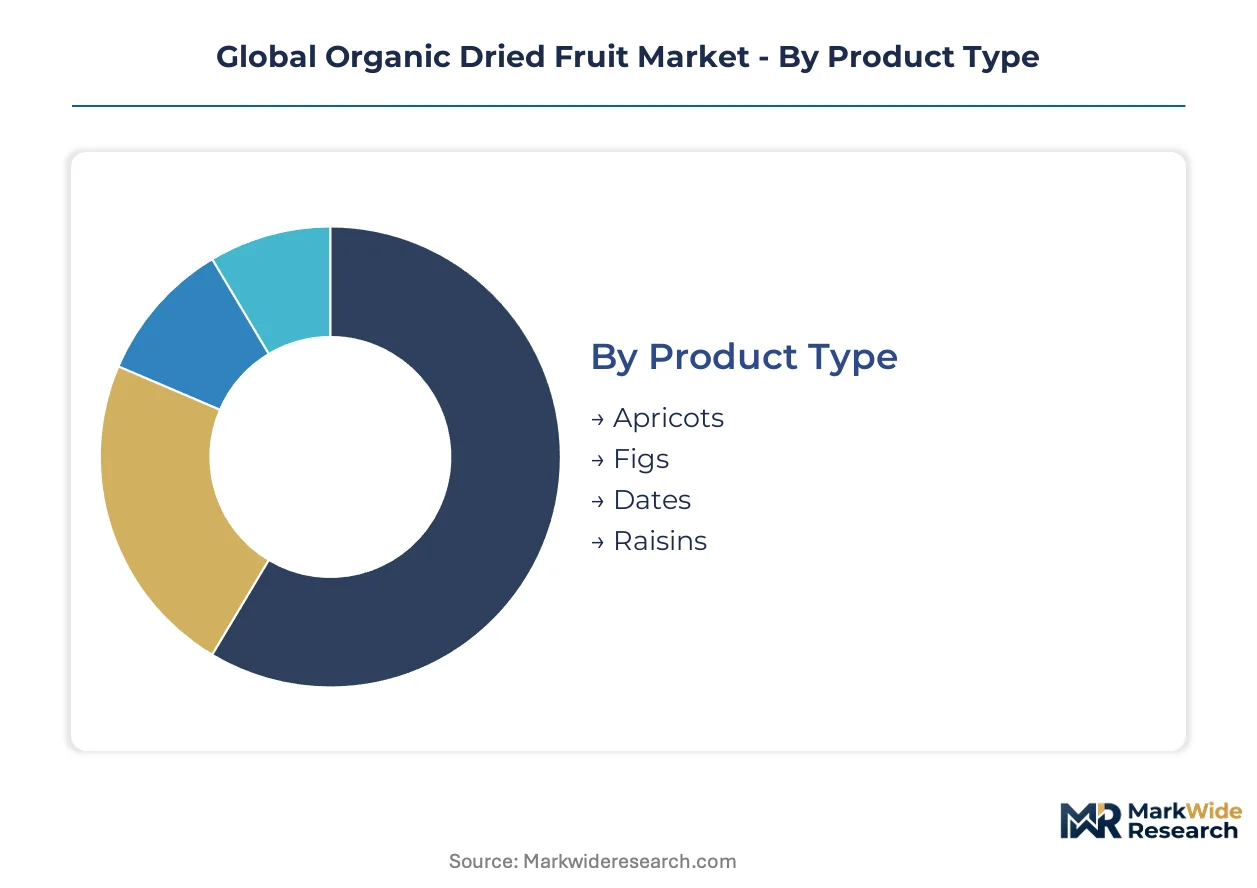
Procurement specifications across the organic dried fruit value chain are fragmenting as EU Organic Regulation enforcement tightens residue thresholds and German retail chains demand format-specific traceability. Buyers now segment supplier qualification by product type, physical form, and end-use application to manage compliance risk and production-line efficiency.
Product Type:
Upgrade cycles in bakery and snack formulations are pushing food manufacturers toward higher-margin organic varieties that command clean-label shelf positioning.
- Raisins:Dehydrated grape varieties from Thompson Seedless and Sultana cultivars dominate industrial procurement volumes. California's San Joaquin Valley cooperatives supply North American cereal and bakery channels, while Turkish Aegean growers serve EU private-label programs facing stricter EFSA residue protocols.
- Dates:Medjool and Deglet Noor varieties anchor natural sweetener applications in energy bars and dairy alternatives. Israeli and Tunisian cooperatives are expanding controlled-atmosphere storage capacity to extend shipping windows for European industrial buyers.
- Apricots:Turkish Malatya and California Central Valley orchards supply halved and whole variants for premium snack mixes.
- Figs:Aydın Province cooperatives in Turkey concentrate organic Calimyrna and Black Mission output for Mediterranean export channels.
Raisins sit at the top of the volume ranking, with dates climbing the fastest as sports nutrition formulators specify paste and syrup variants.
Form:
Cost-tier differentiation separates commodity whole-fruit procurement from value-added processing formats commanding ingredient premiums.
- Powdered:Finely milled organic dried fruit functions as clean-label flavor carriers and natural colorants in gluten-free bakery mixes. Dutch and German manufacturers specify 80-200 micron particle sizes for uniform dispersion in reduced-sugar formulations.
- Whole:Intact fruit units retain consumer-facing retail preference for snacking and gifting applications. California raisin cooperatives and Turkish fig exporters maintain dedicated whole-fruit sorting lines to satisfy Whole Foods Market and REWE Group quality tiers.
- Sliced:Uniform thickness specifications enable consistent rehydration rates in commercial bakery production.
- Chopped:Diced 4-8mm fragments integrate into muesli, granola, and ice cream inclusions without additional processing.
Whole formats dominate current procurement volumes, though powdered variants are gaining share fastest among industrial ingredient buyers.
End User:
Application-specific certification requirements split procurement channels between retail-facing and business-to-business supply chains.
- Food Manufacturers:Industrial buyers specify organic dried fruit powders and chopped formats for clean-label reformulation of breakfast cereals, snack bars, and dairy alternatives. German and Dutch processors require lot-level digital passports to satisfy EU Green Deal traceability mandates.
- Retail Consumers:Direct purchasers select whole and sliced variants in portion-controlled packaging for household snacking. REWE, Edeka, and Carrefour private-label ranges emphasize single-origin Turkish and Californian sourcing stories.
- Bakeries:Artisan and commercial operations source rehydrated whole fruits for bread, pastry, and confectionery applications.
- Restaurants:Foodservice channels procure bulk formats for menu integration in Mediterranean and Middle Eastern cuisine segments.
Food manufacturers represent the dominant demand channel, with retail consumers expanding most quickly as German discounters broaden organic dried fruit shelf space.
Packaging Type:
Supply concentration in Mediterranean and Californian growing regions dictates packaging specifications for moisture control and shelf-life extension.
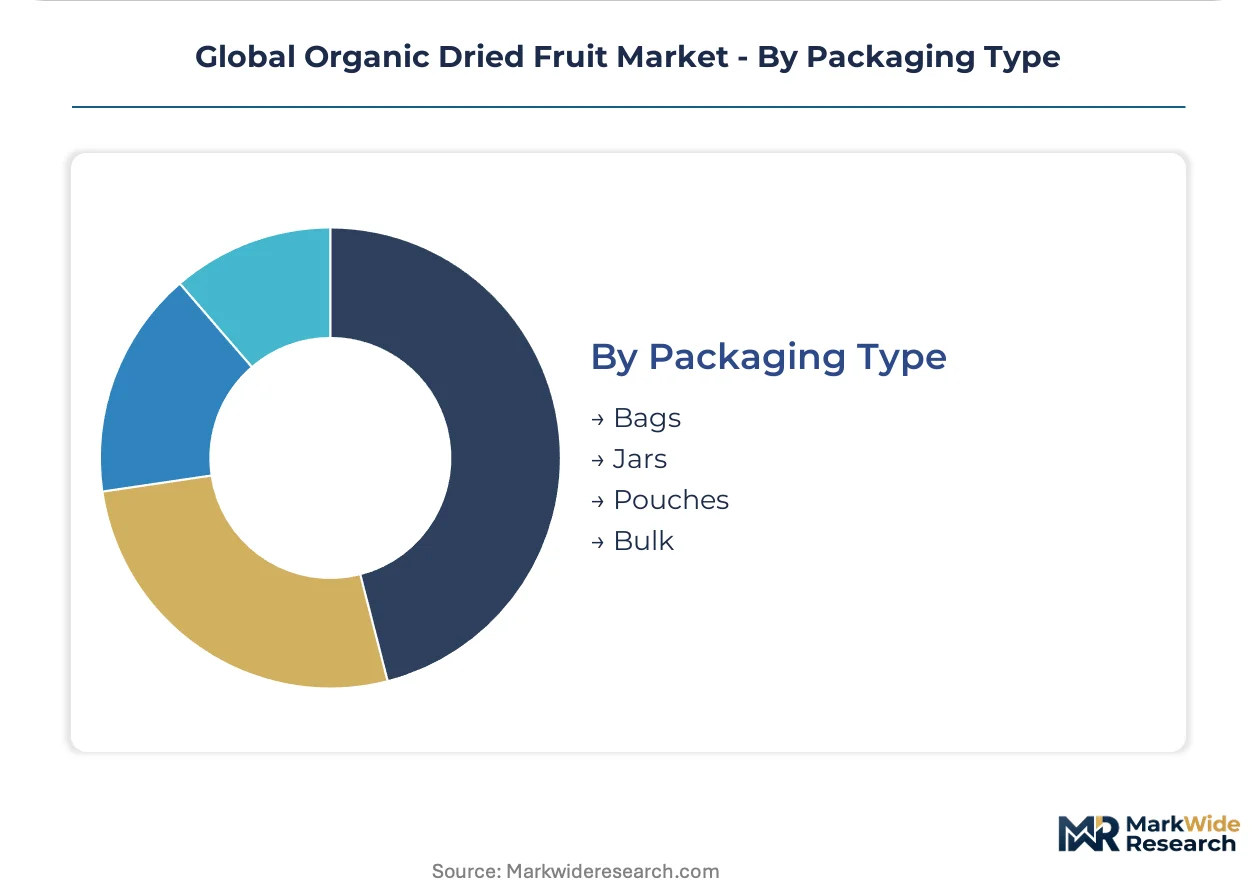
- Bulk:10-25kg food-grade containers serve industrial processors and foodservice distributors with high-throughput requirements. Turkish exporters to Rotterdam and Hamburg increasingly specify vacuum-sealed polyethylene liners to prevent mold in maritime transit.
- Pouches:Stand-up and flat formats with resealable closures capture retail convenience positioning. REACH-compliant virgin fiber and coated alternatives are displacing recycled cardboard for EU-bound shipments.
- Bags:Flexible packaging dominates club-store and conventional retail channels in North American markets.
- Jars:Rigid glass containers target premium gifting and specialty retail positioning in German and Swiss markets.
Bulk packaging leads procurement volumes for industrial channels, with pouches expanding most quickly as private-label programs emphasize portion control and resealability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting organic dried fruit cultivation toward jurisdictions where certification costs and water-access regimes diverge most sharply. Turkish and Californian producers exploit this gap to capture EU-bound volumes.
United States
California's San Joaquin Valley dominates North American raisin output through cooperative structures that pool certification compliance costs. The USDA National Organic Program mandates three-year conversion timelines that filter smaller growers from export eligibility. Fresno County processors deploy radio-frequency tagging to satisfy German retail chain traceability requirements.
Germany
REWE and Edeka private-label expansion drives EU import demand for Turkish organic figs and apricots. The EU Green Deal's Farm to Fork Strategy subsidizes downstream formulation innovation in snack bars and bakery mixes. Hamburg port facilities now require vacuum-sealed bulk packaging to prevent mold in maritime transit from Mediterranean suppliers.
Turkey
Aydın Province fig cooperatives and Malatya apricot growers supply two-thirds of EU organic dried fruit imports. Solar tunnel drying adoption cuts fossil fuel dependence to satisfy EU organic energy-use criteria. Izmir-based exporters face REACH-compliant packaging mandates that displace recycled cardboard for virgin fiber alternatives.
Israel
Medjool date cultivation in the Jordan Valley serves European natural sweetener applications. Controlled-atmosphere storage investments extend shipping windows for industrial buyers in the Netherlands and Belgium. The national agricultural regulator enforces residue protocols that align with EFSA thresholds for EU market access.
India
Maharashtra and Karnataka mango growers pursue export certification to supply Middle Eastern private-label programs. FSSAI organic standards are converging with EU equivalency requirements to reduce documentary friction at Rotterdam customs. Mumbai-based processors experiment with photovoltaic-assisted dehydration for European compliance.
Global Organic Dried Fruit Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue solar-drying technology and blockchain traceability to differentiate positioning. The vendor base clusters around cooperative structures in California and Turkey, with independent processors in Israel and Australia filling specialty date and tropical fruit niches. Three archetypes dominate: vertically integrated cooperatives, ingredient-specialist processors, and retail-private-label suppliers. Competitive moves concentrate on backward integration into orchard certification and pre-commitment contracting to secure harvest volumes ahead of Mediterranean drought cycles.
Among cooperative-structured producers, Sun-Maid Growers of California exemplifies the scale-driven archetype through centralized pooling of San Joaquin Valley output. Graceland Fruit Inc. and Ocean Spray Cranberries Inc. occupy positions within the ingredient-specialist tier, with the latter representing concentrated sourcing from Massachusetts and Wisconsin growing regions. These three entities anchor the competitive landscape without exhaustive claims about specific strategic actions or market positions.
| Leading Market Players |
|---|
| Meduri Farms |
| Angas Park Fruit Co. |
| Sun-Maid Growers of California |
| National Raisin Company |
| Naturz Organics |
| Sunsweet Growers Inc. |
| Lion Raisins |
| Graceland Fruit Inc. |
| Ocean Spray Cranberries Inc. |
| Others |
Value Chain & Pricing Dynamics
Skilled organic certification auditors concentrated in Turkey's Aegean region and California's Central Valley drive labor-cost differentials that widen pricing-tier spreads between EU-compliant premium grades and conventional organic alternatives.
Pricing Analysis
Direct-procurement discounts negotiated between Dutch snack manufacturers and Turkish fig cooperatives are compressing traditional distributor margins that once captured fifteen to twenty percent of landed cost. Three-tier pricing structure across premium, standard, and economy levels separates EU Organic Regulation-certified lots with blockchain traceability from standard-certified and transitional-grade volumes. Pricing pressure stems from California groundwater restrictions raising irrigation expenses for organic raisin growers. Food manufacturers exhibit highest price sensitivity due to reformulation cost targets, while German retail chains absorb premiums for private-label positioning.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg handle bulk consolidation from Mediterranean suppliers before hub-and-spoke delivery to German and Benelux processors. Supply concentrates in Turkey, California, and Israel, with Turkish Aydın Province fig cooperatives and Malatya apricot growers feeding two-thirds of EU import demand. Raw material dependencies center on Thompson Seedless grapes, Medjool date cultivars, and Sultana varietals. Single-origin vulnerability in Massachusetts and Wisconsin organic cranberry output creates weather-driven availability exposure. Distribution runs through vertically integrated cooperatives that pool certification compliance costs across member growers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Organic Dried Fruit Market functions as a stable compounder anchored by EU Green Deal agricultural incentives that subsidize organic orchard conversion across Spain and Italy.
For Market Incumbents: Cement backward integration into certified orchard assets in Turkey's Aydın Province and California's San Joaquin Valley to preempt harvest-volume competition from emerging solar-drying entrants. Lock multi-year direct-procurement contracts with Rotterdam-based processors before equivalency negotiations between USDA and EU organic frameworks conclude.
For New Entrants and Emerging Players: Enter via Maharashtra and Karnataka mango certification programs targeting Middle Eastern private-label gaps where European incumbents maintain limited presence. Solar tunnel drying technology paired with AI Act-compliant batch-tracking systems offers the most penetrable wedge against legacy Turkish cooperatives lacking IT infrastructure.
For Investors and Strategic Acquirers: German retail private-label suppliers are the most active acquirer in this space, seeking captive supply of EU Organic Regulation-certified figs and apricots. Five-to-ten-year viability rests on water-rights security in drought-exposed growing regions. Monitor bilateral organic equivalency agreement updates as the critical inflection signal for cross-border shipment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Orchard Certification Investment | Three-year conversion timelines lock out smaller competitors from EU export eligibility under EFSA protocols. |
| Solar Tunnel Drying Adoption | Photovoltaic-assisted dehydration cuts fossil fuel dependence to satisfy EU organic energy-use criteria. |
| Blockchain Traceability Implementation | Automated batch-tracking enables Turkish cooperatives to demonstrate EU Organic Regulation compliance. |
| Direct-Procurement Contracting | Dutch and Belgian buyers station quality auditors at Aydın Province facilities, displacing Rotterdam traders. |
| REACH-Compliant Packaging Switch | Virgin fiber alternatives replace recycled cardboard to meet European Chemicals Agency substance restrictions. |
Study Parameters
Bottom-up food manufacturer and retail channel modeling reconciled against top-down orchard certification and harvest volume tracking forms the analytical core of this study. Primary interviews with organic certification auditors, cooperative procurement managers, Dutch and German ingredient buyers, and Hamburg port logistics coordinators combined with secondary validation against EU Organic Regulation filings, EFSA residue protocols, USDA National Organic Program standards, and Turkish Aegean Exporters Association trade data. Triangulation across supply-side concentration metrics and demand-channel procurement specifications anchors volume and value estimates.
Input-output matrices map dried fruit format specifications through processing stages to end-use applications across the projection horizon. Segmentation dimensions modeled include product type, physical form, end-user category, and packaging configuration, with regional regulatory cluster and certification grade tier as cross-cutting variables. CAGRs derive from harvest-cycle timing, conversion-period delays, and bilateral equivalency negotiation trajectories. Forecast inputs center on Mediterranean drought pattern probabilities and EU Green Deal subsidy allocation trajectories.
The model holds under stable EU-US organic equivalency recognition and predictable groundwater allocation regimes in California; deviation in bilateral trade agreement updates or severe multi-year drought cycles would shift supply concentration and pricing tier boundaries. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
Organic Cocoa Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Global Organic Soup Market
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
Italy Organic Food Market
Organic Food and Beverages
Organic Yogurt Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
Organic Acai Juice Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
South Africa Organic Food Market