
 Orchard Type Tractors Market | 2026-2036
Orchard Type Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
Orchard Type Tractors Market Analytics
The dealer network for orchard equipment is narrowing as manufacturers consolidate distribution rights across premium territories. John Deere leverages its precision agriculture ecosystem to sustain pricing power in North American fruit belts. Kubota anchors its position in Asian markets through compact chassis designs tailored to terraced hillside operations. CNH Industrial competes via shared powertrain architectures that span its multi-brand portfolio.
Orchard type tractors are low-ground-pressure machines with overall widths typically below 1.2 meters, hydrostatic transmissions, and protective frames designed for dense canopy navigation without branch damage. Their primary purpose is mechanized cultivation, spraying, and harvesting in permanent-crop environments where standard agricultural equipment cannot operate. Narrow tractors and high clearance tractors capture the dominant margin pools, as these configurations command premium pricing in vineyard and tree-nut applications. Electric motors represent the fastest-growing engine type segment, though diesel engines still occupy the volume leadership position across mature markets.
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe compel engine downsizing and after-treatment integration, directly inflating powertrain costs for manufacturers. India's Central Pollution Control Board is phasing in emission norms that will reshape product portfolios for Mahindra & Mahindra and other Asia-focused suppliers. Stakeholders must monitor how battery energy density improvements and charging infrastructure rollouts alter the total cost of ownership calculus for electric orchard tractors.
Market Dynamics
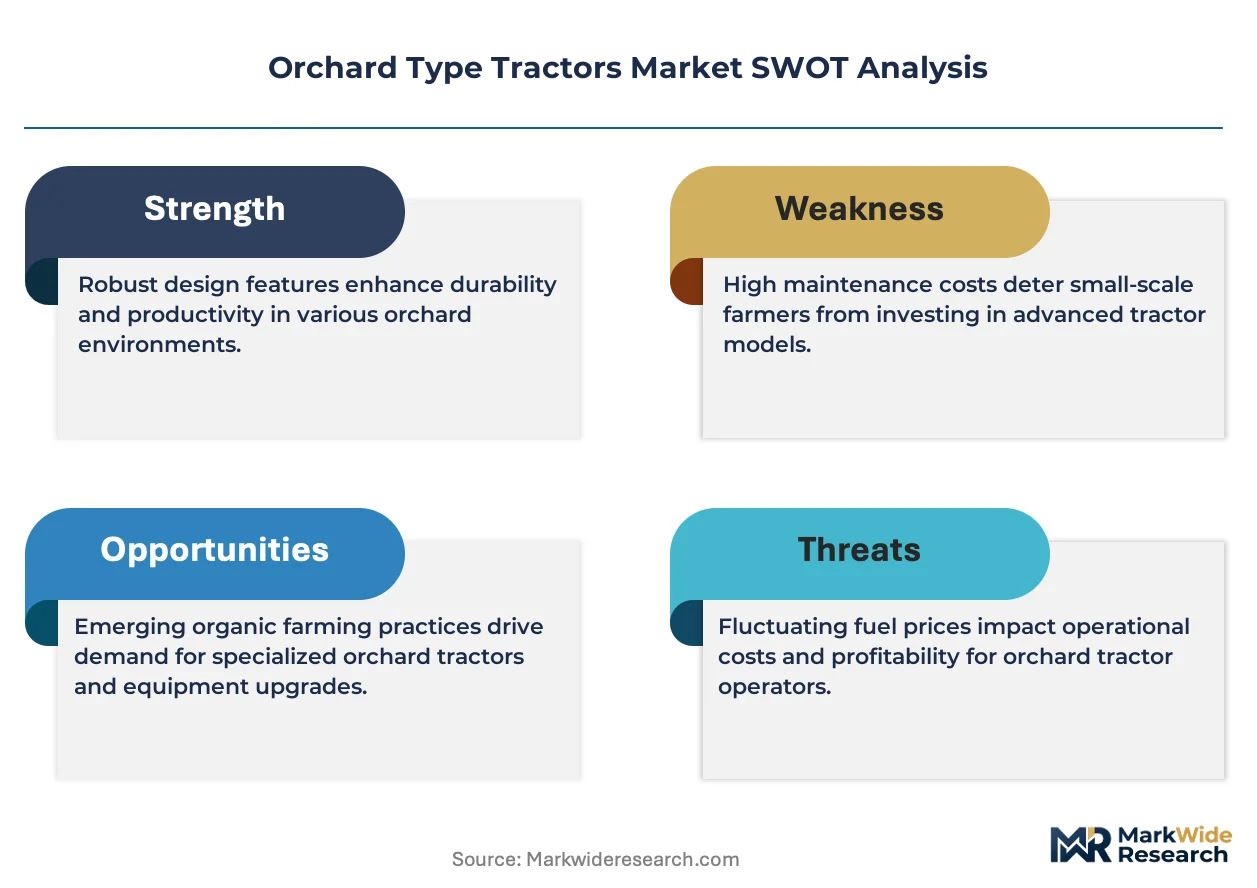
EPA Tier 4 Final emission standards are collapsing the economics of conventional diesel powertrains and forcing manufacturers to absorb six-figure engineering costs per platform. This regulatory compression is redrawing competitive boundaries between incumbents with capital reserves and mid-tier suppliers facing platform obsolescence.
Growth Catalysts
- Hybrid powertrain mandates:EPA Tier 4 Final standards in the United States are compelling manufacturers to integrate electric-assist architectures, opening premium pricing tiers for compliant equipment.
- Vineyard mechanization clusters:Italy's Emilia-Romagna region is driving concentrated demand for ultra-low ground pressure machines as labor costs rise in dense canopy operations.
- Terraced hillside specialization:Compact chassis designs tailored to Asian topography are unlocking mechanization in previously inaccessible terrain.
Market Restraints
- After-treatment cost inflation:Diesel particulate filters and selective catalytic reduction systems add substantial material cost to powertrain assemblies.
- Battery energy density limitations:Current lithium-ion cell chemistry constrains runtime duration for electric orchard tractors operating full cultivation cycles.
- Charging infrastructure gaps:Rural permanent-crop regions lack the grid capacity and fast-charging networks needed for fleet electrification.
Strategic Opportunities
- India emission norm transitions:The Central Pollution Control Board's phased regulations will reshape product portfolios for domestic-focused suppliers.
- Precision agriculture convergence:Integration of GPS-guided autosteer with canopy-sensing sprayers is creating subscription revenue streams beyond equipment sales.
- Dealer network consolidation:Narrowing distribution rights in premium territories creates acquisition targets for manufacturers seeking territorial control.
Industry Challenges
- Powertrain engineering talent scarcity:Hybrid-electric system design requires capabilities concentrated in automotive and aerospace sectors, not traditional agricultural equipment.
- Certification timeline compression:EU Stage V and EPA Tier 4 Final parallel compliance demands are straining validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orchard Type Tractors Market |
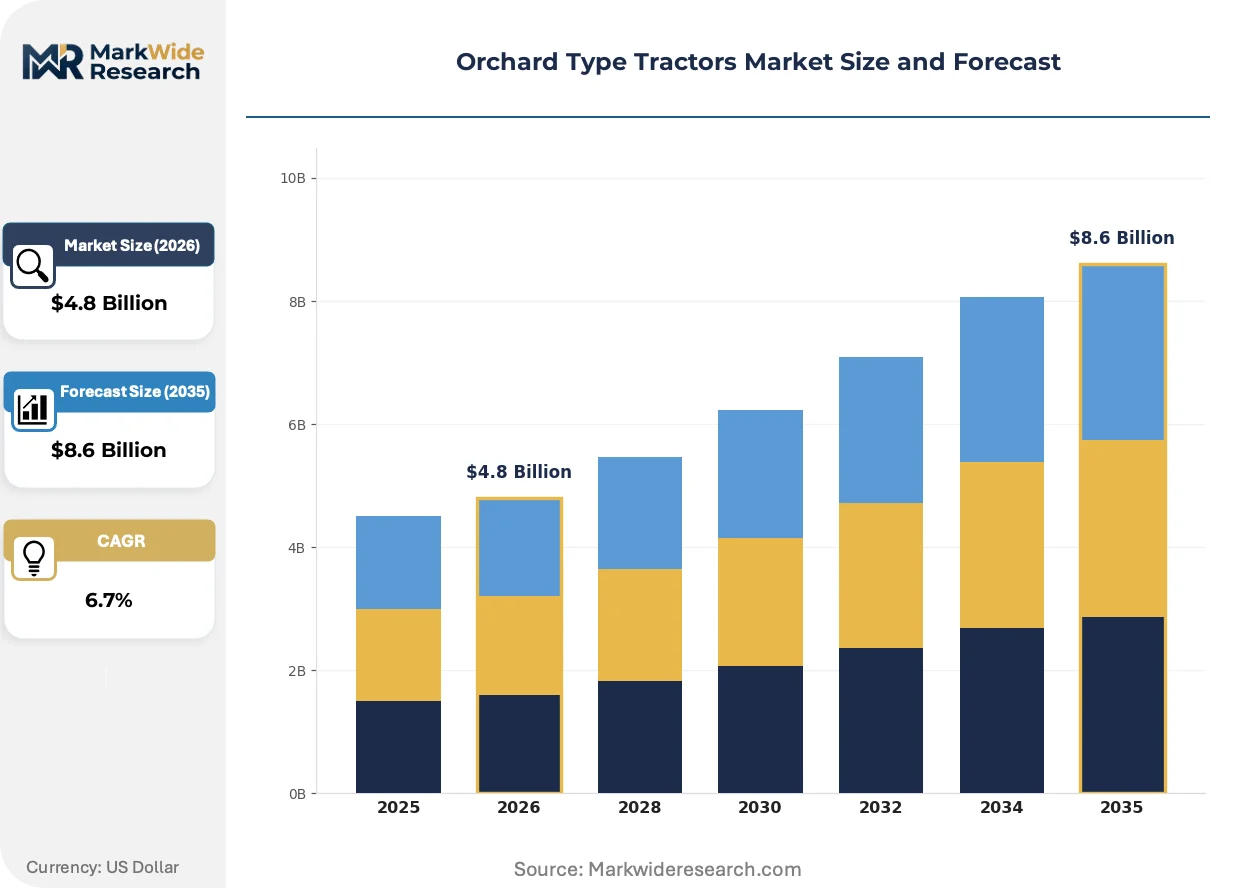
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Narrow Tractors, Specialty Tractors, High Clearance Tractors Engine Type: Diesel Engines, Electric Motors, Hybrid Engines, Biofuel Engines Drive Train: Two-Wheel Drive, Four-Wheel Drive, All-Wheel Drive, Track Drive Application: Fruit Harvesting, Vineyard Maintenance, Soil Preparation, Pest Control |
| Companies Covered | John Deere, Kubota, CNH Industrial, Mahindra & Mahindra, AGCO Corporation, SDF Group, Yanmar, Claas, Argo Tractors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orchard Type Tractors Market Evolving Landscape
Powertrain electrification is collapsing the traditional segmentation between engine displacement classes and enabling new equipment categories previously impossible with mechanical architectures.
Hydrostatic transmissions paired with electric motors are collapsing the maintenance cost advantage that diesel-hydraulic systems held for decades. Specialty crop growers in California's Central Valley are adopting these configurations fastest, driven by air quality management district pressure. The structural consequence is collapsing resale value trajectories for Tier 3 and earlier diesel assets.
EU Stage V regulations are forcing exhaust after-treatment packaging that competes for chassis space with battery packs and hydraulic reservoirs. Manufacturers are responding with shared powertrain architectures that span multiple brand portfolios to amortize compliance costs. Narrow-profile machines in Italian and French vineyard applications face the tightest packaging constraints.
California's Central Valley growers are unbundling equipment procurement from bundled service contracts, instead purchasing maintenance parts directly through manufacturer portals. Traditional dealer service departments are losing attach rates as fleet managers internalize preventive maintenance capabilities. This pattern is most visible among tree-nut operations with centralized equipment yards.
Orchard Type Tractors Market Segmentation
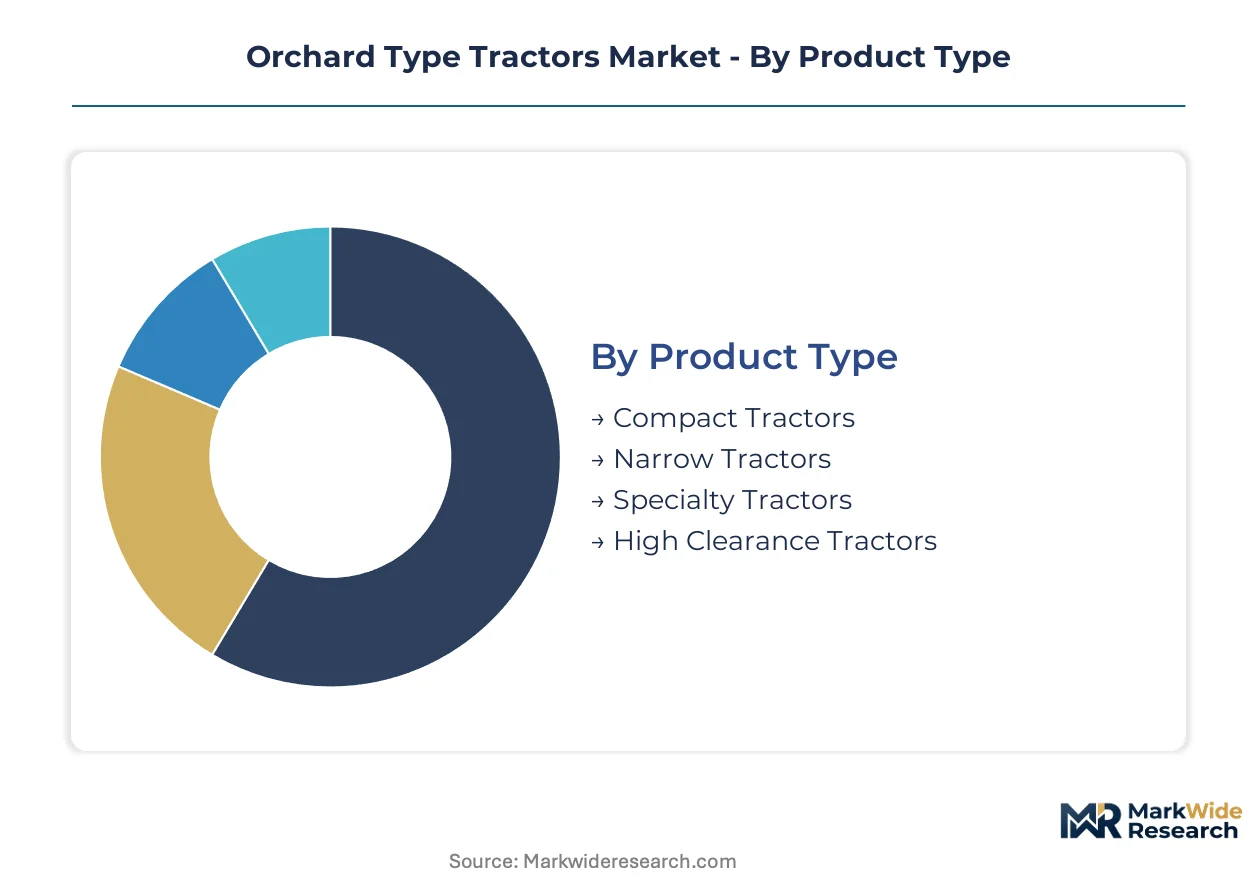
Orchard tractor configurations diverge sharply across permanent-crop environments, where canopy density, row spacing, and terrain gradient dictate equipment selection. Manufacturers engineer distinct chassis architectures for each operational profile, creating tiered margin pools that reward specialization over generic platforms.
Product Type:
Use-case spectrum spans sub-40 horsepower compact units for smallholder operations to 150+ horsepower high-clearance machines for industrial tree-nut harvesting.
- Narrow Tractors:Overall widths below 1.2 meters enable navigation through dense vineyard rows without branch damage. Demand concentrates in Italy's Emilia-Romagna region, where labor cost inflation drives mechanization of previously manual canopy management tasks.
- High Clearance Tractors:Elevated chassis architectures provide ground clearances exceeding 1.5 meters for mid-canopy spraying and harvesting in mature tree-nut orchards. California's Central Valley specialty crop growers are expanding fleets of these machines as air quality management districts tighten emission enforcement.
- Compact Tractors:Sub-50 horsepower machines serve terraced hillside operations in Asian markets where field sizes preclude larger equipment deployment.
- Specialty Tractors:Purpose-built configurations integrate implements for specific permanent-crop tasks, commanding premium pricing in concentrated cultivation zones.
Established volume favors compact tractors; emerging adoption favors high-clearance configurations.
Engine Type:
Powertrain cost tiers stratify sharply as emission compliance burdens reshape total cost of ownership calculations across fleet replacement cycles.
- Diesel Engines:EPA Tier 4 Final and EU Stage V after-treatment requirements have inflated powertrain material costs substantially. Diesel particulate filters and selective catalytic reduction systems now compete for chassis packaging space with hydraulic reservoirs.
- Electric Motors:Battery energy density improvements are extending runtime duration for cultivation cycles, though charging infrastructure gaps in rural permanent-crop regions constrain fleet-scale deployment.
- Hybrid Engines:Electric-assist architectures amortize compliance costs across shared powertrain platforms, climbing the fastest as manufacturers seek intermediate solutions between conventional diesel and full electrification.
- Biofuel Engines:Modified compression-ignition platforms running renewable diesel or biodiesel blends serve operators seeking emission reductions without infrastructure dependency.
Volume leadership remains with diesel; steepest expansion trajectory belongs to hybrid configurations.
Drive Train:
Traction requirements vary from firm vineyard soils requiring minimal ground disturbance to steep hillside terrain demanding continuous all-wheel torque distribution.
- Four-Wheel Drive:Dominates permanent-crop applications where row-end turning and soft soil conditions require balanced torque delivery. Hydrostatic transmissions paired with mechanical four-wheel-drive systems have become the standard configuration for mid-size orchard operations.
- Track Drive:Ultra-low ground pressure systems distribute machine weight across broad contact patches, critical for wet harvest conditions in dense clay soils.
- Two-Wheel Drive:Lightweight mechanical simplicity persists in dry-climate tree-nut applications with firm soil conditions and minimal slope.
- All-Wheel Drive:Fully independent torque management enables precision navigation in irregular terrain, gaining share in premium vineyard mechanization clusters.
Four-wheel drive anchors current procurement; track drive is gaining share fastest in premium territories.
Application:
Task-specific equipment configurations create distinct margin pools based on seasonal utilization rates and implement integration complexity.
- Vineyard Maintenance:Year-round canopy management, pruning, and under-vine cultivation demand versatile platforms with rapid implement changeover. Italian and French wine regions drive concentrated demand for ultra-narrow machines with precision guidance systems.
- Fruit Harvesting:Shaking and catching operations for tree nuts and stone fruits require high-clearance chassis with integrated hydraulic systems for vibratory head attachment.
- Soil Preparation:Subsoiling and cultivation in established orchards favors compact, maneuverable units that minimize root zone disturbance.
- Pest Control:Canopy-sensing sprayers mounted on narrow-profile tractors enable targeted chemical application, reducing input costs and environmental load.
Vineyard maintenance commands the dominant margin pool; pest control applications are expanding most quickly through precision agriculture convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Oakland's container throughput underwrites California's Central Valley as the primary North American gateway for orchard equipment imports, while Italy's Emilia-Romagna logistics corridor channels Mediterranean distribution.
United States
California's Central Valley specialty crop growers are expanding narrow-profile tractor fleets as air quality management districts tighten emission enforcement. EPA Tier 4 Final standards are collapsing conventional diesel economics and forcing hybrid powertrain adoption. Fresno County tree-nut operations are internalizing preventive maintenance capabilities and bypassing traditional dealer service departments.
Italy
Emilia-Romagna's dense vineyard operations are driving concentrated demand for ultra-low ground pressure machines as labor costs rise in canopy management tasks. EU Stage V regulations are forcing exhaust after-treatment packaging that competes for chassis space with battery systems. Bologna's precision agriculture cluster is integrating GPS-guided autosteer with canopy-sensing sprayers.
India
Maharashtra's terraced hillside vineyards and fruit orchards are unlocking mechanization through compact chassis designs previously impossible in narrow terrain. The Central Pollution Control Board's phased emission norms are reshaping product portfolios for domestic-focused suppliers. Nashik's wine region is emerging as a testbed for sub-50 horsepower electric-assist configurations.
Japan
Shizuoka's tea plantations and Yamanashi's vineyard slopes are demanding compact tractors with hydrostatic transmissions tailored to irregular topography. METI's agricultural mechanization subsidies are accelerating replacement cycles for aging diesel fleets. Nagoya's industrial belt is supplying precision hydraulic components for narrow-profile powertrains.
Germany
Baden-Württemberg's steep vineyard terraces are requiring all-wheel-drive torque management systems for precision navigation in irregular terrain. REACH compliance and EU Stage V parallel demands are straining validation resources for multi-brand powertrain architectures. Stuttgart's engineering services cluster is concentrating hybrid-electric system design talent from automotive sector migration.
Orchard Type Tractors Market Competitive Landscape
On the supply side, the industry is consolidating around capital-reserved incumbents capable of absorbing six-figure EPA Tier 4 Final engineering costs per platform. Mid-tier suppliers face platform obsolescence as regulatory compression redraws competitive boundaries. Three archetypes dominate: precision agriculture ecosystem integrators, compact chassis specialists for terraced terrain, and multi-brand portfolio operators leveraging shared powertrain architectures. M&A activity targets territorial distribution rights, while manufacturers pursue strategic partnerships to amortize compliance costs across shared platforms.
Within the precision agriculture tier, John Deere exemplifies ecosystem-based pricing power through integrated farm management systems. Kubota occupies a position among compact chassis specialists serving Asian hillside topography. CNH Industrial represents the multi-brand portfolio archetype, leveraging shared architectures across its equipment lines to distribute regulatory compliance investments. These three anchors illustrate how capital depth and geographic specialization determine competitive survival under emission mandate pressure.
| Leading Market Players |
|---|
| John Deere |
| Kubota |
| CNH Industrial |
| Mahindra & Mahindra |
| AGCO Corporation |
| SDF Group |
| Yanmar |
| Claas |
| Argo Tractors |
| Others |
Value Network & Pricing Analysis
Undercapacity in European engine component manufacturing is compressing Tier 4 Final compliance timelines and forcing manufacturers to pre-pay for scarce after-treatment assembly capacity. This utilization squeeze simultaneously inflates powertrain input costs and concentrates pricing leverage among foundries certified for EPA and EU Stage V architectures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates precision agriculture ecosystem bundles from bare-chassis configurations. Price differentiation hinges on telematics integration depth and emission certification tier, with California air quality management districts driving premium tier absorption. Cost compression in economy diesel configurations is intensifying because residual value collapse for Tier 3 assets eliminates trade-in support. Fleet operators in tree-nut applications exhibit lowest price sensitivity due to cultivation cycle criticality, while smallholder vineyard owners in emerging markets anchor the economy tier.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates powertrain component sourcing decisions for multi-brand portfolio operators. Supply concentrates in Italy for narrow-profile hydraulic systems, Germany for precision transmission assemblies, and Japan for compact chassis castings. Raw material dependencies span high-strength steel for protective frames, lithium-ion cells for electric-assist modules, and rare-earth magnets for motor assemblies. Single-source vulnerability persists in exhaust after-treatment substrate manufacturing. Distribution runs through manufacturer-direct portals for large fleet accounts and consolidated dealer networks for territory-exclusive service coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive survival as precision agriculture ecosystems subsume standalone equipment margins through subscription-based farm management integration. Interoperability between canopy-sensing implements and GPS-guided autosteer is collapsing the boundary between hardware procurement and ongoing service revenue.
For Market Incumbents: Insulate core powertrain architecture investments through backward integration into battery pack assembly and captive supply of hydraulic control modules. Consolidate territorial distribution rights in Italy's Emilia-Romagna and California's Central Valley before mid-tier suppliers secure emission-compliant platform access. Priority lever rests on hybrid-electric engineering talent acquisition from automotive sector migration.
For New Entrants and Emerging Players: India's Maharashtra terraced hillside vineyards represent the most penetrable entry point for sub-50 horsepower electric-assist configurations underserved by incumbent compact chassis portfolios. Nashik's wine region offers regulatory sandbox conditions through Central Pollution Control Board phased norm transitions. Go-to-market angle should emphasize direct manufacturer portal procurement bypassing traditional dealer service departments.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision agriculture ecosystem integrators with telemetry subscription attach rates exceeding hardware depreciation cycles. Long-term viability across the analysis window favors acquisition targets possessing shared powertrain architectures that amortize EPA Tier 4 Final compliance costs across multi-brand portfolios. Signal to watch is charging infrastructure deployment velocity in rural permanent-crop regions as inflection indicator for fleet-scale electrification economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Platform Standardization | Shared architectures across brand portfolios distribute EPA Tier 4 Final engineering costs. |
| Precision Agriculture Ecosystem Integration | John Deere's farm management system bundling creates subscription revenue beyond equipment sales. |
| Backward Integration into Battery Assembly | Captive lithium-ion pack production secures supply chain control for electric-assist configurations. |
| Territorial Distribution Rights Consolidation | Exclusive dealer network control in premium vineyard clusters locks out mid-tier competitors. |
| Charging Infrastructure Partnership | Grid capacity expansion in California Central Valley enables fleet electrification at scale. |
Research Methodology
Desk research of customs trade filings, agricultural equipment registration databases, and emission certification records preceded structured interviews with orchard fleet managers, precision agriculture technology directors, hydraulic systems procurement leads, and aftermarket service heads. Primary fieldwork combined with secondary validation from SEC equipment manufacturer disclosures and EPA engine certification listings. Bottom-up unit shipment estimates were triangulated against top-down powertrain production capacity assessments across the analysis window.
Assumption sets held emission regulation enforcement timelines and battery energy density improvement curves fixed while varying lithium carbonate price trajectories and charging infrastructure deployment rates. Segmentation dimensions modeled include tractor configuration category, engine type architecture, drive train specification, and permanent-crop application task. CAGRs were derived from installed base replacement cycle analysis and fleet expansion patterns in mechanizing vineyard operations. Industry-specific forecast inputs incorporated air quality management district enforcement intensity and labor cost inflation in canopy management tasks.
Stress conditions across lithium supply disruption, EPA enforcement acceleration, and vineyard mechanization adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding powertrain cost trajectories and subscription revenue conversion rates. Specific risk factors that could revise projections include unilateral tariff imposition on European hydraulic components and faster-than-anticipated battery chemistry breakthroughs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
Tractor Implements Market
Agricultural Machinery
Farm Tractor Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Wheat Milling Machine Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
Agriculture and Farm Machinery Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
Latin America Agricultural Machinery Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
North America Haying and Forage Machinery Market