
 Flavor Drops Market | 2026-2036
Flavor Drops Market Size, Share, and Industry Trends Forecast 2026-2036
Flavor Drops Market Analysis
Market Context
Multi-source botanical extract procurement is pivoting toward vertically integrated supply chains as ingredient traceability becomes a purchasing priority. Beyond Water leverages captive flavor formulation partnerships to secure consistent extract quality across its hydration SKU range. LorAnn Oils sustains century-old manufacturing scale in confectionery-grade concentrates, while Capella Flavor Drops competes through direct-to-consumer channel control in the DIY e-liquid adjacent segment.
Technical Definition and Segment Structure
Flavor drops are highly concentrated, water-soluble or oil-dispersible liquid flavoring systems typically dosed at 0.1–2.0% by weight, manufactured through solvent extraction, steam distillation, or enzymatic bioconversion of natural or nature-identical precursors. Their primary commercial purpose is to impart precise sensory profiles to finished goods without adding significant caloric, volumetric, or textural load. Liquid drops dominate volume throughput in beverage applications where pump-and-pour dispensing aligns with industrial line speeds, while powder drops command margin premiums in sports nutrition sachets requiring shelf-stable portability. The household end-user segment shows the fastest trajectory as SodaStream-compatible flavor cartridges normalize at-home carbonation customization.
Regulatory Framework and Outlook
FDA oversight of flavoring substances under 21 CFR 172, EFSA evaluations of food contact materials, and FEMA GRAS self-determination protocols collectively shape formulation permissibility and cross-border market access timelines. REACH compliance in Europe adds testing burdens for synthetic aroma chemical imports, while China's SAMR national food safety standards mandate label disclosure of all flavoring compounds above threshold limits. Stakeholders must monitor evolving natural flavor definition disputes between FDA and EFSA, as divergent rulings on enzymatically processed extracts threaten to bifurcate acceptable ingredient decks across Atlantic trade lanes.
Market Dynamics
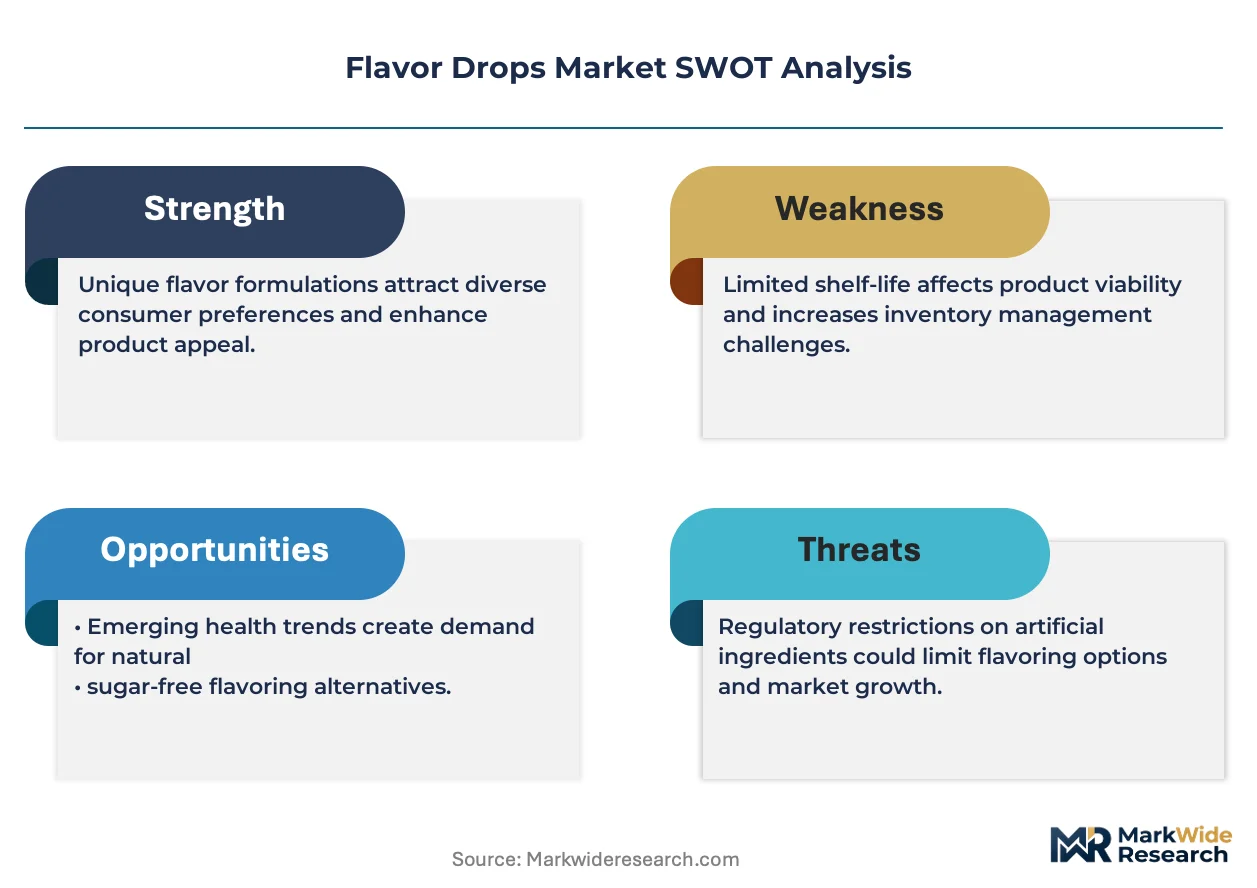
Clean-label formulation mandates from FDA and EFSA are compressing synthetic flavoring acceptance windows, forcing manufacturers toward enzymatic bioconversion and captive botanical sourcing to maintain shelf presence in major retail channels.
Growth Catalysts
- Carbonation appliance penetration:SodaStream-compatible cartridge systems normalize at-home flavor customization, creating pull-through demand for concentrated dosing formats in household kitchens.
- Sports nutrition format evolution:Powder sachets and ready-to-mix bottles favor micro-dose liquid concentrates over bulk flavor systems, aligning with gym and trail portability requirements.
- REACH compliance acceleration:European synthetic aroma chemical testing protocols push formulators toward natural extract alternatives, expanding addressable market for botanical-derived drops.
Market Restraints
- Vanilla and citrus extract price volatility:Madagascar vanilla bean harvest fluctuations and Florida citrus greening disease create input cost instability that squeezes mid-tier manufacturer margins.
- Supply concentration in Southeast Asian processing:Steam distillation capacity clusters in Indonesia and Vietnam, exposing buyers to monsoon disruption and port congestion risks.
- Natural flavor definition divergence:FDA enzymatic processing rulings conflict with EFSA botanical extract standards, forcing dual formulation tracks for trans-Atlantic distribution.
Strategic Opportunities
- China functional beverage white space:SAMR's expanded flavor additive positive list opens formulation latitude for sports and energy drink applications previously restricted to synthetic options.
- Pharmaceutical masking applications:Pediatric and geriatric liquid medication palatability requirements create adjacent demand for bitter-blocking flavor systems at clinical-grade purity thresholds.
- Direct-to-brewer coffee roasting partnerships:Specialty roasters seek custom flavor profiling tools for seasonal limited releases, bypassing traditional flavor house minimum order constraints.
Industry Challenges
- Flavor chemist talent scarcity:Retiring baby-boomer formulators and insufficient university pipeline output create bottlenecks in natural extract characterization and stability testing capabilities.
- Multi-jurisdiction label compliance:Divergent SAMR, FDA, and EFSA disclosure thresholds for allergen cross-contamination and processing aids force SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavor Drops Market |
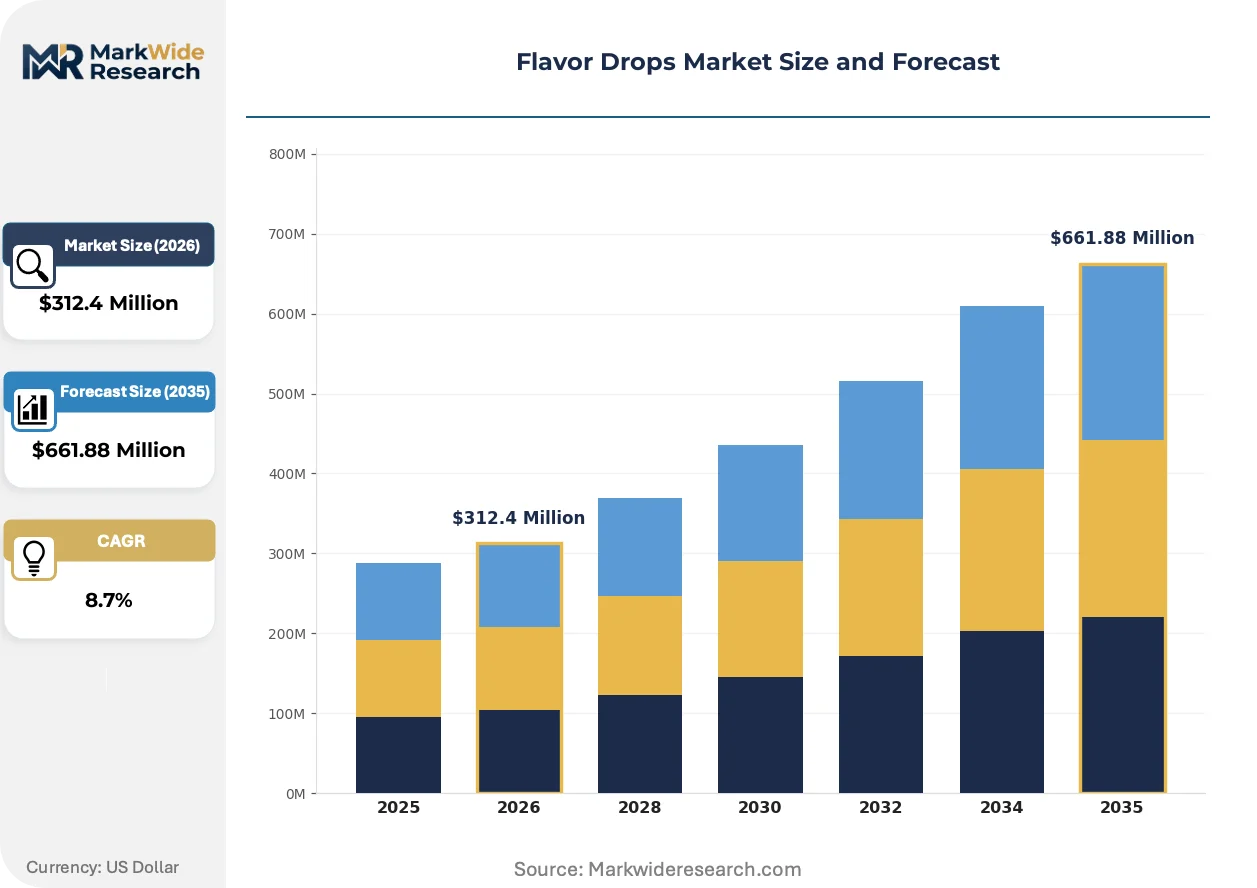
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Drops, Powder Drops, Syrup Drops, Concentrate Drops Application: Beverages, Confectionery, Bakery, Sauces End User: Household, Food Service, Retail, Industrial Flavor Profile: Fruity, Savory, Spicy, Herbal |
| Companies Covered | Beyond Water, My Protein, Flavorah, LorAnn Oils, Flavor West Manufacturing, Capella Flavor Drops, GymBeam, Prozis, SodaStream, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavor Drops Market Emerging Trajectories
Enzymatic extraction and precision fermentation platforms are collapsing the cost premium between natural-identical and botanical-derived flavoring systems, redrawing competitive boundaries between synthetic and natural supply bases.
Precision fermentation of volatile aroma compounds is rewriting cost structures for high-value botanicals like saffron and vanilla. Beverage manufacturers in Germany and the United States are qualifying these bioconverted materials at pilot scale. The technology is compressing the historical 10:1 price gap between synthetic vanillin and Bourbon vanilla extract, forcing mid-tier natural suppliers to defend positioning through provenance storytelling rather than chemistry alone.
EFSA's updated guidance on food contact materials and enzymatic processing aids is tightening migration testing requirements for flavor delivery systems. Manufacturers must now document substrate origin and enzyme catalyst specificity for natural flavor claims. Sports nutrition brands selling into European markets are reformulating to preempt 2025 enforcement windows, accelerating substitution timelines for legacy solvent-extracted ingredients.
Subscription-based flavor curation is displacing traditional retail trial-and-repeat purchase patterns. Direct-to-consumer platforms offer personalized palate profiling and quarterly flavor rotations, capturing lifetime value from home carbonation enthusiasts. This model concentrates most visibly in United States metropolitan markets where appliance penetration exceeds 15% of households and digital native brands control last-mile fulfillment.
Flavor Drops Market Segmentation
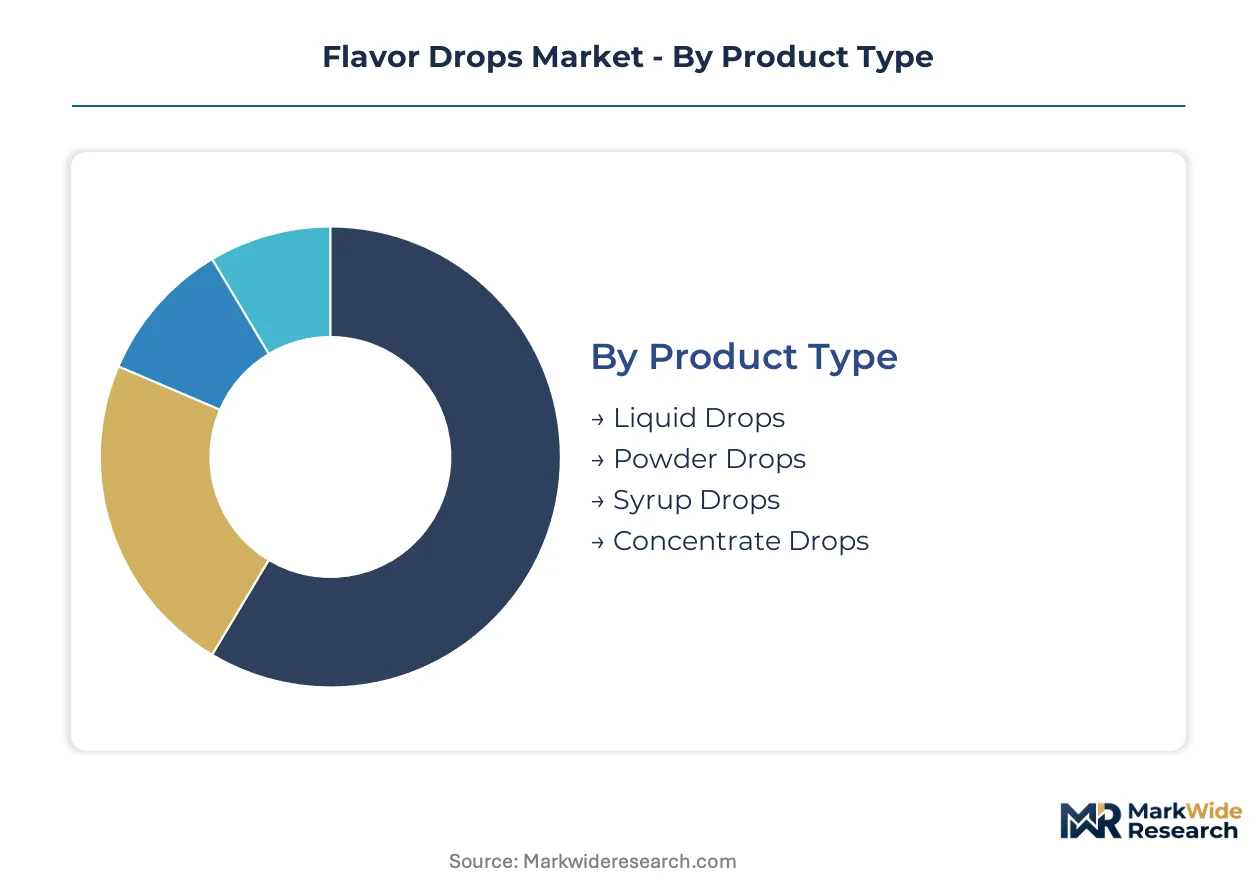
Supply chain configuration in flavor drops varies sharply across product formats, with liquid systems dominating high-volume beverage lines while powder concentrates capture premium sports nutrition margins. Segmentation reveals how formulation physics and dispensing economics partition end-use demand.
Product Type:
Steam distillation and enzymatic bioconversion capacity clusters in Southeast Asian processing hubs, concentrating supply risk for natural extract-dependent formats.
- Liquid Drops:Water-soluble or oil-dispersible concentrates dosed at 0.1–2.0% by weight, manufactured through solvent extraction or steam distillation. Pump-and-pour dispensing aligns with industrial beverage line speeds in Germany and United States bottling facilities, though Madagascar vanilla bean price volatility squeezes mid-tier manufacturer margins.
- Powder Drops:Spray-dried or encapsulated flavor systems requiring shelf-stable portability for sports nutrition sachets. Gym and trail usage in United States metropolitan markets favors micro-dose formats over bulk alternatives, with powder commanding margin premiums despite higher unit production costs.
- Syrup Drops:Viscous sugar-carrying bases common in confectionery applications.
- Concentrate Drops:Ultra-high potency extracts for pharmaceutical masking and clinical-grade applications.
Liquid drops absorb the bulk of installed capacity; powder drops are expanding most quickly.
Application:
End-use economics separate high-throughput commodity dosing from precision flavor layering in premium finished goods.
- Beverages:Carbonated soft drinks, functional waters, and energy formulations represent the primary throughput channel. SodaStream-compatible cartridge systems in United States households normalize at-home customization, pulling demand for concentrated dosing formats previously confined to industrial settings.
- Confectionery:Hard candy, chocolate, and gummy applications require heat-stable flavor systems resistant to thermal degradation during cooking.
- Bakery:Yeast-compatibility and oven-stability specifications limit viable flavor chemistries.
- Sauces:Acid and salt tolerance requirements for condiment and dressing applications.
Beverage applications command the largest share of volume throughput; confectionery claims the steepest expansion trajectory for natural extract substitution.
End User:
Channel control and minimum order constraints partition the market between direct-to-consumer agility and industrial scale procurement.
- Household:Home carbonation enthusiasts and DIY beverage makers purchasing through subscription curation platforms. United States metropolitan markets where appliance penetration exceeds 15% of households show concentrated adoption of personalized palate profiling and quarterly flavor rotations.
- Food Service:Restaurant and café bulk procurement with custom flavor profiling requirements.
- Retail:Supermarket and specialty store shelf-stable SKUs facing clean-label disclosure pressures.
- Industrial:Beverage and confectionery manufacturers with captive formulation partnerships and vertical integration into botanical sourcing.
Industrial end users absorb the bulk of installed capacity; household segments are gaining share fastest through direct-to-consumer platform expansion.
Flavor Profile:
Botanical sourcing geography and extraction method economics concentrate supply risk for premium natural profiles.
- Fruity:Citrus and berry extracts dominate volume, though Florida citrus greening disease and monsoon disruption in Southeast Asian processing clusters create input instability. Precision fermentation platforms are collapsing cost premiums for nature-identical alternatives.
- Savory:Umami and fermented notes for sauces and savory snacks.
- Spicy:Capsaicin and pungent extract systems for ethnic sauce and snack applications.
- Herbal:Botanical extracts for functional beverage positioning and adaptogenic claims.
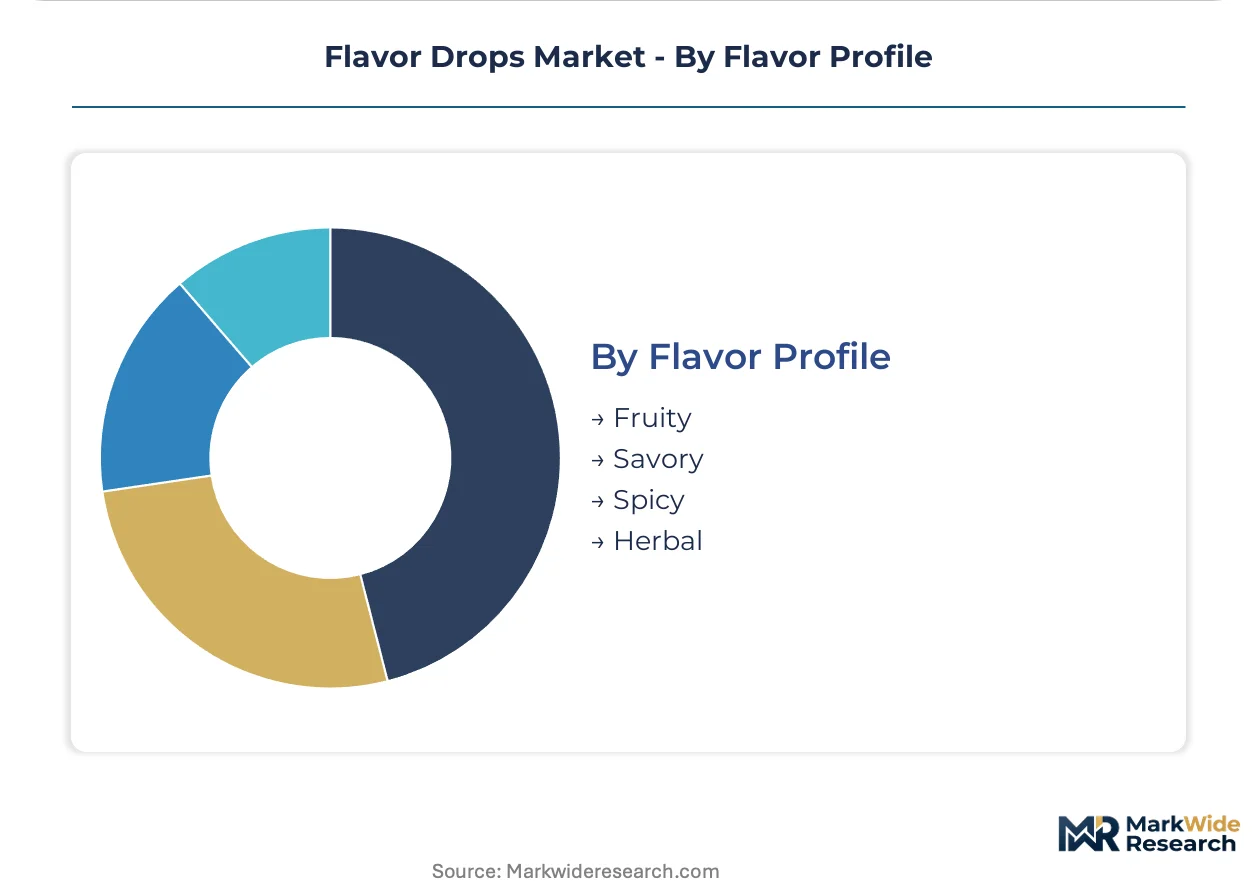
Fruity profiles absorb the bulk of installed capacity; herbal profiles are climbing the fastest on functional beverage demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madagascar vanilla bean harvests and Indonesian steam distillation capacity anchor supply-side geography for concentrated flavoring systems, while demand concentrates in markets with mature functional beverage infrastructure.
United States
Home carbonation appliance penetration exceeds 15% of metropolitan households, pulling concentrated dosing formats from industrial lines into kitchen settings. FDA oversight under 21 CFR 172 shapes formulation permissibility for clean-label claims. Greater Chicago and New Jersey corridor host beverage contract manufacturing clusters where pump-and-pour dispensing systems align with high-speed bottling economics.
Germany
Precision fermentation pilots for bioconverted vanilla and saffron aroma compounds are qualifying at industrial scale in Baden-Württemberg facilities. REACH compliance protocols and EFSA food contact material guidance tighten migration testing requirements for enzymatic processing aids. The Cologne-Düsseldorf industrial corridor concentrates flavor house technical centers serving carbonated soft drink and sports nutrition formulators.
China
SAMR's expanded flavor additive positive list opens formulation latitude for sports and energy drink applications previously restricted to synthetic options. Yangtze River Delta beverage manufacturers are integrating captive botanical sourcing to secure extract traceability for premium functional water positioning. Shanghai and Hangzhou host the fastest-growing direct-to-consumer flavor subscription platforms targeting home carbonation users.
Indonesia
Steam distillation capacity for clove, nutmeg, and tropical fruit extracts clusters in Java and Sumatra processing hubs. Monsoon disruption and port congestion at Tanjung Priok expose buyers to supply interruption risks for natural extract-dependent formats. Domestic processors are backward integrating into plantation ownership to secure substrate origin documentation for EFSA and FDA natural flavor claims.
Vietnam
Citrus and spice extract processing facilities in the Mekong Delta and Central Highlands serve European and North American flavor houses seeking alternatives to Chinese supply concentration. Tropical cyclone exposure and irrigation infrastructure gaps create harvest volatility for key botanical inputs. Da Nang and Ho Chi Minh City processing zones are upgrading enzymatic bioconversion capabilities to meet tightening natural extract purity specifications.
Flavor Drops Market Vendor Landscape
Strategic partnerships dominate the current landscape as mid-tier manufacturers seek captive botanical sourcing and formulation expertise to defend shelf presence against integrated rivals. The vendor base spans century-old confectionery concentrate specialists, direct-to-consumer platform operators, and sports nutrition brands with captive flavor development. Three archetypes define positioning: vertically integrated extract processors, direct-to-consumer subscription curators, and industrial-scale contract manufacturers. M&A activity and capacity expansion in Southeast Asian distillation facilities represent the dominant competitive vectors.
Within the heritage manufacturing tier, LorAnn Oils exemplifies century-scale production of confectionery-grade concentrates, while Capella Flavor Drops occupies a position in direct-to-consumer channel control for adjacent DIY segments. Beyond Water represents the sports nutrition vertical integration archetype, leveraging captive flavor formulation partnerships to secure consistent extract quality across hydration SKU ranges. These three anchors illustrate how competitive positioning splits between provenance storytelling, digital-native distribution, and backward integration into botanical supply.
| Leading Market Players |
|---|
| Beyond Water |
| My Protein |
| Flavorah |
| LorAnn Oils |
| Flavor West Manufacturing |
| Capella Flavor Drops |
| GymBeam |
| Prozis |
| SodaStream |
| Others |
Supply Flow & Price Mechanics
Madagascar vanilla bean futures and Indonesian clove spot indices cascade through flavor drop manufacturing tiers, compressing margins for mid-tier formulators while rewarding vertically integrated processors with captive botanical sourcing and provenance documentation premiums.
Pricing Analysis
Service bundling separates contract manufacturing tiers in this market, with formulation support and stability testing included in premium partnerships while economy buyers purchase unbundled concentrates without technical backing. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and extract origin documentation, with FDA natural flavor claims and EFSA enzymatic processing compliance commanding substantial uplifts. Cost compression in the standard tier is intensifying because precision fermentation platforms are collapsing historical premiums for botanical-derived vanillin and saffron aroma compounds. Industrial beverage manufacturers show lowest price sensitivity due to volume scale and formulation lock-in, while household direct-to-consumer subscribers exhibit highest elasticity to subscription pricing adjustments.
Supply Chain Analysis
Returns and quality disputes flow back through flavor house technical centers in Germany and the United States, where reformulation services and extract requalification absorb reverse-logistics costs into partnership pricing. Steam distillation capacity concentrates in Indonesia, Vietnam, and Madagascar, drawing from tropical botanical substrates vulnerable to monsoon disruption and harvest volatility. Raw material dependencies rest on vanilla beans, citrus peels, and spice oleoresins sourced through concentrated Southeast Asian processing clusters. Single-source vulnerability in the Java-Sumatra corridor exposes buyers to port congestion at Tanjung Priok and cyclone-related harvest interruptions. Distribution runs through beverage contract manufacturers in Greater Chicago and New Jersey, flavor house technical centers in Cologne-Düsseldorf, and direct-to-consumer subscription platforms in United States metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as clean-label formulation mandates from FDA and EFSA force synthetic-reliant mid-tier manufacturers toward expensive natural extract transitions or exit.
For Market Incumbents: Lock in captive botanical sourcing through plantation ownership or long-term offtake agreements in Indonesia and Madagascar before substrate traceability requirements harden into regulatory mandates. Deepen enzymatic bioconversion capabilities in Baden-Württemberg and New Jersey technical centers to defend positioning against precision fermentation entrants rewriting cost structures for high-value extracts. Priority levers include backward integration into clove and nutmeg plantation assets and preemptive SAMR compliance investment for China functional beverage expansion. For New Entrants and Emerging Players: Specialty coffee roasters seeking custom seasonal flavor profiling represent the most penetrable buyer archetype currently underserved by traditional flavor house minimum order constraints. Direct-to-brewer partnerships bypass incumbent volume thresholds and capture premium pricing for limited-release formulations. White-space targets include pharmaceutical bitter-masking applications at clinical-grade purity thresholds and China home carbonation subscription platforms in Shanghai and Hangzhou where appliance penetration is accelerating fastest. Go-to-market execution should emphasize digital-native palate profiling tools and quarterly flavor rotation curation. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier natural extract processors in Vietnam and Indonesia with installed distillation capacity but insufficient working capital to complete enzymatic bioconversion upgrades. Long-term viability over the five-to-ten year horizon hinges on securing EFSA-compliant substrate origin documentation and FDA natural flavor claim substantiation. Acquisition targets should demonstrate captive plantation relationships or precision fermentation partnerships. The signal to watch is EFSA enforcement action on enzymatic processing aid migration testing, which will accelerate substitution demand and consolidate share toward compliant processors.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Plantation Acquisition | Backward integration into Madagascar vanilla and Indonesian clove estates secures substrate traceability for FDA and EFSA natural flavor claims. |
| Enzymatic Bioconversion Scale-Up | Baden-Württemberg and New Jersey facility upgrades defend margin positioning against precision fermentation cost compression. |
| SAMR Pre-Compliance Investment | Early alignment with China's expanded flavor additive positive list captures functional beverage formulation latitude ahead of competitors. |
| Direct-to-Brewer Channel Launch | Specialty coffee roasting partnerships bypass traditional flavor house minimums and capture premium seasonal release pricing. |
| Pharmaceutical Masking Partnership | Clinical-grade purity thresholds for pediatric and geriatric liquid medications open adjacent demand beyond food and beverage applications. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with flavor chemists, beverage formulation directors, botanical procurement managers, and sports nutrition brand managers. FEMA GRAS determinations, FDA 21 CFR 172 submissions, EFSA food contact material guidance, and SAMR national food safety standards provided regulatory validation. Bottom-up modeling triangulated against top-down trade flow analysis and production capacity surveys across Southeast Asian distillation facilities.
Segmentation granularity extended to liquid versus powder versus syrup drop formats, beverage versus confectionery versus pharmaceutical applications, and household versus industrial end-user channels across the analysis window. CAGRs derived from installed capacity expansion timelines, appliance penetration curves for home carbonation systems, and substitution elasticity estimates for natural versus synthetic flavoring systems. Precision fermentation pilot scale-up trajectories and enzymatic extraction yield improvements informed technology-driven cost compression assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA-FDA natural flavor definition divergence, Madagascar vanilla harvest volatility, and precision fermentation platform commercialization timelines. Practitioners should monitor EFSA enforcement windows for enzymatic processing aid documentation, SodaStream household penetration rates in United States metropolitan markets, and SAMR flavor additive list revisions for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Natural Food Colors Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Smoke Flavorings Market
Flavorings and Food Additives
Vanilla Bean Market
Flavorings and Food Additives
American Spikenard Extract Market
Flavorings and Food Additives
All-Natural Flavors System Market
Flavorings and Food Additives
Pine Bark Extract Market
Flavorings and Food Additives
Citrus Extract Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Botanical Flavors Market
Flavorings and Food Additives
Natural Food Colors and Flavors Market
Flavorings and Food Additives
Global Paprika Oleoresin Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market