
 Pumpkin Spice Products Market | 2026-2036
Pumpkin Spice Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pumpkin Spice Products Market Analytics
Seasonal subscription boxes and loyalty-program early-access releases is restructuring how pumpkin spice SKUs reach consumers before traditional retail windows. Starbucks Corporation leverages its mobile-order ecosystem to lock in repeat seasonal purchases. McCormick & Company, Inc. anchors the grocery channel with spice blends that command shelf space from August through December. Nestlé S.A. extends its manufacturing scale into co-branded creamer and beverage lines that compete for refrigerated case placement.
Pumpkin spice products encompass flavor-infused consumer goods combining cinnamon, nutmeg, ginger, clove, and pumpkin-derived compounds for sensory-driven seasonal consumption. These formulations rely on oleoresin extraction and spray-drying processes to preserve volatile aromatic compounds through shelf-stable distribution. Coffee and creamers within the product type segment capture the highest margin pools due to beverage repeat-purchase behavior and premium pricing tolerance. Seasonal promotions within the application dimension now generate concentrated revenue windows that compress inventory risk into predictable eight-week cycles. E-commerce channels for customer types including individuals and cafés are growing fastest as direct-to-consumer sampling replaces traditional in-aisle discovery.
The FDA governs flavor ingredient disclosure under FEMA GRAS determinations, while the USDA oversees organic certification claims that premium pumpkin spice labels increasingly pursue. State-level cottage food laws in California and New York additionally shape how small-batch producers access retail and food service channels. Stakeholders must monitor how clean-label enforcement and supply chain documentation requirements reshape supplier qualification criteria ahead of each seasonal production cycle.
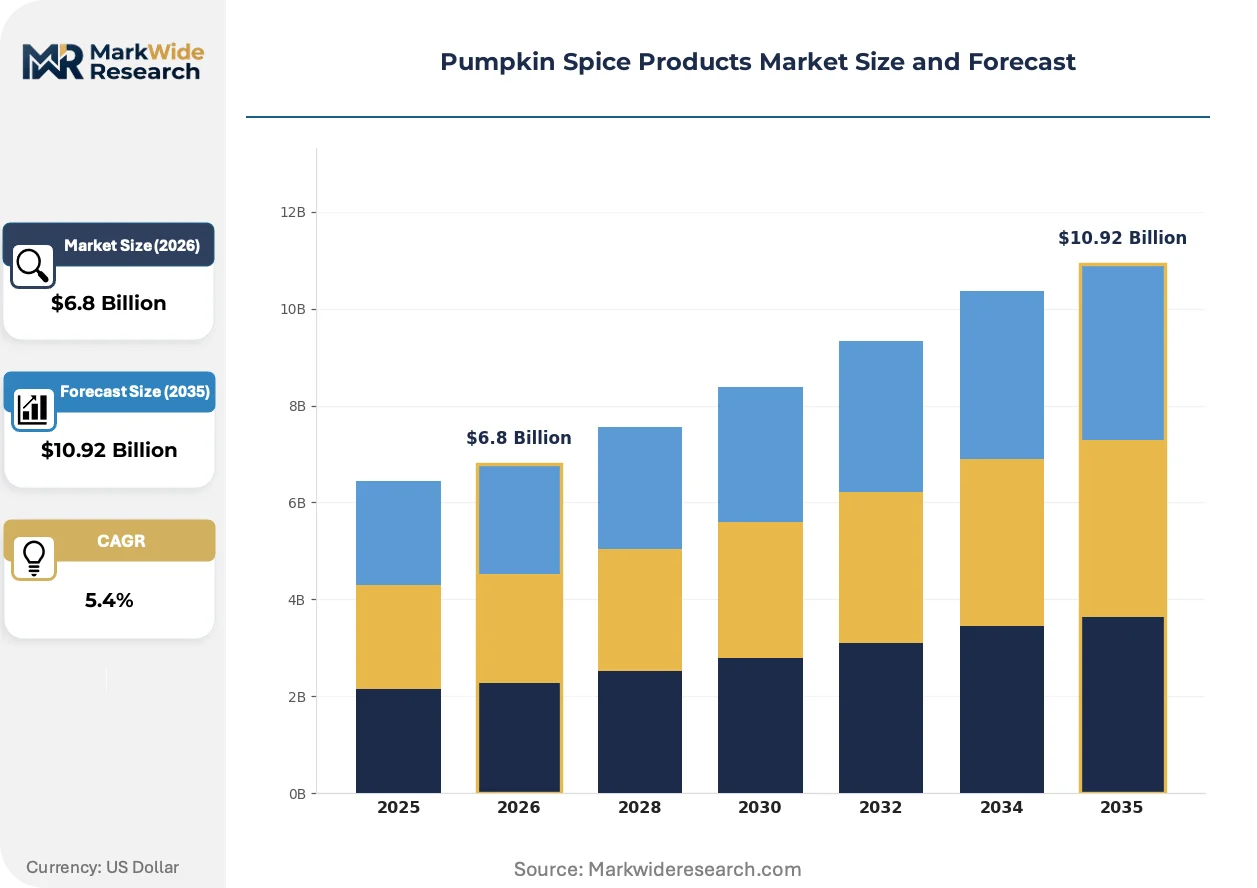
Market Dynamics
Seasonal compression of purchasing windows is forcing pumpkin spice suppliers to front-load manufacturing capacity before August, creating inventory risk that reshapes working capital requirements across the flavor supply chain.
Growth Catalysts
- FEMA GRAS flavor determinations:The FDA's streamlined approval pathway for cinnamon, nutmeg, and clove oleoresins accelerates new product formulation cycles for beverage and bakery applications.
- Specialty coffee chains:Mobile-order ecosystems and loyalty-program early access is locking in repeat seasonal purchases before traditional retail windows open.
- Spray-drying technology:Advanced encapsulation processes preserve volatile aromatic compounds through extended shelf-stable distribution, enabling direct-to-consumer channels.
Market Restraints
- Vanilla price volatility:Madagascar and Indonesian vanilla bean harvest fluctuations create input cost instability for blended spice formulations.
- Indonesian clove supply concentration:Geographic clustering of clove production exposes processors to weather-driven harvest disruptions and export quota restrictions.
- Eight-week revenue concentration:Compressed seasonal demand windows generate working capital intensity and inventory obsolescence risk for small-batch producers.
Strategic Opportunities
- Clean-label certification:USDA organic and non-GMO verification programs command premium shelf placement and pricing tolerance in Northeast urban corridors.
- Co-manufacturing partnerships:Refrigerated case placement for creamer and beverage lines leverages existing dairy processor infrastructure without greenfield capex.
- Subscription box channels:Curated seasonal sampling replaces in-aisle discovery for younger demographics, building year-round brand engagement beyond peak autumn months.
Industry Challenges
- Flavor chemist talent scarcity:Specialized expertise in oleoresin extraction and volatile compound stabilization commands premium compensation, constraining mid-tier producer R&D capacity.
- Dual jurisdiction compliance:State-level cottage food laws in California and New York create fragmented qualification criteria that complicate multi-state retail and food service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pumpkin Spice Products Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Candles, Coffee, Cookies, Creamers Application: Food Service, Retail, E-commerce, Seasonal Promotions Packaging Type: Bottles, Jars, Bags, Tins Customer Type: Individuals, Restaurants, Cafés, Bakeries |
| Companies Covered | McCormick & Company, Inc., Spice Islands, Starbucks Corporation, Frontier Co-op, Rodelle, The Kraft Heinz Company, Dunkin’ Donuts, Libby's, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pumpkin Spice Products Market Evolving Landscape
Formulation transparency and supply chain documentation are reshaping competitive qualification criteria, while extraction technology advances compress production timelines for seasonal launches.
Encapsulation technology is expanding into pumpkin spice applications through micro-encapsulation of volatile aromatic compounds. Beverage manufacturers and ready-to-drink coffee brands are adopting these spray-dried formats at accelerating rates for extended shelf-life claims. This diffusion is expanding into premium single-serve creamer segments that previously relied on liquid concentrate distribution.
Clean-label enforcement under FDA flavor ingredient disclosure requirements is tightening documentation standards for natural versus artificial flavor claims. The industrial consequence is supplier qualification audits that now require batch-level traceability back to oleoresin extraction facilities. Bakery and confectionery segments in the Pacific Northwest urban corridors are responding fastest by reformulating around certified organic spice blends.
Direct-to-consumer sampling through curated subscription channels is displacing traditional supermarket aisle discovery for younger demographics. Food service distributors and independent cafés are sourcing through e-commerce platforms that offer smaller minimum order quantities and faster turnaround than legacy broadline distributors. This behavioral shift concentrates most visibly in Northeast metropolitan markets where seasonal menu turnover cycles compress ordering lead times.
Pumpkin Spice Products Market Segmentation
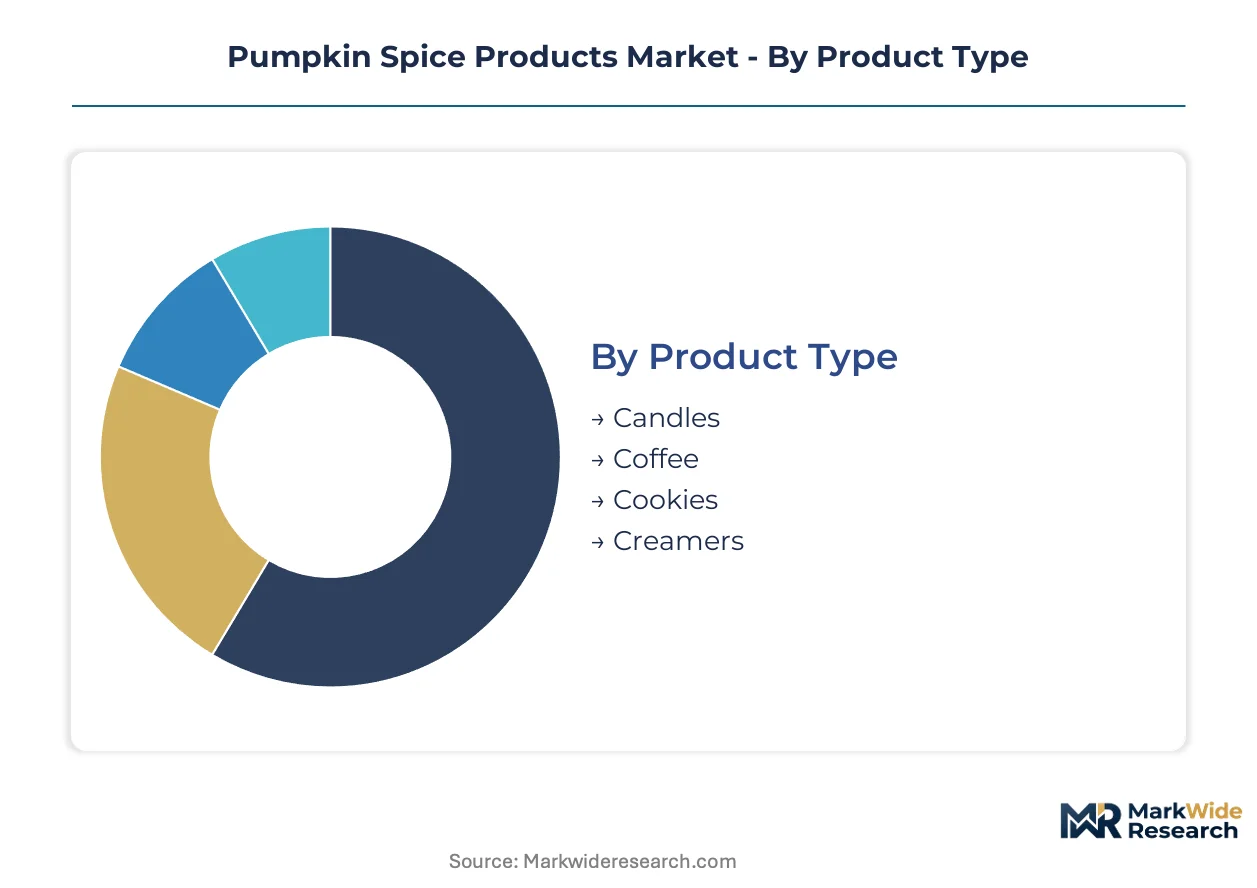
Pumpkin spice procurement patterns diverge sharply across product formats and channel structures. Understanding these fault lines exposes where FDA flavor disclosure rules apply versus where cottage food exemptions create regulatory arbitrage.
Product Type:
FDA FEMA GRAS determinations govern oleoresin formulations in ingestible categories, while candles fall under EPA and state-level air quality jurisdictions with lighter documentation burdens.
- Coffee:Roasted whole bean and ground formats incorporate spray-dried pumpkin spice coatings that preserve volatile aromatic compounds through distribution. Specialty coffee chains in the Northeast urban corridors command premium shelf placement for single-origin pumpkin spice blends during compressed eight-week seasonal windows.
- Creamers:Refrigerated liquid and shelf-stable powder formats require dual USDA dairy inspection and FDA flavor additive compliance. Co-manufacturing partnerships with existing dairy processors dominate this segment due to capital-intensive cold-chain infrastructure requirements.
- Candles:Soy and paraffin wax bases carry pumpkin spice fragrance loads without food-grade certification constraints. Pacific Northwest consumers drive demand for clean-burning soy alternatives with essential oil-based scent formulations.
- Cookies:Packaged baked goods face USDA organic certification audits and state-level cottage food law fragmentation when produced by small-batch manufacturers. Clean-label reformulation pressures concentrate in Northeast metropolitan markets.
Leading the category by volume: Coffee. Growing fastest: Creamers.
Application:
Channel selection dictates inventory risk profile, with food service and e-commerce exhibiting opposing working capital intensity patterns.
- Food Service:Independent cafés and bakery chains source through broadline distributors with concentrated seasonal procurement calendars. Mobile-order ecosystem integration at specialty coffee chains compresses lead times to four-week windows.
- Retail:Grocery channel placement from August through December requires slotting fee commitments and promotional calendar alignment. McCormick & Company anchors this channel with spice blend shelf space dominance.
- E-commerce:Direct-to-consumer sampling replaces in-aisle discovery for younger demographics, enabling smaller minimum order quantities than legacy distribution. Subscription box curation builds year-round brand engagement beyond peak autumn months.
- Seasonal Promotions:Limited-time offers generate concentrated revenue windows that compress inventory obsolescence risk into predictable cycles. Starbucks Corporation leverages loyalty-program early access to lock in repeat purchases before traditional retail windows open.
Food Service captures the steepest expansion trajectory as independent cafés accelerate menu turnover frequency.
Packaging Type:
Format selection correlates with shelf-life requirements and supply chain documentation standards for volatile compound preservation.
- Bottles:Glass and PET containers for liquid creamers and ready-to-drink beverages require refrigerated case placement and extended label disclosure under FDA flavor ingredient rules.
- Jars:Wide-mouth glass formats dominate candle and premium spice blend segments, supporting visual merchandising and reuse value propositions in retail environments.
- Bags:Flexible packaging for ground coffee and cookies enables modified atmosphere preservation of aromatic compounds through multi-layer barrier films.
- Tins:Metal canisters command premium positioning for gift-oriented candle and cookie assortments, particularly in Northeast urban corridor seasonal displays.
Bags lead by unit volume. Jars gain share fastest on premium positioning strength.
Customer Type:
Procurement scale and specification rigor separate individual consumers from commercial food service operators.
- Individuals:Direct-to-consumer channels and retail procurement dominate, with subscription box sampling displacing supermarket discovery for millennial and Gen-Z demographics.
- Restaurants:Full-service operators source pumpkin spice ingredients through food service distributors with quarterly menu planning cycles and batch-level traceability requirements.
- Cafés:Specialty coffee chains and independent espresso bars drive highest-margin procurement through mobile-order ecosystem integration and loyalty-program lock-in.
- Bakeries:Small-batch producers navigate California and New York cottage food law fragmentation to access retail and food service channels, facing dual jurisdiction compliance burdens.
Cafés lead by revenue per transaction. Individuals expand most quickly through e-commerce channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors pumpkin spice product innovation through Starbucks Corporation's mobile-order ecosystem and Pacific Northwest consumer preference for premium single-origin formulations.
United States
Specialty coffee chains and bakeries in the Northeast urban corridors drive concentrated seasonal procurement volumes. The FDA's FEMA GRAS determinations govern oleoresin extraction standards for cinnamon and clove formulations. Pacific Northwest metropolitan markets exhibit fastest clean-label adoption rates for USDA organic certified spice blends.
Germany
European bakery chains and confectionery manufacturers source pumpkin spice formulations for autumn seasonal product lines. EFSA flavor ingredient assessments align with EU clean-label enforcement trends. Bavaria's food processing clusters concentrate R&D investment in natural flavor extraction technologies.
United Kingdom
Coffee shop chains and premium grocery retailers expand pumpkin spice SKU ranges during compressed eight-week seasonal windows. UK Food Standards Agency labeling requirements mirror EU transparency mandates for natural versus artificial flavor claims. London metropolitan area dominates e-commerce subscription box penetration for direct-to-consumer spice sampling.
Canada
Food service distributors and independent cafés accelerate menu turnover frequency for autumn limited-time offerings. Health Canada flavor additive regulations require disclosure thresholds comparable to FDA standards. Ontario's dairy processing infrastructure supports co-manufacturing partnerships for refrigerated creamer production.
Japan
Convenience store chains and specialty coffee retailers integrate pumpkin spice variants into seasonal beverage rotations. METI food labeling standards enforce strict origin documentation for imported spice components. Tokyo metropolitan area concentrates demand for premium gift-oriented tin packaging formats.
Pumpkin Spice Products Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the pumpkin spice value chain. The market exhibits tiered consolidation with multinational flavor houses anchoring grocery shelf space while specialty roasters capture premium coffee segment margins. Three archetypes dominate: vertically integrated spice processors with extraction capabilities, beverage-focused brands with direct consumer channel control, and co-manufacturing specialists leveraging third-party dairy infrastructure. Competitive intensity centers on clean-label certification acquisition and seasonal production cycle compression.
Within the multinational flavor house tier, McCormick & Company, Inc. and Nestlé S.A. occupy positions defined by manufacturing scale and refrigerated distribution reach. Starbucks Corporation exemplifies the beverage-centric archetype through mobile-order ecosystem integration. Frontier Co-op represents the cooperative sourcing model with direct farmer relationships.
| Leading Market Players |
|---|
| McCormick & Company, Inc. |
| Spice Islands |
| Starbucks Corporation |
| Frontier Co-op |
| Rodelle |
| The Kraft Heinz Company |
| Dunkin' Donuts |
| Libby's |
| Nestlé S.A. |
| Others |
Value Network & Pricing Analysis
Madagascar vanilla bean harvest fluctuations transmit cost volatility through blended spice formulations into three-tier pricing structures across premium organic, standard commercial, and private-label economy tiers. Indonesian clove supply concentration amplifies this input cost sensitivity for mid-tier producers lacking backward integration into oleoresin extraction facilities.
Pricing Analysis
Value-based pricing anchored to USDA organic certification commands shelf placement premiums in Northeast urban corridors where clean-label tolerance peaks. Pricing stratifies across certified organic, natural flavor, and artificial compound tiers based on batch-level traceability depth and FEMA GRAS documentation rigor. Cost compression in the artificial tier intensifies as private-label entrants erode margin pools previously protected by seasonal scarcity. Independent cafés exhibit highest price sensitivity due to compressed eight-week procurement windows, while specialty coffee chains absorb premium tiers through loyalty-program lock-in.
Supply Chain Analysis
Flavor chemist talent scarcity in Indonesia, Madagascar, and the United States constrains oleoresin extraction capacity expansion ahead of seasonal production ramps. Clove sourcing from Indonesian archipelago regions, vanilla from Madagascar and Papua New Guinea, and cinnamon from Sri Lankan and Vietnamese plantations creates geographic dispersion that feeds into spray-drying encapsulation facilities. Single-source vulnerability in Indonesian clove harvests exposes processors to export quota disruptions and weather-driven yield volatility. Distribution runs through refrigerated dairy infrastructure for creamer formats and ambient broadline networks for shelf-stable spice blends.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA FEMA GRAS flavor determinations erect compliance moats that favor capitalized incumbents with dedicated regulatory affairs infrastructure over cottage food law-restricted small-batch competitors.
For Market Incumbents: Anticipate clean-label enforcement tightening by securing USDA organic certification across entire SKU ranges before audit backlogs extend qualification timelines. Acquire oleoresin extraction capabilities or captive supply agreements with Indonesian and Sri Lankan processors to defend margin position against vanilla price volatility. Channel control through mobile-order ecosystem integration at specialty coffee chains represents the priority defensive lever against direct-to-consumer subscription entrants. For New Entrants and Emerging Players: California cottage food law amendments opening retail access for home kitchen producers create a window for small-batch spice blend differentiation through hyperlocal sourcing narratives. White-space concentrates in Pacific Northwest urban corridors where clean-burning soy candle demand outpaces essential oil supply chain maturity. Target e-commerce subscription box channels with curated autumn sampling formats that bypass slotting fee barriers blocking grocery retail entry. For Investors and Strategic Acquirers: Accelerating co-manufacturing partnership announcements between dairy processors and beverage brands is the leading indicator that refrigerated creamer segment consolidation is imminent. Five-to-ten-year viability favors vertically integrated spice processors with captive extraction infrastructure over asset-light brand designers dependent on third-party oleoresin supply. Watch for FDA batch-level traceability enforcement actions as the signal triggering distressed acquisition opportunities among documentation-deficient mid-tier producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleoresin Extraction | Captive supply from Indonesian clove and Sri Lankan cinnamon processors insulates margin from commodity volatility. |
| USDA Organic Certification Program | Premium shelf placement in Northeast urban corridors commands pricing tolerance exceeding standard tier benchmarks. |
| Co-Manufacturing Partnership with Dairy Processors | Refrigerated case placement for creamer lines leverages existing cold-chain infrastructure without greenfield capex. |
| Direct-to-Consumer Subscription Launch | Curated seasonal sampling displaces supermarket discovery for millennial demographics and builds year-round engagement. |
| Mobile-Order Ecosystem Integration | Loyalty-program early access at specialty coffee chains locks repeat purchases before traditional retail windows open. |
Research Methodology
Document review covered FDA FEMA GRAS determinations, USDA organic certification databases, and state-level cottage food law filings, complemented by interviews with flavor chemists at oleoresin extraction facilities, procurement directors at specialty coffee chains, category buyers at Northeast grocery retailers, and regulatory affairs leads at multinational spice houses. Secondary validation drew from customs import records for vanilla and clove shipments, SEC 10-K filings of publicly traded flavor houses, and Nielsen retail audit data for seasonal spice category performance. Bottom-up SKU-level buildups and top-down market sizing triangulated volume and value estimates.
Segment-level outputs across product type, application, packaging format, and customer type dimensions were generated through structured modeling across the projection horizon. CAGRs were derived from historical growth pattern analysis adjusted for seasonal compression effects and clean-label adoption curve assumptions. Forecast inputs incorporated spray-drying technology diffusion rates, mobile-order ecosystem penetration at specialty coffee chains, and subscription box channel growth trajectories.
The model assumes a particular technology adoption path for micro-encapsulation of volatile aromatic compounds; alternative pathways for solvent-based extraction would alter the outlook for shelf-life extension claims and clean-label positioning. Material deviation in FDA enforcement intensity for batch-level traceability or Indonesian export quota restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Fenchol Market
Flavorings and Food Additives
Roast Flavoring Market
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Original and Flavored Syrup Market
Flavorings and Food Additives
Culinary Essence Market
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
Grapefruit Oil Market
Flavorings and Food Additives
Citrus Extract Market
Flavorings and Food Additives
Carotenoids Pigment Market
Flavorings and Food Additives
Food Grade Menthol Crystal Market
Flavorings and Food Additives
United States Food Flavor and Enhancer Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Cholic Acid Market