
 Egypt Food Flavor and Enhancer Market | 2026-2036
Egypt Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Food Flavor and Enhancer Market Foresight
Multi-sourced procurement of flavor compounds is shifting toward consolidated supplier relationships among Egyptian food manufacturers. Givaudan SA leverages its regional technical service centers to secure formulation partnerships with local processors. Cargill anchors its position through backward integration into agricultural feedstock sourcing across the Nile Delta. BASF SE competes on synthetic molecule consistency for cost-sensitive beverage applications.
Food flavor and enhancer systems comprise volatile aromatic compounds, taste-active molecules, and modulators engineered to intensify sensory perception in processed foods; these formulations typically specify purity thresholds, heat stability parameters, and solubility profiles to survive industrial processing conditions. Their primary commercial purpose centers on standardizing taste experiences across production batches while masking off-notes from functional ingredients like proteins or fortificants. Natural flavors command premium positioning as Egyptian consumers associate clean labels with safety, though artificial flavors still dominate volume in mass-market beverages where cost constraints govern procurement decisions. Dairy applications represent an emerging margin pool, with yogurt and cheese processors seeking customized flavor systems that differentiate against imported regional brands.
Egypt's national food safety regulator enforces additive maximum limits and labeling disclosures that directly determine which enhancer chemistries gain market access. Compliance with CODEX-aligned standards shapes import eligibility for international suppliers while local manufacturers adapt formulations to avoid reformulation costs. FSSAI-equivalent local certification requirements for new flavor substances create approval timelines that influence product pipeline planning. Stakeholders must monitor pending updates to Egypt's food additive positive list, as expansion or restriction of specific enhancer categories would immediately redirect R&D investment and supplier qualification efforts across the value chain.
Market Dynamics
Consolidated supplier relationships are compressing procurement cycles across Egypt's food processing corridor, with technical service proximity now outweighing price arbitrage in vendor selection criteria.
Growth Catalysts
- Nile Delta Agricultural Feedstock Expansion:Backward integration into local vanilla and citrus cultivation reduces import dependency for natural flavor precursors. Egyptian processors secure supply continuity through contract farming arrangements with Delta cooperatives.
- CODEX-Aligned Additive Positive List Expansion:Egypt's national food safety authority has streamlined approval pathways for enzymatic flavor modulators. This regulatory clarity accelerates product pipeline commercialization for both domestic and international suppliers.
- Heat-Stable Encapsulation Technology:Advanced spray-drying and lipid-coating systems enable flavor survival in UHT dairy and extruded snack applications. Local dairy processors adopt these systems to differentiate against regional import competition.
Market Restraints
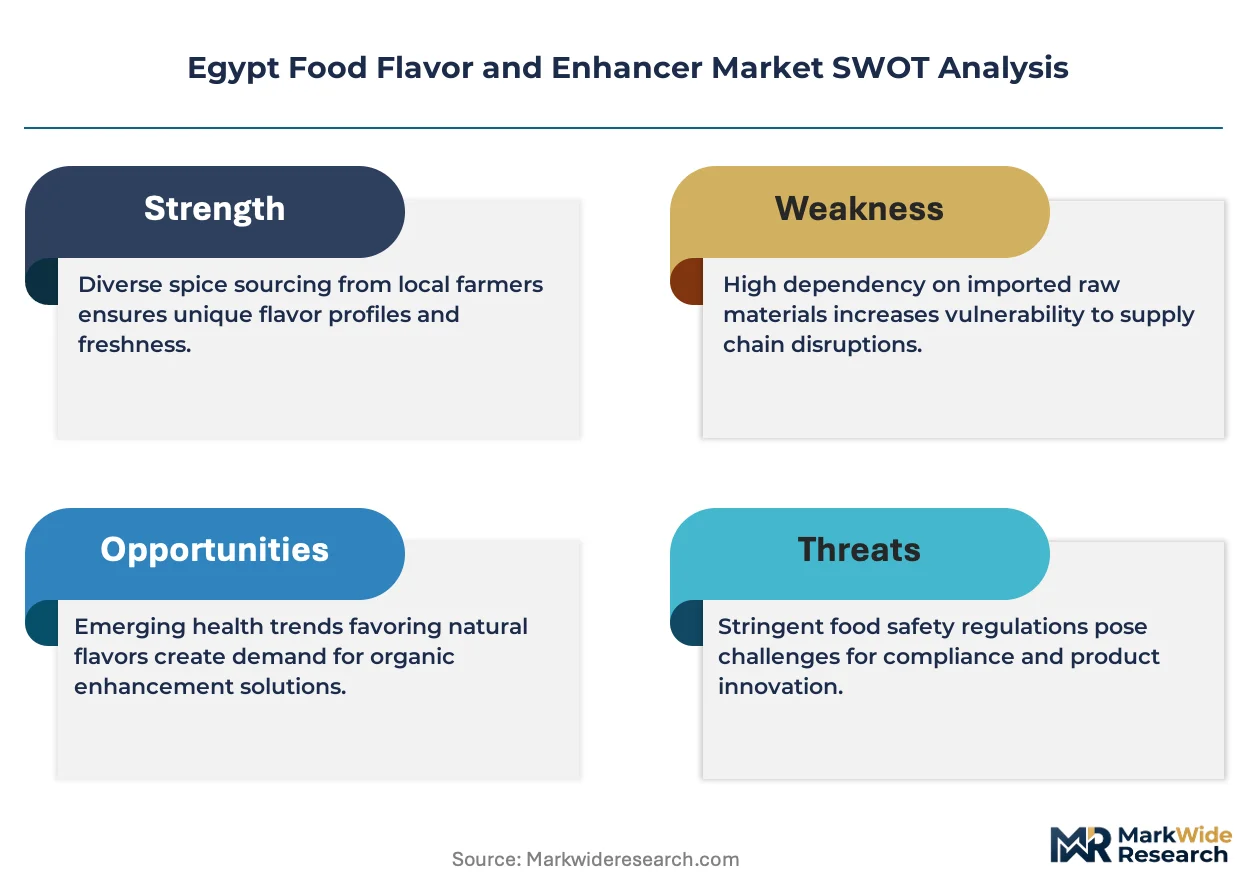
- Synthetic Aromatic Compound Import Concentration:Seventy percent of artificial flavor precursors enter through Alexandria Port, creating single-point vulnerability. Currency volatility directly amplifies formulation cost instability for mass-market beverage producers.
- FSSAI-Equivalent Certification Timelines:Novel flavor substance approvals require eighteen-to-twenty-four-month safety dossier reviews. This regulatory friction delays innovation launch windows and elevates compliance overhead for reformulation cycles.
- Natural Extract Yield Variability:Climate stress on Egyptian mint and chamomile harvests generates batch-to-batch aromatic inconsistency. Clean-label positioning demands absorb margin compression from quality control redundancy.
Strategic Opportunities
- Upper Egypt Dairy Processing Corridor:Underpenetrated yogurt and cheese manufacturing in Sohag and Qena governorates presents greenfield flavor system partnerships. Regional processors seek turnkey formulation support to compete with Greater Cairo brands.
- E-Commerce Direct-to-Processor Channels:Digital procurement platforms bypass traditional distributor markups for mid-scale snack manufacturers. Alibaba-sourced flavor compound marketplaces gain traction among cost-conscious importers.
- Clean-Label Enzymatic Modulators:Consumer safety associations drive preference for fermentation-derived taste enhancers over synthetic alternatives. Regulatory tailwinds favor "natural flavor" label claims that command shelf price premiums.
Industry Challenges
- Flavor Chemist Talent Scarcity:Formulation expertise for heat-stable dairy applications concentrates among retiring veterans at state research institutes. Knowledge transfer gaps threaten continuity in customized savory system development.
- Legacy ERP Integration Friction:Batch traceability requirements under updated labeling standards clash with decades-old inventory systems at family-owned processing plants. Digital upgrade capex competes with working capital needs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Food Flavor and Enhancer Market |
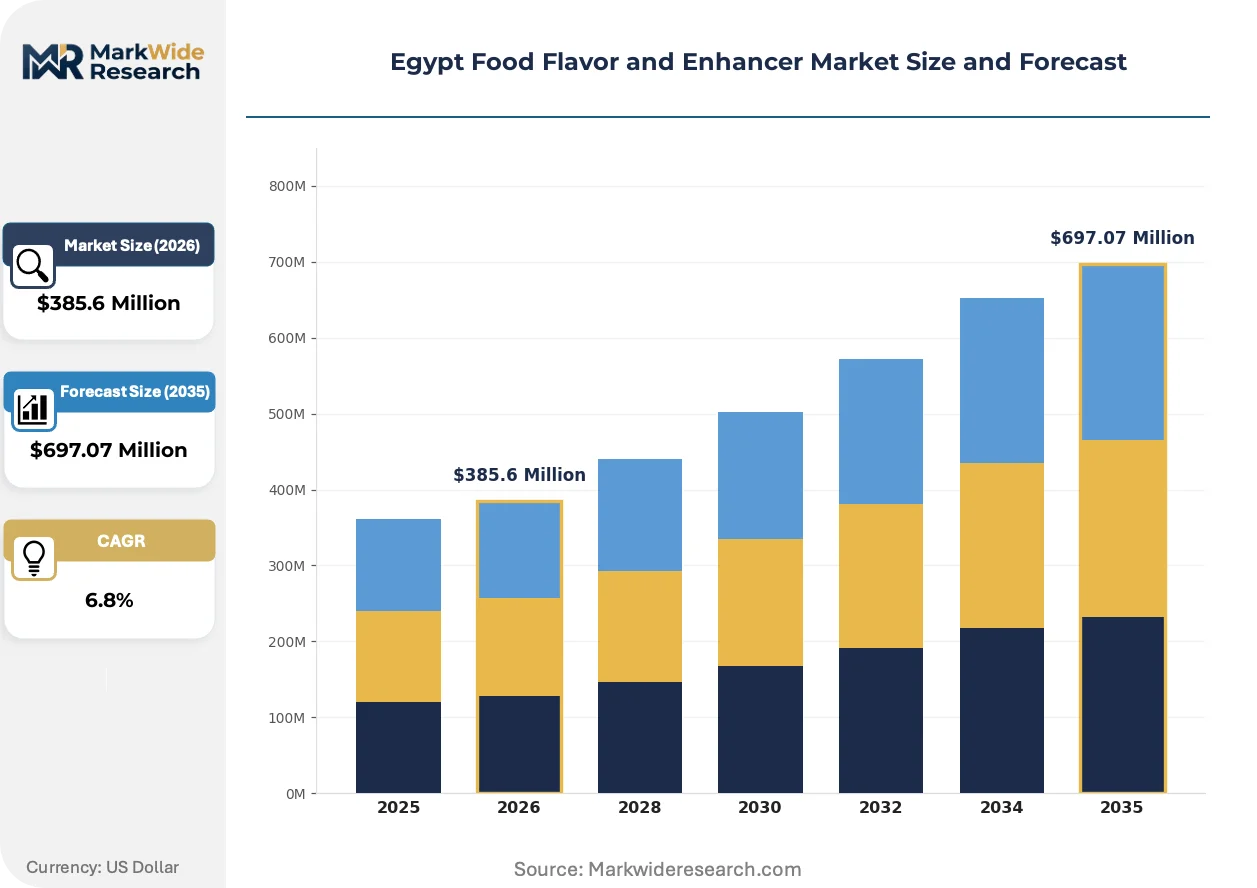
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Seasonings, Flavor Enhancers Application: Beverages, Bakery, Snacks, Dairy Products End User: Food Manufacturers, Restaurants, Catering Services, Retail Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Archer Daniels Midland Company, DuPont de Nemours, Inc., Givaudan SA, Cargill, BASF SE, International Flavors & Fragrances Inc., Symrise AG, Sensient Technologies Corporation, DSM-Firmenich, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Food Flavor and Enhancer Market Shifts & Advancements
Active reformulation cycles are compressing product development timelines, with sensory standardization and regulatory compliance now running in parallel rather than sequential workflows.
Microencapsulation technology is modularizing flavor delivery architectures across Egypt's snack and dairy sectors. Extruded corn and wheat manufacturers adopt lipid-matrix shell systems to preserve volatile top-notes through high-temperature processing. This modularizing capability enables regional processors to replicate imported product sensory profiles without proprietary foreign formulation licenses.
Egypt's national food safety authority has implemented additive maximum limit revisions aligned with CODEX Alimentarius frameworks. The tightened disclosure requirements force reformulation of legacy beverage enhancers containing cyclamate blends. Mass-market soft drink bottlers in Greater Cairo now accelerate clean-label transitions to avoid packaging write-downs.
Direct technical service engagements are displacing traditional distributor intermediaries in procurement workflows. Mid-scale dairy processors in 10th of Ramadan City now contract flavor houses for on-site pilot trials rather than accepting standard catalog offerings. This behavioral shift concentrates supplier relationships around formulation partnership depth rather than volume discount leverage.
Egypt Food Flavor and Enhancer Market Segmentation
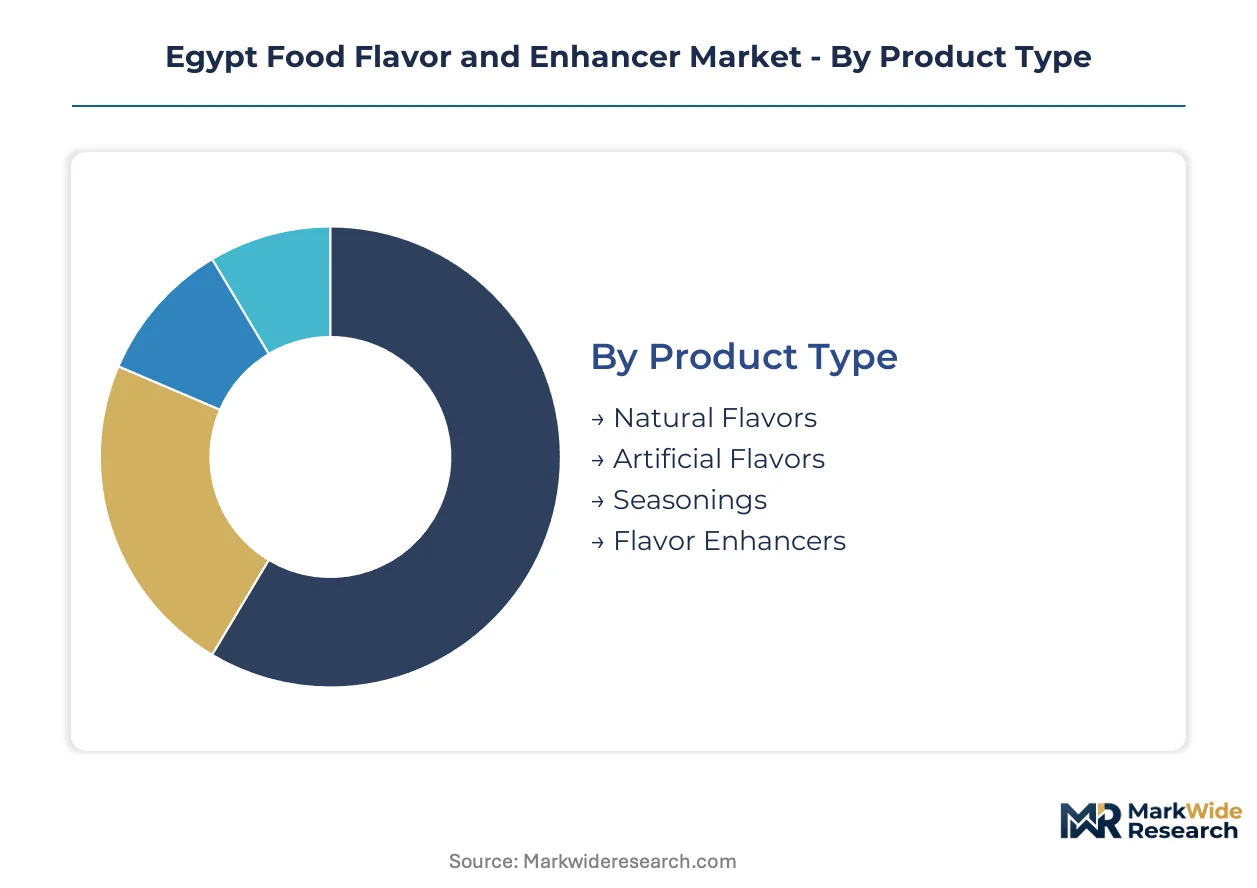
Egypt's food flavor and enhancer market segments along four distinct axes that determine procurement behavior and margin capture. Product type differentiation separates clean-label premiums from mass-market volume plays. Application concentration in Greater Cairo's processing corridor shapes regional supplier qualification priorities.
Product Type:
Supply concentration for flavor precursors varies sharply across extraction methods and synthesis pathways, dictating which Egyptian processors can secure reliable feedstock.
- Natural Flavors:Volatile aromatic compounds derived from Egyptian citrus, mint, and vanilla cultivation in the Nile Delta. Clean-label positioning commands shelf price premiums as consumer safety associations drive preference for extraction-based ingredients over synthetic alternatives. Greater Cairo dairy processors absorb the bulk of supply for yogurt differentiation against regional imports.
- Artificial Flavors:Synthetic aromatic molecules engineered for batch-to-batch consistency in cost-sensitive applications. Seventy percent of precursors enter through Alexandria Port, creating currency-amplified cost instability for mass-market beverage bottlers. Heat-stable encapsulation systems enable survival in UHT processing conditions.
- Seasonings:Spice and herb blends standardized for industrial food manufacturing scale.
- Flavor Enhancers:Taste-active modulators including nucleotides and amino acid derivatives regulated under CODEX-aligned maximum limits.
Artificial flavors absorb the bulk of installed capacity; natural flavors are expanding most quickly.
Application:
Cost tier stratification separates premium formulation partnerships from catalog-based commodity procurement across Egypt's food processing corridor.
- Beverages:Mass-market soft drink bottlers dominate volume demand for synthetic enhancers, with cyclamate blend reformulation accelerating under tightened disclosure requirements. UHT dairy drinks adopt lipid-matrix encapsulation to preserve volatile top-notes through sterilization.
- Dairy Products:Yogurt and cheese processors in 10th of Ramadan City seek customized flavor systems for regional brand competition. Direct technical service engagements now displace traditional distributor intermediaries for on-site pilot trials.
- Bakery:Heat-stable vanilla and butter flavor systems for industrial bread and pastry manufacturing.
- Snacks:Extruded corn and wheat applications requiring spray-dried encapsulation for high-temperature processing survival.
Beverages absorb the bulk of installed capacity; dairy products are gaining share fastest.
End User:
Customer type determines technical service intensity and formulation customization depth in procurement relationships.
- Food Manufacturers:Consolidated supplier relationships now compress procurement cycles, with proximity of regional technical service centers outweighing price arbitrage in vendor selection. Mid-scale processors in 10th of Ramadan City prioritize turnkey formulation support over volume discounts.
- Restaurants:Foodservice operators in Greater Cairo's hospitality corridor demand standardized seasoning blends for menu consistency across outlet networks.
- Catering Services:Bulk procurement of cost-optimized flavor systems for institutional feeding contracts.
- Retail:Private-label snack and dairy brands seeking clean-label positioning for supermarket shelf placement.
Food manufacturers absorb the bulk of installed capacity; restaurants are climbing the fastest.
Distribution Channel:
Channel maturity separates legacy inventory systems from digital procurement platforms in Egypt's flavor compound marketplace.
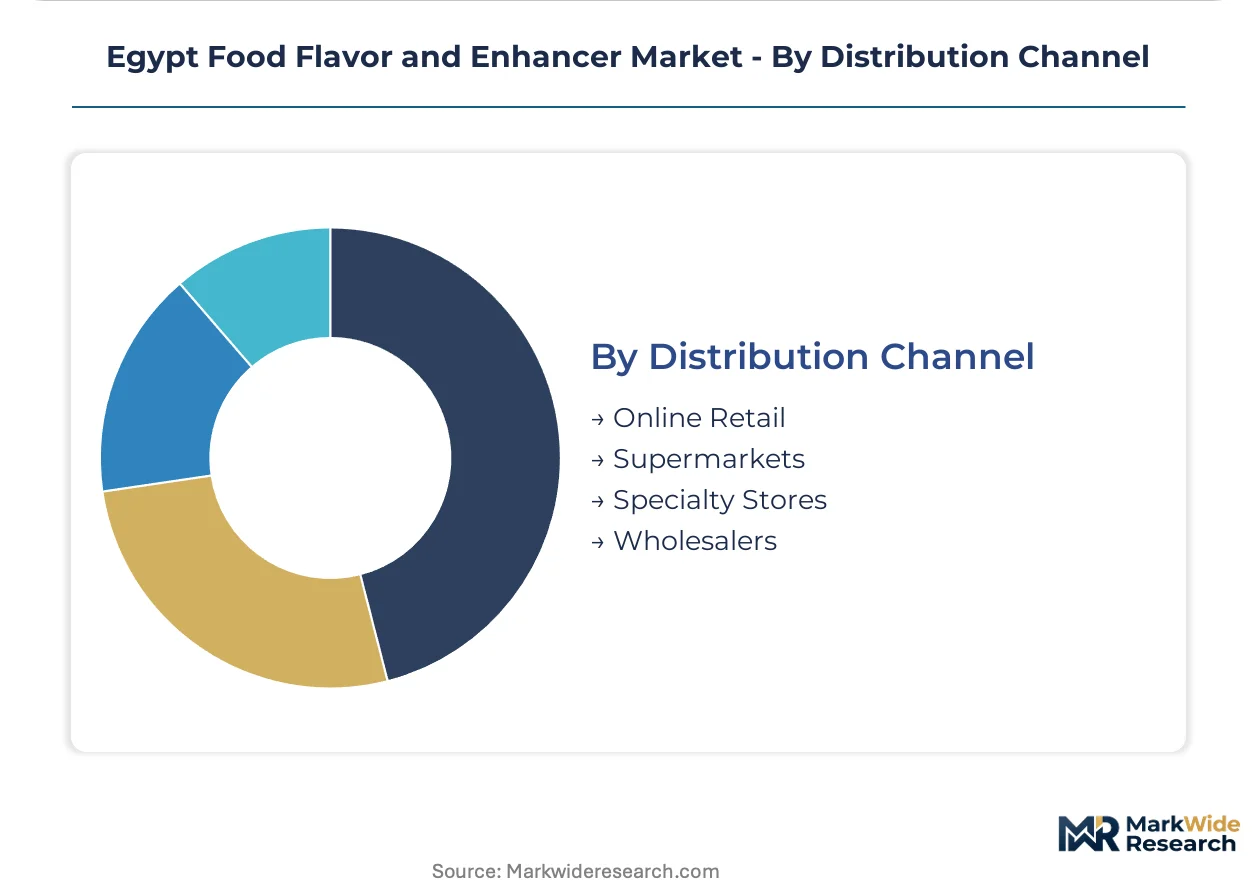
- Online Retail:Alibaba-sourced flavor compound marketplaces gain traction among cost-conscious importers, bypassing traditional distributor markups. Digital procurement platforms enable mid-scale snack manufacturers to access international supplier catalogs directly.
- Wholesalers:Traditional intermediaries in Alexandria and Cairo maintain grip on bulk artificial flavor precursor distribution, though their role diminishes as direct technical service engagements expand.
- Supermarkets:Retail shelf placement for consumer-packaged seasonings and specialty extracts.
- Specialty Stores:Gourmet and ethnic flavor boutiques serving premium restaurant and home cooking segments.
Wholesalers absorb the bulk of installed capacity; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nile Delta citrus and vanilla cultivation anchors Egypt's natural flavor feedstock base, while Greater Cairo's industrial corridor concentrates processing demand. Sub-regional differentiation separates established manufacturing hubs from emerging production zones.
Greater Cairo
Dairy processors in 10th of Ramadan City drive customized flavor system demand for yogurt differentiation against regional imports. Egypt's national food safety authority enforces CODEX-aligned additive maximum limits that determine enhancer chemistry market access. Technical service centers from international suppliers cluster in Obour City to support on-site pilot trials for mid-scale manufacturers.
Nile Delta
Contract farming arrangements for vanilla and citrus precursors reduce import dependency for natural flavor extraction. Agricultural cooperatives across Sharqia and Dakahlia governorates supply raw material to processors seeking clean-label positioning. BASF SE and Cargill anchor procurement relationships through backward integration into local feedstock sourcing.
Alexandria Port Corridor
Seventy percent of synthetic aromatic compound imports enter through this single-point gateway, amplifying currency volatility impacts on mass-market beverage formulation costs. Port logistics constraints create inventory management challenges for artificial flavor precursor distributors. International suppliers maintain bonded warehouse capacity to buffer against Egyptian pound fluctuations.
Upper Egypt
Underpenetrated yogurt and cheese manufacturing in Sohag and Qena governorates presents greenfield flavor system partnership opportunities. Regional processors seek turnkey formulation support to compete with Greater Cairo brands. Givaudan SA leverages technical service proximity to secure emerging relationships outside the traditional industrial corridor.
Egypt Food Flavor and Enhancer Market Competitive Landscape
Technical service proximity dominates the current landscape as procurement criteria shift from price arbitrage to formulation partnership depth. The vendor base concentrates around multinational flavor houses with regional technical centers and local agricultural integrators with captive feedstock supply. Three archetypes define competitive positioning: global integrated houses with full-service capabilities, agricultural processors with backward integration into Nile Delta cultivation, and specialty modulator suppliers focused on enzymatic clean-label solutions. Capacity expansion in encapsulation technology and strategic partnerships for direct-to-processor digital channels represent the dominant competitive moves.
Among Switzerland-based integrated houses, Givaudan SA exemplifies the technical service-led archetype through regional formulation centers. German chemical conglomerate BASF SE occupies a position within synthetic molecule consistency for cost-sensitive applications. US agricultural processor Cargill anchors the backward-integrated tier through Nile Delta feedstock control. These three entities represent distinct strategic vectors: service depth, manufacturing scale, and supply chain captivity.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| DuPont de Nemours, Inc. |
| Givaudan SA |
| Cargill |
| BASF SE |
| International Flavors & Fragrances Inc. |
| Symrise AG |
| Sensient Technologies Corporation |
| DSM-Firmenich |
| Others |
Supply & Pricing Matrix
Flavor chemist expertise concentration in Greater Cairo's industrial corridor compresses labor-cost differentials between premium formulation partnerships and catalog-based commodity procurement, widening pricing-tier spreads between customized sensory systems and standard artificial flavor volumes.
Pricing Analysis
Technical service bundling separates premium-tier partnerships from unbundled commodity transactions in Egypt's flavor procurement landscape. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by customization depth, certification grade under CODEX-aligned standards, and heat-stability performance. Cost compression in the economy tier intensifies because currency volatility amplifies synthetic precursor import costs through Alexandria Port. Mass-market beverage bottlers exhibit highest price sensitivity; dairy processors seeking regional brand differentiation demonstrate lowest sensitivity and absorb premium service fees.
Supply Chain Analysis
Freight cost concentration through Alexandria Port creates single-point vulnerability for seventy percent of artificial flavor precursor imports entering Egypt. Supply draws from India, China, and Germany for synthetic aromatic molecules; natural extraction feeds from Nile Delta citrus and vanilla cultivation. Raw material dependencies center on petrochemical-derived precursors, agricultural feedstocks, and enzymatic modulator substrates. Single-source vulnerability at the port gateway amplifies formulation cost instability during Egyptian pound fluctuations. Distribution runs through bonded warehouse networks buffering currency exposure, with direct technical service engagements displacing traditional wholesaler intermediaries for mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's food flavor market sits in a technology-transition phase as microencapsulation systems displace legacy spray-drying architectures for heat-stable dairy and snack applications.
For Market Incumbents: To counter talent scarcity among retiring flavor chemists at state research institutes, secure knowledge transfer partnerships with technical universities in Sharqia and Qena governorates. Backward integration into Nile Delta vanilla contract farming locks in clean-label feedstock supply continuity against climate-stressed harvest variability. For New Entrants and Emerging Players: E-commerce direct-to-processor channels in Upper Egypt present the most penetrable entry vector, targeting underpenetrated yogurt and cheese manufacturers in Sohag and Qena with turnkey formulation support. Alibaba-sourced compound marketplaces enable cost-conscious importers to bypass traditional distributor markups and establish initial relationships before technical service expansion. For Investors and Strategic Acquirers: The window for entry favors agricultural integrators with captive Nile Delta feedstock control and encapsulation technology capabilities. Long-term viability hinges on regulatory tailwinds favoring enzymatic clean-label modulators over synthetic alternatives. Watch Egypt's national food safety authority pending updates to the additive positive list as the critical inflection signal for R&D investment redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Heat-stable lipid-matrix systems enable UHT dairy processors to replicate imported sensory profiles without foreign formulation licenses. |
| Nile Delta Contract Farming Expansion | Backward integration into vanilla and citrus cultivation reduces import dependency for natural flavor precursors seeking clean-label positioning. |
| Direct Technical Service Deployment | On-site pilot trials in 10th of Ramadan City displace traditional distributor intermediaries and deepen supplier-processor formulation partnerships. |
| Digital Procurement Platform Launch | Alibaba-sourced marketplaces bypass wholesaler markups for mid-scale snack manufacturers seeking cost-optimized artificial flavor compounds. |
| CODEX Alignment Certification Investment | Streamlined approval pathways for enzymatic modulators accelerate product pipeline commercialization under Egypt's updated food additive standards. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Egypt-focused analysis. Primary interviews with flavor house technical directors, dairy processor procurement leads, Nile Delta agricultural cooperative managers, and food safety authority compliance officers combined with secondary validation from CODEX Alimentarius frameworks, Egyptian customs import databases, and industry association production surveys. Bottom-up volume modeling across product types and applications triangulated against top-down market sizing from trade flow analysis.
Granularity-level modeling segmented the market by natural versus artificial flavor extraction method, beverage versus dairy versus snack application, and Greater Cairo versus Nile Delta versus Upper Egypt regional production clusters. CAGRs derived from trend extrapolation of import volume trajectories, capacity expansion announcements, and regulatory approval timelines across the projection horizon. Industry-specific forecast inputs included climate stress indices for Egyptian mint and chamomile harvests and currency volatility assumptions for Alexandria Port synthetic precursor costs.
The model holds under stable CODEX-aligned regulatory enforcement and continued Nile Delta agricultural productivity; deviation in additive positive list restrictions or prolonged currency devaluation would shift volume trajectories between natural and artificial flavor tiers. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Canola Lecithin Market
Flavorings and Food Additives
Salts and Flavored Salts Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Smoke Flavorings Market
Flavorings and Food Additives
Tangerine Peel Extract Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Oil Soluble Flavors Market
Flavorings and Food Additives
Flavor and Flavor Enhancers Market
Flavorings and Food Additives
Global Natural Food Colorants Market
Flavorings and Food Additives
Bitter Apricot Extract Market
Flavorings and Food Additives
Poria Cocos Extract Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Vanillin Market
Flavorings and Food Additives
Africa Food Flavor Market