
 D-Limonene Market | 2026-2036
D-Limonene Market Size, Share, and Industry Trends Forecast 2026-2036
D-Limonene Market Analysis
The gap between pharmaceutical-grade and industrial-grade D-limonene is consolidating as purity specifications tighten and buyers consolidate suppliers. Florida Chemical Company leverages its captive orange oil supply from Florida groves to sustain cost advantages in commodity industrial grades. DSM-Firmenich differentiates through high-purity extraction capabilities that serve European fragrance houses and pharmaceutical formulators. Symrise AG competes by controlling distillation technology that yields consistent chiral specifications for flavor applications.
D-limonene is a monocyclic monoterpene hydrocarbon extracted primarily from cold-pressed orange peel oil, typically comprising over 90% of citrus terpene fractions by weight, with a boiling point of 176°C and CAS registry 5989-27-5. Its primary commercial purpose centers on solvent replacement for halogenated and aromatic hydrocarbons, alongside flavor and fragrance compounding. Food-grade D-limonene commands premium positioning in flavoring agents for beverages and confectionery, while industrial-grade supply dominates volume in cleaning products and degreasing solvents where cost sensitivity prevails. Pharmaceutical-grade extraction represents the fastest-growing margin pool, driven by excipient demand and active pharmaceutical ingredient synthesis.
The EPA regulates D-limonene under the Toxic Substances Control Act and FIFRA for pesticide and antimicrobial applications, while REACH in Europe mandates registration and hazard communication for terpene imports above one-tonne thresholds. FDA food additive regulations under 21 CFR 182.60 govern flavoring use, creating compliance differentiation between grades. Stakeholders must monitor bio-based content certification schemes and evolving state-level VOC restrictions in California and the Northeast Corridor, as these determine market access for solvent applications.
Market Dynamics
REACH regulation in Europe is forcing petrochemical solvent displacement toward citrus-derived alternatives, while North American manufacturing facilities accelerate industrial cleaner reformulation to meet tightening volatile organic compound thresholds.
Growth Catalysts
- REACH VOC restrictions:European ECHA mandates on volatile organic compound emissions redirect formulators toward D-limonene as a compliant replacement for aromatic hydrocarbons in degreasing applications.
- Food-grade flavoring demand:Beverage and confectionery manufacturers in Brazil's Sao Paulo state leverage integrated orange processing complexes to secure consistent terpene supply for natural flavoring agents.
- Halogenated solvent phase-out:EPA FIFRA enforcement against chlorinated degreasers positions D-limonene as the preferred drop-in substitute across metal fabrication and electronics cleaning operations.
Market Restraints
- Citrus crop volatility:Florida and Brazil orange harvest fluctuations create raw material uncertainty that compresses margin predictability for cold-pressed oil processors.
- Supply concentration risk:Integrated processing complexes in Sao Paulo state control disproportionate terpene fraction capacity, creating geographic single-point vulnerability.
- Terpenoid oxidation instability:D-limonene's susceptibility to autoxidation and subsequent skin sensitization limits pharmaceutical-grade shelf life and complicates excipient qualification timelines.
Strategic Opportunities
- Pharmaceutical excipient expansion:FDA 21 CFR 182.60 compliance pathways enable D-limonene penetration into transdermal drug delivery systems and active pharmaceutical ingredient synthesis.
- California CARB alignment:State-level VOC restrictions in the Northeast Corridor and California create regulatory tailwinds for bio-based solvent certification schemes displacing petroleum derivatives.
- Chiral specification services:Flavor houses demand consistent enantiomeric purity that specialized distillation technology can command premium positioning for.
Industry Challenges
- Pharmaceutical-grade purification capex:Supercritical CO2 extraction and molecular distillation equipment requires substantial capital deployment to meet tightening USP-NF monograph specifications.
- Multi-jurisdiction compliance synchronization:Simultaneous EPA TSCA, REACH registration, and FDA food additive maintenance creates divergent documentation burdens that strain smaller processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | D-Limonene Market |
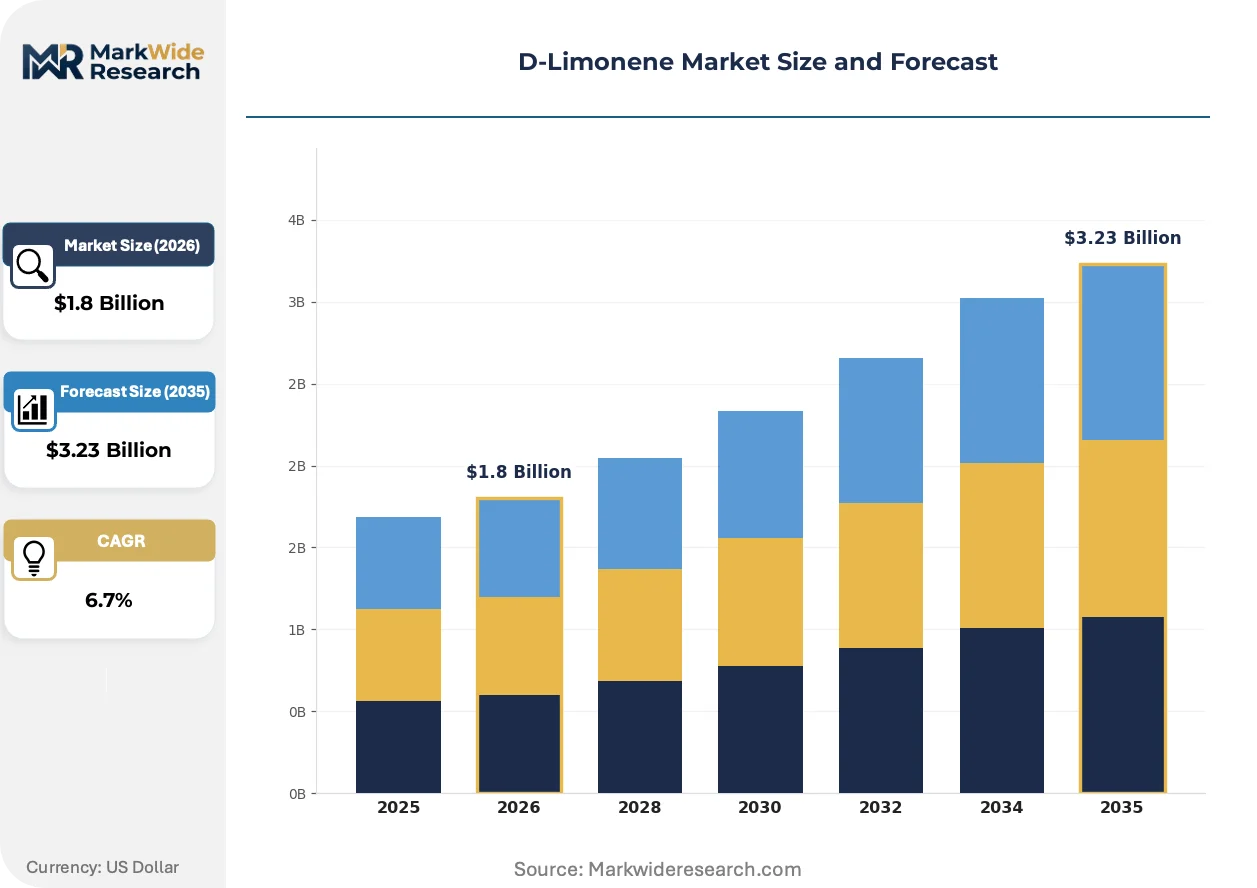
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Cleaning Products, Flavoring Agents, Perfumes, Solvents End User: Food & Beverage, Pharmaceuticals, Cosmetics, Manufacturing Packaging Type: Drums, Bottles, Totes, Bulk Containers |
| Companies Covered | Orchidia, Spectrum Chemical Mfg. Corp, Florida Chemical Company, DSM-Firmenich, Symrise AG, Citrosuco, Lemonconcentrate S.L.U, Sucorrico SA, Cutrale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
D-Limonene Market Emerging Trajectories
Supercritical fluid extraction technology is absorbing capital allocation as processors seek to bridge the purity gap between industrial and pharmaceutical grades without thermal degradation of heat-sensitive terpenes.
Supercritical CO2 extraction systems operate at near-ambient temperatures, preserving chiral integrity during D-limonene recovery from orange peel oil. European fragrance houses and pharmaceutical formulators are absorbing this capability at accelerated procurement cycles to secure excipient-grade supply chains. The technology is absorbing market share from traditional steam distillation by enabling simultaneous pesticide residue reduction and optical purity enhancement.
REACH registration mandates under ECHA guidance now require full hazard communication dossiers for terpene imports exceeding one-tonne annual thresholds. Industrial solvent distributors are absorbing compliance costs through supplier consolidation rather than portfolio diversification. Brazilian processors serving European industrial cleaners face the steepest documentation burdens, redirecting investment toward in-house toxicology testing capabilities.
Specification-driven procurement now dominates pharmaceutical and fragrance segments, displacing spot-market purchasing for commodity industrial grades. Buyers in these categories are consolidating approved supplier lists to three qualified vendors maximum, compressing qualification timelines and demanding locked-in chiral certificates of analysis. This pattern is most visible in German and Swiss pharmaceutical manufacturing clusters where USP-NF compliance gates procurement access.
D-Limonene Market Segmentation
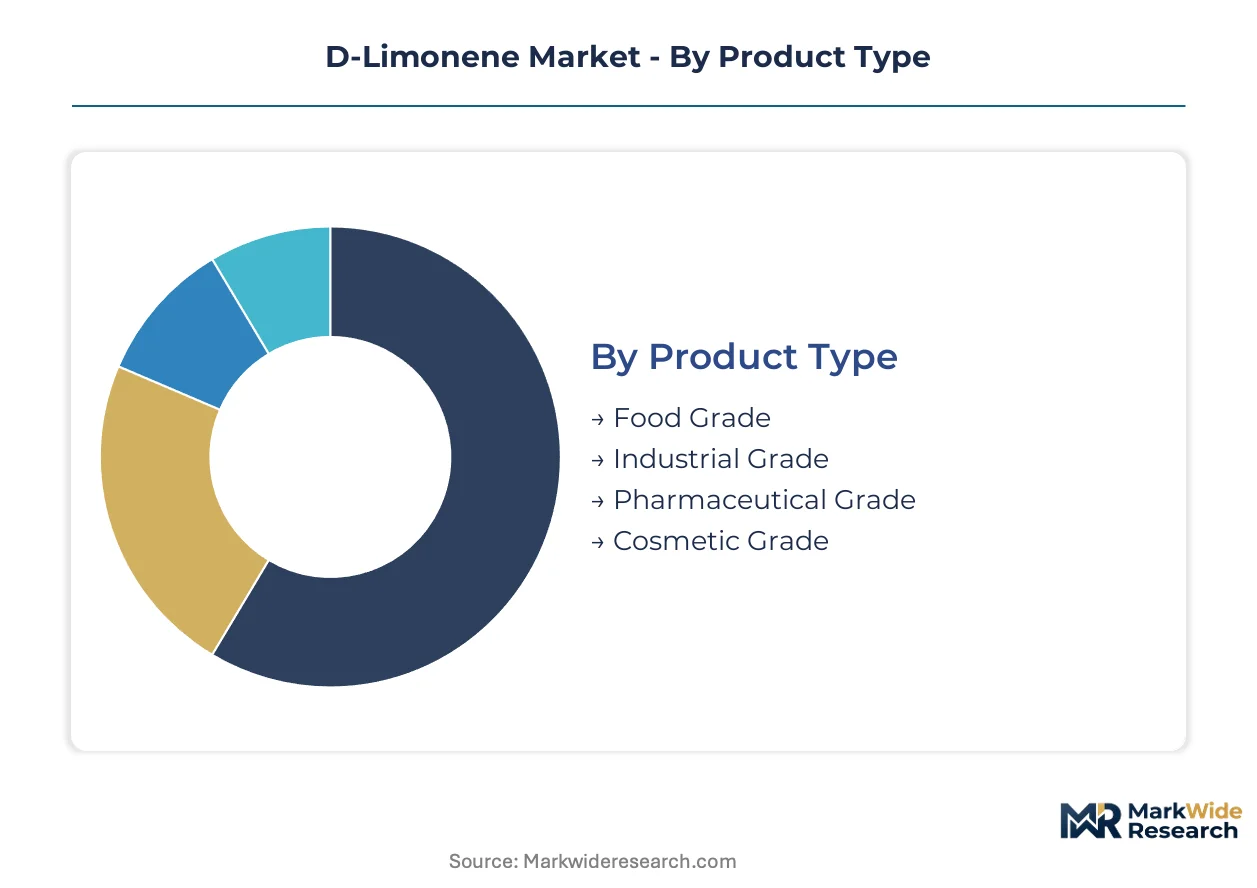
D-limonene's four-grade product architecture creates distinct margin pools that separate commodity solvent buyers from specification-driven pharmaceutical and fragrance formulators. Packaging and application segmentation further stratifies procurement patterns between bulk industrial offtake and precision-dosed specialty supply.
Product Type:
Volume concentrates in industrial grades where citrus peel oil supply chains achieve scale, while pharmaceutical and cosmetic specifications command tiered premiums based on purity thresholds.
- Food Grade:D-limonene meeting FDA 21 CFR 182.60 specifications serves natural flavoring applications in beverages and confectionery, with demand clustering in Brazil's Sao Paulo state where Citrosuco and Cutrale operate integrated orange processing complexes.
- Industrial Grade:Comprising over 90% of citrus terpene fractions by weight with typical boiling point of 176°C, this specification dominates degreasing solvent displacement of halogenated hydrocarbons in North American manufacturing facilities under tightening EPA FIFRA enforcement.
- Pharmaceutical Grade:USP-NF monograph compliance enables excipient applications in transdermal drug delivery systems, with supercritical CO2 extraction technology preserving chiral integrity for active pharmaceutical ingredient synthesis.
- Cosmetic Grade:REACH-registered supply serves European fragrance houses requiring consistent enantiomeric purity certificates from specialized distillation operators.
Mature deployment sits with Industrial Grade. Newer deployment is concentrated in Pharmaceutical Grade.
Application:
Cost tier separation distinguishes solvent replacement volumes from compounding premiums in flavor and fragrance end-uses.
- Cleaning Products:Industrial degreasers and household cleaners leverage d-limonene's solvent properties to displace petrochemical alternatives under California CARB and Northeast Corridor VOC restrictions.
- Flavoring Agents:Natural flavoring demand from beverage manufacturers concentrates procurement in Brazil's integrated orange processing regions where cold-pressed oil supply chains achieve cost efficiency.
- Perfumes:European fragrance houses absorb supercritical fluid extraction capabilities at accelerated procurement cycles to secure specification-grade terpene supply with consistent chiral certificates.
- Solvents:Metal fabrication and electronics cleaning operations position d-limonene as the preferred drop-in substitute for chlorinated degreasers facing EPA phase-out pressure.
Procurement scale clusters in Cleaning Products. Margin expansion is accelerating in Perfumes.
End User:
Customer type determines compliance burden intensity, from FDA food additive maintenance to REACH registration and EPA TSCA synchronization.
- Food & Beverage:Beverage and confectionery manufacturers in Brazil leverage captive orange oil supply from Florida Chemical Company's Florida grove operations for consistent terpene sourcing.
- Pharmaceuticals:German and Swiss manufacturing clusters consolidate approved supplier lists to three qualified vendors maximum, compressing qualification timelines for USP-NF compliant excipient access.
- Cosmetics:European formulators face ECHA hazard communication dossier requirements for terpene imports exceeding one-tonne annual thresholds.
- Manufacturing:North American metal fabrication facilities accelerate industrial cleaner reformulation to meet tightening volatile organic compound emission standards.
Regulatory documentation burdens concentrate in Pharmaceuticals. Volume throughput dominates in Manufacturing.
Packaging Type:
Supply concentration shapes logistics economics, with bulk infrastructure determining cost competitiveness for commodity grades.
- Drums:Standard 55-gallon steel drums serve mid-volume industrial solvent distributors requiring flexibility across multiple manufacturing accounts.
- Bottles:Precision-dosed packaging enables pharmaceutical and cosmetic formulators to manage oxidation-sensitive terpenoid inventory with controlled shelf-life exposure.
- Totes:Intermediate bulk containers balance handling efficiency with inventory turnover for regional cleaning product manufacturers.
- Bulk Containers:Tank truck and railcar deliveries achieve minimum unit economics for integrated processors supplying commodity industrial grades to large-scale degreasing operations.
Handling efficiency concentrates in Bulk Containers. Specification control dominates in Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's integrated orange processing complexes in Brazil anchor terpene fraction capacity, while regulatory divergence across jurisdictions reshapes trade flows and local production economics.
United States
Florida's citrus belt supplies cold-pressed orange oil to industrial solvent manufacturers facing EPA FIFRA enforcement against chlorinated degreasers. California CARB VOC restrictions accelerate reformulation of cleaning products toward bio-based alternatives. Metal fabrication clusters in Ohio and Michigan absorb tank-truck deliveries of commodity-grade D-limonene for drop-in solvent replacement.
Brazil
Citrosuco and Cutrale operate captive distillation capacity serving beverage flavoring demand from São Paulo state processors. ANVISA food additive regulations govern export-grade terpene certification for North American and European offtake. The São Paulo industrial corridor concentrates fractionation infrastructure within 200 kilometers of primary orange grove operations.
Germany
REACH registration mandates under ECHA guidance require full hazard communication dossiers for terpene imports exceeding one-tonne thresholds. Fragrance houses in the Cologne-Düsseldorf corridor consolidate approved supplier lists to three qualified vendors maximum. Supercritical CO2 extraction capabilities serve pharmaceutical formulators seeking USP-NF compliant excipient supply.
Switzerland
Swissmedic pharmaceutical regulations drive excipient-grade procurement from specialized distillation operators with locked-in chiral certificates. Basel's pharmaceutical manufacturing cluster compresses qualification timelines for transdermal drug delivery system applications. Specification-driven procurement displaces spot-market purchasing for fragrance and pharmaceutical grades.
China
GB standards and MIIT industrial policy guide domestic solvent replacement programs in electronics cleaning operations. Yangtze River Delta manufacturers position D-limonene as a substitute for halogenated hydrocarbons in printed circuit board fabrication. NMPA pharmaceutical regulations create compliance differentiation for imported versus domestic excipient-grade supply.
D-Limonene Market Vendor Landscape
Premium-margin players sit above commodity-margin players across purity specification tiers, with pharmaceutical and fragrance grades commanding tiered premiums over industrial solvent volumes. The vendor base separates into integrated citrus processors with captive peel oil supply, specialized distillation operators with chiral control capabilities, and regional distributors absorbing REACH compliance costs through supplier consolidation. Three archetypes dominate: backward-integrated grove-to-terpene processors, technology-differentiated purification specialists, and compliance-heavy industrial solvent distributors. Competitive moves concentrate on supercritical extraction capacity deployment and multi-jurisdiction registration maintenance.
Among integrated processors, Florida Chemical Company and Citrosuco exemplify the backward-integrated archetype with captive orange oil supply chains. DSM-Firmenich occupies a position representing the purification-specialist tier, while Symrise AG anchors the fragrance-grade distillation segment with chiral specification capabilities.
| Leading Market Players |
|---|
| Orchidia |
| Spectrum Chemical Mfg. Corp |
| Florida Chemical Company |
| DSM-Firmenich |
| Symrise AG |
| Citrosuco |
| Lemonconcentrate S.L.U |
| Sucorrico SA |
| Cutrale |
| Others |
Supply Flow & Price Mechanics
Backward integration into captive orange grove operations anchors both supply security and margin control for D-limonene processors. Florida Chemical Company and Citrosuco leverage in-house peel oil extraction to buffer raw material volatility while commanding premium positioning in specification-grade markets.
Pricing Analysis
Yield-locked pricing for pharmaceutical-grade supply ties contract values to chiral purity outcomes rather than input volume. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates USP-NF compliant excipients from commodity solvent volumes. Cost compression in industrial grades is intensifying because Brazilian processors face REACH documentation burdens that smaller distributors cannot absorb. Food and beverage manufacturers demonstrate highest price sensitivity, while German pharmaceutical clusters accept locked-in premiums for qualified vendor access.
Supply Chain Analysis
Dual-sourcing mandates from Swiss and German pharmaceutical buyers require qualified suppliers in both Brazil and the United States. Raw material supply draws from Florida citrus groves, São Paulo state orange processing complexes, and secondary Mediterranean peel oil recovery. Single-source vulnerability concentrates in São Paulo's integrated distillation corridor, where Citrosuco and Cutrale control disproportionate fractionation capacity. Distribution runs through tank-truck bulk deliveries for industrial grades and precision-bottle packaging for oxidation-sensitive pharmaceutical inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is mounting as REACH registration costs and supercritical extraction capex requirements force sub-scale processors toward exit. Regulatory compliance burdens favor integrated operators with in-house toxicology and certification capabilities.
For Market Incumbents: Cement supplier consolidation advantages by acquiring distressed REACH-registered distributors in the Northeast Corridor. Lock in chiral specification capabilities through supercritical CO2 extraction capacity additions that emerging entrants cannot replicate. Florida grove operations provide defensive moats against Brazilian crop volatility.
For New Entrants and Emerging Players: Enter via California CARB-aligned solvent certification services for metal fabrication clusters seeking compliant degreaser reformulation. Target pharmaceutical excipient white space through specialized distillation partnerships with Swissmedic-registered operators. Go-to-market leverage rests on locked-in chiral certificates rather than volume scale.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by backward-integrated processors seeking geographic diversification beyond São Paulo supply concentration. Long-term viability favors operators with simultaneous FDA 21 CFR 182.60, REACH, and EPA TSCA maintenance capabilities. Watch for Florida citrus greening disease progression as inflection indicator for raw material cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Deployment | Preserves chiral integrity for USP-NF pharmaceutical excipient qualification. |
| Backward Integration into Grove Operations | Captive orange oil supply buffers Brazilian crop volatility for Florida processors. |
| REACH Registration Consolidation | Absorbs compliance costs through supplier reduction rather than portfolio diversification. |
| California CARB Certification Alignment | Unlocks bio-based solvent access under state-level VOC restriction programs. |
| Pharmaceutical Vendor Qualification | Compresses approved supplier lists to three qualified vendors in German clusters. |
Methodological Framework
Document review covered customs trade data, ECHA registration dossiers, and FDA food additive filings, complemented by interviews with citrus processing plant managers, fragrance house procurement leads, pharmaceutical excipient qualification officers, and industrial solvent distribution channel partners. Secondary validation drew from SEC 10-K disclosures of listed chemical processors, ANVISA export certification records, and Swissmedic pharmaceutical ingredient databases. Bottom-up volume estimates triangulated against top-down market sizing from trade flow analysis.
Cross-referencing historical capacity expansion patterns against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include grade tier, end-use application, packaging format, and regional production hub. CAGRs derived from slope-log analysis of volume trajectories, incorporating citrus crop yield forecasts and regulatory phase-out schedules for halogenated solvents as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Brazilian climate disruption or Florida citrus greening acceleration scenarios. Deviation in REACH enforcement intensity or EPA FIFRA chlorinated solvent phase-out timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
All-Natural Flavors System Market
Flavorings and Food Additives
Citrus Extract Market
Flavorings and Food Additives
South America Flavors and Fragrances Market
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Roast Flavoring Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Egypt Food Colorants Market
Flavorings and Food Additives
Middle East Food Premix Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
Italy Food Colorants Market