
 Savory Extract Market | 2026-2036
Savory Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Savory Extract Market Analytics
Flavor chemist shortages across European and North American manufacturing hubs is unwinding capacity expansion timelines for savory extract producers. Kerry Group plc leverages its integrated taste and nutrition platform to sustain long-term supply agreements with multinational food manufacturers. Givaudan anchors its competitive position through deep specialization in natural flavor precursors and biotechnology-driven extraction methods. Symrise competes by controlling raw material sourcing across Mediterranean herb and spice growing regions.
Savory extracts comprise concentrated flavoring preparations derived from proteins, amino acids, and nucleotides through thermal processing, enzymatic hydrolysis, or fermentation, designed to deliver umami depth and mouthfeel enhancement in reduced-sodium formulations. Vegetable extracts and yeast-based derivatives dominate current volume flows, while mushroom extracts represent the fastest-growing product type as plant-forward menus expand across foodservice channels. Application demand concentrates in food processing and seasoning, where margin pools favor liquid and powder forms optimized for industrial-scale dosing systems.
EFSA flavoring regulations, FDA GRAS notification requirements, and China's GB standards for food flavorings collectively shape product registration pathways and label claim permissibility across major supply corridors. Compliance with evolving EU Green Deal sustainability benchmarks now influences supplier qualification criteria for extract procurement at tier-one food manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and market access barriers.
Market Dynamics
Clean-label mandates from snack food manufacturers are forcing savory extract suppliers to reconfigure supply chains around yeast-derived and vegetable-based inputs, compressing timelines for synthetic flavor replacement.
Growth Catalysts
- EFSA Flavoring Regulations:Updated oversight under the EU Green Deal sustainability benchmarks is accelerating supplier qualification for clean-label extract procurement at tier-one food manufacturers.
- Yeast Fermentation:Industrial-scale enzymatic hydrolysis is displacing thermal processing as the dominant extraction method, lowering energy intensity while preserving amino acid profiles.
- Germany:Industrial food processing clusters in Bavaria and Baden-Württemberg anchor procurement volumes for premium sauce production, concentrating demand from extract suppliers.
Market Restraints
- Flavor Chemist Scarcity:Shortages across European and North American manufacturing hubs are unwinding capacity expansion timelines for producers seeking to scale thermal processing operations.
- Raw Material Concentration:Mediterranean herb and spice growing regions control upstream supply, exposing extract manufacturers to climate volatility and harvest inconsistency.
- Regulatory Divergence:Misalignment between EFSA flavoring regulations, FDA GRAS notification requirements, and China's GB standards is fragmenting product registration pathways and label claim permissibility.
Strategic Opportunities
- Plant-Forward Foodservice:Mushroom extracts represent underpenetrated white space as restaurant chains expand umami-forward reduced-sodium menus across North American and European channels.
- Biotechnology Convergence:Integration of precision fermentation with enzymatic hydrolysis is enabling novel nucleotide profiles previously unattainable through conventional thermal methods.
- EU Green Deal Procurement:Sustainability-linked supplier qualification criteria are creating preferential access lanes for extract producers with verified carbon footprint reductions.
Industry Challenges
- Formulation Expertise Gap:Shortages of protein chemists with dual competency in sensory science and regulatory compliance are delaying clean-label reformulation cycles.
- Legacy Dosing System Integration:Industrial food processors face capex burdens retrofitting liquid and powder extract handling equipment optimized for synthetic flavor workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Savory Extract Market |
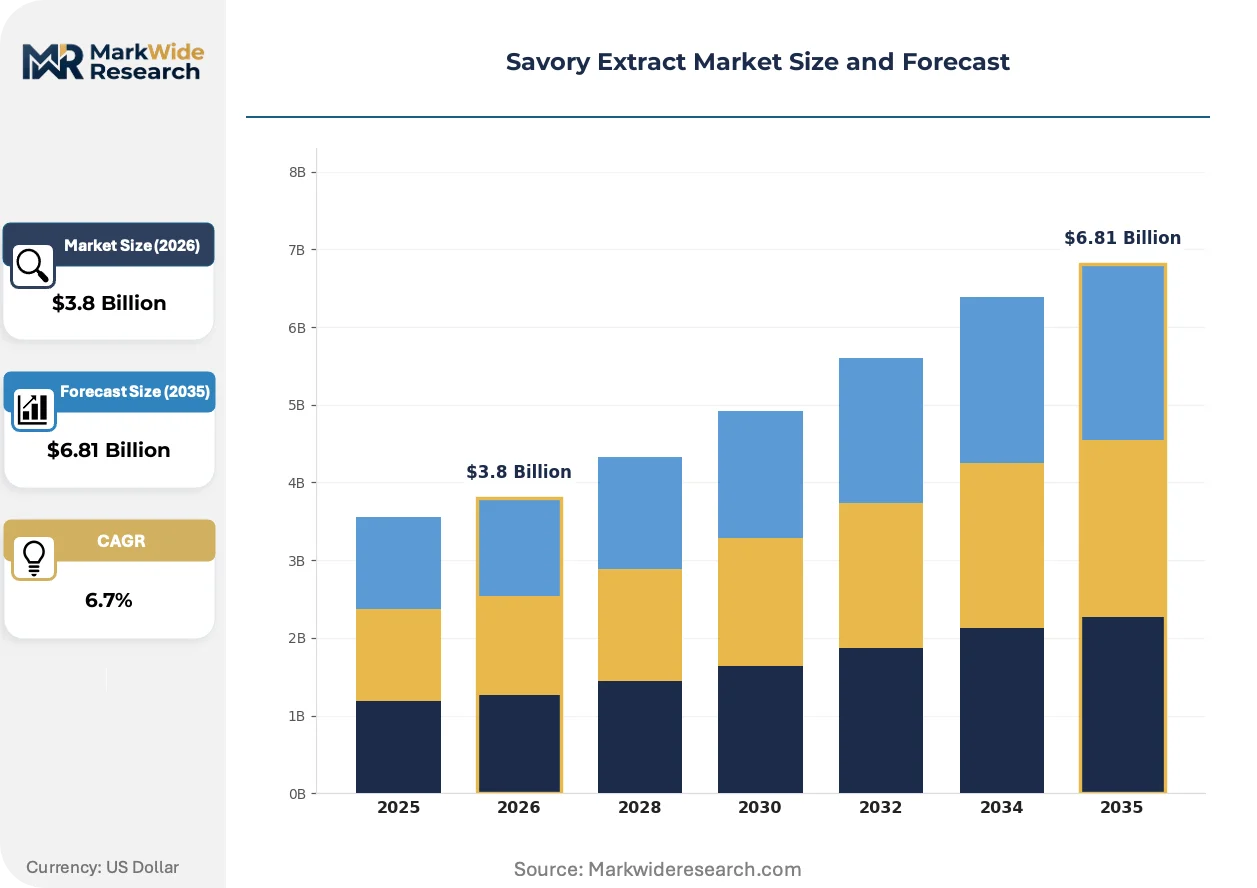
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Extracts, Mushroom Extracts, Meat Extracts, Spice Extracts Application: Food Processing, Snack Foods, Seasoning, Sauces End User: Food Manufacturers, Retailers, Restaurants, Catering Services Form: Liquid, Powder, Paste, Granulated |
| Companies Covered | Ajinomoto Co., Kerry Group plc, Lesaffre, Givaudan, Archer Daniels Midland Company, AngelYeast Co., Symrise, Tate & Lyle, Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Savory Extract Market Evolving Landscape
Biotechnology-driven extraction methods are compressing development cycles while regulatory fragmentation forces parallel compliance tracks across major supply corridors.
Precision fermentation platforms are miniaturizing production footprints for savory extract manufacturing. Mid-scale food processors in the Netherlands and Denmark are adopting modular bioreactor systems at pilot scale. This distributed production model is miniaturizing the traditional centralized extract facility, enabling regional supply security and reduced transport emissions.
REACH chemical safety assessments and the EU F-Gas Regulation are tightening solvent recovery requirements for extraction operations. Industrial flavor houses face capital allocation decisions between retrofitting existing thermal processing lines or migrating to aqueous enzymatic systems. German extract producers are responding fastest, leveraging existing biotechnology infrastructure from pharmaceutical adjacent industries.
Direct supplier relationships are displacing layered distribution networks for savory extract procurement. Large snack food manufacturers in the United States are consolidating vendor bases and negotiating long-term offtake agreements with yeast extract specialists. This concentration pattern is most visible in California and Illinois, where clean-label reformulation timelines have compressed from 18-month cycles to 8-month windows.
Savory Extract Market Segmentation
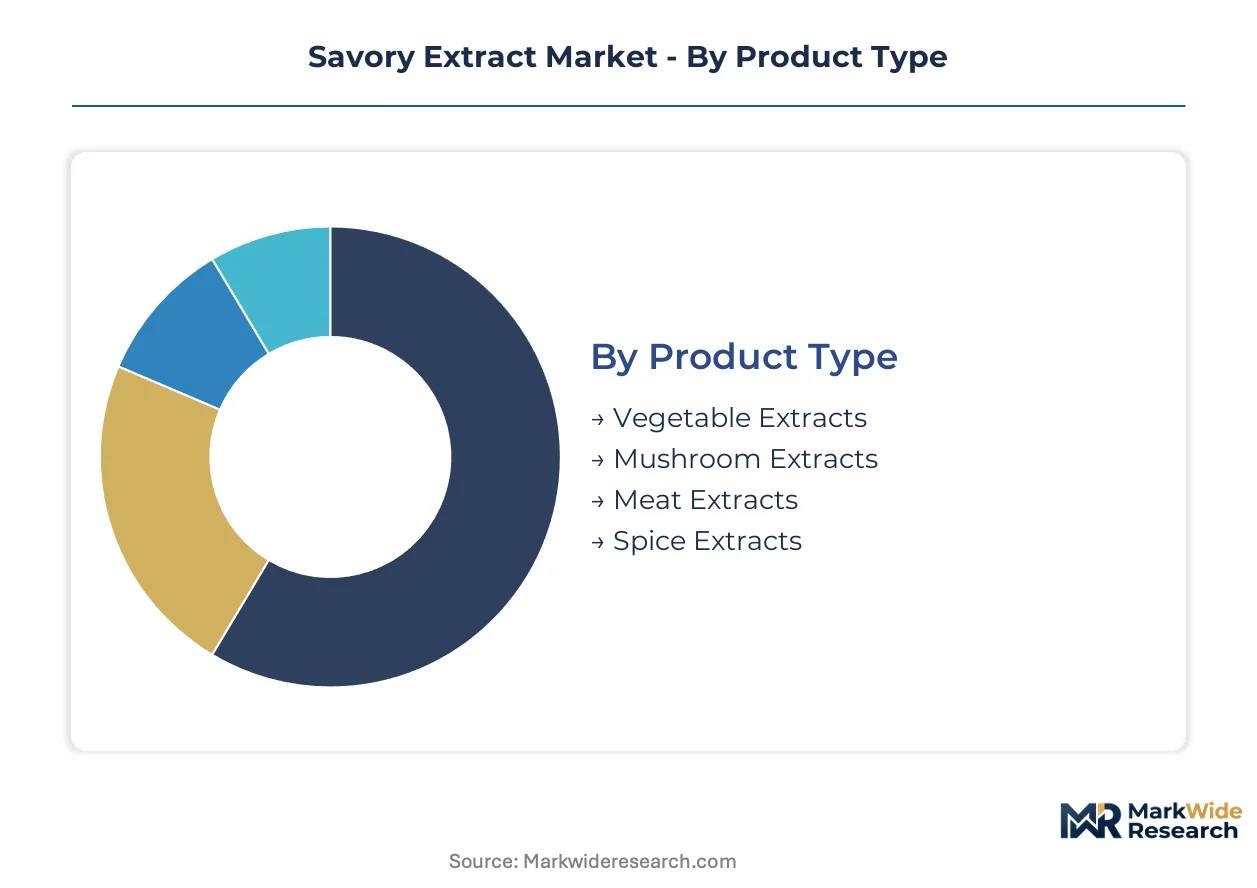
Savory extract procurement patterns diverge sharply across product categories, with vegetable and yeast-derived formats dominating clean-label reformulation while mushroom variants capture plant-forward menu expansion. Form factor selection directly determines dosing system compatibility and sodium reduction efficacy in industrial food processing environments.
Product Type:
Vegetable extracts anchor domestic supply chains across German and Dutch processing clusters, while mushroom extracts drive export-led growth into North American foodservice channels.
- Vegetable Extracts:Concentrated preparations from tomatoes, onions, and celery deliver foundational umami profiles through thermal processing or enzymatic hydrolysis. Bavarian sauce manufacturers in Germany anchor procurement volumes for premium liquid formats, constrained by EFSA flavoring regulation compliance timelines for clean-label certification.
- Mushroom Extracts:Shiitake and porcini-derived concentrates provide nucleotide-rich umami enhancement without sodium reliance. California-based restaurant chains and Illinois snack food manufacturers are expanding offtake agreements for powdered variants, compressing reformulation windows from eighteen to eight months.
- Meat Extracts:Thermally processed beef, chicken, and pork concentrates retain traditional application in Central European broth and soup manufacturing, though clean-label substitution pressure is eroding share.
- Spice Extracts:Mediterranean herb-derived concentrates from rosemary, thyme, and black pepper supply flavor modulation and antioxidant functionality to seasoning blends.
Vegetable extracts command the established base. The steepest expansion runs through mushroom extracts.
Application:
Margin structures favor liquid and powder forms in food processing, while snack food applications demand rapid-dissolve powder specifications for clean-label seasoning adhesion.
- Food Processing:Industrial-scale soup, broth, and prepared meal manufacturing consumes bulk liquid extracts through automated dosing systems. German Baden-Württemberg clusters concentrate demand for reduced-sodium formulations meeting EU Green Deal procurement criteria.
- Snack Foods:Extruded and coated products require low-moisture powder extracts with uniform particle distribution for seasoning adherence. US manufacturers in California and Illinois are consolidating vendor bases around yeast extract specialists with verified carbon footprint reductions.
- Seasoning:Blend houses combine multiple extract types with salt replacers and flavor potentiators for retail and foodservice distribution.
- Sauces:Premium condiment production in Bavaria favors vegetable-derived liquid concentrates with declared clean-label status under EFSA oversight.
Food processing retains volume leadership. Snack foods are climbing the fastest as clean-label mandates accelerate synthetic flavor displacement.
End User:
Direct supplier relationships are displacing distribution layers, with food manufacturers consolidating procurement while restaurants pilot mushroom extract integration for plant-forward menus.
- Food Manufacturers:Multinational processors negotiate long-term offtake agreements with extract houses, leveraging integrated taste and nutrition platforms for reformulation support. Kerry Group plc and Givaudan anchor supply security through biotechnology-driven extraction partnerships.
- Retailers:Private-label seasoning and sauce brands demand cost-competitive powder extracts with clean-label positioning for shelf differentiation.
- Restaurants:Chain operators in North America and Europe are testing mushroom extract formulations for umami-forward reduced-sodium menu items.
- Catering Services:Institutional foodservice procurement favors standardized liquid extracts for batch consistency in high-volume preparation.
Food manufacturers command the established base. Restaurants are gaining share fastest as plant-forward menu expansion accelerates extract trials.
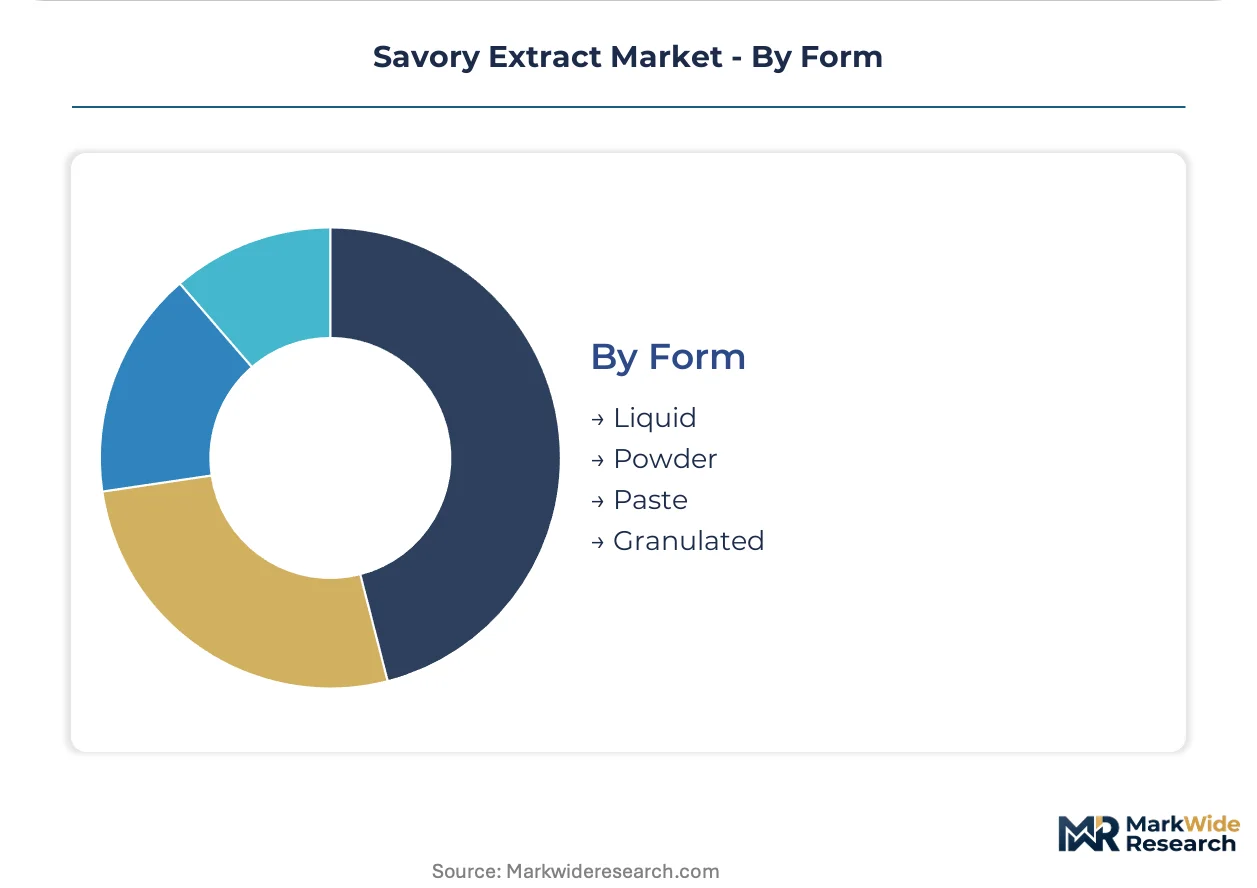
Form:
Liquid formats dominate industrial dosing infrastructure, while powder variants enable clean-label reformulation in legacy snack processing equipment without capital retrofit.
- Liquid:Pumpable concentrates with controlled viscosity integrate directly into thermal processing lines and automated batch systems. German extract producers leverage pharmaceutical-adjacent biotechnology infrastructure for aqueous enzymatic production.
- Powder:Spray-dried and agglomerated formats dissolve rapidly for seasoning application and dry blend incorporation. REACH chemical safety assessments and EU F-Gas Regulation solvent recovery requirements favor aqueous processing methods.
- Paste:High-solids concentrates serve artisanal sauce and spread manufacturers requiring intense flavor impact at low usage rates.
- Granulated:Free-flowing particles reduce dusting and improve handling characteristics for manual seasoning operations in smaller processing facilities.
Liquid forms command the established base. Powder is expanding most quickly as clean-label retrofit avoidance drives snack food adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA oversight of flavoring regulations under the EU Green Deal has positioned Germany as the regulatory anchor for savory extract procurement standards across European supply corridors.
Germany
Industrial food processing clusters in Bavaria and Baden-Württemberg drive concentrated demand for premium vegetable-derived liquid extracts. REACH chemical safety assessments and EU F-Gas Regulation solvent recovery requirements are accelerating migration from thermal processing to aqueous enzymatic systems. Munich-based sauce manufacturers anchor procurement volumes for clean-label certified concentrates.
United States
Snack food manufacturers in California and Illinois are consolidating vendor bases around yeast extract specialists with verified carbon footprint reductions. FDA GRAS notification requirements shape label claim permissibility for mushroom-derived umami formulations. Chicago-area extruded product facilities are retrofitting legacy dosing equipment for rapid-dissolve powder specifications.
China
GB standards for food flavorings govern product registration pathways for yeast fermentation platforms serving domestic seasoning blend houses. Precision fermentation infrastructure from pharmaceutical-adjacent industries in Jiangsu and Zhejiang provinces is repurposing for extract manufacturing. Shanghai-based flavor houses are negotiating direct supplier relationships with multinational food processors.
Netherlands
Mid-scale food processors in Randstad and Brabant regions are piloting modular bioreactor systems for distributed savory extract production. ECHA oversight of chemical safety assessments influences solvent selection for Mediterranean herb-derived concentrates. Eindhoven-area biotechnology facilities are miniaturizing traditional centralized extract manufacturing footprints.
France
Seasoning blend houses in Île-de-France and Provence-Alpes-Côte d'Azur source spice extracts from controlled Mediterranean herb growing regions. ANSM and CNIL oversight intersects with EFSA flavoring regulations for clean-label certification timelines. Lyon-based foodservice distributors are testing mushroom extract formulations for plant-forward menu expansion.
Savory Extract Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational taste-and-nutrition platforms commanding long-term supply agreements while regional fermentation specialists capture clean-label retrofit demand. The structure fragments across three strategic archetypes: integrated taste platforms with biotechnology capabilities, yeast fermentation specialists with carbon-verified supply chains, and Mediterranean herb sourcing controllers with extraction expertise. Competitive moves concentrate on backward integration into raw material sourcing and technology licensing for precision fermentation platforms.
Within the integrated platform tier, Kerry Group plc and Givaudan occupy positions exemplifying the convergence of taste science with biotechnology-driven extraction methods. Symrise represents the raw material control archetype through its positioning across Mediterranean herb and spice growing regions. These three anchors illustrate how supplier qualification criteria under EU Green Deal procurement standards are reshaping competitive positioning.
| Leading Market Players |
|---|
| Ajinomoto Co. |
| Kerry Group plc |
| Lesaffre |
| Givaudan |
| Archer Daniels Midland Company |
| AngelYeast Co. |
| Symrise |
| Tate & Lyle |
| Sensient Technologies Corporation |
| Others |
Value Network & Pricing Analysis
EFSA flavoring regulations under EU Green Deal sustainability benchmarks gate supplier qualification and price differentiation simultaneously, compressing procurement timelines for clean-label certified extracts while elevating premiums for carbon-verified supply chains.
Pricing Analysis
German Bavarian sauce manufacturers pay premiums for EFSA-certified vegetable-derived liquid concentrates relative to standard thermal-processed alternatives. Three-tier pricing structure across premium enzymatic, standard thermal, and economy synthetic-replacement levels tracks certification grade and volume scale. Cost compression in economy tiers intensifies because yeast fermentation specialists are consolidating vendor bases. Snack food manufacturers in Illinois exhibit highest price sensitivity due to legacy equipment retrofit avoidance, while premium sauce producers in Munich show lowest sensitivity given reformulation timeline pressures.
Supply Chain Analysis
Container availability constraints on Mediterranean-to-Rotterdam lanes elevate inbound logistics costs for spice extract shipments. Upstream supply concentrates in Spain, Morocco, and Turkey for rosemary and thyme inputs, while yeast fermentation draws from dedicated facilities in Germany and the Netherlands. Raw material dependencies include nucleotide-rich mushroom substrates, Mediterranean herb harvests, and pharmaceutical-grade fermentation nutrients. Single-source vulnerability runs through concentrated Mediterranean herb growing regions exposed to climate volatility. Distribution runs through direct supplier relationships displacing layered wholesale networks for large snack food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment, where EFSA certification timelines and EU Green Deal procurement criteria create sticky supplier relationships that resist rapid displacement.
For Market Incumbents: Fortify backward integration into Mediterranean herb sourcing regions to secure supply against climate volatility. Expand aqueous enzymatic production capacity in Baden-Württemberg to capture clean-label retrofit demand from snack food manufacturers. Defend against precision fermentation startups by accelerating biotechnology licensing partnerships.
For New Entrants and Emerging Players: Anchor in mushroom extract white space for North American foodservice channels, where plant-forward menu expansion outpaces incumbent supply capacity. Target California-based restaurant chains with rapid-dissolve powder specifications optimized for reduced-sodium formulations. Pursue direct supplier relationships bypassing consolidated vendor bases.
For Investors and Strategic Acquirers: EU Green Deal procurement milestones reshape the acquisition landscape toward carbon-verified yeast fermentation specialists. Long-term viability favors platforms with integrated taste-and-nutrition capabilities spanning regulatory compliance and reformulation support. Target acquisition archetype: mid-scale biotechnology extract houses with EFSA certification and pharmaceutical-adjacent infrastructure. Monitor EFSA flavoring regulation enforcement consistency as inflection indicator for qualification cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Herb Sourcing | Secures Mediterranean supply against climate volatility for EFSA-certified extract production. |
| Precision Fermentation Platform Licensing | Enables novel nucleotide profiles for umami-forward reduced-sodium formulations. |
| Direct Supplier Relationship Consolidation | Compresses procurement layers for snack food manufacturers in California and Illinois. |
| Aqueous Enzymatic System Migration | Lowers solvent recovery burdens under REACH and EU F-Gas Regulation compliance. |
| Carbon Footprint Verification Program | Unlocks EU Green Deal preferential procurement lanes at tier-one food manufacturers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA guidance documents, EU customs trade data, and SEC filings from integrated taste platforms. Primary interviews engaged flavor chemists at extract houses, procurement leads at German sauce manufacturers, regulatory affairs specialists, and foodservice menu development directors. Secondary validation drew from REACH chemical safety assessments, EU F-Gas Regulation implementation reports, and pharmaceutical-adjacent biotechnology facility disclosures. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Segmentation dimensions modeled include product type, application, end user, and form factor across the projection horizon. Value outputs reflect unit economics by extract category, regional procurement cluster, and certification tier. CAGRs were derived from trend extrapolation of clean-label adoption curves and synthetic flavor displacement rates. Industry-specific forecast inputs incorporated EFSA compliance timeline acceleration and yeast fermentation capacity expansion trajectories.
Decision-makers should treat outputs as directional under sustained EFSA enforcement and EU Green Deal procurement adoption; material deviation would warrant model refresh. Specific risk factors include regulatory divergence between EFSA and FDA GRAS pathways, flavor chemist scarcity constraining capacity expansion, and Mediterranean harvest volatility disrupting herb supply. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Carotenoids Pigment Market
Flavorings and Food Additives
Citrus Extract Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Kokumi Flavor Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Farnesol Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market
Flavorings and Food Additives
Citrus-Based Sugar-Reduction Flavor Modulators Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
Canola Lecithin Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
Food Flavors Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
Global Vanilla (B2B) Market