
 Apple Essence Market | 2026-2036
Apple Essence Market Size, Share, and Industry Trends Forecast 2026-2036
Apple Essence Market Analytics
Subscription-based technical support for flavor formulation is pivoting how essence suppliers monetize relationships beyond ingredient sales. Symrise leverages its integrated flavor creation platforms to sustain long-term contracts with multinational beverage clients. Givaudan anchors its position through captive apple orchards in France that secure raw material traceability. Döhler competes by controlling regional distillation capacity across Central Europe.
Apple essence comprises volatile aromatic compounds—primarily 2-methylbutyl acetate, hexanal, and trans-2-hexenal—recovered through steam distillation or cold-pressing of Malus domestica fruit, then standardized to specific flavor intensity measured in fold concentrations for industrial dosing. Its primary commercial purpose centers on delivering authentic apple top-notes in formulations where fresh fruit inclusion proves impractical. Concentrated essence leads product type margins due to lower logistics costs per flavor unit, while organic essence registers the fastest expansion as EU organic certification tightens supply pools. Within end users, beverage formulation dominates volume offtake, whereas pharmaceuticals commands premium pricing for USP-grade aromatic extracts.
REACH registration through ECHA governs synthetic flavor precursor imports into Europe, while FDA FEMA GRAS determinations shape permissible use levels in US food applications. USDA organic certification and EU organic regulation jointly determine market access for premium-positioned natural extracts. Stakeholders must monitor evolving EU flavoring regulation proposals that could recategorize certain natural-identical compounds, forcing reformulation investments across existing product lines.
Market Dynamics
Clean-label beverage formulation mandates are compressing synthetic flavor substitution timelines while concentrating procurement power among multinational drink manufacturers seeking certified natural extract supply chains.
Growth Catalysts
- REACH registration protocols:ECHA compliance requirements for synthetic precursors are redirecting European beverage formulators toward verified natural essence sources, tightening supply qualification standards.
- Carbonated drink manufacturers:Premium positioning strategies in Germany are amplifying specification intensity for authentic apple top-notes in reduced-sugar formulations.
- Steam distillation recovery rates:Cold-pressing technology refinements are improving volatile compound yield efficiency from Malus domestica processing operations.
Market Restraints
- Raw material seasonality:Northern hemisphere apple harvest concentration creates 8-month supply windows requiring costly inventory carry for continuous industrial dosing.
- EU organic certification scarcity:Limited certified orchard acreage in France and Italy restricts premium-grade organic essence batch volumes.
- Natural-identical compound recategorization risk:Pending EU flavoring regulation proposals threaten reformulation investments across existing product lines using 2-methylbutyl acetate.
Strategic Opportunities
- Pharmaceutical USP-grade extracts:Aromatic compound standardization for therapeutic applications commands pricing multiples above beverage-grade equivalents.
- Subscription-based technical support:Flavor formulation advisory services create recurring revenue streams beyond commodity ingredient transactions.
- Captive orchard backward integration:Direct control over Malus domestica cultivation secures traceability documentation required by EU organic regulation and USDA organic certification.
Industry Challenges
- Flavor chemist talent scarcity:Specialized expertise in volatile compound standardization and fold concentration calibration limits formulation service expansion.
- Multi-jurisdiction compliance synchronization:Simultaneous FDA FEMA GRAS determinations, REACH registrations, and organic audits extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apple Essence Market |
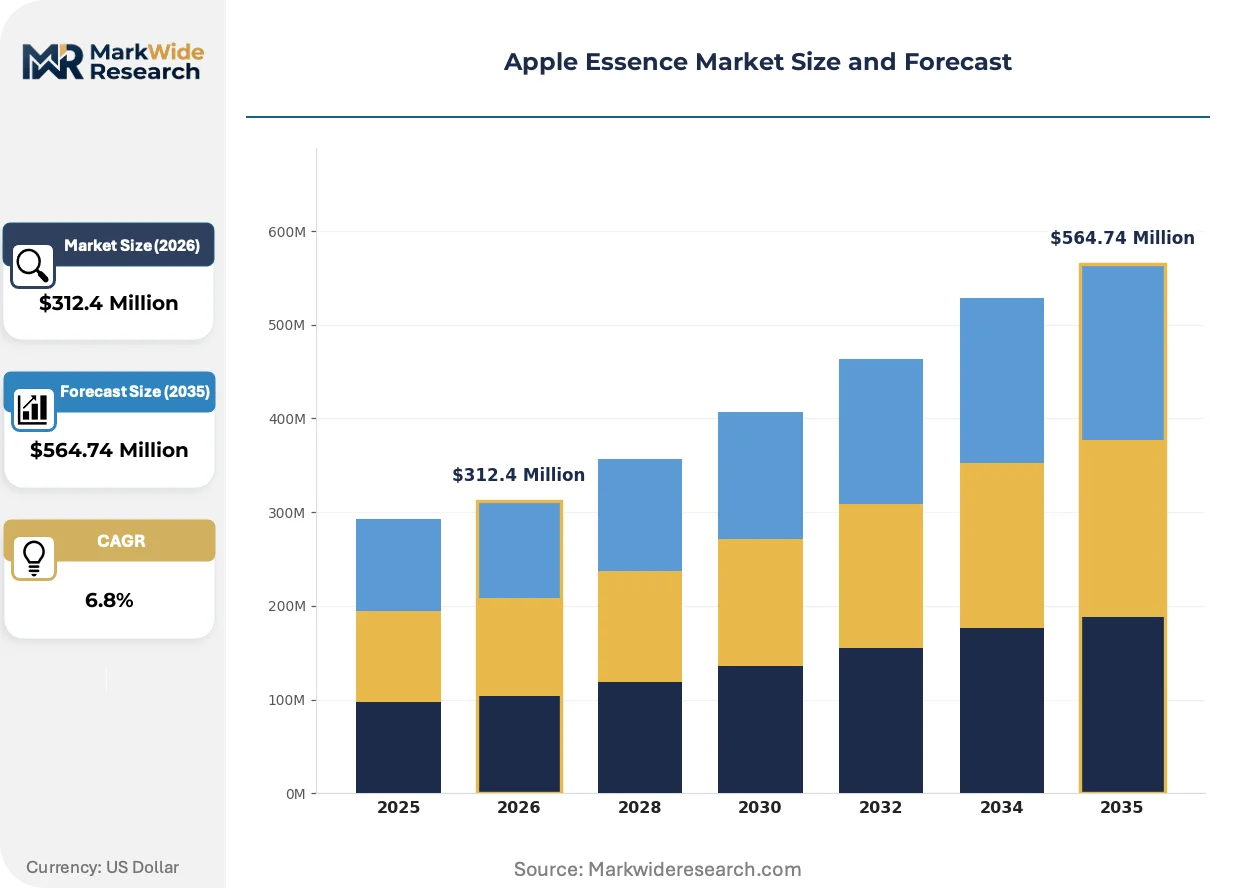
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Essence, Natural Extract, Synthetic Flavor, Organic Essence End User: Food & Beverage Industry, Cosmetics & Personal Care, Pharmaceuticals, Nutraceuticals Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Application: Baking, Beverage Formulation, Confectionery, Aroma Therapy |
| Companies Covered | R.C. Treatt, Shaanxi Fuheng (FH) Biotechnology, Shenzhen Tangzheng Biotechnology, Magical Flavour, Döhler, Symrise, Givaudan, Sensient Technologies, Frutarom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apple Essence Market Evolving Landscape
Essence suppliers are embedding analytical chemistry capabilities directly into customer technical service models, transforming ingredient transactions into collaborative formulation partnerships.
Supercritical CO2 extraction technology is integrating into commercial apple essence production lines, replacing conventional steam distillation for heat-sensitive volatile recovery. Mid-sized beverage formulators in Spain and Portugal are piloting these systems to preserve delicate ester profiles. The technology is integrating quality differentiation into supplier selection criteria, compressing margins for conventional distillation operators.
EU organic regulation tightening is mandating stricter contamination thresholds for synthetic pesticide residues in natural extracts. Batch rejection rates at French and Italian processing facilities are rising as certification bodies implement enhanced testing protocols. Organic essence suppliers are responding by contracting dedicated orchard blocks with documented integrated pest management histories.
Beverage procurement teams are consolidating supplier rosters from 15-20 vendors to 3-5 strategic partners with captive raw material sources. This concentration is visible most acutely in Germany, where premium carbonated drink manufacturers now require multi-year supply agreements with orchard-integrated processors. Technical service depth and formulation collaboration capabilities are displacing price-only selection criteria in vendor qualification scorecards.
Apple Essence Market Segmentation
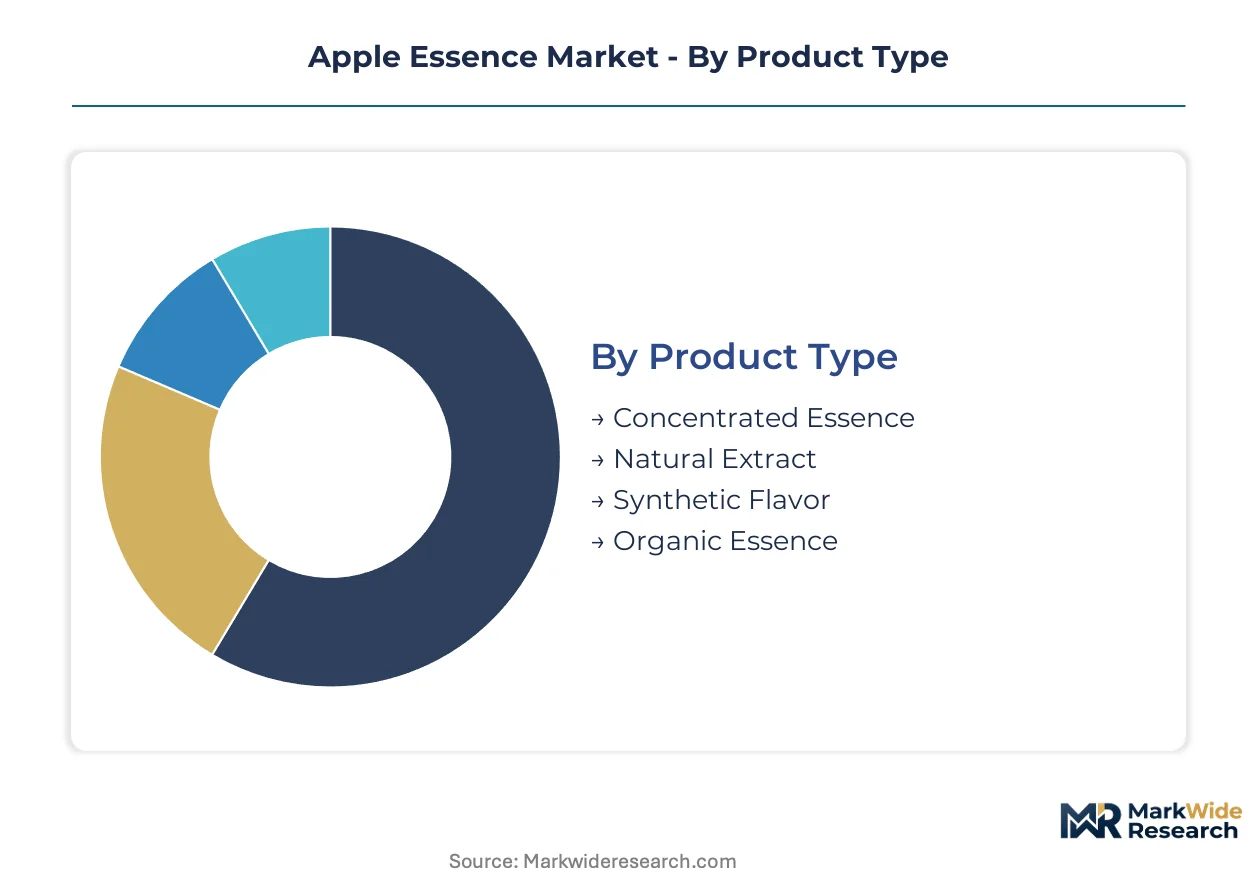
Apple essence procurement patterns diverge sharply across specification tiers and end-use requirements. Technical standards for volatile compound recovery and fold concentration calibration create distinct commercial segments with incompatible supply chains.
Product Type:
Steam distillation yield efficiency and cold-pressing technology adoption define the specification hierarchy.
- Concentrated Essence:Standardized to 150-400 fold concentrations through fractional distillation of Malus domestica volatiles. Beverage manufacturers in Germany specify concentrated grades for reduced-sugar carbonated drinks where authentic top-note intensity must survive dilution.
- Organic Essence:Derived from EU-certified orchards with documented integrated pest management histories and sub-ppm synthetic residue thresholds. French processors face rising batch rejection rates under tightened EFSA contamination protocols, restricting premium-grade volumes.
- Natural Extract:Cold-pressed or steam-distilled without fold concentration standardization. Mid-tier baking applications in Spain and Portugal absorb volume.
- Synthetic Flavor:Laboratory-synthesized 2-methylbutyl acetate and hexanal formulations. REACH registration requirements through ECHA are redirecting European formulators toward verified natural alternatives.
Mature deployment sits with Concentrated Essence. Newer deployment is concentrated in Organic Essence.
End User:
Pricing multiples and compliance intensity stratify demand across industrial buyers.
- Food & Beverage Industry:Dominates volume offtake through beverage formulation and baking applications. Clean-label mandates from multinational drink manufacturers are compressing synthetic flavor substitution timelines.
- Pharmaceuticals:USP-grade aromatic extracts for therapeutic applications command strict volatile compound standardization. Regulatory documentation requirements exceed beverage-grade specifications.
- Cosmetics & Personal Care:Fragrance compound integration for skincare and haircare formulations. Traceability documentation from captive orchard sources is displacing price-only selection criteria.
- Nutraceuticals:Functional food and dietary supplement flavor masking. Smaller batch volumes with accelerated qualification protocols.
Volume concentration rests with Food & Beverage Industry. Margin expansion is steepest in Pharmaceuticals.
Distribution Channel:
Supply chain control and technical service depth determine channel viability.
- Direct Sales:Multi-year supply agreements with orchard-integrated processors. Technical formulation collaboration and captive raw material traceability documentation.
- Specialty Stores:Small-batch procurement for artisanal food producers and independent cosmetics formulators. Limited standardization support.
- Online Retail:Catalog-based ordering for standardized fold concentrations. Growing share among mid-sized Spanish and Portuguese beverage pilot operations.
- Supermarkets:Consumer-facing small-format essence products. Minimal industrial relevance.
Procurement power concentrates through Direct Sales. Channel experimentation is visible in Online Retail.
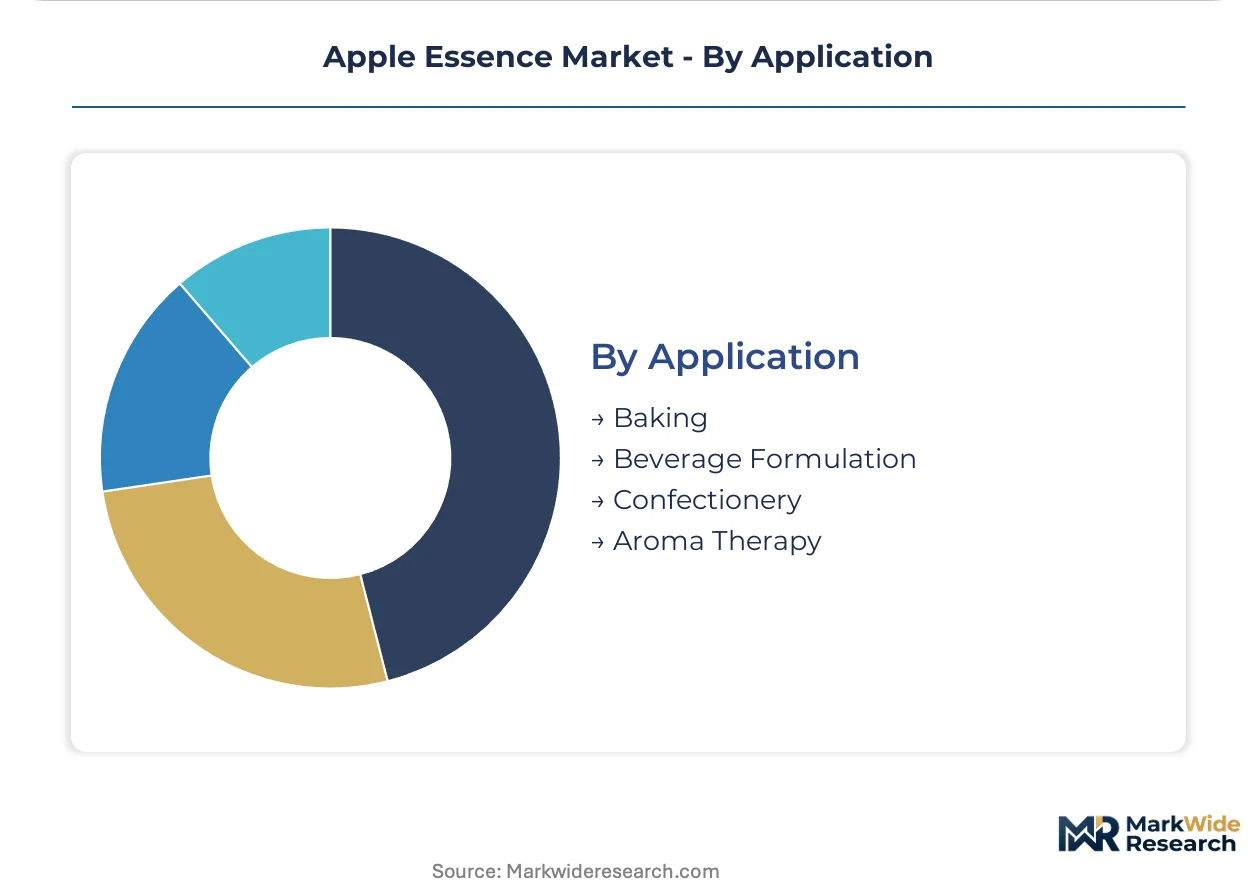
Application:
Heat stability requirements and dosing precision separate commercial use cases.
- Beverage Formulation:Carbonated drink manufacturers in Germany require authentic apple top-notes in reduced-sugar matrices. Cold-pressing technology refinements preserve delicate ester profiles against thermal degradation.
- Baking:Heat-stable volatile retention through oven cycles. Lower fold concentration specifications than beverage applications.
- Confectionery:Hard candy and gummy matrix integration with controlled release characteristics.
- Aroma Therapy:Therapeutic-grade standardization for diffusers and topical applications. Smaller addressable market with premium positioning.
Established integration characterizes Baking. Fastest adoption velocity is occurring in Beverage Formulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in European orchard regions while consumption pulls toward German beverage manufacturers and North American flavor houses. This geographic split creates specialized trade flows for certified organic grades. Cold-pressing capacity investments in France and Italy are reshaping supply reliability.
Germany
Premium carbonated drink manufacturers in Bavaria and North Rhine-Westphalia specify authentic apple top-notes for reduced-sugar formulations. REACH compliance through ECHA redirects procurement toward verified natural extract sources. Cologne-based flavor houses are consolidating supplier rosters from fifteen vendors to three strategic partners with captive orchard documentation.
France
Captive apple orchards in Normandy and the Loire Valley secure raw material traceability for EU organic certification. EFSA contamination protocols are tightening synthetic pesticide residue thresholds, elevating batch rejection rates at processing facilities. Lyon and Grasse flavor clusters are embedding analytical chemistry capabilities into customer technical service models.
United States
FDA FEMA GRAS determinations shape permissible use levels in beverage and pharmaceutical applications. USP-grade aromatic extract demand from New Jersey and Pennsylvania therapeutic manufacturers commands premium pricing multiples. California and Washington State cold-pressing operations are piloting supercritical CO2 extraction for heat-sensitive volatile recovery.
Italy
Integrated pest management histories in Trentino-Alto Adige and Emilia-Romagna orchards support premium organic essence batch volumes. EU organic regulation tightening is mandating stricter contamination documentation. Bologna and Modena processing facilities are contracting dedicated orchard blocks to secure certification compliance.
China
Shaanxi and Shandong Province biotechnology clusters are expanding steam distillation capacity for export-grade natural extracts. GB standards and SAMR food additive regulations govern domestic flavor ingredient specifications. Shenzhen and Shanghai technical service centers are developing subscription-based formulation advisory for multinational beverage clients.
Apple Essence Market Competitive Landscape
Top-tier vendors anchor integrated flavor creation platforms, while mid-scale regional processors compete on distillation capacity and orchard control. The vendor base stratifies across three tiers: multinational essence houses with captive raw material sources, European orchard-integrated processors, and Asian biotechnology specialists expanding export capabilities. Dominant competitive moves include backward integration into Malus domestica cultivation and multi-year supply agreement concentration with beverage procurement teams.
Within the integrated platform tier, Symrise, Givaudan, and Döhler represent contrasting geographic anchors for supply chain control strategies. Symrise exemplifies the flavor house archetype with technical service depth sustaining long-term multinational contracts. Givaudan occupies a position emphasizing raw material traceability through orchard ownership. Döhler sits within the regional processor vector competing on Central European distillation infrastructure and direct sales channel penetration.
| Leading Market Players |
|---|
| R.C. Treatt |
| Shaanxi Fuheng (FH) Biotechnology |
| Shenzhen Tangzheng Biotechnology |
| Magical Flavour |
| Döhler |
| Symrise |
| Givaudan |
| Sensient Technologies |
| Frutarom |
| Others |
Value Network & Pricing Analysis
EU organic regulation tightening gates both qualified supply and premium-tier pricing access, as EFSA contamination protocols elevate batch rejection rates at French and Italian processing facilities and restrict certified orchard volumes eligible for premium positioning. German beverage manufacturers now require documented integrated pest management histories and captive raw material traceability, compressing supplier rosters and amplifying pricing power for compliant processors.
Pricing Analysis
Margin tightening in organic grades reflects EU certification scarcity and rising rejection rates under EFSA protocols. Three-tier pricing structure across premium organic, standard concentrated, and economy natural extract levels stratifies the market, with certification grade and volume scale as primary differentiation drivers. Cost-down pressure on synthetic alternatives accelerates because REACH registration through ECHA redirects European formulators toward verified natural sources. Mid-sized Spanish and Portuguese beverage pilot operations demonstrate highest price sensitivity, while pharmaceutical USP-grade buyers accept substantial premiums for therapeutic-standard documentation.
Supply Chain Analysis
Specialized flavor chemist scarcity in France, Italy, and Germany constrains volatile compound standardization capacity and fold concentration calibration throughput. Supply concentrates in French and Italian orchard regions with captive cultivation, while Chinese biotechnology clusters in Shaanxi and Shandong Province expand steam distillation capacity for export-grade volumes. Raw material dependencies rest on Malus domestica harvest timing, cold-pressing equipment availability, and supercritical CO2 extraction technology access. Single-source vulnerability runs through Northern hemisphere harvest concentration creating 8-month supply windows. Distribution runs through direct sales channels with multi-year supply agreements dominating strategic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU organic certification scarcity and REACH compliance costs force smaller processors without captive orchard assets toward exit or acquisition.
For Market Incumbents: Deploy captive orchard backward integration to secure traceability documentation required by tightening EFSA protocols and USDA organic certification. Expand supercritical CO2 extraction capacity in France and Italy to differentiate against conventional distillation operators facing margin compression. Symrise and Givaudan demonstrate how integrated flavor creation platforms sustain long-term multinational contracts against emerging biotechnology specialists from China. For New Entrants and Emerging Players: REACH registration protocols in Europe open a window for verified natural essence sourcing partnerships with German beverage manufacturers consolidating supplier rosters. Target pharmaceutical USP-grade aromatic extracts where therapeutic application pricing multiples exceed beverage-grade equivalents by substantial margins. Pursue subscription-based technical support models to generate recurring revenue streams beyond commodity ingredient transactions. For Investors and Strategic Acquirers: Rising batch rejection rates at French processing facilities under tightened EU organic regulation is the leading indicator that orchard-integrated processors with documented integrated pest management histories will command sustained premium positioning. Over the medium-term horizon, acquisition targets should prioritize Central European distillation infrastructure with multi-year supply agreements already contracted to Bavarian and North Rhine-Westphalia carbonated drink manufacturers. Watch for supercritical CO2 extraction technology adoption velocity among mid-sized Spanish and Portuguese beverage formulators as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Orchard Backward Integration | Direct Malus domestica cultivation secures EU organic certification traceability documentation required by German beverage procurement teams. |
| Supercritical CO2 Extraction Scale-Up | Heat-sensitive volatile recovery technology preserves delicate ester profiles for premium reduced-sugar carbonated drink formulations. |
| Subscription-Based Technical Support Launch | Flavor formulation advisory services transform transactional ingredient sales into recurring revenue relationships with multinational clients. |
| Pharmaceutical USP-Grade Certification Investment | Therapeutic aromatic compound standardization commands pricing multiples above beverage-grade equivalents from New Jersey manufacturers. |
| Multi-Year Supply Agreement Concentration | Strategic partnerships with 3-5 orchard-integrated processors displace price-only selection criteria in German vendor qualification scorecards. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving flavor formulation directors, beverage procurement leads, orchard operations managers, and EU organic certification auditors. ECHA REACH registration databases, FDA FEMA GRAS determinations, and EFSA contamination protocol documentation provided regulatory boundary conditions. Bottom-up volume estimates from French and Italian processing facility capacities were reconciled against top-down demand projections from German carbonated drink manufacturer procurement patterns.
Data-stream reconciliation across supply-side capacity assessments and demand-side procurement surveys shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type hierarchy, end-use industry compliance intensity, distribution channel control levels, and application heat stability requirements. CAGRs were derived from trend extrapolation of clean-label substitution timelines and organic certification expansion constraints, with supercritical CO2 extraction adoption rates and EU flavoring regulation proposal progression as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for cold-pressing versus steam distillation yield efficiency would alter the outlook for volatile compound recovery economics. Forecasts reflect documented assumptions regarding REACH compliance redirection timelines and EFSA contamination threshold evolution. Material deviation in EU organic regulation finalization or FDA FEMA GRAS determination revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Sea Urchin and Roe Flavor Ingredients Market
Flavorings and Food Additives
Smoked Dextrose Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
Pine Bark Extract Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Licorice Extract Market
Flavorings and Food Additives
Flavor and Flavor Enhancers Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Mint Essential Oils Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Lemon Oil Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
Egypt Food Colorants Market