
 UK Food Flavor and Enhancer Market | 2026-2036
UK Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
UK Food Flavor and Enhancer Market Analytics
ISO 22000 certification is redrawing competitive boundaries for UK flavor suppliers. Givaudan leverages its integrated taste innovation platform to sustain premium positioning across bakery and beverage accounts. Kerry Group anchors its presence through captive dairy and savory extraction capabilities serving British food manufacturers.
Food flavors and enhancers comprise aromatic compounds, taste-active molecules, and seasoning blends formulated at precise concentrations measured in parts per million to modify or intensify sensory perception in finished products. Natural flavors command premium positioning as clean-label formulations displace artificial alternatives in processed foods and snacks. Seasonings and spice mixtures capture expanding margin pools in restaurant and catering channels where ethnic cuisine diversification accelerates volume pull.
The FSA enforces novel food authorization requirements that gate market entry for innovative botanical extracts and fermentation-derived flavor precursors. REACH compliance obligations from the broader European regulatory inheritance continue shaping chemical safety documentation burdens for artificial flavor portfolios. Stakeholders must monitor evolving UK divergence from retained EU food law as domestic regulatory autonomy crystallizes.
Market Dynamics
FSA novel food authorization timelines are compressing qualification windows for fermentation-derived flavor precursors, forcing UK manufacturers to front-load regulatory documentation before product development completes.
Growth Catalysts
- Clean-label mandates from British retailers:Major UK supermarket chains now require natural flavor declarations on private-label processed foods, pulling reformulation demand through the supply chain.
- ISO 22000 certification expansion:Food manufacturers in Greater London and the Midlands are mandating certified flavor suppliers, filtering out uncertified competitors and consolidating procurement pools.
- Ethnic cuisine diversification:Restaurant and catering channels across England are expanding authentic seasoning portfolios, creating volume pull for specialized spice blends and regional flavor profiles.
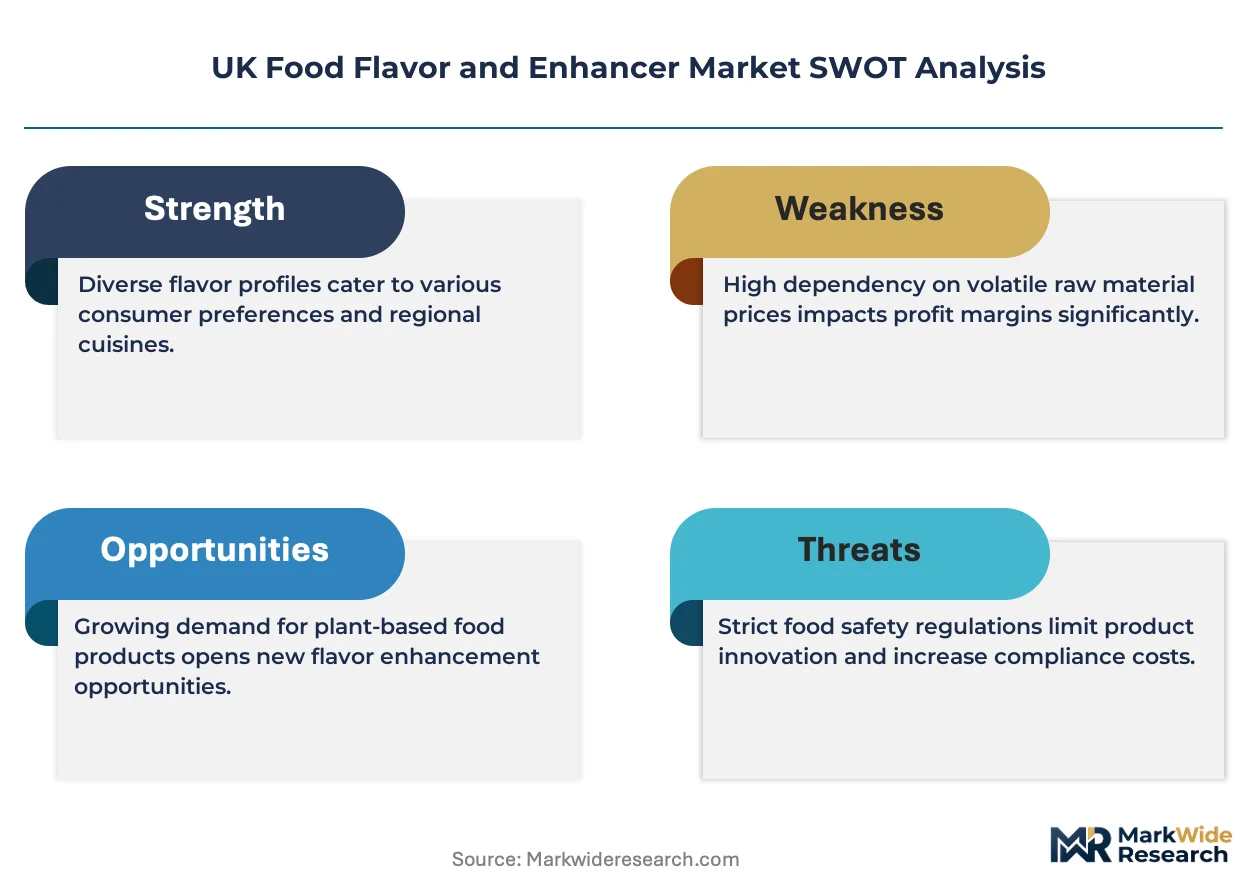
Market Restraints
- Novel food authorization costs:FSA safety assessment fees and toxicology study requirements for botanical extracts impose fixed cost barriers that disproportionately burden small and mid-sized flavor developers.
- Natural extract supply concentration:Vanilla, citrus, and spice oleoresin sourcing clusters in Madagascar, India, and Indonesia expose UK formulators to climate-driven harvest volatility and currency fluctuation.
- REACH documentation legacy:Artificial flavor portfolios retain compliance obligations for chemical safety dossiers despite UK regulatory divergence, sustaining administrative overhead without EU market access benefits.
Strategic Opportunities
- Precision fermentation scale-up:Biotech-derived flavor molecules bypass agricultural extraction constraints and novel food pathways entirely, offering UK producers cost structures decoupled from commodity crop cycles.
- Scottish and Welsh food manufacturing expansion:Devolved government food sector incentives are attracting flavor supplier co-location outside England's saturated Midlands corridor.
- Direct-to-manufacturer digital platforms:B2B flavor sample and specification portals are compressing the traditional broker-distributor channel, enabling smaller UK formulators to access national bakery and beverage accounts directly.
Industry Challenges
- Flavor chemist talent scarcity:UK university food science programs produce insufficient graduates with combined organic chemistry and sensory evaluation training, extending recruitment cycles for R&D functions.
- Clean-label reformulation complexity:Natural flavor replacements for artificial alternatives require concentration adjustments and stability testing that disrupt established production lines and extend time-to-market.
- Dual regulatory tracking burden:Flavor suppliers must simultaneously monitor FSA divergence from retained EU law and anticipate Northern Ireland protocol alignment requirements, doubling compliance monitoring headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Food Flavor and Enhancer Market |
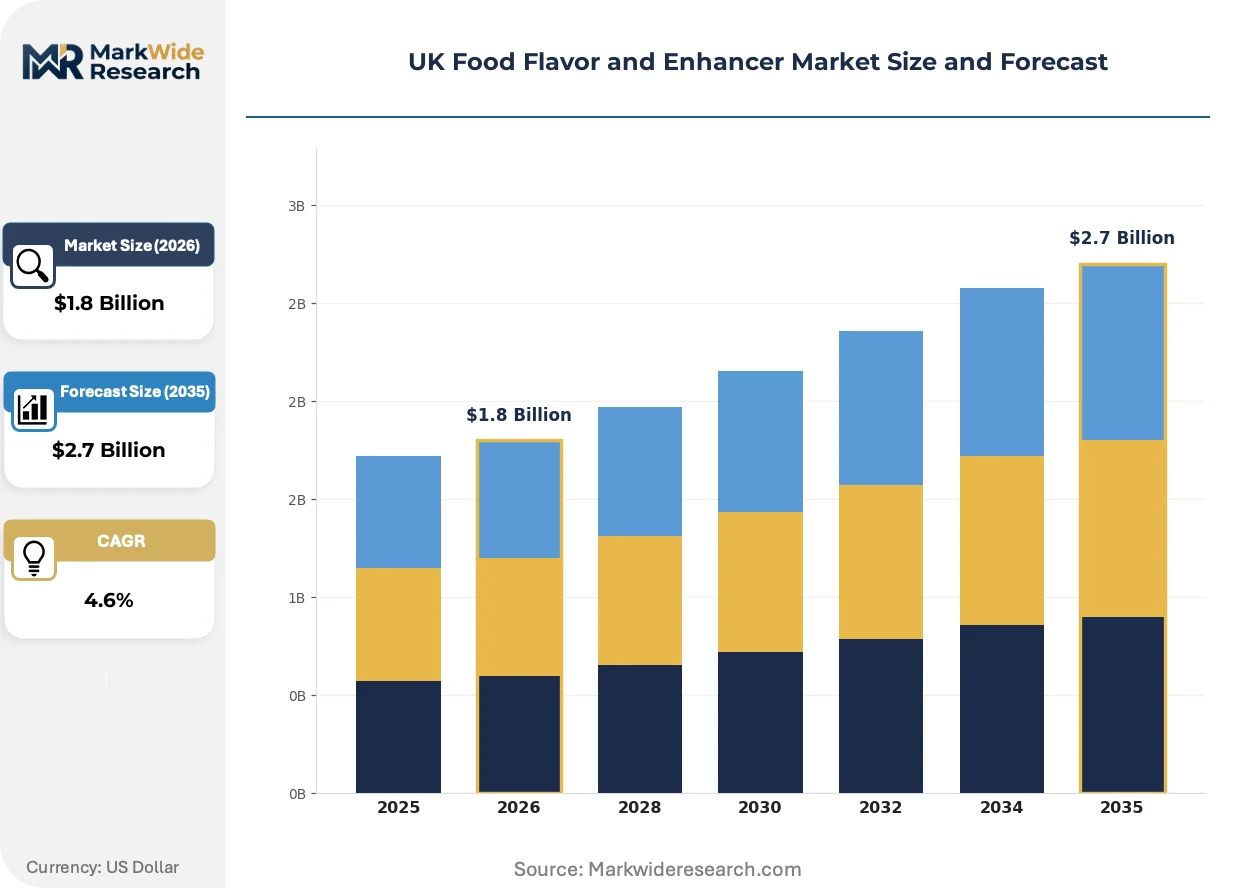
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Seasonings, Spice Mixes Application: Processed Foods, Beverages, Snacks, Bakery Products End User: Food Manufacturers, Restaurants, Catering Services, Retailers Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Specialty Stores |
| Companies Covered | Givaudan, Symrise AG, Firmenich SA, International Flavors & Fragrances Inc., Sensient Technologies Corporation, Kerry Group, Archer Daniels Midland Company, T. Hasegawa, Mane, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Food Flavor and Enhancer Market Evolving Landscape
Bioprocessing advances and regulatory pathway fragmentation are simultaneously enabling new production modalities and complicating market entry for UK flavor developers. Three distinct shifts are restructuring competitive capability requirements.
Precision fermentation infrastructure is miniaturizing. Startups and mid-scale UK producers now deploy modular bioreactor systems that slash capital requirements for biosynthetic flavor molecule production. Beverage and snack manufacturers in Manchester and Birmingham are qualifying these suppliers for pilot-scale contracts that bypass traditional agricultural extract supply chains. The technology is miniaturizing production economics, enabling distributed manufacturing models that reduce transport costs and freshness degradation risks.
FSA guidance on novel foods is hardening evidentiary standards for botanical extracts and enzyme-modified flavor precursors. The regulator now requires extended stability data and consumption exposure modeling that extends authorization timelines. Fermentation-derived and synthetic biology flavor categories face the steepest documentation burdens, pushing developers toward self-determined GRAS-equivalent pathways that carry litigation exposure but accelerate commercialization.
Buyer concentration among British supermarket private-label divisions is consolidating flavor specification authority. Procurement teams at Tesco, Sainsbury's, and Asda now mandate consolidated supplier panels with integrated taste innovation capabilities, displacing fragmented multi-vendor purchasing. This concentration is most visible in bakery and savory categories, where single-source flavor and texture solution contracts are replacing discrete ingredient procurement.
UK Food Flavor and Enhancer Market Segmentation
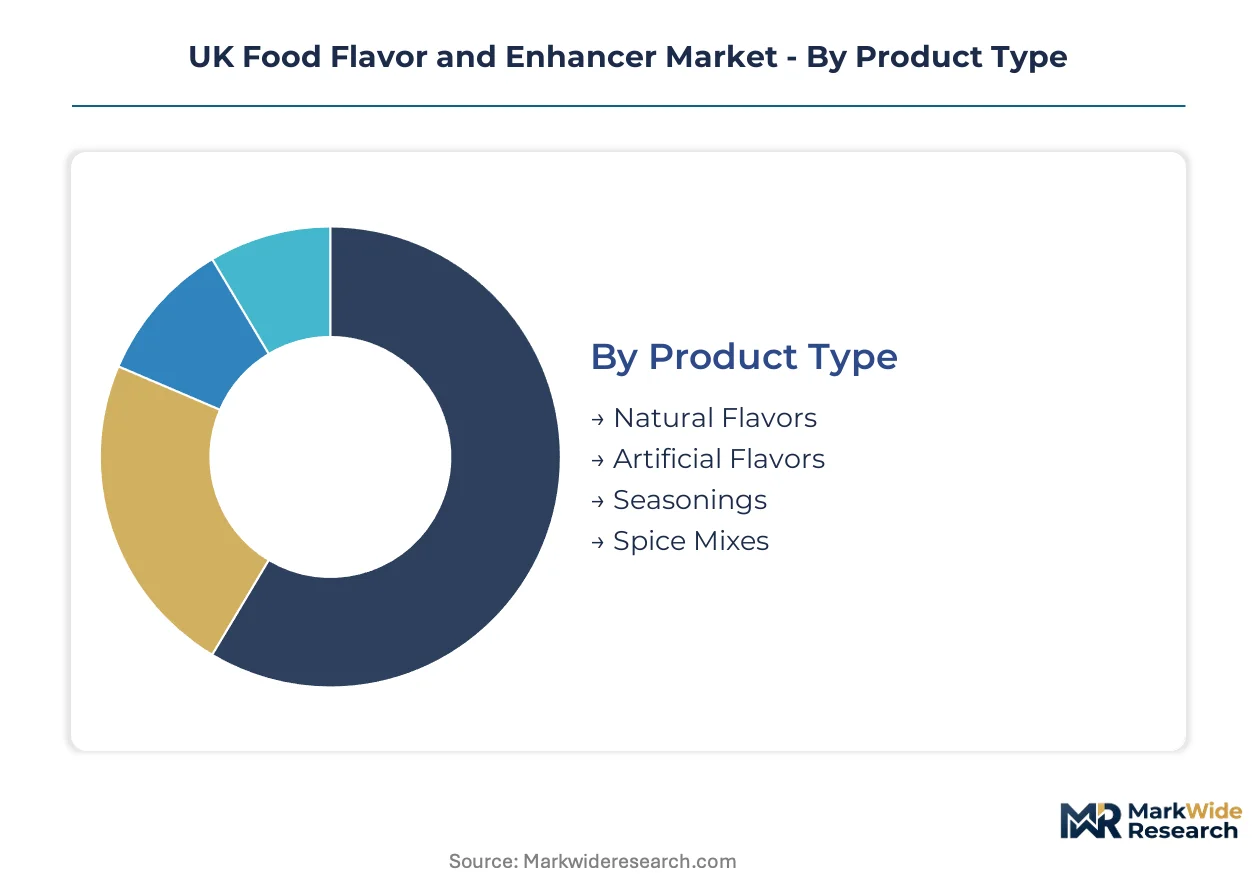
Segmentation in the UK food flavor and enhancer market reveals distinct procurement patterns across product categories and distribution channels. FSA novel food authorization requirements create divergent compliance burdens that reshape competitive positioning within each segment. Understanding these structural divisions enables suppliers to align R&D investment with the highest-margin qualification pathways.
Product Type:
FSA regulatory pathways differentiate natural and artificial flavor categories through distinct safety assessment protocols. Novel food authorization timelines compress commercialization windows for fermentation-derived natural extracts while artificial portfolios retain REACH documentation obligations.
- Natural Flavors:Botanical extracts and fermentation-derived aromatic compounds formulated without synthetic precursors. Greater London bakery manufacturers and Midlands beverage processors are mandating natural declarations on clean-label reformulations, pulling volume away from artificial alternatives despite higher input costs.
- Artificial Flavors:Chemically synthesized aromatic molecules including esters, aldehydes, and ketones manufactured through controlled organic reactions. Cost-sensitive snack producers in northern England retain artificial specifications for mass-market product lines where price positioning limits reformulation flexibility.
- Seasonings:Salt-based blends incorporating umami-active compounds and hydrolyzed proteins for savory applications.
- Spice Mixes:Ground oleoresin and essential oil combinations targeting ethnic cuisine diversification in restaurant channels.
Natural flavors handles the majority of throughput; spice mixes is the fastest mover on share.
Application:
End-use concentration across England's manufacturing belt determines flavor specification complexity and volume scale. Processed food corridors around Birmingham and Manchester impose distinct stability and shelf-life requirements that filter supplier capabilities.
- Processed Foods:Ready meals, sauces, and convenience products requiring heat-stable flavor systems with extended shelf-life performance. Midlands manufacturing clusters serving Tesco and Sainsbury's private-label divisions are consolidating procurement around ISO 22000-certified suppliers with integrated taste innovation platforms.
- Beverages:Carbonated soft drinks, juices, and functional drinks demanding water-soluble flavor compounds with pH tolerance across acidic formulations. Greater London bottling facilities are expanding natural citrus and botanical extract specifications to meet retailer clean-label mandates.
- Snacks:Savory and sweet coated products requiring oil-compatible flavor delivery systems.
- Bakery Products:Bread, cakes, and pastries needing heat-resistant volatile compounds that survive oven temperatures.
Processed foods dominates volume throughput; beverages is climbing the fastest on specification value.
End User:
Customer type dictates contract structure, with food manufacturers favoring long-term supply agreements while foodservice channels prioritize spot purchasing flexibility. Procurement centralization among British supermarket private-label divisions is compressing vendor panels.
- Food Manufacturers:Industrial-scale processors of packaged goods with formulation stability requirements and batch consistency mandates. Bakery and savory manufacturers across England are qualifying single-source flavor suppliers to replace fragmented multi-vendor purchasing.
- Restaurants:Independent and chain dining establishments sourcing authentic ethnic seasoning portfolios for menu diversification. London's restaurant density is driving volume pull for specialized spice blends and regional flavor profiles.
- Catering Services:Institutional foodservice operators with cost-driven procurement and standardized menu requirements.
- Retailers:Supermarket private-label divisions with consolidated specification authority and integrated taste innovation demands.
Food manufacturers handles the majority of throughput; restaurants is gaining share fastest on ethnic cuisine expansion.
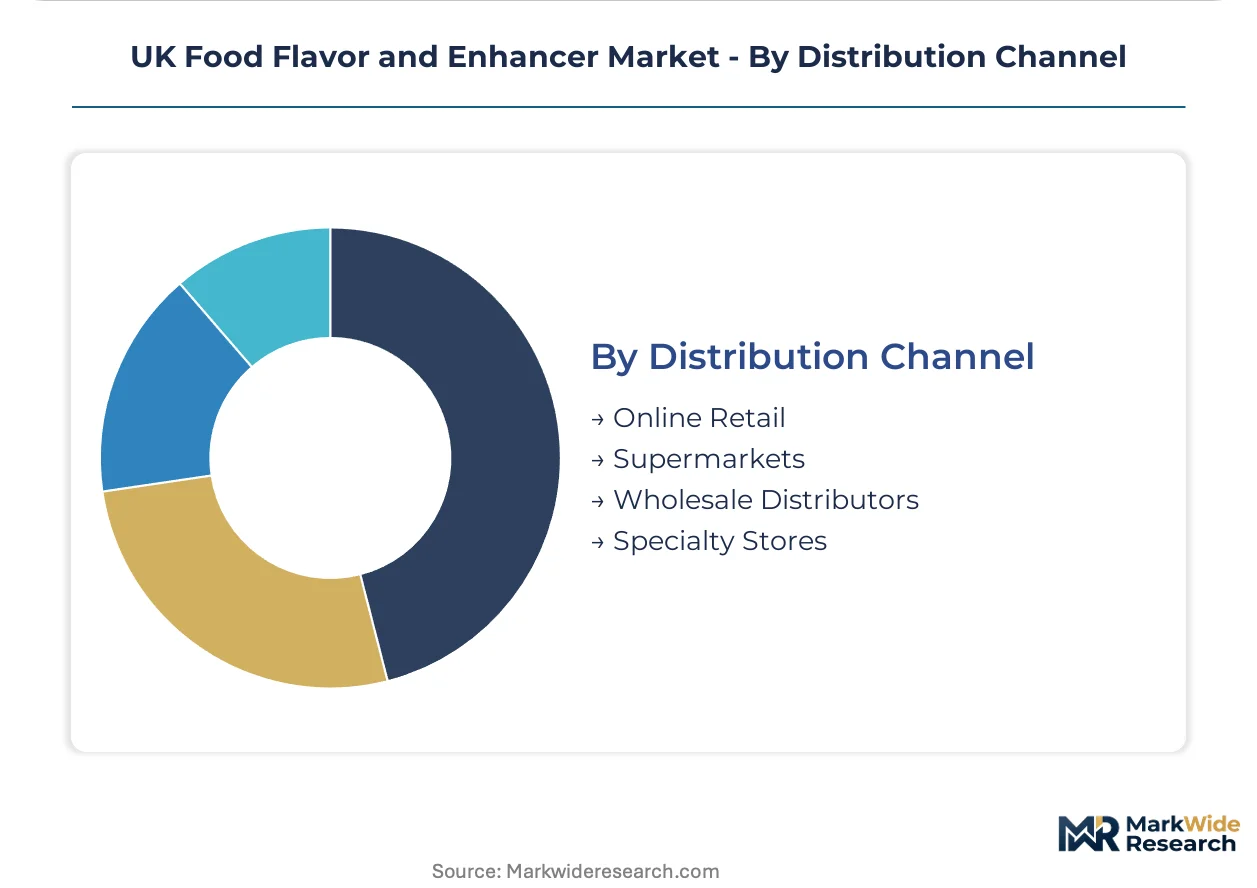
Distribution Channel:
Channel configuration determines margin capture and customer access speed. Digital platforms are compressing traditional broker-distributor hierarchies while specialty stores retain premium positioning for artisan formulators.
- Online Retail:B2B portals and direct-to-manufacturer digital platforms enabling sample ordering, specification access, and contract negotiation. Smaller UK formulators are bypassing traditional distribution to reach national bakery and beverage accounts directly.
- Supermarkets:Corporate procurement divisions controlling private-label flavor specifications with consolidated supplier panel requirements. Tesco, Sainsbury's, and Asda are mandating integrated taste innovation capabilities that displace discrete ingredient purchasing.
- Wholesale Distributors:Regional stockholding intermediaries serving food manufacturers with just-in-time delivery requirements.
- Specialty Stores:Niche suppliers targeting artisan producers and premium positioning segments.
Supermarkets dominates specification authority; online retail is expanding most quickly on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Devolved government incentives across Scotland and Wales are attracting flavor supplier co-location outside England's saturated Midlands corridor, reshaping manufacturing geography. The FSA's retained EU regulatory inheritance continues to bind all four nations while divergence accelerates. England's processed food belt still dominates volume concentration.
London and Southeast England
Greater London beverage processors are mandating natural citrus and botanical extract specifications to meet Tesco and Sainsbury's clean-label mandates. The FSA's novel food authorization requirements gate entry for innovative fermentation-derived precursors. Heathrow-adjacent logistics clusters enable just-in-time delivery to bottling facilities across the Thames Valley manufacturing zone.
Midlands Manufacturing Belt
Birmingham and Manchester food manufacturers are consolidating procurement around ISO 22000-certified suppliers with integrated taste innovation platforms. REACH compliance obligations from retained EU law sustain documentation burdens for artificial flavor portfolios. The region's ready meal and sauce production corridors impose heat-stable flavor system requirements that filter supplier capabilities.
Scotland
Scottish government food sector incentives are pulling flavor supplier investment northward from England's saturated corridors. Food Standards Scotland coordinates with the FSA on novel food assessments while maintaining distinct enforcement priorities. Edinburgh and Glasgow food manufacturing clusters are expanding savory and dairy extraction capabilities for British processors.
Wales
Welsh devolved administration economic development programs are targeting food ingredient manufacturing for regional diversification. The FSA Wales office enforces retained EU food law with emerging divergence considerations. Cardiff and Newport logistics corridors offer cost-competitive co-location for flavor distribution serving western England markets.
Northern England
Cost-sensitive snack producers across Yorkshire and Lancashire retain artificial flavor specifications for mass-market product lines where price positioning limits reformulation flexibility. The FSA's extended stability data requirements for botanical extracts disproportionately burden smaller regional formulators. Leeds and Sheffield manufacturing zones sustain legacy procurement patterns distinct from southern clean-label mandates.
UK Food Flavor and Enhancer Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded Swiss and Irish groups commanding premium positioning through integrated taste innovation platforms while private mid-scale British formulators filter into spot-market channels. The vendor base stratifies into three tiers: global integrated players with captive extraction capabilities, regional specialists with ISO 22000 certification serving supermarket private-label divisions, and artisan formulators targeting ethnic cuisine niches. M&A activity concentrates on precision fermentation startups, while capacity expansion focuses on modular bioreactor deployment for biosynthetic molecule production.
Among Switzerland-based integrated groups, Givaudan and Firmenich SA exemplify the premium-tier archetype through their positioning across bakery and beverage accounts. Irish-listed Kerry Group occupies a distinct position through its captive dairy and savory extraction capabilities. These three entities represent the consolidated procurement panels that Tesco, Sainsbury's, and Asda now mandate, displacing fragmented multi-vendor purchasing across England's manufacturing belt.
| Leading Market Players |
|---|
| Givaudan |
| Symrise AG |
| Firmenich SA |
| International Flavors & Fragrances Inc. |
| Sensient Technologies Corporation |
| Kerry Group |
| Archer Daniels Midland Company |
| T. Hasegawa |
| Mane |
| Others |
Value Network & Pricing Analysis
ISO 22000 certification gates both supplier qualification and price differentiation simultaneously, creating a bifurcated market where certified incumbents command premium positioning while uncertified competitors filter into spot-market channels serving cost-sensitive northern England snack producers.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers. Three-tier pricing structure across certified-natural, uncertified-natural, and artificial specifications prevails. Cost compression in artificial flavor tiers intensifies because REACH documentation obligations sustain administrative overhead without EU market access benefits. Food manufacturers in the Midlands demonstrate least price sensitivity due to consolidated procurement mandates from Tesco and Sainsbury's private-label divisions.
Supply Chain Analysis
Just-in-time delivery preferences dominate among Greater London beverage processors, while strategic stockpiling characterizes spice oleoresin procurement given Madagascar, India, and Indonesia sourcing concentration. Vanilla, citrus extracts, and hydrolyzed proteins constitute critical input dependencies. Single-source vulnerability in botanical extract supply exposes UK formulators to climate-driven harvest volatility. Distribution runs through supermarket private-label procurement divisions with consolidated supplier panel requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FSA novel food authorization timelines create switching costs that lock in qualified suppliers and repel rapid competitive entry.
For Market Incumbents: Secure captive extraction capabilities through backward integration into Scottish and Welsh dairy and savory processing clusters. Expand ISO 22000-certified capacity in Edinburgh and Glasgow to preempt devolved government incentive competition. Precision fermentation startups threaten traditional agricultural extract positioning; defend by accelerating modular bioreactor deployment for biosynthetic molecule production. For New Entrants and Emerging Players: Anchor in Northern England cost-sensitive snack segments where artificial flavor specifications persist and incumbent certification mandates have weakest penetration. Target Yorkshire and Lancashire manufacturing zones with direct-to-manufacturer digital platforms that bypass traditional broker-distributor channels. Qualify for spot-market supply to regional formulators lacking Tesco and Sainsbury's panel access. For Investors and Strategic Acquirers: FSA divergence from retained EU law reshapes the acquisition landscape by extending compliance monitoring headcount requirements and favoring scaled players with dedicated regulatory affairs functions. Long-term viability centers on precision fermentation infrastructure that bypasses agricultural commodity cycles. Target mid-scale British formulators with modular bioreactor pilots and established supermarket relationships. Watch for Northern Ireland protocol alignment requirements as inflection signal for dual regulatory tracking burden intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Biosynthetic production decouples flavor molecules from Madagascar vanilla harvest volatility. |
| ISO 22000 Certification Investment | Qualification gates access to Tesco and Sainsbury's consolidated procurement panels. |
| Scottish Co-Location Expansion | Devolved government incentives reduce cost base versus England's saturated Midlands corridor. |
| Direct-to-Manufacturer Platform Launch | Digital channels compress broker-distributor hierarchies and accelerate sample-to-contract velocity. |
| Novel Food Authorization Front-Loading | Early regulatory documentation investment compresses FSA qualification windows for fermentation-derived precursors. |
Research Methodology
Cross-validation between primary fieldwork with flavor chemists and procurement directors and secondary validation through FSA guidance documents and supermarket private-label specification databases anchors the qualitative findings. Industry stakeholders interviewed include R&D directors at Midlands beverage processors, category buyers at Tesco and Sainsbury's, regulatory affairs leads navigating novel food pathways, and plant managers at Scottish dairy extraction facilities. Secondary sources encompass FSA novel food authorization registers, REACH compliance documentation, customs trade data for vanilla and spice oleoresin imports, and SEC filings from listed Swiss and Irish integrated flavor groups. Bottom-up volume modeling triangulates against top-down value estimates across the projection horizon.
Sensitivity analysis frames the quantitative outputs, with segmentation modeled across natural versus artificial flavor type, processed foods versus beverages versus snacks application, and food manufacturer versus foodservice end-user. CAGRs derive from trend extrapolation anchored in clean-label mandate intensity and ethnic cuisine diversification velocity. Industry-specific forecast inputs include FSA authorization timeline compression rates and precision fermentation capacity buildout trajectories.
Decision-makers should treat outputs as directional under stable FSA regulatory divergence assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions around continued supermarket private-label consolidation and sustained REACH documentation obligations. Revision becomes warranted when Northern Ireland protocol alignment requirements cross thresholds that fundamentally alter dual regulatory tracking economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Browning Enhancers Market
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Brazzein Market
Food Enhancers and Additives
North America Food Flavor and Enhancer Market
Food Enhancers and Additives
Fortified Salts Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Canada Food Flavor and Enhancer Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
Yellow Fats Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
United Kingdom Interesterified Fats Market
Food Enhancers and Additives
Africa Water Enhancer Market