

Neuro-Sensory Flavored Beverages Innovation Market Size, Share, and Industry Trends Forecast 2026-2036
Neuro-Sensory Flavored Beverages Innovation Market Insights
Revenue-based licensing of proprietary flavor modulation platforms is reconfiguring capital requirements for new entrants in the neuro-sensory beverage space. Givaudan leverages its captive biotech research infrastructure to sustain formulation leadership across cognitive-enhancement applications. Kerry Group anchors European supply through integrated taste and nutrition service bundles that reduce client switching costs. Sensient Technologies competes via specialized natural-extraction capabilities that command premium positioning in clean-label adaptogenic blends.
Neuro-sensory flavored beverages integrate bioactive compounds, volatile aromatic molecules, and taste-modulating peptides to trigger targeted neurological responses including alertness modulation or stress reduction. Manufacturing employs microencapsulation and emulsion stabilization to preserve volatile actives through pasteurization and shelf storage. Functional drinks dominate current revenue as established distribution infrastructure accelerates placement in convenience and wellness retail channels. Cognitive Enhancement applications lead volume growth as working professionals and students substitute nootropic beverages for traditional caffeine sources. Adaptogenic Blends represent the fastest-expanding product type, with margin pools concentrating in proprietary botanical extraction methods and clinical substantiation packages.
FDA GRAS self-affirmation pathways and EFSA novel food consultations shape formulation choices and market access timelines for neuro-active ingredients in the United States and European Union respectively. The country's national pharmaceutical regulator in India evaluates borderline nutraceutical claims through FSSAI licensing, creating compliance complexity for imported functional beverages. Stakeholders must monitor evolving nootropic substance scheduling decisions across key jurisdictions to anticipate reformulation requirements and distribution restrictions.
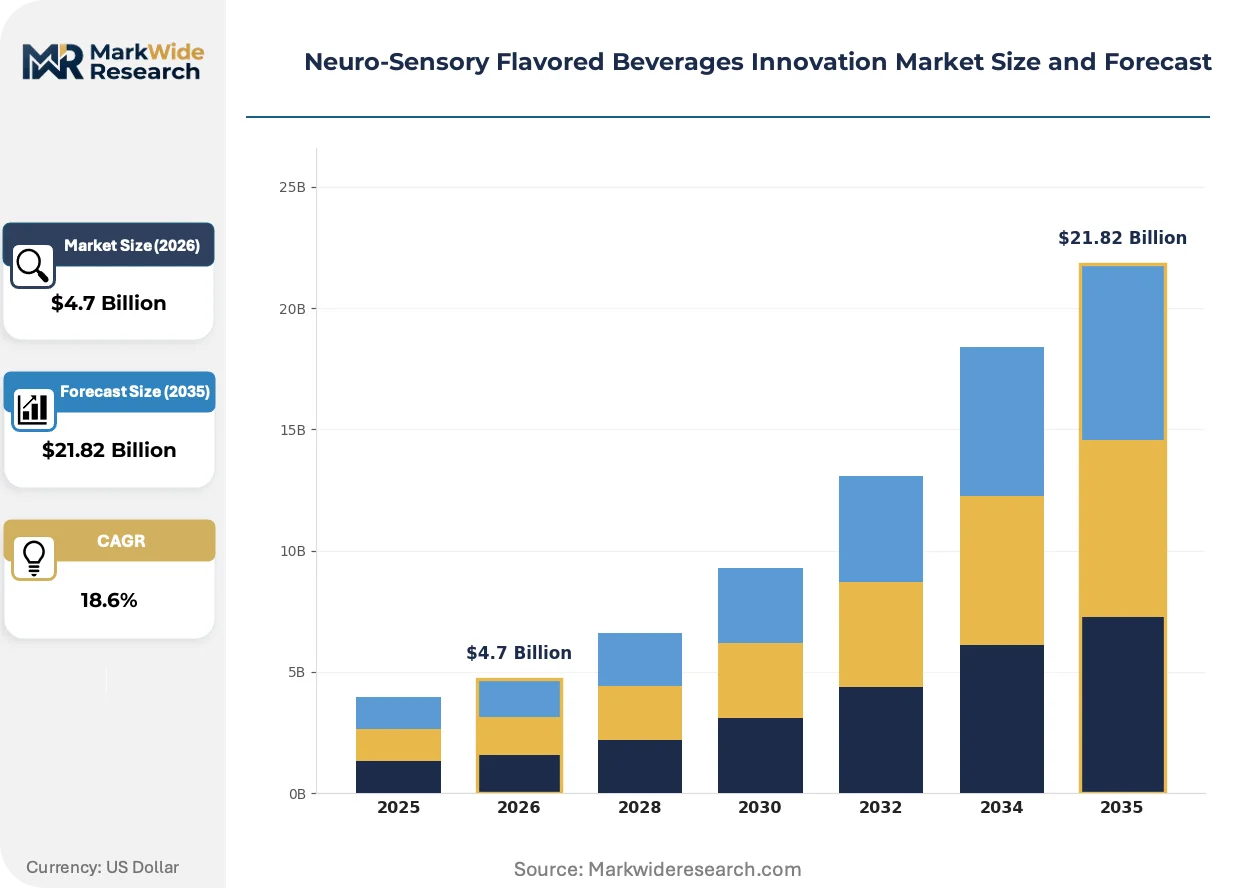
Market Dynamics
Direct-to-consumer subscription models are compressing traditional retail shelf cycles while forcing rapid formulation iteration. Microencapsulation advances now enable pasteurization-stable nootropic delivery, but FDA GRAS self-affirmation timelines and EFSA novel food consultations create divergent market access speeds across jurisdictions.
Growth Catalysts
- Adaptogenic ingredient pipelines:Botanical extraction methods for ashwagandha and rhodiola are achieving clinical substantiation packages that unlock wellness retail placement. Clean-label positioning accelerates trial rates among young adults.
- EFSA novel food pathway maturation:Streamlined consultations for L-theanine and GABA derivatives reduce European market entry friction. Manufacturers leverage these precedents to fast-track subsequent filings.
- Cognitive enhancement demand from working professionals:Nootropic beverages substitute traditional caffeine sources in knowledge-economy employment clusters. Subscription retention rates exceed conventional functional drink benchmarks.
Market Restraints
- Volatile botanical input costs:Rhodiola rosea and bacopa monnieri harvests concentrate in limited alpine and subtropical zones. Weather-driven supply shocks transmit directly to COGS.
- GRAS affirmation cost barriers:FDA self-affirmation requires toxicology dossiers exceeding mid-tier manufacturer R&D budgets. Capital concentration favors established flavor houses with captive biotech infrastructure.
- Technical stability limitations:Volatile aromatic molecules degrade through standard hot-fill pasteurization. Shelf-life compression restricts convenience channel distribution.
Strategic Opportunities
- Underpenetrated Indian wellness retail:FSSAI licensing complexity has delayed multinational entry. Local formulation partnerships bypass import claim restrictions.
- Sports performance application expansion:Pre-workout nootropic stacks with electrolyte matrices target amateur athletic segments. This application currently lacks dedicated SKUs.
- EU Green Deal packaging mandates:Recyclable mono-material bottles receive preferential retail placement. Early compliance creates shelf-space advantages.
Industry Challenges
- Clinical substantiation talent scarcity:Neuropharmacology PhDs with beverage formulation experience command premium compensation. Recruitment bottlenecks delay pipeline velocity.
- Microencapsulation capex intensity:Spray-drying and coacervation equipment requires seven-figure facility investments. Scale economics disadvantage emerging brands.
- Cross-jurisdiction claim harmonization:Cognitive enhancement messaging permissible under US structure-function rules triggers pharmaceutical reclassification in multiple EU member states. Legal review costs compound.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuro-Sensory Flavored Beverages Innovation Market Trends and Innovations
Formulation science is converging with neuropharmacology to create measurable cognitive endpoints. This convergence demands new testing protocols and accelerates partnership structures between ingredient suppliers and clinical research organizations.
Lipid-based nano-delivery systems are hybridizing with traditional emulsion stabilization to protect volatile nootropics through thermal processing. Beverage manufacturers in the United States and Germany adopt these platforms at pilot scale. The technology is hybridizing supply chain requirements, forcing ingredient suppliers to integrate encapsulation services or cede margin to specialized technology licensors.
EFSA's 2023 guidance on cognitive health claims has tightened evidentiary standards for novel food approvals. Manufacturers must now submit randomized controlled trials rather than observational data. Adaptogenic blend categories face the steepest compliance cost increases, with several pending applications withdrawn for additional endpoint testing.
Young adults now purchase functional beverages through telehealth-integrated wellness platforms rather than conventional grocery channels. These platforms bundle biometric tracking with personalized nootropic subscriptions. The behavior shift concentrates in coastal United States metropolitan markets where direct-to-consumer logistics infrastructure is densest.
Neuro-Sensory Flavored Beverages Innovation Market Segmentation
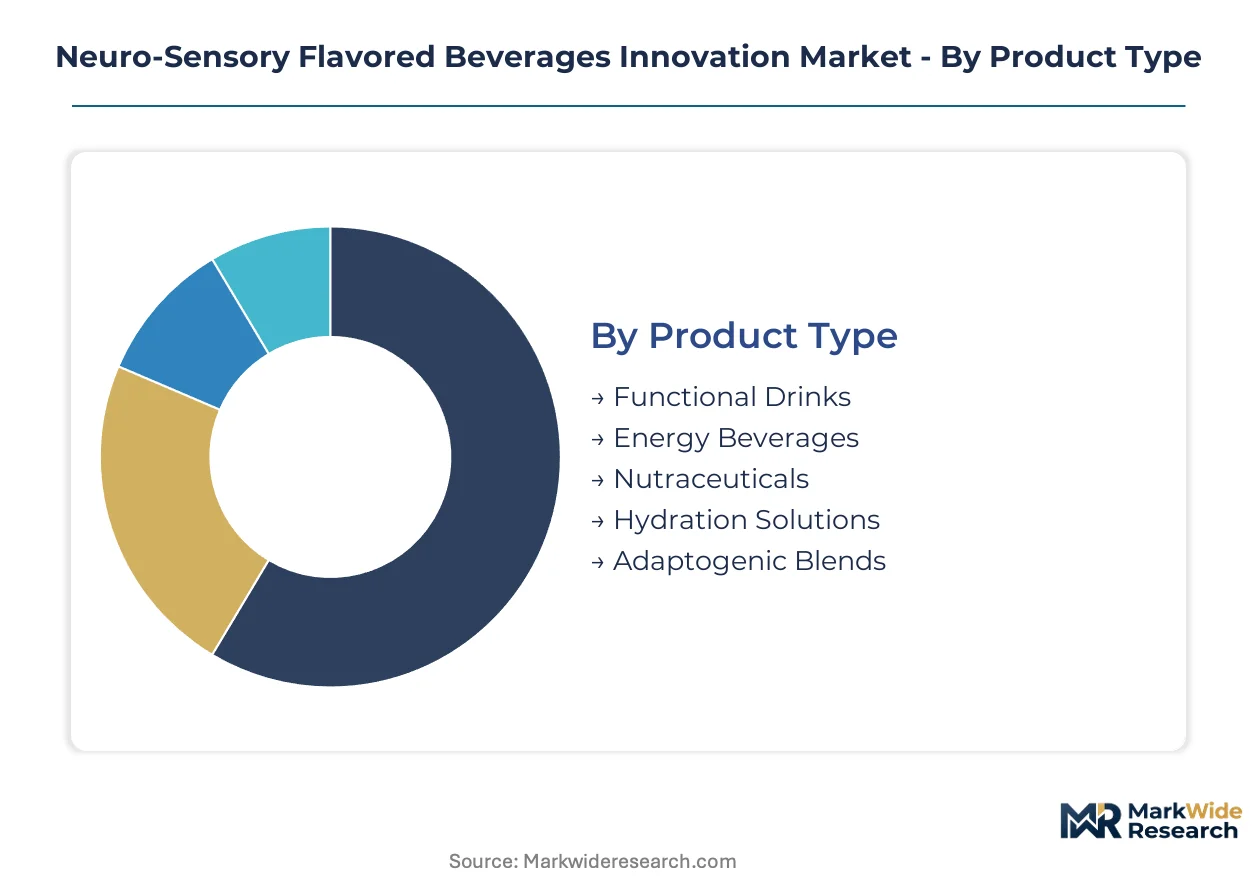
Neuro-sensory beverage manufacturers navigate four distinct segmentation axes that determine formulation priorities, channel strategy, and margin architecture. Product type and application define technical requirements, while flavor profile and end-user demographics shape positioning and pricing power.
Product Type:
Functional drinks span alertness modulation, metabolic support, and immune function through bioactive peptide and botanical combinations. Energy beverages rely on caffeine-adaptogen matrices that extend duration without jitters. Nutraceuticals deliver clinical-grade nootropic dosing with substantiation packages. Hydration solutions integrate electrolytes with stress-reducing amino acids. Adaptogenic Blends command premium positioning through proprietary extraction methods and multi-herb synergies.
- Functional Drinks:These products integrate bioactive compounds, volatile aromatic molecules, and taste-modulating peptides to trigger targeted neurological responses. Demand concentrates in the United States where direct-to-consumer subscription models and wellness retail chains drive trial and repeat purchase rates.
- Adaptogenic Blends:Proprietary botanical extraction methods and clinical substantiation packages create defensible margin pools. Young adults represent the fastest-expanding end-user demographic as these functional beverages displace conventional soft drinks.
- Energy Beverages:Caffeine-adaptogen matrices extend stimulant duration while reducing sympathetic nervous system overload.
- Nutraceuticals:Clinical-grade nootropic dosing requires FDA GRAS self-affirmation or EFSA novel food consultation pathways.
- Hydration Solutions:Electrolyte-amino acid combinations target athletic recovery and cognitive performance maintenance.
The dominant share belongs to Functional Drinks, while Adaptogenic Blends is closing the gap fastest.
Flavor Profile:
Flavor selection in neuro-sensory beverages operates on a cost-to-positioning spectrum. Citrus and berry profiles leverage commodity extract supply chains. Herbal, spice, and floral categories require specialized sourcing and command formulation premiums.
- Citrus Infusions:Limonene and other volatile terpenes provide natural mood elevation through olfactory pathways. Working professionals in coastal United States metropolitan markets prefer these profiles for morning consumption rituals.
- Herbal Extracts:Rosemary, sage, and bacopa deliver nootropic effects through rosmarinic acid and bacoside compounds. Supply concentrates in Mediterranean and subtropical cultivation zones with weather-driven harvest variability.
- Spiced Tones:Cinnamon, ginger, and turmeric extracts provide anti-inflammatory and thermogenic secondary benefits.
- Floral Aromas:Lavender, chamomile, and passionflower target GABAergic stress reduction pathways.
- Berry Mixes:Anthocyanin-rich blends appeal to antioxidant-conscious consumers seeking cognitive protection claims.
Citrus Infusions anchor volume shipments, though Herbal Extracts are gaining share fastest through wellness retail expansion.
Application:
Application segmentation maps directly to neuropharmacological targets and daily use-case timing. Morning-positioned products emphasize dopaminergic and cholinergic pathways. Evening formulations prioritize GABA modulation and cortisol reduction.
- Cognitive Enhancement:Nootropic beverages substitute traditional caffeine sources in knowledge-economy employment clusters. Subscription retention rates exceed conventional functional drink benchmarks.
- Stress Relief:Cortisol-modulating adaptogens target high-pressure professional environments with measurable biomarker endpoints.
- Sleep Support:Melatonin-free GABA and magnesium formulations avoid next-day grogginess.
- Mood Elevation:Serotonin precursor and anandamide reuptake inhibitor combinations address subclinical mood variation.
- Focus Improvement:Sustained attention formulations compete with prescription stimulants in academic and creative professional segments.
Cognitive Enhancement commands the largest revenue pool, while Stress Relief is expanding most quickly through corporate wellness program adoption.
End User:
End-user segmentation reveals divergent channel preferences and price elasticity profiles. Digital-native demographics favor subscription and telehealth-integrated platforms. Established professionals retain higher retail loyalty but demand clinical substantiation.
- Young Adults:This demographic purchases functional beverages through telehealth-integrated wellness platforms rather than conventional grocery channels. These platforms bundle biometric tracking with personalized nootropic subscriptions.
- Working Professionals:Knowledge-economy employees substitute nootropic beverages for traditional caffeine sources in employment clusters.
- Fitness Enthusiasts:Pre-workout nootropic stacks with electrolyte matrices target amateur athletic segments.
- Students:Academic performance pressure drives trial of focus-enhancing formulations during examination periods.
- Seniors:Neuroprotective claims require stricter clinical substantiation to overcome skepticism in this demographic.
Young Adults generate the highest subscription retention, while Working Professionals are converting to habitual use fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States metropolitan corridors while European manufacturers absorb EFSA compliance premiums. Subscription retention rates in coastal American cities exceed wellness retail benchmarks by significant margins. Regulatory divergence between FDA self-affirmation and EFSA novel food pathways creates asymmetric market entry timelines.
United States
Direct-to-consumer subscription models dominate trial acquisition in coastal metropolitan markets. FDA GRAS self-affirmation pathways allow rapid formulation iteration for nootropic ingredients. Boston and San Francisco employment clusters drive habitual consumption among knowledge-economy professionals seeking caffeine alternatives.
Germany
EFSA novel food consultations create extended approval timelines for adaptogenic botanicals. Kerry Group anchors European supply through integrated taste and nutrition service bundles. Munich and Hamburg wellness retail chains command premium shelf placement for clinical-grade nootropic formulations.
India
FSSAI licensing complexity delays multinational entry into underpenetrated wellness retail channels. The country's national pharmaceutical regulator evaluates borderline nutraceutical claims through stringent import restrictions. Mumbai and Bangalore formulation partnerships bypass regulatory barriers for local production.
United Kingdom
Telehealth-integrated wellness platforms concentrate subscription growth in London metropolitan corridors. MHRA borderline substance guidance shapes nootropic ingredient import policies. Cambridge and Oxford academic clusters generate demand for focus-enhancing beverages among research professionals.
Japan
Consumer familiarity with functional foods accelerates nootropic beverage acceptance in Tokyo and Osaka. PMDA consultation requirements for novel food ingredients extend market access timelines. METI support programs for health-conscious product innovation subsidize domestic formulation R&D.
Neuro-Sensory Flavored Beverages Innovation Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in extraction and encapsulation technology. The vendor base stratifies between captive biotech infrastructure holders and outsourced formulation service providers. Three archetypes dominate: integrated flavor houses with proprietary delivery platforms, specialized natural-extraction contractors, and contract manufacturers with clinical substantiation capabilities. M&A activity concentrates on botanical extraction assets and microencapsulation technology licensors.
Among Swiss-headquartered platform integrators, Givaudan and Firmenich International exemplify the captive research infrastructure archetype. dsm-firmenich occupies a position bridging nutrition science and sensory formulation. Kerry Group represents the integrated service bundle model with European supply chain concentration. These entities anchor competitive dynamics through revenue-based licensing of proprietary flavor modulation platforms.
| Leading Market Players |
|---|
| Givaudan |
| dsm-firmenich |
| International Flavors & Fragrances |
| Symrise |
| Kerry Group |
| T. Hasegawa |
| Sensient Technologies |
| Firmenich International |
| Glanbia |
| Others |
Pricing and Supply Chain Analysis
Rhodiola rosea harvests in alpine Central Asia and bacopa monnieri cultivation in subtropical India concentrate upstream supply for adaptogenic actives, concentrating margin pools with extractors possessing captive botanical sourcing and clinical substantiation capabilities.
Pricing Analysis
Configured-to-order pricing for proprietary adaptogenic blends commands substantial premiums over standard functional drink formulations. Three-tier pricing structure across premium, standard, and economy levels segments by clinical substantiation depth and botanical extraction method. Price differentiation hinges on GRAS affirmation status and clean-label certification tier. Pricing pressure stems from volatile harvest yields in concentrated cultivation zones. Subscription-based buyers in coastal United States metropolitan markets exhibit lowest price sensitivity, while convenience channel distributors face acute margin compression.
Supply Chain Analysis
Upstream feedstock for nootropic actives draws from India, China, and alpine Central Asian republics for botanical inputs, with volatile aromatic molecules sourced from Mediterranean cultivation zones. Raw material dependencies center on ashwagandha rootstock, rhodiola rosea, bacopa monnieri, and specialized terpene extracts. Single-source vulnerability concentrates in alpine rhodiola harvests exposed to weather-driven supply shocks. Distribution runs through direct-to-consumer subscription platforms and wellness retail chains in the United States, with European channels absorbing EFSA compliance premiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward telehealth-integrated wellness platforms and subscription aggregators, as channel consolidation among young adult demographics compresses traditional retail negotiation leverage.
For Market Incumbents: Harden formulation moats through captive microencapsulation infrastructure and accelerated GRAS affirmation pipelines. Deepen backward integration into alpine rhodiola and subtropical bacopa cultivation to offset harvest volatility. Secure exclusive clinical substantiation partnerships with research organizations before EFSA evidentiary standards tighten further. For New Entrants and Emerging Players: Build out sports performance nootropic stacks targeting amateur athletic segments, the most penetrable white-space application lacking dedicated SKUs. Establish local formulation partnerships in India to bypass FSSAI import restrictions. Pursue telehealth platform distribution partnerships rather than conventional grocery channel slotting. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers possessing clinical substantiation capabilities but lacking captive extraction infrastructure. Long-term viability favors platforms integrating formulation science with neuropharmacology testing protocols. Watch for EFSA novel food consultation withdrawals as inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Substantiation Partnership | Randomized controlled trial packages unlock EFSA novel food approvals and wellness retail placement. |
| Captive Botanical Extraction | Proprietary ashwagandha and rhodiola processing secures margin pools against commodity price volatility. |
| Direct-to-Consumer Platform Launch | Subscription models in coastal United States metropolitan markets exceed conventional retail retention benchmarks. |
| Microencapsulation Technology Licensing | Pasteurization-stable nootropic delivery opens convenience channel distribution previously restricted by shelf-life limitations. |
| Local Formulation Joint Venture | Indian production partnerships bypass FSSAI import claim restrictions for underpenetrated wellness retail channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across beverage formulation scientists, neuropharmacology researchers, wellness retail category buyers, direct-to-consumer platform operators, and regulatory affairs specialists. Secondary validation drew from FDA GRAS notification databases, EFSA novel food consultation registers, FSSAI licensing records, customs import data, and clinical trial registries. Bottom-up volume modeling triangulated against top-down expenditure estimates across product type, application, flavor profile, and end-user demographic segments.
Calibration anchored historical consumption patterns to observed subscription retention rates and wellness retail scan data across the analysis window. Segmentation dimensions modeled include product type, application, flavor profile, and end-user demographic with regional regulatory cluster overlays. CAGRs were derived from growth rate convergence analysis. Forecast inputs incorporated EFSA consultation timeline assumptions and microencapsulation technology adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by flavor houses or regulatory acceleration by FDA would shift outcomes. Cross-checking against Nielsen wellness beverage retail audit data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.