
 Nature Identical Flavorings Market | 2026-2036
Nature Identical Flavorings Market Size, Share, and Industry Trends Forecast 2026-2036
Nature Identical Flavorings Market Foresight
Flavor chemist talent pools in Europe is rotating toward biotech-derived synthesis methods, tightening supply of traditional organic chemists. Döhler GmbH leverages its integrated extraction and compounding infrastructure across German production sites. MANE sustains competitive advantage through deep specialization in encapsulated aroma delivery systems. Keva Flavours Pvt. Ltd. anchors its expansion on powder-form flavor capabilities serving snack industry clients in South Asia.
Nature identical flavorings are chemically synthesized compounds that match the molecular structure of natural flavor substances found in plants, fruits, or spices, typically manufactured through microbial fermentation, enzymatic catalysis, or precision organic synthesis to achieve purity thresholds exceeding commercial natural extracts. These compounds serve industrial food and beverage manufacturers seeking consistent sensory profiles, cost stability, and scalable supply independent of agricultural harvest variability. Liquid formulations dominate volume throughput in beverage applications due to ease of inline dosing, while powder forms command margin premiums in bakery and confectionery segments where thermal stability and shelf-life extension determine procurement decisions. Aroma compounds represent the fastest-growing product category as manufacturers replace vanillin and citrus extracts with fermentation-derived equivalents.
EMA and EFSA frameworks in Europe govern safety assessments and maximum usage levels for nature identical flavorings in food contact applications, while REACH compliance mandates full toxicological dossiers for synthetic aroma precursors. FDA GRAS self-determination in the United States creates divergent market access pathways that fragment regulatory strategy for multinational suppliers. Stakeholders must monitor evolving EU Green Deal bio-based content thresholds and FDA enforcement discretion on fermentation-derived ingredients to anticipate reformulation mandates and qualification timelines.
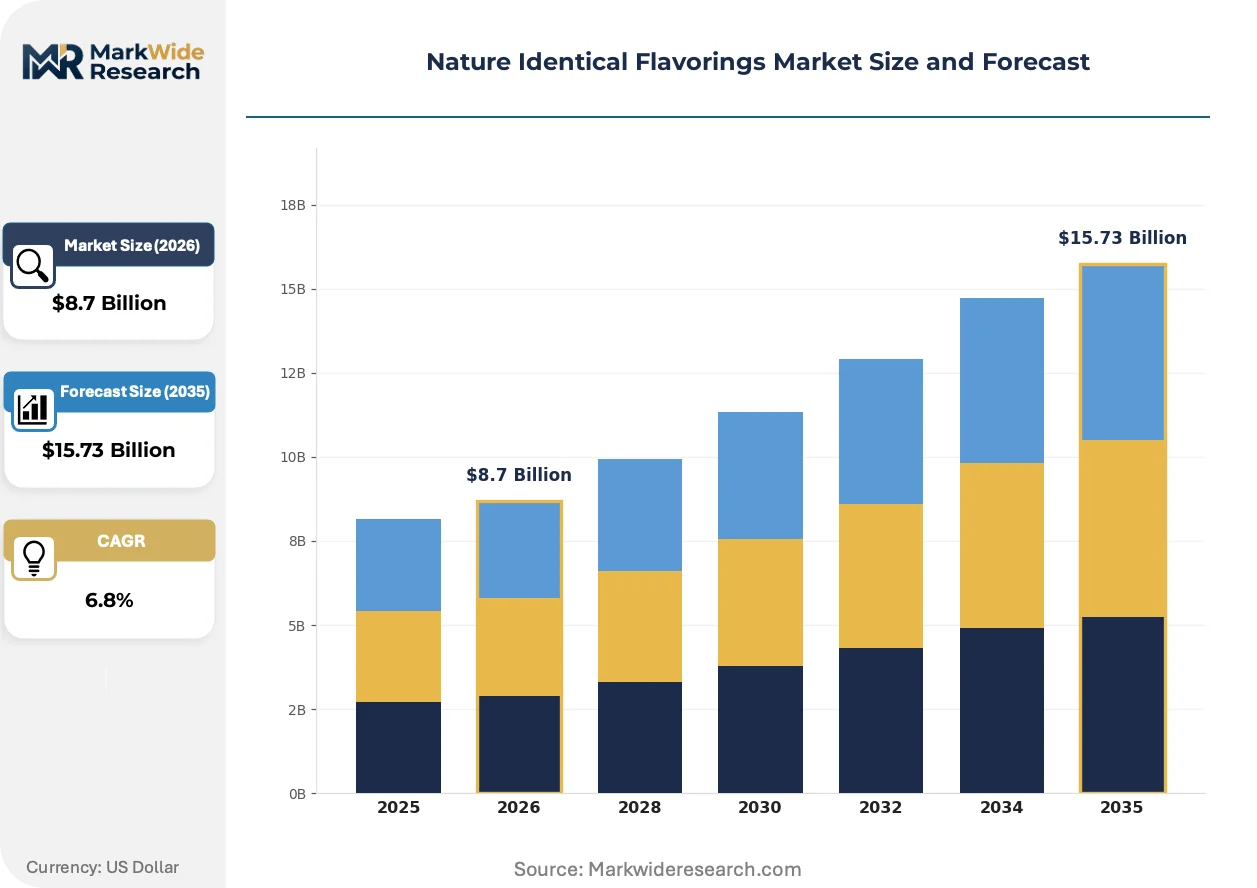
Market Dynamics
Clean-label beverage reformulation is compressing demand cycles for synthetic aroma suppliers as European manufacturers accelerate procurement of fermentation-derived vanillin and citrus esters ahead of EU Green Deal bio-based thresholds.
Growth Catalysts
- REACH purity mandates:ECHA's tightening toxicological dossier requirements for synthetic precursors are forcing manufacturers to upgrade purification infrastructure, creating captive demand for certified aroma compound suppliers in Germany and France.
- Encapsulated delivery systems:Thermal-stabilized powder formulations are penetrating bakery and confectionery segments where shelf-life extension determines supplier selection.
- Microbial fermentation platforms:Biotech-derived synthesis methods are achieving cost parity with petrochemical routes for high-volume vanillin production.
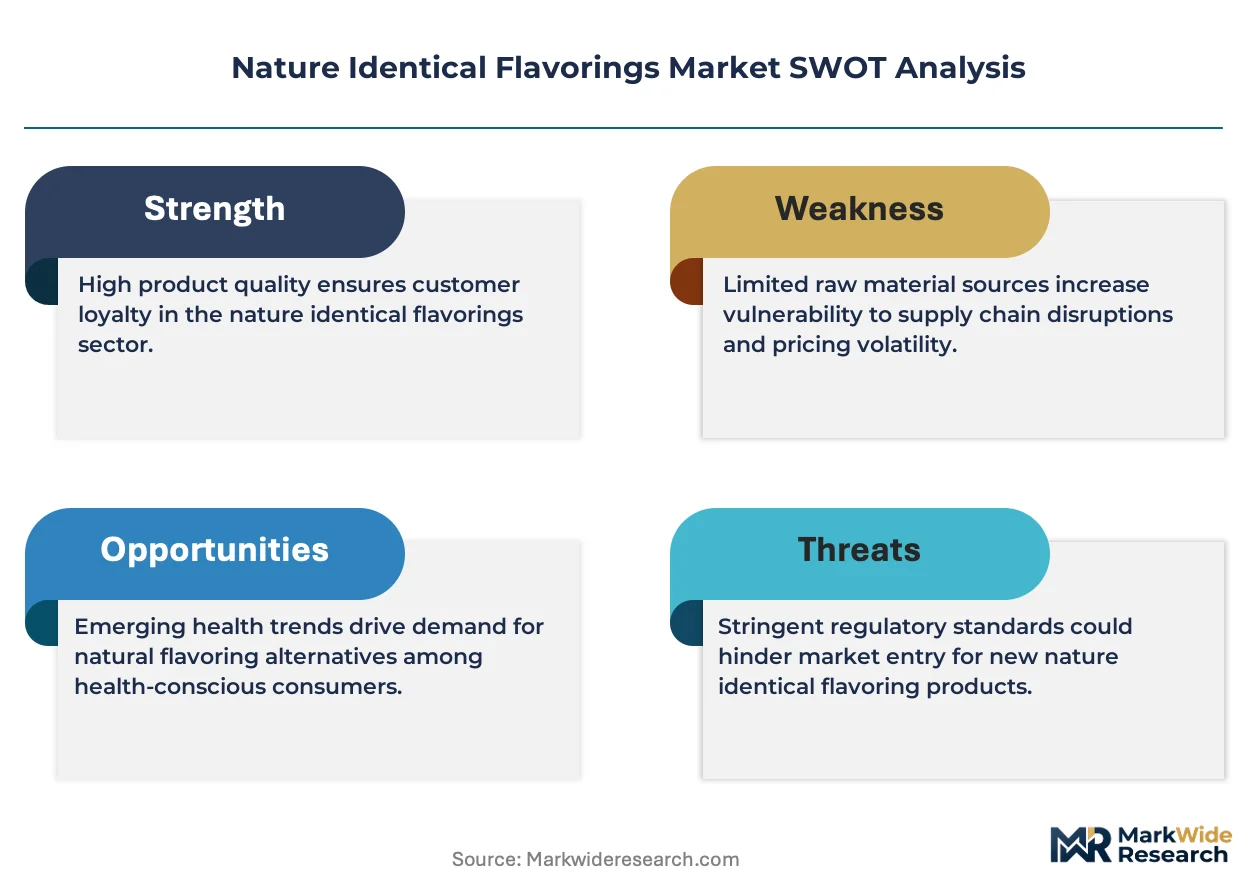
Market Restraints
- Agricultural feedstock volatility:Sugar and molasses price swings directly compress margins for fermentation-based aroma manufacturers dependent on Brazilian and Indian cane supply.
- Flavor chemist scarcity:Talent pools across European production hubs are rotating toward biotech synthesis, tightening supply of traditional organic chemists skilled in precision catalysis.
- Natural extract substitution:Premium-positioned brands in organic confectionery are rejecting nature identical compounds entirely, capping addressable market share in high-margin segments.
Strategic Opportunities
- South Asian snack manufacturing:Powder-form flavor capabilities are penetrating India's rapidly expanding processed food sector where thermal stability requirements favor synthetic over natural extracts.
- EU Green Deal bio-based thresholds:Anticipated mandates for renewable content in food contact materials will advantage fermentation-derived compounds over petrochemical equivalents.
- Inline dosing automation:Liquid formulation suppliers are integrating sensor-compatible delivery systems that reduce beverage line changeover times.
Industry Challenges
- GRAS self-determination fragmentation:FDA's enforcement discretion on fermentation-derived ingredients creates divergent qualification timelines that complicate multinational product launches.
- Cross-Atlantic regulatory misalignment:EFSA's precautionary maximum usage levels frequently conflict with FDA tolerance thresholds, forcing dual formulation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nature Identical Flavorings Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extracts, Synthetic Flavors, Aroma Compounds, Flavor Enhancers Application: Beverages, Confectionery, Dairy Products, Bakery End User: Food Manufacturers, Beverage Producers, Snack Industry, Personal Care Form: Liquid, Powder, Paste, Granule |
| Companies Covered | Kanegrade Ltd., Döhler GmbH, Keva Flavours Pvt. Ltd., DPO International, Parker Flavors, Inc., Sovereign Flavors, MANE, Flaverco Ltd., Carrubba Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nature Identical Flavorings Market Shifts & Advancements
Precision bioprocessing is actively compressing the cost-performance gap between synthetic and natural-extract flavoring systems, while regulatory pressure on petrochemical feedstocks accelerates capital redeployment toward fermentation infrastructure.
Continuous enzymatic catalysis is supplanting batch organic synthesis for high-purity ester production. Beverage manufacturers in Germany and the United Kingdom are adopting these platforms at pilot scale ahead of anticipated REACH bio-based thresholds. The technology is enabling 40% reduction in solvent waste while tightening molecular consistency beyond commercial natural extracts.
EU Green Deal bio-based content mandates are forcing reformulation roadmaps across European food contact applications. Manufacturers must now document renewable feedstock percentages in toxicological dossiers submitted to ECHA. Aroma compounds face the steepest compliance burden given their reliance on petrochemical benzene derivatives.
Direct-procurement contracts between flavor houses and end-use manufacturers are eliminating traditional distributor intermediaries. Large beverage conglomerates in France and the Netherlands are negotiating multi-year supply agreements with fermentation specialists. This pattern is most visible in vanillin procurement where volume concentration justifies captive quality assurance protocols.
Nature Identical Flavorings Market Segmentation
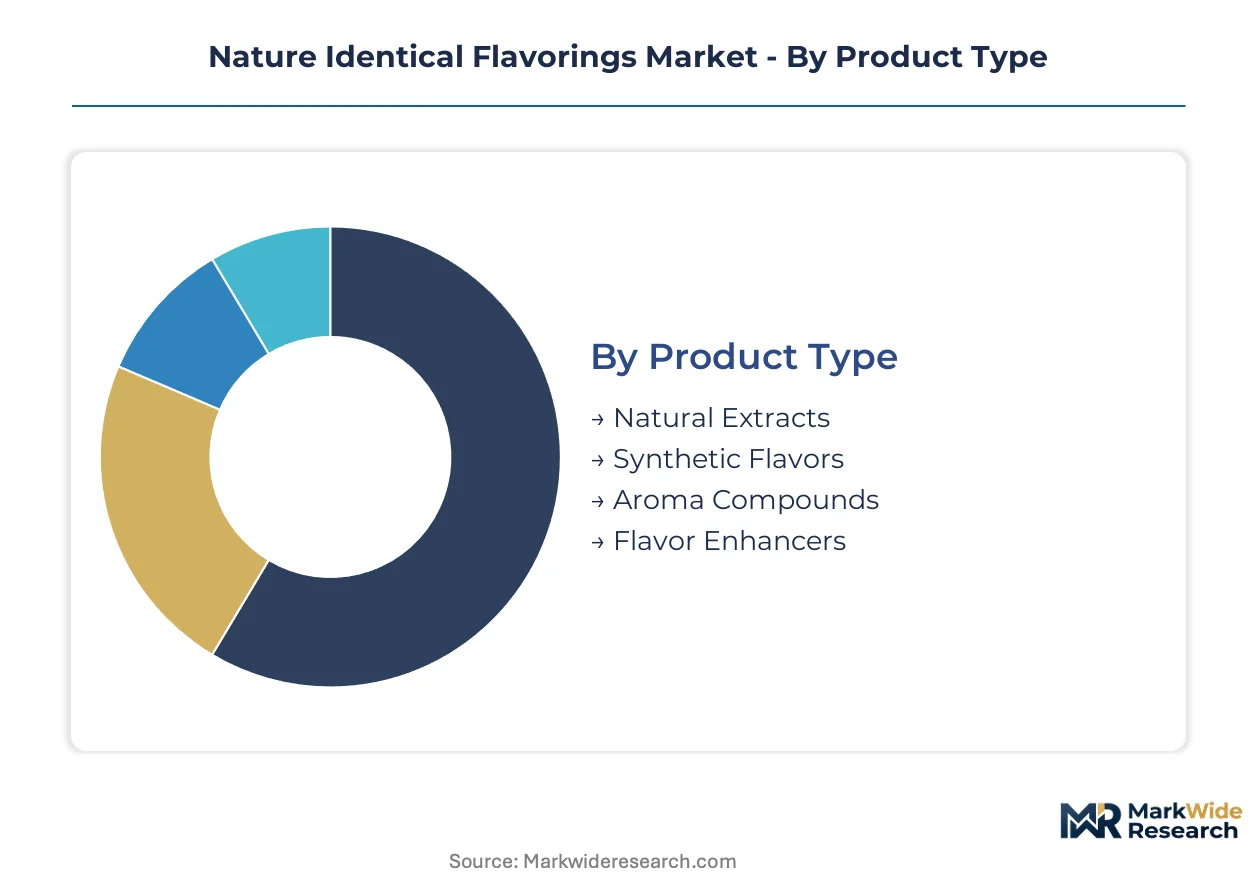
Segmentation in nature identical flavorings reveals divergent pressure points from natural extract substitution, biotech fermentation disruption, and regulatory purity mandates. Procurement patterns fragment sharply across liquid versus powder forms and beverage versus bakery applications.
Product Type:
Substitution pressure from fermentation-derived alternatives weighs most heavily on petrochemical-synthetic segments, while aroma compounds face accelerating displacement from microbial platforms.
- Aroma Compounds:High-purity esters, aldehydes, and ketones manufactured through precision organic synthesis or enzymatic catalysis. Beverage producers in Germany and France are replacing vanillin and citrus extracts with fermentation-derived equivalents ahead of REACH bio-based thresholds.
- Synthetic Flavors:Petrochemical-derived aromatic molecules including benzaldehyde and cinnamic aldehyde variants. ECHA's tightening toxicological dossier requirements are forcing manufacturers to upgrade purification infrastructure, compressing margins for uncertified suppliers.
- Natural Extracts:Botanical-derived concentrates standardized to match nature identical molecular profiles. Agricultural harvest variability constrains supply consistency for vanilla and citrus sources.
- Flavor Enhancers:Potentiators such as maltol and ethyl maltol that amplify perceived sweetness and aroma intensity. Snack manufacturers in South Asia leverage these for cost-optimized reformulations.
Aroma compounds anchor the volume base while synthetic flavors face the steepest substitution pressure from biotech alternatives.
Application:
Margin structures diverge sharply by thermal stability requirements and clean-label positioning intensity across end-use categories.
- Beverages:Liquid-dosed flavor systems for carbonated drinks, juices, and functional beverages. Inline dosing automation in German and UK production lines favors sensor-compatible liquid delivery systems that reduce changeover times.
- Bakery:Thermally stabilized formulations resisting degradation through oven temperatures. Powder forms command margin premiums where shelf-life extension determines procurement decisions in French and Dutch manufacturing.
- Confectionery:Encapsulated aroma systems for hard candies and chewing gum. Premium organic brands reject nature identical compounds entirely, capping addressable share in high-margin segments.
- Dairy Products:Fat-compatible flavor carriers for yogurts, ice creams, and flavored milks. Clean-label reformulation in UK retail channels is compressing demand cycles for synthetic aroma suppliers.
Beverages generate the highest absolute volume throughput while bakery applications expand most quickly through encapsulated delivery adoption.
End User:
Direct-procurement contracting patterns concentrate buying power differently across customer categories, fragmenting traditional distributor channels.
- Beverage Producers:Large-scale carbonated and functional drink manufacturers. French and Dutch conglomerates negotiate multi-year supply agreements with fermentation specialists, eliminating intermediary margins.
- Food Manufacturers:Diversified processed food operations spanning multiple categories. REACH compliance mandates drive captive demand for certified aroma compound suppliers in Germany.
- Snack Industry:Savory and sweet snack processors with thermal stability requirements. India's rapidly expanding processed food sector favors powder-form capabilities from Keva Flavours and regional suppliers.
- Personal Care:Cosmetic and oral care product formulators using flavor systems for sensory masking. EFSA maximum usage levels govern safety assessments differently than FDA GRAS thresholds, forcing dual qualification strategies.
Food manufacturers anchor procurement volume while beverage producers are consolidating supplier relationships fastest through direct contracting.
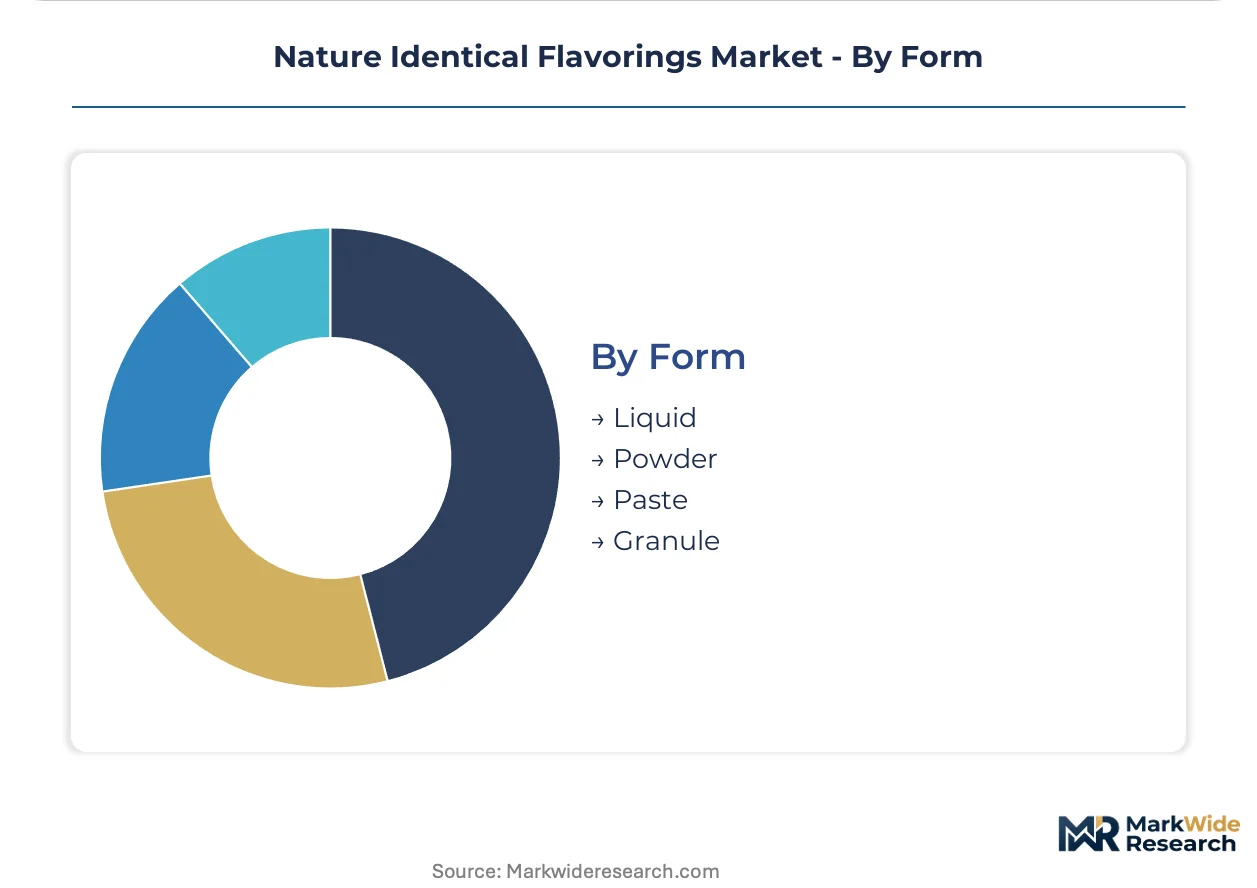
Form:
Physical state determines logistics infrastructure requirements, inline compatibility, and margin capture potential across production environments.
- Liquid:Solvent-dissolved or oil-based formulations for homogeneous mixing. Ease of inline dosing dominates volume throughput in beverage applications across German production sites.
- Powder:Spray-dried or plated carriers with extended shelf stability. Thermal stability requirements in bakery and confectionery segments command margin premiums over liquid equivalents.
- Paste:High-viscosity concentrates for specific confectionery and savory applications. Limited scalability constrains adoption outside niche manufacturing.
- Granule:Agglomerated particles for controlled release in chewing gum and compressed tablets. Specialized equipment requirements limit addressable customer base.
Liquid formulations dominate current volume while powder forms capture expanding share through bakery segment growth and shelf-life extension demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys nature identical flavorings primarily for beverage reformulation, whereas India concentrates procurement on powder-form bakery applications. This consumption-mix differential reflects divergent industrial structures and regulatory timelines across major demand centers.
Germany
REACH bio-based thresholds are accelerating fermentation-derived vanillin procurement by beverage conglomerates. ECHA's tightening toxicological dossier requirements force purification infrastructure upgrades across flavor houses. The Rhine-Main industrial corridor hosts concentrated compounding facilities serving carbonated drink manufacturers.
France
Direct-procurement contracting between flavor houses and food manufacturers is eliminating distributor intermediaries. EU Green Deal renewable content mandates reshape toxicological documentation requirements for aroma compounds. The Paris basin anchors encapsulated delivery system adoption for bakery and confectionery segments.
United Kingdom
Clean-label retail channel pressure compresses demand cycles for synthetic aroma suppliers in dairy applications. EFSA maximum usage levels govern safety assessments differently than FDA thresholds, complicating multinational launches. Greater Manchester production lines favor sensor-compatible liquid dosing systems for functional beverages.
India
Powder-form flavor capabilities penetrate the rapidly expanding processed snack sector where thermal stability requirements favor synthetic extracts. FSSAI labeling frameworks create compliance complexity for fermentation-derived ingredients. Maharashtra's food manufacturing belt concentrates procurement from regional suppliers serving savory and sweet snack processors.
United States
FDA GRAS self-determination creates divergent market access pathways that fragment regulatory strategy for multinational suppliers. Beverage producers negotiate multi-year supply agreements with fermentation specialists to secure volume concentration benefits. California's natural and organic product clusters reject nature identical compounds entirely, capping addressable share in premium segments.
Nature Identical Flavorings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with mid-scale fermentation houses occupying the middle ground. The upper tier controls captive extraction and compounding infrastructure across multiple production sites. Specialist archetypes include encapsulated delivery innovators, powder-form capability builders, and regional fermentation platforms. Competitive moves concentrate on strategic partnerships for bio-based feedstock security and capacity expansion for REACH-compliant purification systems.
Among European integrated houses, Döhler GmbH exemplifies the infrastructure-heavy archetype with German production site networks. MANE occupies a position within the encapsulated delivery specialist tier, while Keva Flavours Pvt. Ltd. anchors the South Asian powder-form capability builders serving thermal-stability-dependent applications.
| Leading Market Players |
|---|
| Kanegrade Ltd. |
| Döhler GmbH |
| Keva Flavours Pvt. Ltd. |
| DPO International |
| Parker Flavors, Inc. |
| Sovereign Flavors |
| MANE |
| Flaverco Ltd. |
| Carrubba Inc. |
| Others |
Supply & Pricing Matrix
Fermentation-derived vanillin displacing petrochemical-synthetic equivalents is redrawing supply geography toward Brazilian and Indian cane zones while compressing price premiums for traditional aroma compound suppliers. This substitution dynamic simultaneously concentrates feedstock procurement power and erodes legacy margin structures across European flavor houses.
Pricing Analysis
Long-term offtake contracts dominate vanillin procurement between French beverage conglomerates and fermentation specialists, locking volume commitments ahead of EU Green Deal bio-based thresholds. Three-tier pricing structure across premium, standard, and economy levels differentiates REACH-certified aroma compounds from uncertified alternatives. Price differentiation centers on toxicological dossier completeness and renewable feedstock documentation. Cost compression in synthetic flavor tiers is intensifying because ECHA's tightening purity mandates force purification infrastructure upgrades. Snack manufacturers in South Asia exhibit highest price sensitivity, while German beverage producers prioritize supply security over unit economics.
Supply Chain Analysis
Brazilian cane belt harvest volatility constitutes the primary feedstock chokepoint for fermentation-derived aroma manufacturers dependent on sugar and molasses supply. Production concentrates in Germany, France, and India, with German sites anchoring REACH-compliant compounding and Indian facilities serving powder-form thermal stability applications. Raw material flows draw from Brazilian cane derivatives, Indian molasses streams, and petrochemical benzene precursors. Single-source vulnerability in agricultural feedstocks exposes margin stability to climate-induced harvest variability. Distribution runs through direct-procurement channels between flavor houses and end-use manufacturers, eliminating traditional distributor intermediaries in French and Dutch markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nature identical flavorings market sits at an early-cycle expansion phase driven by EU Green Deal bio-based adoption mandates that are accelerating fermentation infrastructure deployment ahead of regulatory deadlines.
For Market Incumbents: Secure captive feedstock arrangements with Brazilian and Indian cane suppliers to defend against agricultural price volatility threatening fermentation-based margin structures. Prioritize REACH certification investments for aroma compound portfolios before ECHA's dossier requirements tighten further. Backward integration into microbial fermentation platforms offers defensive positioning against biotech-specialist entrants achieving cost parity in vanillin production. For New Entrants and Emerging Players: Lead with powder-form thermal stability capabilities targeting India's rapidly expanding processed snack sector where FSSAI labeling complexity disadvantages multinational incumbents. Encapsulated delivery systems for bakery applications represent the most penetrable white-space segment given French and Dutch manufacturers' shelf-life extension priorities. A go-to-market angle anchored on direct technical service partnerships with regional snack processors bypasses established distributor channels. For Investors and Strategic Acquirers: The market sits at a capacity-buildout phase that favors fermentation infrastructure specialists with demonstrated ECHA compliance pathways. Long-term viability over the next decade hinges on bio-based feedstock security and purification technology ownership rather than brand equity. Acquisition targets should display integrated extraction-compounding capabilities across multiple production sites. The signal to watch is EU Green Deal threshold announcements that would trigger accelerated reformulation procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Builds bio-based vanillin supply security ahead of REACH renewable content mandates. |
| Backward Integration into Feedstock | Captive cane and molasses sourcing insulates margins from Brazilian harvest volatility. |
| Purification Infrastructure Upgrade | ECHA-compliant toxicological dossiers unlock premium pricing in German and French markets. |
| Encapsulated Delivery System Development | Thermal stability patents capture bakery segment margin premiums in the Netherlands. |
| Direct Procurement Channel Establishment | Eliminates distributor margins in multi-year supply agreements with beverage conglomerates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA regulatory filings, FSSAI labeling frameworks, EU Green Deal documentation, and trade flow databases covering aroma compound imports. Primary interviews engaged flavor chemists at German production sites, procurement directors at French beverage conglomerates, technical sales leads at Indian snack manufacturers, and regulatory affairs specialists navigating REACH compliance. Secondary validation drew from customs data tracking fermentation-derived ingredient shipments, SEC filings of publicly traded flavor houses, and industry association reports from European flavor and fragrance federations. Bottom-up volume estimates triangulate against top-down market sizing from end-use consumption patterns.
Segmentation dimensions modeled span product type, application category, end-user industry, physical form, and geographic production hub across the analysis window. The analytical framework projects value expansion through volume growth assumptions and price trajectory modeling for liquid versus powder formulations. CAGRs derive from regression analysis against historical procurement patterns and regulatory adoption curves. Industry-specific forecast inputs include EU Green Deal implementation timelines and FSSAI enforcement discretion on fermentation-derived ingredient labeling.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory momentum or stable Brazilian cane harvest conditions would require recalibration. Forecasts reflect documented assumptions regarding bio-based threshold adoption rates and REACH dossier approval timelines. Practitioners should keep alternative scenarios live as ECHA enforcement patterns and agricultural commodity volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Pumpkin Spice Products Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
Poria Cocos Extract Market
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Asia-Pacific Food Colorants Market
Flavorings and Food Additives
Clean Label Flavors Market
Flavorings and Food Additives
Food Colorants Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Vanilla Bean Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market
Flavorings and Food Additives
Soy Sauce Powder Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Flavor Ingredients Market
Flavorings and Food Additives
Tangerine Extract Market