
 Oral & Topical Anaesthetics Market | 2026-2036
Oral & Topical Anaesthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Oral & Topical Anaesthetics Market Analytics
Subscription-based replenishment programs for dental practices is consolidating procurement patterns across the Oral & Topical Anaesthetics landscape. Johnson & Johnson leverages its hospital-grade manufacturing infrastructure to anchor supply contracts with major dental service organizations. Dentsply Sirona specializes in procedure-specific anaesthetic kits that integrate with its broader dental equipment ecosystem. Septodont dominates European dental anaesthetic ampoule production through captive polymer suppliers.
Oral and topical anaesthetics comprise pharmacological agents that reversibly block sodium ion channels in neuronal membranes, typically formulated at concentrations between 2% and 20% depending on tissue penetration requirements and procedural duration. These compounds serve primarily to eliminate sensation during minor surgical, dental, and dermatological interventions without inducing general unconsciousness. Lidocaine formulations command the largest revenue share due to established safety profiles across cream, gel, and injectable delivery modes, while benzocaine-free alternatives gain structural momentum as FDA warnings on methemoglobinemia risk reshape paediatric and oral care segments. Transmucosal delivery systems represent the fastest-growing form factor, absorbing margin pools from conventional injectable protocols in dental settings.
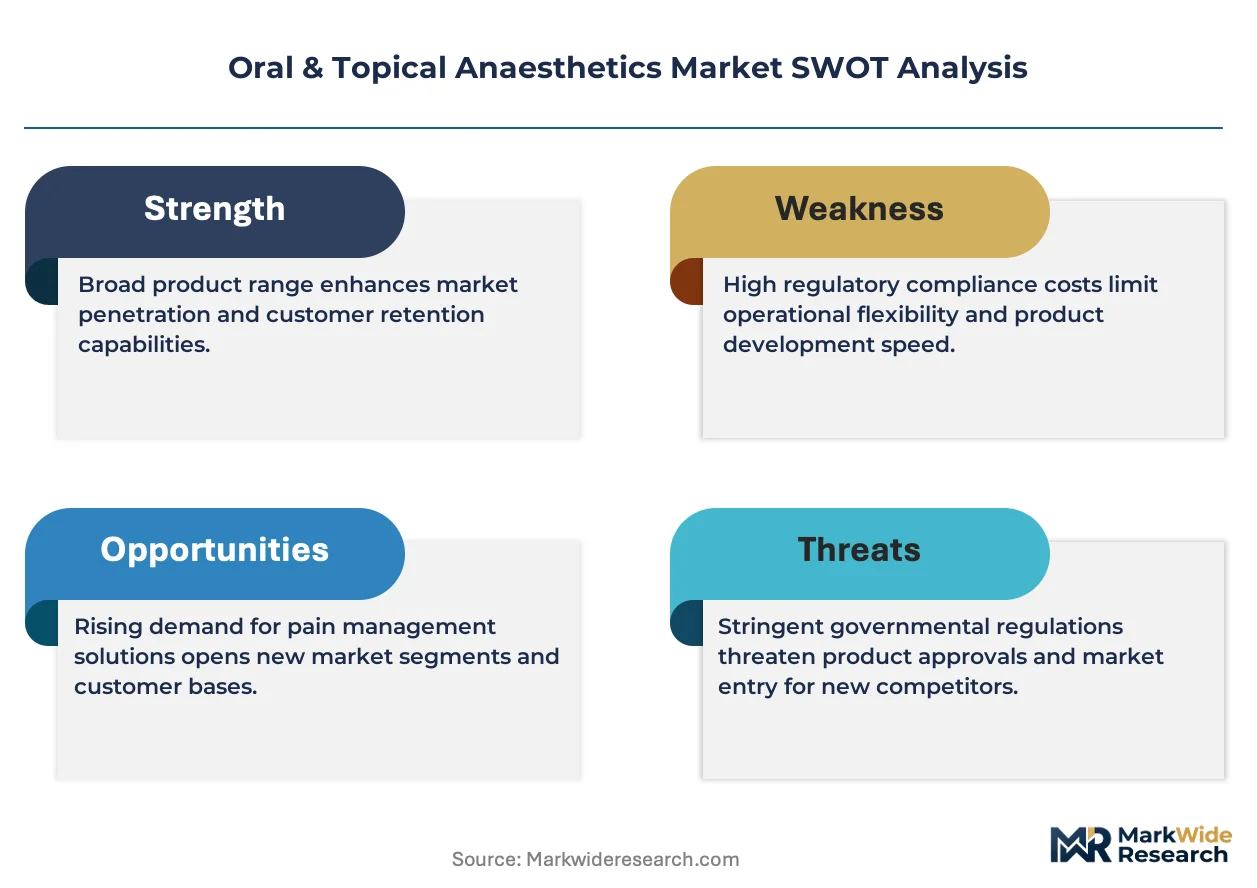
The FDA oversees New Drug Application and Abbreviated New Drug Application pathways for topical anaesthetic approvals, while the EMA's Committee for Medicinal Products for Human Use harmonizes concentration limits and paediatric contraindications across European markets. ISO 10993 biocompatibility standards govern material safety for patch and film-based delivery systems, creating compliance thresholds that filter smaller manufacturers from premium contract opportunities. Stakeholders must monitor evolving paediatric labelling requirements and generic substitution policies as these regulatory vectors determine which formulation portfolios retain pricing power.
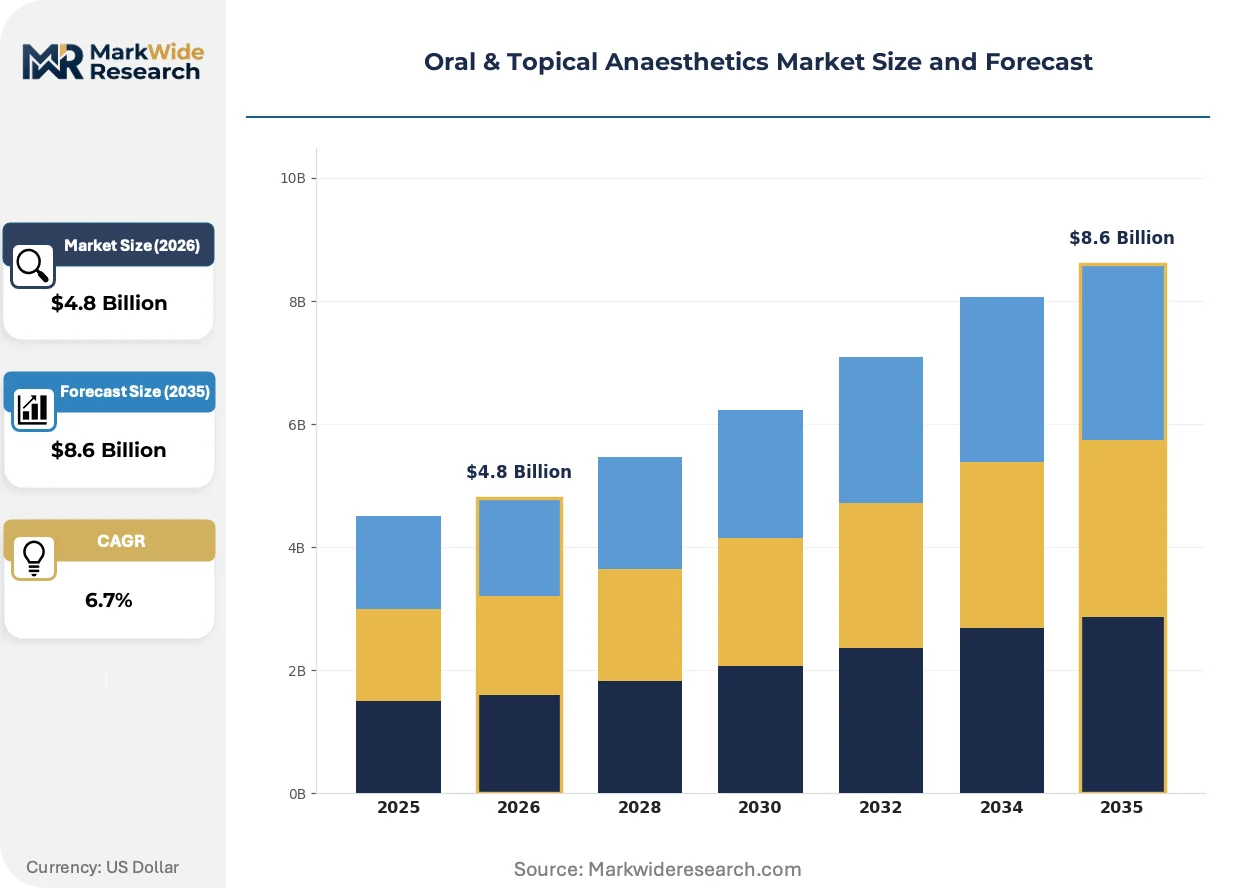
Market Dynamics
Transmucosal delivery systems are compressing demand for injectable protocols across dental practices, restructuring procurement toward procedure-specific kits and subscription-based replenishment models that consolidate vendor relationships.
Growth Catalysts
- Ambulatory surgical centre expansion:United States outpatient facilities drive volume concentration for topical anaesthetic applications. These centres prioritise rapid-turnover formulations that minimise recovery observation periods.
- FDA ANDA pathway acceleration:Streamlined generic approval timelines for topical anaesthetics intensify competitive entry. Generic substitution policies expand addressable patient populations across dermatology and dental segments.
- Benzocaine-free formulation migration:Methemoglobinemia warnings reshape paediatric and oral care product portfolios. Reformulation investments redirect R&D resources toward lidocaine and tetracaine alternatives.
Market Restraints
- Active pharmaceutical ingredient concentration:Lidocaine and prilocaine precursor supply concentrates among European and Asian chemical manufacturers. Single-source dependencies create formulation bottlenecks during regulatory inspections.
- ISO 10993 biocompatibility compliance:Material safety testing thresholds for patch and film-based delivery systems filter smaller manufacturers from premium contract opportunities. Certification costs disproportionately burden mid-scale producers.
- Paediatric labelling restrictions:EMA Committee for Medicinal Products for Human Use harmonisation efforts impose concentration limits that constrain product line extensions. Age-specific contraindications fragment addressable markets.
Strategic Opportunities
- Subscription-based dental procurement:Dental service organisations consolidate purchasing through replenishment programs that lock in multi-year supply contracts. Vendor stickiness increases through integrated equipment-anaesthetic kit bundling.
- Transmucosal film convergence:Polymer science advances enable rapid-dissolving oral films that combine anaesthetic delivery with haemostatic agents. Dual-function formulations command premium positioning in periodontal applications.
- European polymer captive supply:Backward integration into ampoule and syringe component manufacturing insulates producers from medical-grade plastic shortages. Captive moulding capacity secures batch consistency for high-viscosity gel formulations.
Industry Challenges
- Formulation stability expertise:Shortage of pharmaceutical chemists specialising in topical anaesthetic shelf-life extension complicates product development timelines. Talent competition intensifies against broader dermatology and pain management sectors.
- Legacy equipment integration:Dental practices with installed injection systems resist protocol transitions to transmucosal alternatives. Staff retraining requirements and sunk equipment costs delay adoption curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral & Topical Anaesthetics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lidocaine, Benzocaine, Tetracaine, Pramoxine Application: Dental Procedures, Skin Surgery, Pain Management, Wound Care Form: Cream, Gel, Spray, Patch Delivery Mode: Topical, Oral, Injectable, Transmucosal |
| Companies Covered | Johnson & Johnson, Dentsply Sirona, Septodont, GlaxoSmithKline, AstraZeneca, Bayer AG, Sanofi, Hikma Pharmaceuticals, Henry Schein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral & Topical Anaesthetics Market Evolving Landscape
Delivery mechanism innovation and regulatory pressure on paediatric safety are restructuring competitive positioning across formulation types, with digital procurement platforms accelerating vendor consolidation among dental service organisations.
Iontophoresis-assisted transdermal delivery is electrifying anaesthetic penetration depth for dermatological procedures. Cosmetic dermatology clinics adopt these systems to reduce needle anxiety among aesthetic patients. The technology is electrifying margin pools from conventional injectable protocols by enabling nurse-administered treatments previously requiring physician injection.
EMA paediatric investigation plan requirements now mandate age-stratified safety data for new topical anaesthetic submissions. Formulation developers must conduct dedicated juvenile toxicology studies that extend development timelines. Dental applications face heightened scrutiny as regulators link benzocaine exposure to rare but serious blood oxygenation disorders.
Dental service organisations now mandate outcome-based vendor scorecards that tie contract renewal to supply reliability metrics. Traditional distributor relationships yield to direct manufacturer partnerships with guaranteed stockholding commitments. United States multi-location dental chains pilot this model most aggressively, using procurement scale to extract preferential allocation during supply constraints.
Oral & Topical Anaesthetics Market Segmentation
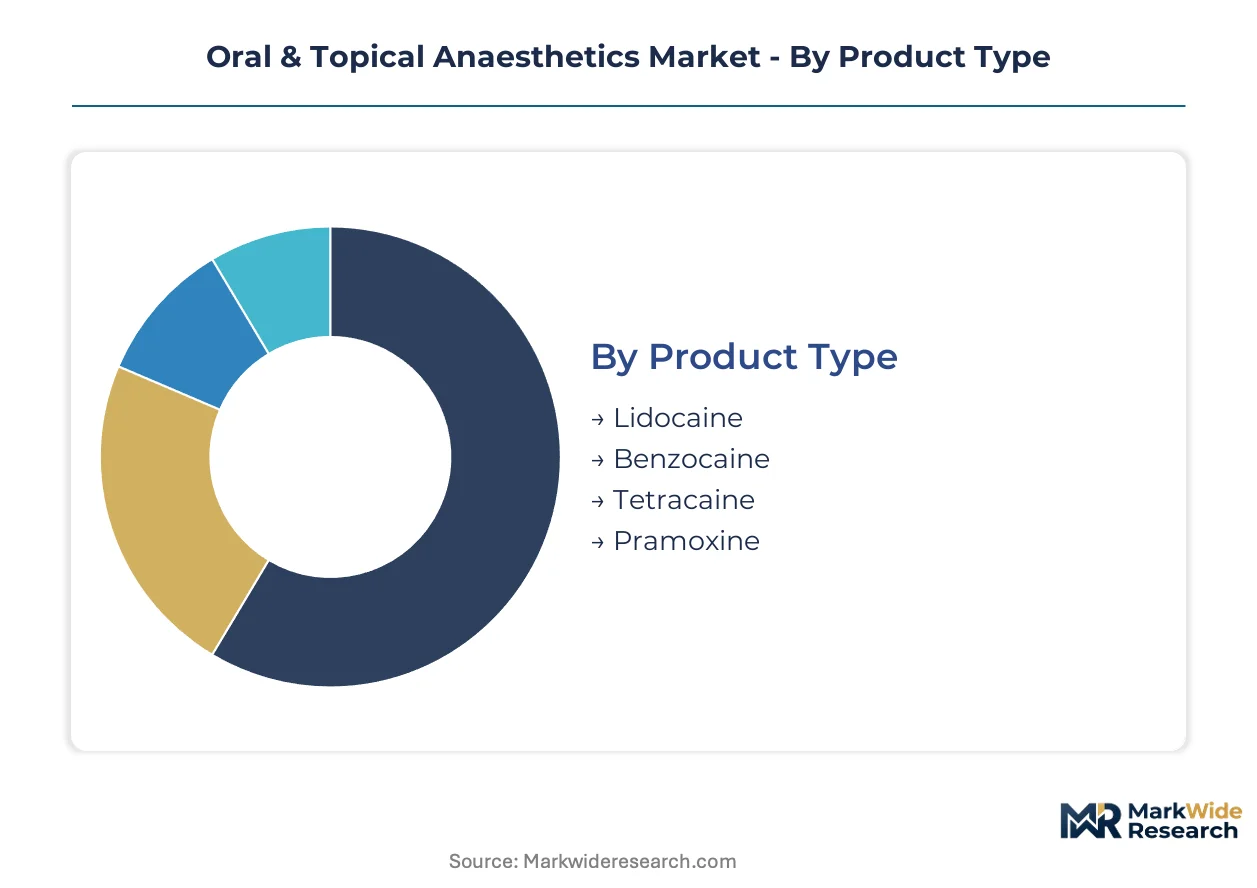
Segmentation in oral and topical anaesthetics reveals how formulation chemistry, procedural setting, and delivery technology intersect to determine procurement patterns. Understanding these divisions exposes where substitution pressures and premium positioning opportunities concentrate across dental, dermatological, and surgical applications.
Product Type:
Replacement cycles for anaesthetic agents accelerate as safety warnings and generic substitution policies reshape clinical preferences.
- Lidocaine:The amino amide structure provides rapid onset and intermediate duration across cream, gel, and injectable vehicles. Dental clinics in the United States favour lidocaine for high-throughput procedures where predictable metabolism minimises recovery observation. FDA ANDA pathway approvals for generic lidocaine formulations intensify price competition while expanding patient access.
- Benzocaine:The ester-based compound serves topical mucosal applications through spray and gel presentations. Methemoglobinemia warnings from the FDA and EMA Committee for Medicinal Products for Human Use have triggered reformulation away from benzocaine in paediatric oral care, compressing demand in favour of lidocaine alternatives.
- Tetracaine:Long-acting ester anaesthetic reserved for extended-duration ophthalmic and spinal applications requiring sustained blockade.
- Pramoxine:Low-sensitisation alternative for dermatological itch relief and minor skin procedures where allergic response to amides or esters must be minimised.
Volume placements concentrate in Lidocaine; the faster expansion belongs to Pramoxine as allergen-free positioning gains clinical traction.
Application:
Procedure economics and reimbursement structures determine which anaesthetic applications absorb premium pricing versus commodity procurement.
- Dental Procedures:Injectable lidocaine with epinephrine dominates crown preparations, extractions, and periodontal interventions. Ambulatory surgical centre expansion across the United States drives procedure volume concentration where rapid-turnover anaesthetic protocols maximise chair utilisation.
- Skin Surgery:Topical creams and patches precede dermatological excisions, biopsies, and cosmetic laser treatments. Iontophoresis-assisted delivery systems penetrate cosmetic dermatology clinics seeking needle-anxiety reduction for aesthetic patients.
- Pain Management:Transdermal patches and compounded gels address chronic neuropathic and post-surgical pain outside acute procedural settings.
- Wound Care:Spray formulations enable painless dressing changes in burn units and chronic ulcer management where mechanical stimulation triggers disproportionate discomfort.
Revenue gravity centres on Dental Procedures; Skin Surgery climbs the fastest as cosmetic procedure volume expands.
Form:
Manufacturing complexity and stability requirements separate premium-positioned formats from commodity alternatives.
- Cream:Oil-in-water emulsions suit large-surface dermatological applications where spreadability and occlusion control matter. Compounding pharmacies in the United States customise cream bases for off-label pain management protocols.
- Gel:Hydroalcoholic matrices provide rapid drying and tissue adhesion for oral mucosal and periodontal applications. Dental service organisations specify gel viscosity grades compatible with automated dispensing systems.
- Spray:Metered-dose aerosols deliver precise volume to inaccessible mucosal surfaces during endoscopy and wound debridement.
- Patch:Reservoir or matrix-type transdermal systems enable prolonged release for chronic pain without repeated application.
Procurement scale favours Gel; Patch formats gain share fastest as chronic pain applications expand.
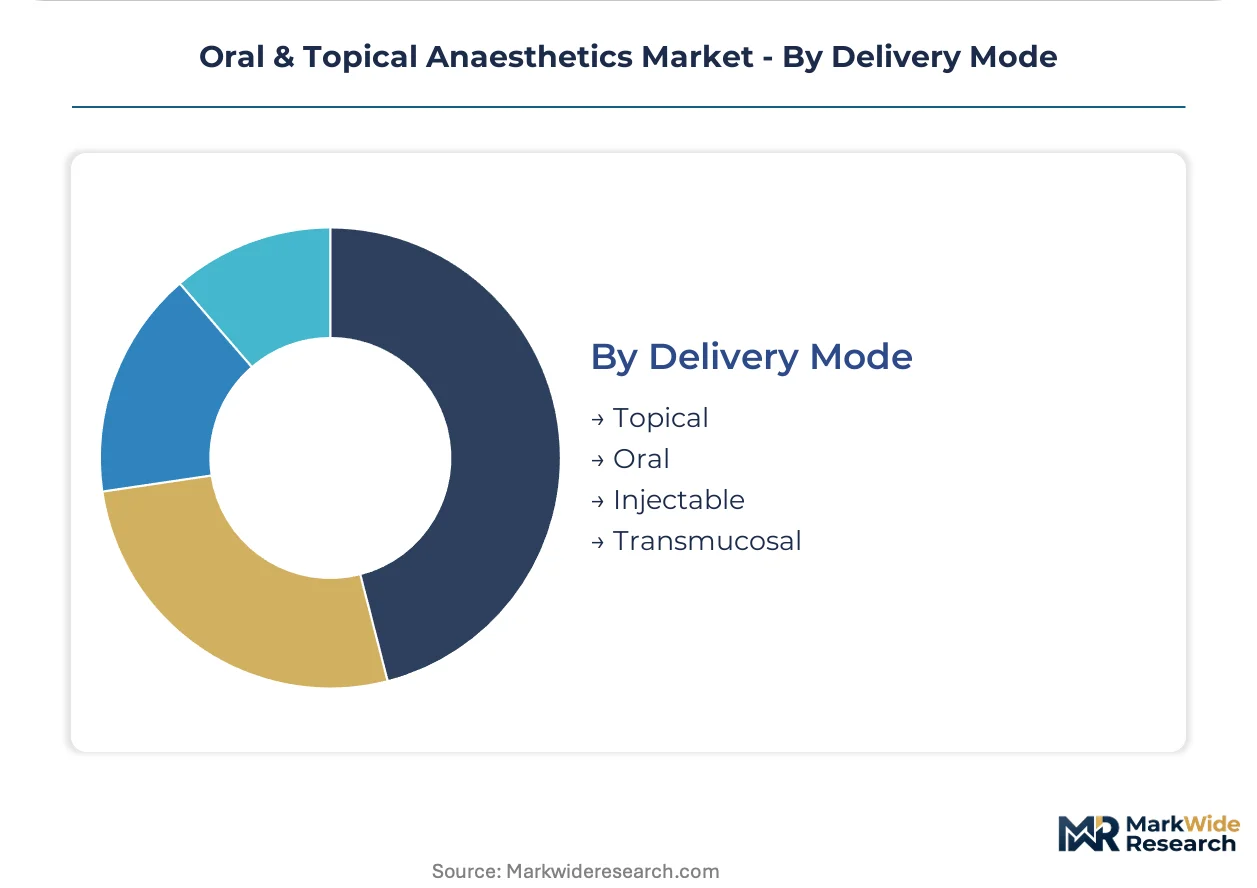
Delivery Mode:
Staff training requirements and capital equipment integration determine how quickly practices migrate between delivery paradigms.
- Topical:Passive diffusion across intact or compromised skin serves superficial dermatological procedures. ISO 10993 biocompatibility certification filters smaller manufacturers from premium patch and film contract opportunities.
- Oral:Transmucosal absorption through buccal, sublingual, or gingival surfaces enables needle-free dental anaesthesia. Polymer science advances produce rapid-dissolving oral films combining anaesthetic with haemostatic agents for periodontal applications.
- Injectable:Direct tissue infiltration and nerve blockade remain standard for deep dental and surgical interventions requiring profound anaesthesia.
- Transmucosal:Emerging film and tablet formats displace conventional injectable protocols in paediatric and anxiety-sensitive patient populations.
Injectable modes retain volume dominance; Transmucosal alternatives expand most quickly as dental practices adopt needle-sparing protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European API manufacturers supply precursor chemicals to formulation plants across multiple continents, while consumption concentrates in outpatient surgical networks and dental service organizations. The United States absorbs the largest absolute volume through ambulatory surgical centre expansion. Regulatory divergence between FDA and EMA paediatric labelling requirements creates formulation complexity for multinational portfolios.
United States
Ambulatory surgical centres in Texas, Florida, and Arizona drive lidocaine consumption through high-throughput dermatological and dental procedures. The FDA's streamlined ANDA pathway accelerates generic topical anaesthetic entry, intensifying price competition in cream and gel segments. Henry Schein distributes through Phoenix and Dallas distribution hubs to dental service organizations consolidating procurement.
Germany
Baden-Württemberg hosts precision polymer manufacturers supplying ampoule and syringe components to European dental anaesthetic producers. The EMA Committee for Medicinal Products for Human Use harmonizes paediatric concentration limits that constrain benzocaine formulation extensions. Stuttgart-area polymer science clusters advance rapid-dissolving transmucosal film technologies.
China
Zhejiang and Jiangsu provinces concentrate lidocaine and prilocaine precursor production for global formulation supply. NMPA biocompatibility certification requirements for patch-based delivery systems filter smaller manufacturers from premium export contracts. Shanghai medical device clusters integrate iontophoresis-assisted delivery systems for cosmetic dermatology applications.
India
Maharashtra and Gujarat host contract manufacturing organizations producing generic lidocaine formulations for export to African and Southeast Asian markets. CDSCO paediatric investigation plan requirements extend development timelines for transmucosal film submissions. Hyderabad pharmaceutical clusters specialize in high-viscosity gel formulations for periodontal applications.
Brazil
São Paulo dental chains expand transmucosal anaesthetic adoption to reduce needle anxiety in paediatric patient populations. ANVISA import substitution policies favour local formulation production over finished product imports. Rio de Janeiro cosmetic dermatology clinics pilot iontophoresis systems for nurse-administered aesthetic procedures.
Oral & Topical Anaesthetics Market Competitive Landscape
Capital-heavy pharmaceutical manufacturers compete with asset-light formulation specialists across the Oral & Topical Anaesthetics landscape. Three multinational conglomerates anchor hospital-grade supply contracts through integrated manufacturing infrastructure, while mid-scale dental specialists dominate procedure-specific kit bundling. Competitive dynamics centre on backward integration into polymer component supply and multi-year subscription procurement lock-ins with dental service organizations.
Within the conglomerate tier, Johnson & Johnson and GlaxoSmithKline occupy positions anchored by hospital-grade manufacturing infrastructure and broad therapeutic portfolios. Dentsply Sirona exemplifies the dental-specialist archetype through equipment-anaesthetic integration. Septodont represents European captive supply chain configuration through polymer manufacturing control. These three anchors illustrate how scale-driven supply reliability competes against procedure-specific bundling strategies.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Dentsply Sirona |
| Septodont |
| GlaxoSmithKline |
| AstraZeneca |
| Bayer AG |
| Sanofi |
| Hikma Pharmaceuticals |
| Henry Schein |
| Others |
Value Network & Pricing Analysis
Captive polymer manufacturing in Baden-Württemberg and Zhejiang anchors both supply security and premium pricing power for dental anaesthetic producers. Backward integration into ampoule and syringe components insulates European and Chinese manufacturers from medical-grade plastic shortages while enabling consistent batch quality that commands contract premiums from dental service organizations.
Pricing Analysis
Cost-down pressure on generic lidocaine formulations accelerates as FDA ANDA pathway approvals intensify manufacturer competition. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified patch producers from commodity gel suppliers. Dental service organizations extract volume discounts through multi-year subscription contracts, while ambulatory surgical centres prioritize rapid-turnover formulations over price minimization.
Supply Chain Analysis
Single-source vulnerability sits with European and Asian chemical manufacturers concentrating lidocaine and prilocaine precursor production. Formulation plants in India and Brazil draw from Zhejiang and Jiangsu API clusters, creating tariff exposure during trade policy shifts. Distribution runs through Henry Schein hub networks in Phoenix and Dallas, with dental service organizations mandating guaranteed stockholding commitments as allocation insurance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Oral & Topical Anaesthetics Market functions as a vertical-integration race where polymer science capabilities and captive component supply determine contract win rates. Players securing backward control over ampoule moulding and rapid-dissolving film substrates capture procurement consolidation momentum from dental service organizations.
For Market Incumbents: To counter generic substitution pressure from FDA ANDA pathway entrants, Johnson & Johnson and Dentsply Sirona should deepen captive polymer supply through European moulding capacity expansion and lock dental service organizations into equipment-anaesthetic kit bundling with guaranteed allocation terms. For New Entrants and Emerging Players: Paediatric anxiety-sensitive patient populations represent the most penetrable white-space target, as benzocaine reformulation creates demand for lidocaine-based transmucosal films. Iontophoresis-assisted delivery systems for cosmetic dermatology clinics offer a second entry vector with premium positioning potential. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale dental specialists with integrated equipment-anaesthetic portfolios and ISO 10993-certified patch manufacturing capabilities. Long-term viability hinges on polymer science talent retention and multi-year subscription contract coverage ratios. Watch FDA paediatric labelling rulemaking as an inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Polymer Manufacturing Expansion | Backward integration into ampoule production insulates Septodont from medical-grade plastic supply shocks. |
| Transmucosal Film R&D Investment | Dual-function anaesthetic-haemostatic formulations command premium positioning in periodontal applications. |
| Subscription Procurement Lock-In | Multi-year replenishment programs with dental service organizations reduce churn and stabilize revenue visibility. |
| ISO 10993 Certification Acceleration | Biocompatibility compliance filters smaller competitors from premium patch and film contract opportunities. |
| EMA Paediatric Investigation Plan Alignment | Age-stratified safety data investments preempt regulatory fragmentation across European markets. |
Research Methodology
FDA filings, EMA Committee for Medicinal Products for Human Use submissions, and ISO 10993 biocompatibility registries formed the secondary backbone, cross-referenced against customs data tracking lidocaine precursor trade flows. Primary interviews with dental service organization procurement directors, GPO contracts managers, and pharmaceutical regulatory affairs leads validated formulation portfolio strategies and contract structuring practices. Bottom-up manufacturer capacity assessments and top-down procedure volume estimates were triangulated against ambulatory surgical centre expansion data.
Historical trendline analysis of generic substitution rates and ANDA approval velocities informed projection modeling across the analysis window. Segmentation dimensions included product chemistry, delivery mode, procedural setting, and regional regulatory cluster. CAGR derivation incorporated dental clinic procedure throughput indices, polymer science patent filing velocities, and paediatric formulation safety warning trajectories as industry-specific inputs.
Revisions become necessary when EMA paediatric concentration limits tighten, FDA benzocaine restrictions expand, or medical-grade polymer supply disruptions materialize. Forecasts reflect documented assumptions about ambulatory surgical centre expansion cadence and generic entry timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
South Africa Diabetes Drugs Market
Pharmaceuticals
Global Chick Embryo Cell Rabies Vaccine Market
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Pharmacy Dark Store Market
Pharmaceuticals
Anticonvulsants Market