
 Anaesthesia Machines Market | 2026-2036
Anaesthesia Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Anaesthesia Machines Market Intelligence
The European Union's F-Gas Regulation, which restricts potent greenhouse gases like desflurane, is hardening requirements for low-flow anaesthesia delivery systems. Drägerwerk AG & Co. KGaA leverages its engineering expertise in gas management to meet these new standards. GE Healthcare differentiates through its integrated digital platforms that optimize gas consumption. Mindray Medical International Limited competes on providing advanced workstation features at accessible price points for emerging markets.
Anaesthesia machines are medical devices designed to create and mix a fresh gas flow of medical gases and inhalational anaesthetic agents. These systems precisely control the concentration of agents like sevoflurane and deliver them to a patient's breathing circuit. Advanced anaesthesia workstations dominate the hospital segment due to their integration with patient monitoring and electronic health records. Meanwhile, demand from ambulatory surgical centers is driving sales of more compact and portable anaesthesia units.
Market access hinges on compliance with stringent regulatory frameworks, including the US FDA's 510(k) clearance process and the EU's Medical Device Regulation (MDR). In China, the NMPA enforces specific GB standards for medical electrical equipment. Stakeholder decisions will center on balancing investment in software-driven features against the need for hardware reliability and cost containment in diverse clinical settings.
Market Dynamics
The convergence of environmental regulations and clinical efficiency goals represents the central force shaping the anaesthesia machines market. Mandates targeting greenhouse gas emissions from anaesthetic agents are compelling a hardware evolution towards low-flow systems, directly influencing product design and hospital procurement criteria.
Growth Catalysts
- Infrastructure Expansion in India:The build-out of new hospitals and surgical centers across India, supported by government healthcare initiatives, creates a sustained demand pipeline for new anaesthesia workstations and portable units.
- Ambulatory Surgical Center Growth:A procedural shift towards outpatient settings for minor surgeries is expanding the ambulatory surgical center segment, which requires compact, efficient, and cost-effective anaesthesia delivery systems.
- Low-Flow Anaesthesia Adoption:Environmental policies, such as the EU's F-Gas Regulation, combined with hospital cost-reduction efforts, accelerate the transition to low-flow and minimal-flow anaesthesia techniques, necessitating machines with advanced gas delivery and monitoring capabilities.
Market Restraints
- High Capital Investment:The significant upfront cost of advanced anaesthesia workstations with integrated monitoring and digital features acts as a major purchasing barrier for hospitals with constrained capital budgets, particularly in emerging economies.
- Stringent Regulatory Pathways:Navigating the complex and lengthy approval processes of multiple regulatory bodies, including the US FDA, the EU's MDR, and China's NMPA, increases development costs and time-to-market for new devices.
- Technician Skill Requirements:The increasing software complexity and network integration of modern anaesthesia workstations demand a higher level of technical expertise for maintenance and troubleshooting, which can be a limiting factor in regions with a shortage of trained biomedical engineers.
Strategic Opportunities
- AI-Powered Consumption Optimization:Integrating machine learning algorithms to analyze real-time patient data can enable predictive alerts and automated adjustments, minimizing anaesthetic agent consumption and improving patient safety outcomes.
- Portable Systems for Non-Traditional Settings:There is an unmet need for ruggedized, ultra-portable anaesthesia units for use in disaster response scenarios, military field medicine, and rural healthcare outreach programs.
- Software-as-a-Service (SaaS) Models:Offering advanced software features, such as data analytics or decision support modules, on a subscription basis can create new recurring revenue streams and lower the initial acquisition cost for customers.
Industry Challenges
- Interoperability with Legacy Systems:Ensuring seamless data communication between new anaesthesia workstations and a hospital's existing, often fragmented, ecosystem of patient monitors and electronic health record (EHR) platforms remains a significant technical hurdle.
- Cybersecurity Vulnerabilities:As anaesthesia machines become more connected, they are increasingly exposed to cybersecurity threats, requiring manufacturers to invest heavily in securing devices against potential breaches that could compromise patient safety.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anaesthesia Machines Market |
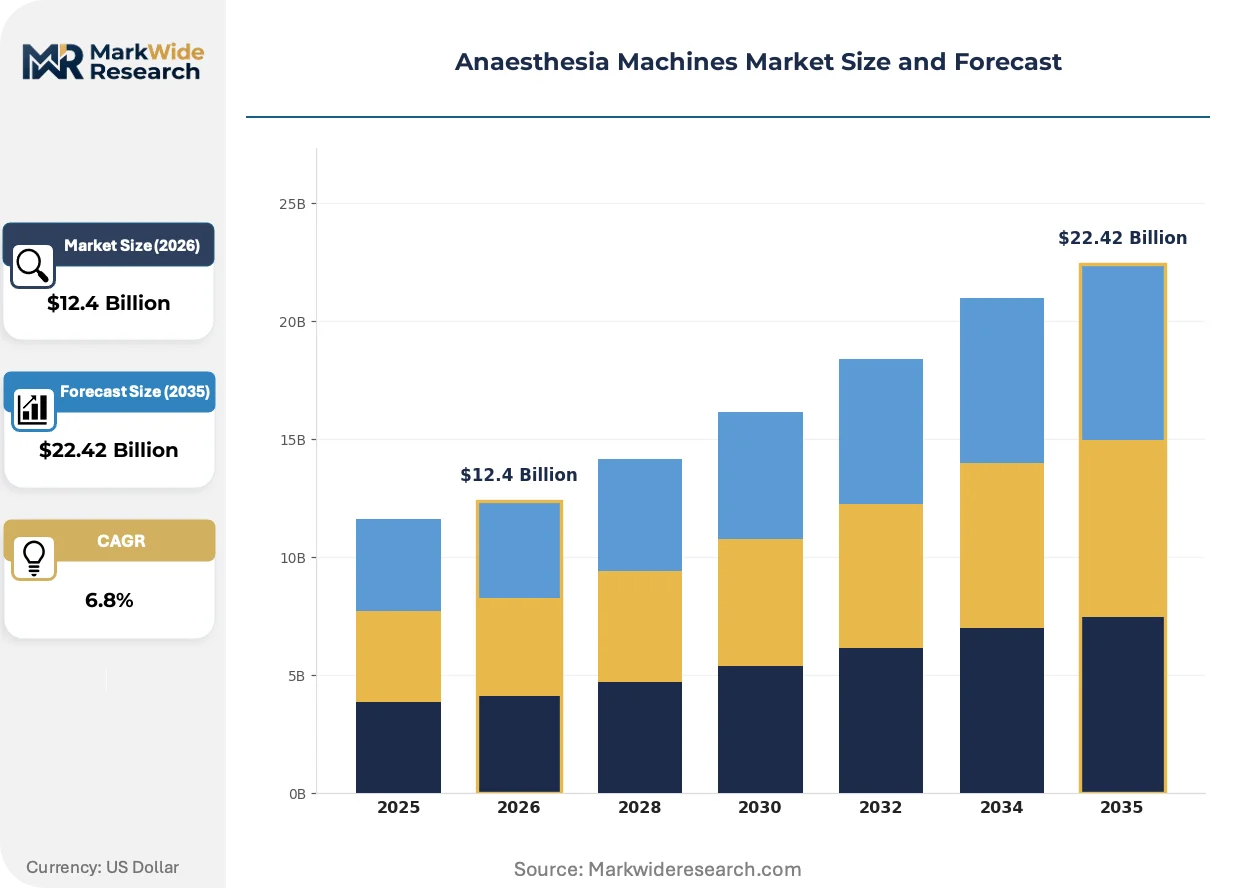
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Anaesthesia Machines, Advanced Anaesthesia Workstations, Portable Anaesthesia Units, Veterinary Anaesthesia Machines Technology: Mechanical Ventilation, Electronic Ventilation, Integrated Gas Monitoring, Digital Vaporizer Systems, Automatic Flow Control Application: Surgical Procedures, Dental Anaesthesia, Critical Care, Emergency Transport, Outpatient Surgeries End User: Hospitals, Ambulatory Surgical Centers, Dental Clinics, Mobile Medical Units, Veterinary Clinics |
| Companies Covered | GE Healthcare, Drägerwerk AG & Co. KGaA, Mindray Medical International Limited, Koninklijke Philips N.V., Maquet Getinge Group, Medtronic PLC, B. Braun SE, Fisher & Paykel Healthcare, Penlon Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anaesthesia Machines Market Strategic Shifts & Innovations
The market's evolution is defined by a technological pivot from standalone hardware to integrated, data-centric perioperative ecosystems. This transition is driven by the need to enhance patient safety, optimize resource utilization, and meet increasingly stringent regulatory and data security standards across clinical environments.
Closed-loop control systems represent a significant product evolution, using sensors to monitor patient physiological parameters like end-tidal gas concentration. Large academic medical centers and integrated delivery networks are the earliest adopters of this technology. This advancement is automating the precise titration of inhaled anaesthetics, freeing clinicians to focus on higher-level cognitive tasks and patient oversight during surgery.
Data privacy frameworks, including HIPAA in the United States and GDPR in Europe, are fundamentally altering device design. This regulatory pressure compels manufacturers to embed robust cybersecurity measures, such as data encryption and secure boot processes, into the core architecture of anaesthesia workstations. The hospital segment, with its deep integration of electronic health records, is most affected, prioritizing devices with verifiable security certifications.
A notable shift in purchasing behavior involves the move towards evaluations based on total cost of ownership rather than just initial capital outlay. This model considers long-term expenses related to consumables, service contracts, and anaesthetic gas consumption efficiency. Such a holistic assessment is most prevalent in the mature healthcare markets of North America and Western Europe, where budget optimization is a primary institutional goal.
Anaesthesia Machines Market Segmentation
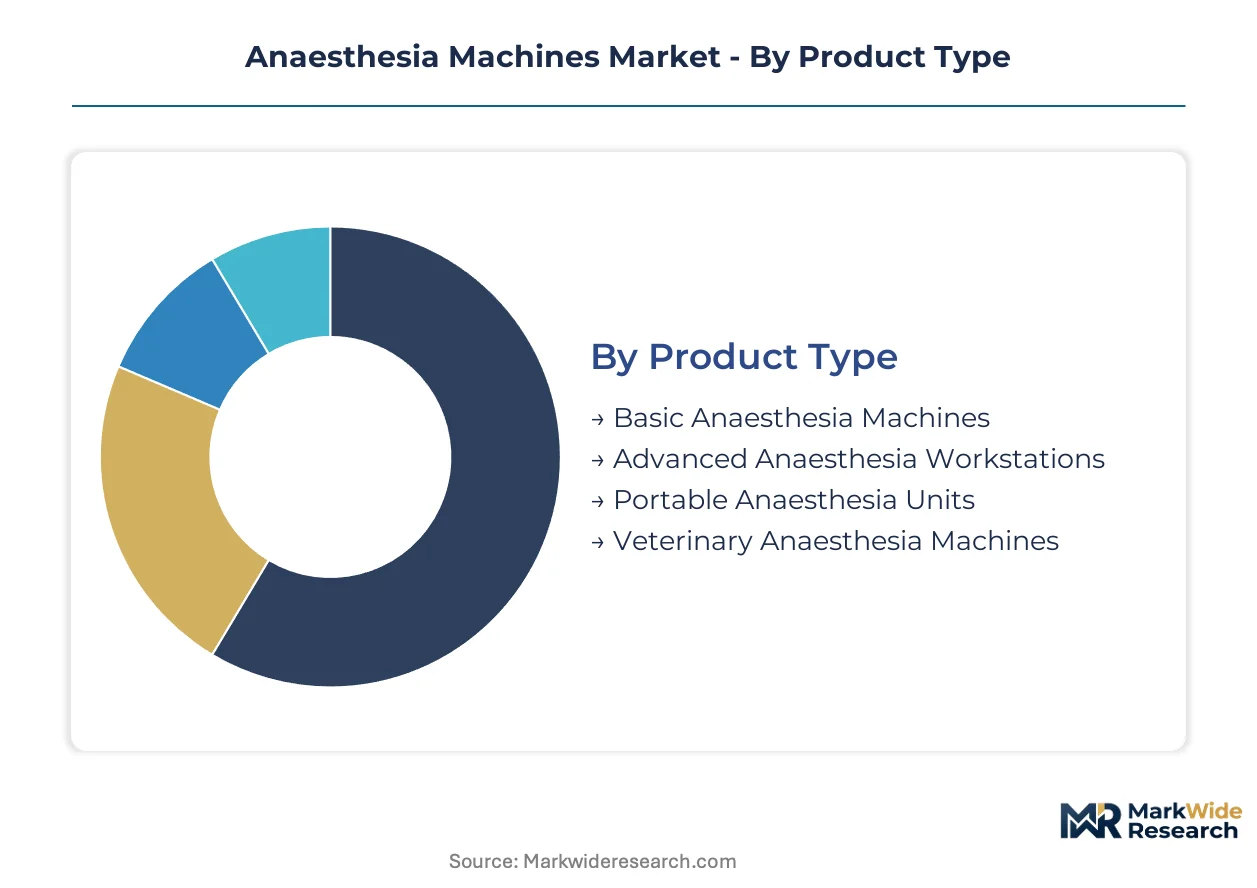
The anaesthesia machines market segmentation reflects diverse clinical requirements, technological advancements, and varying end-user needs across the healthcare landscape. Understanding these distinct segments is crucial for manufacturers to tailor product development and market access strategies effectively. Regulatory compliance and cost efficiencies also influence segment performance.
Product Type:
Supply concentration for anaesthesia machines often reflects the technical complexity and integration required by different product types.
- Advanced Anaesthesia Workstations:These systems integrate gas delivery, patient monitoring, and electronic health records for comprehensive perioperative management. Demand concentrates in large hospital networks due to their need for centralized data and advanced clinical features.
- Portable Anaesthesia Units:These compact devices offer mobility and efficiency for use in diverse clinical settings, often featuring simplified controls. Demand is expanding in ambulatory surgical centers, driven by the shift towards outpatient minor surgical procedures.
- Basic Anaesthesia Machines:These provide fundamental gas mixing and delivery capabilities for less complex procedures.
- Veterinary Anaesthesia Machines:These systems are specifically designed for animal patients, adapting to varying sizes and physiological needs.
Today's leader: Advanced Anaesthesia Workstations. Tomorrow's challenger: Portable Anaesthesia Units.
Technology:
The application spectrum of anaesthesia machines directly influences the technological features required for safe and efficient patient care.
- Integrated Gas Monitoring:These systems precisely measure and display concentrations of inhaled anaesthetics and respiratory gases within the patient breathing circuit. Demand concentrates in all advanced clinical settings, driven by the critical need for patient safety and low-flow anaesthesia optimization.
- Automatic Flow Control:This technology uses sensor feedback and algorithms to autonomously adjust anaesthetic gas delivery, optimizing consumption and patient stability. Demand is emerging in academic medical centers, propelled by the pursuit of AI-powered efficiency and reduced agent waste.
- Mechanical Ventilation:This technology relies on pressure-driven bellows or pistons to deliver breathing gases to the patient.
- Electronic Ventilation:These systems use electronically controlled valves and flow sensors for precise and adaptable respiratory support.
- Digital Vaporizer Systems:These components accurately convert liquid anaesthetic agents into vapor for delivery, often with electronic controls.
The segment expanding most quickly is Automatic Flow Control, driven by advancements in AI-powered optimization.
Application:
Customer type preferences and operational requirements significantly shape the demand for specific anaesthesia machine applications.
- Surgical Procedures:This foundational application covers the broad spectrum of operations requiring general anaesthesia in hospital operating rooms. Demand remains consistently high in all healthcare systems, underpinned by the essential role of surgery in modern medicine.
- Outpatient Surgeries:This application involves minor surgical interventions performed in ambulatory settings, emphasizing rapid patient recovery and efficient turnover. Demand is rapidly expanding due to the shift of procedures from inpatient to more cost-effective outpatient environments.
- Dental Anaesthesia:This application focuses on sedation and general anaesthesia for dental and oral surgery procedures.
- Critical Care:Anaesthesia machines are adapted for prolonged ventilation and sedation management in intensive care units.
- Emergency Transport:These portable units provide respiratory support and anaesthesia during patient transfers or in pre-hospital settings.
The shift towards value-based care and efficiency is redefining demand for Outpatient Surgeries within this category.
End User:
The volume of procedures performed by different end-user types directly dictates their anaesthesia machine procurement patterns.
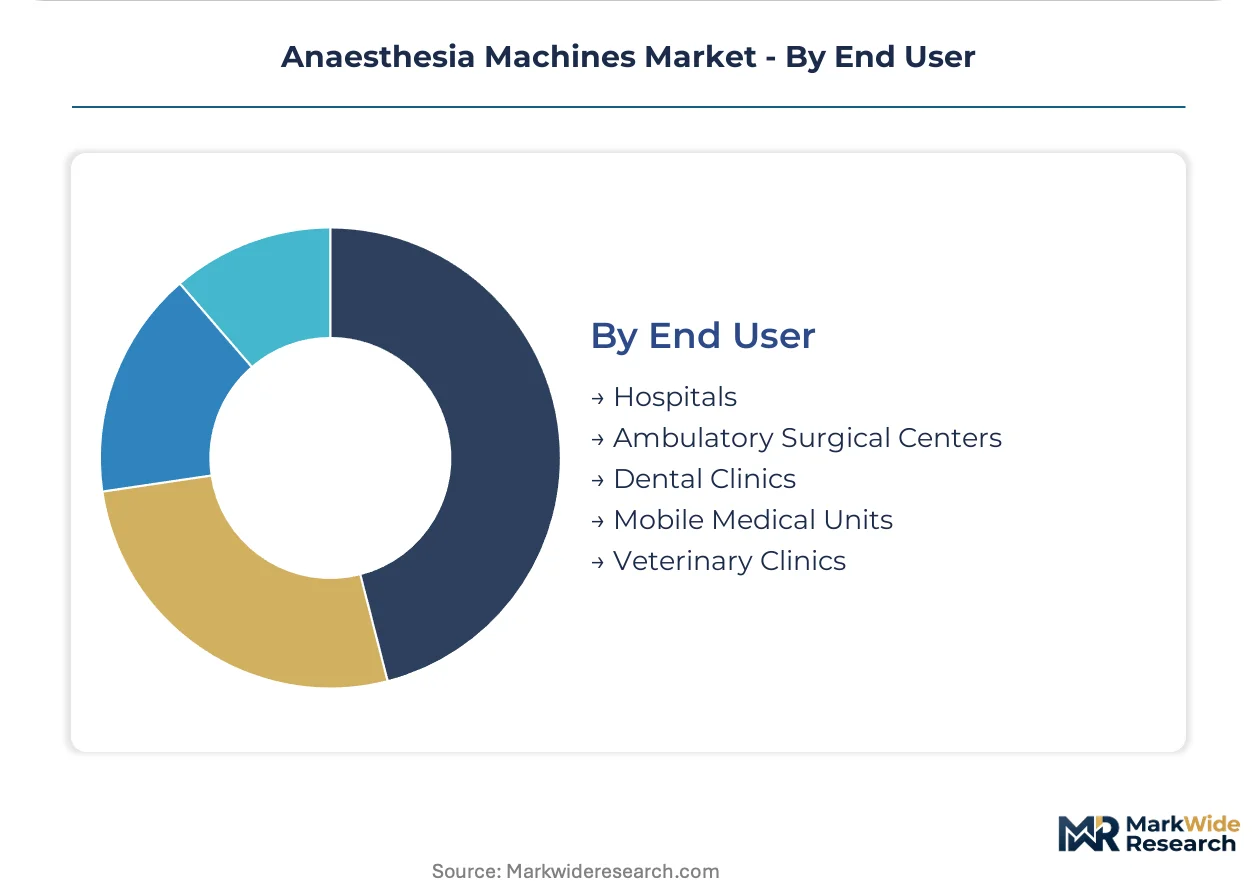
- Hospitals:These institutions represent the largest end-user segment, utilizing a wide array of advanced anaesthesia workstations for complex surgeries and critical care. Demand concentrates in established healthcare systems globally, driven by the comprehensive nature of inpatient medical services.
- Ambulatory Surgical Centers:These specialized facilities focus on outpatient procedures, requiring compact, efficient, and cost-effective anaesthesia units. Demand is expanding across North America and Europe, propelled by the economic advantages of shifting minor surgeries to outpatient settings.
- Dental Clinics:These facilities employ anaesthesia machines for sedation and general anaesthesia during various dental procedures.
- Mobile Medical Units:These units require ruggedized, portable anaesthesia systems for field operations and emergency response.
- Veterinary Clinics:These clinics use specialized anaesthesia equipment tailored for animal care and surgical interventions.
Growth in this category is increasingly concentrated in Ambulatory Surgical Centers, reflecting the procedural shift towards outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The anaesthesia machines market originated with early innovations in gas delivery and patient safety, primarily scaled in Western Europe and North America. These regions continue to drive technological advancements and regulatory compliance standards for medical devices. The industry's evolution reflects a continuous effort to enhance precision and integration in clinical settings.
United States
Demand for advanced anaesthesia workstations is driven by large hospital networks and ambulatory surgical centers. The US FDA's 510(k) clearance process dictates market access for new devices. Major medical device manufacturing clusters exist in California and Massachusetts, fostering innovation in integrated digital platforms.
Germany
Germany's market demand is shaped by a strong focus on engineering precision and low-flow anaesthesia techniques. The EU's F-Gas Regulation directly influences product design and procurement criteria for anaesthetic agents. The medical technology hub around Erlangen and Tuttlingen concentrates expertise in advanced gas management systems.
India
Infrastructure expansion in India, supported by government healthcare initiatives, creates substantial demand for new anaesthesia units. The country's Central Drugs Standard Control Organization (CDSCO) regulates medical device approvals and market entry. Major hospital build-outs in cities like Mumbai and Bengaluru are increasing procurement of both workstations and portable units.
China
China experiences significant demand for advanced workstation features at accessible price points, particularly in its expanding hospital sector. The NMPA enforces specific GB standards for medical electrical equipment, influencing local manufacturing and imports. Industrial clusters in the Yangtze River Delta and Pearl River Delta are centers for domestic anaesthesia machine production.
United Kingdom
The United Kingdom's market prioritizes cost-effective and efficient anaesthesia delivery systems for its National Health Service. Compliance with the EU's Medical Device Regulation (MDR) remains crucial for devices sold in the UK, even post-Brexit. London and the Southeast region host numerous medical technology companies and research institutions driving clinical adoption.
Anaesthesia Machines Market Key Industry Players
Capital-heavy producers compete with asset-light designers, creating a tiered market structure for anaesthesia machines. The market exhibits consolidation among established manufacturers offering comprehensive solutions. Strategic archetypes include integrated system providers, specialized component suppliers, and regional value-segment players. Dominant competitive moves involve portfolio diversification and strategic partnerships to navigate complex regulatory environments.
Among the integrated system providers, US-based GE Healthcare exemplifies a focus on digital platforms and advanced software features for optimizing gas consumption. German-based Drägerwerk AG & Co. KGaA, an AG & Co. KGaA structured entity, represents engineering expertise in gas management and compliance with stringent European regulations. Shenzhen-based Mindray Medical International Limited, a Limited company, anchors the value segment by providing advanced workstation features at accessible price points for emerging markets, expanding its global footprint. These companies collectively demonstrate the market's emphasis on technological leadership and regional market penetration strategies.
| Leading Market Players |
|---|
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Mindray Medical International Limited |
| Koninklijke Philips N.V. |
| Maquet Getinge Group |
| Medtronic PLC |
| B. Braun SE |
| Fisher & Paykel Healthcare |
| Penlon Limited |
| Others |
Cost & Logistics Intelligence
Advanced anaesthesia workstation complexity creates a distinct tier divergence, influencing both premium pricing and the intricate supply chains for integrated digital components. Conversely, portable units reflect value-based pricing and simpler component sourcing.
Pricing Analysis
Value-based pricing characterizes advanced anaesthesia workstations, reflecting their integrated digital platforms and stringent regulatory compliance. Price differentiation stems from specialized features and after-sales service contracts. Pricing pressure stems from increased competition in emerging markets and hospital cost containment initiatives. Ambulatory Surgical Centers exhibit the highest price sensitivity, while large hospital networks prioritize advanced functionality over initial cost.
Supply Chain Analysis
Direct-to-hospital channels often handle advanced anaesthesia workstation distribution, while regional distributors manage portable unit sales. Component supply concentrates in Germany for precision engineering and China for electronic manufacturing. Key dependencies include specialized sensors and microprocessors. A structural supply chain risk is the potential single-source vulnerability for certain advanced electronic components, impacting production stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anaesthesia machines market demonstrates stable compounding growth, driven by continuous infrastructure expansion in emerging economies. This sustained demand underpins long-term investment prospects across diverse clinical settings.
For Market Incumbents:
Cement market leadership by investing heavily in AI-powered consumption optimization and robust cybersecurity features. This counters the threat of stringent regulatory shifts like the F-Gas Regulation and value-segment new entrants. Prioritize R&D in closed-loop systems and secure necessary certifications to maintain competitive advantage. Deepening channel control in key growth regions like India also reinforces position.
For New Entrants and Emerging Players:
Local distributor networks offer the best entry point for new players targeting underpenetrated segments. Focus on developing ruggedized, ultra-portable anaesthesia units for disaster response and rural healthcare outreach programs. Ambulatory Surgical Centers represent a highly penetrable segment due to their demand for efficient, cost-effective solutions. A strong go-to-market angle involves offering advanced features through flexible Software-as-a-Service models.
For Investors and Strategic Acquirers:
Consolidation pressure builds where technological complexity meets regulatory compliance, favoring integrated system providers. The market offers strong long-term viability for the next decade, driven by essential medical demand and evolving clinical practices. Target mid-cap specialists with strong intellectual property in AI-driven gas optimization or robust portable systems for non-traditional settings. The signal to watch is the widespread adoption of closed-loop control systems in leading academic medical centers.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Consumption Optimization Launch | This enhances patient safety and reduces anaesthetic agent waste, aligning with environmental regulations. |
| EU MDR Compliance Investment | Securing certification ensures market access and competitive standing within the stringent European Union healthcare landscape. |
| Hospital System Integration Partnerships | Seamless data flow with electronic health records optimizes perioperative workflows for large institutions. |
| Emerging Market Geographic Expansion | Tapping into infrastructure build-outs in India and China drives significant volume growth. |
| Software-as-a-Service (SaaS) Modules | Subscription-based offerings create recurring revenue streams and lower initial acquisition costs for customers. |
Research Approach
Direct dialogue with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers provided primary insights. This was validated against secondary sources including US FDA filings, EU MDR guidance, and NMPA GB standards. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and comprehensive market understanding.
Volume and value forecasts were generated across the analysis window, utilizing a sophisticated analytical framework. Key segmentation dimensions modeled included product type, technology, application, end user, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends and projected market dynamics. Forecast inputs included surgical procedure volumes and hospital bed capacity expansion.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory shifts and rapid technological disruption. This analysis reflects assumptions regarding healthcare spending and adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Epinephrine Market
Anesthesiology
Endotracheal Tube Cuffs Market
Anesthesiology
Dental Anesthesia Market
Anesthesiology
Global Anesthesia Gases Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Airway Catheters Market
Anesthesiology
US Anesthesiology Service Market
Anesthesiology
Anesthetics Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Inhalation Anesthetics Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Delirium Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market