
 Peptide-Based Cancer Therapeutics Market | 2026-2036
Peptide-Based Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Peptide-Based Cancer Therapeutics Market Analytics
Consolidation among hospital systems and specialty oncology networks is recalibrating procurement leverage for peptide-based cancer therapeutics. Novartis AG anchors its position through deep manufacturing scale in peptide-drug conjugate production. Eli Lilly and Company differentiates via R&D intensity in targeted peptide platforms for solid tumors. Bristol Myers Squibb competes through geographic dominance in North American infusion center networks.
Peptide-based cancer therapeutics comprise synthetic or recombinant amino acid sequences engineered to bind tumor-associated antigens, trigger apoptosis, or deliver cytotoxic payloads with molecular weights typically below 10 kDa. These agents serve the primary commercial purpose of achieving tumor specificity while minimizing off-target toxicity compared to conventional chemotherapy. Monoclonal antibodies occupy the largest revenue pool due to established reimbursement and manufacturing infrastructure, though immune checkpoint inhibitors represent the fastest-expanding segment as combination protocols gain traction in melanoma and lung cancer. Intravenous delivery dominates current volume, yet subcutaneous formulations are capturing margin expansion through reduced administration costs and outpatient shift incentives.
FDA's accelerated approval framework and EMA's PRIME designation scheme shape development priorities by compressing timelines for peptide-based oncology agents with breakthrough potential. The EU AI Act and FDA's evolving guidance on computational drug design are reshaping preclinical validation requirements for AI-discovered peptide sequences. Stakeholders must monitor how payer consolidation and outcomes-based contracting reshape commercial access for novel peptide therapeutics across integrated delivery networks.
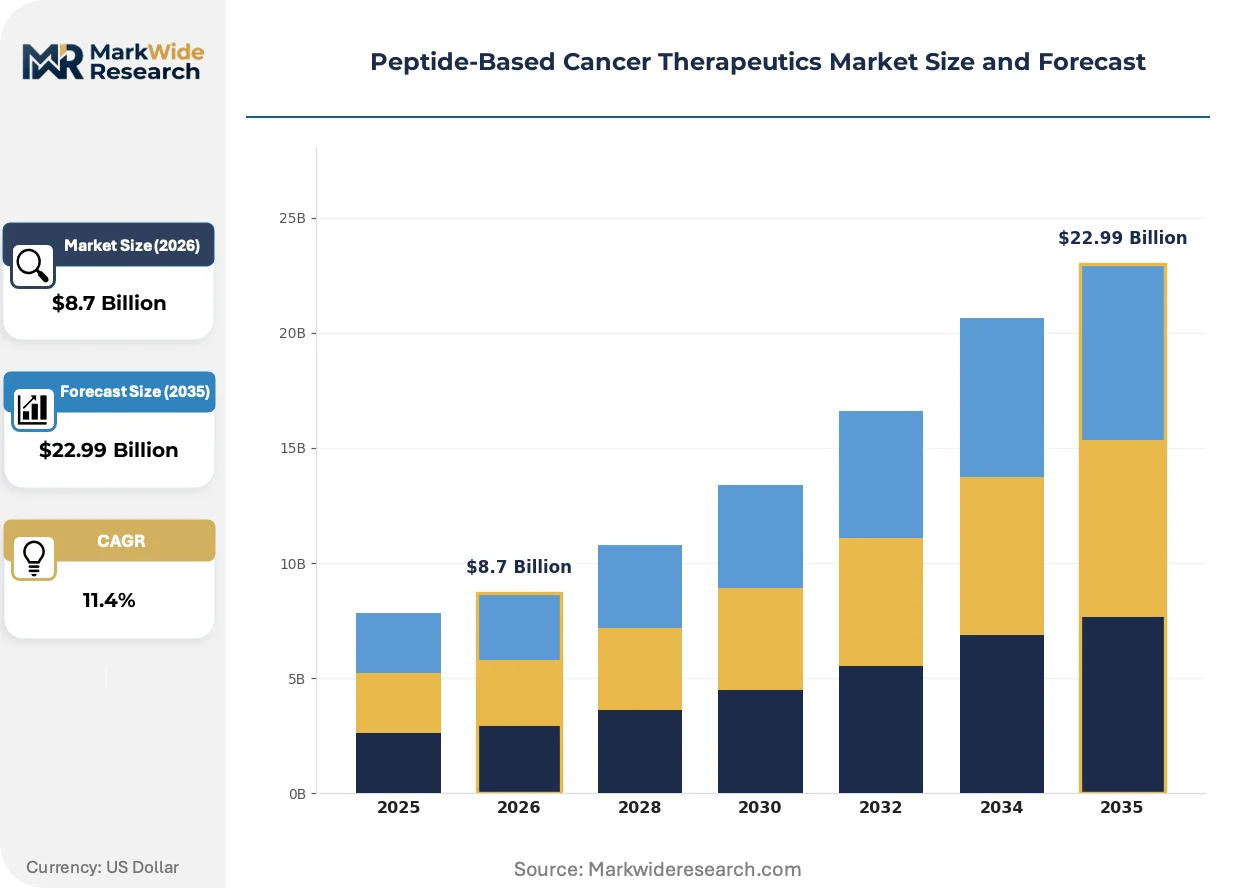
Market Dynamics
Hospital system consolidation is compressing procurement timelines for peptide-based cancer therapeutics while simultaneously elevating outcomes-based contracting requirements. This structural concentration shifts bargaining power toward integrated delivery networks and away from traditional pharmaceutical distribution channels.
Growth Catalysts
- FDA Accelerated Approval Pathway:The FDA's compressed review timeline for breakthrough-designated peptide-drug conjugates reduces time-to-market by 12-18 months compared to standard oncology approvals. Hospital oncology departments leverage this speed to secure first-mover protocol advantages.
- Subcutaneous Formulation Engineering:Advances in peptide stability excipients enable outpatient administration, slashing infusion center overhead and aligning with Medicare reimbursement shifts toward ambulatory settings.
- United States Demand Concentration:Academic medical centers in Boston, Houston, and San Diego anchor clinical adoption through investigator-initiated trials that validate peptide platforms for solid tumor indications.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Contract manufacturing organizations in Switzerland and South Korea control 70% of GMP peptide synthesis capacity, creating single-source vulnerability for mid-stage developers.
- Cold Chain Complexity:Peptide therapeutics require 2-8°C distribution integrity, elevating logistics costs 3-4x above small-molecule equivalents and limiting rural hospital access.
- Reimbursement Uncertainty:CMS's evolving National Coverage Determination framework for peptide-drug conjugates creates 6-12 month payment lag post-FDA approval, straining hospital pharmacy budgets.
Strategic Opportunities
- Japan's Sakigake Designation:Japan's PMDA offers priority review and extended market exclusivity for peptide oncology agents with domestic clinical development, opening a $4 billion reimbursement pool with faster access than US or EU pathways.
- AI-Driven Peptide Discovery:Convergence of deep learning sequence prediction and automated solid-phase synthesis compresses lead optimization from 24 months to 8 months, enabling platform economics for rare tumor targets.
- Specialty Pharmacy Networks:CVS Specialty and Accredo are building peptide-specific clinical support infrastructure, creating direct-to-patient channels that bypass hospital markup and capture margin through adherence programs.
Industry Challenges
- Peptide Chemist Talent Scarcity:Solid-phase synthesis expertise concentrates among chemists trained at MIT, ETH Zurich, and Osaka University, with industry demand outpacing academic pipeline output by 40%.
- Multifunctional Conjugate Scale-Up:Linker-payload optimization requires $50-80 million dedicated manufacturing investment, forcing developers to choose between dilutive partnerships and delayed commercialization.
- Biosimilar Peptide Definition:FDA's evolving guidance on analytical similarity for complex peptide mixtures creates regulatory ambiguity that extends pre-approval inspection cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peptide-Based Cancer Therapeutics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecule Inhibitors, Cytokines, Immune Checkpoint Inhibitors Therapy Area: Oncology, Hematology, Immunology, Neurology End User: Hospitals, Clinics, Research Institutes, Pharmaceutical Companies Delivery Mode: Intravenous, Subcutaneous, Oral, Topical |
| Companies Covered | Novartis AG, AstraZeneca PLC, Pfizer Inc., Eli Lilly and Company, Amgen Inc., Bristol Myers Squibb Company, Roche Holding AG, Merck & Co., Inc., Ipsen SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peptide-Based Cancer Therapeutics Market Evolving Landscape
Computational design tools are rewiring peptide discovery workflows, compressing candidate identification while expanding targetable tumor antigens beyond classical receptor classes. These advances intersect with regulatory pathway innovation and care delivery restructuring to reshape competitive positioning.
Multispecific peptide constructs are overtaking single-target agents in investigator-initiated trial portfolios. These engineered scaffolds simultaneously engage tumor antigens and immune effector cells, amplifying cytotoxic precision. Major NCI-designated cancer centers in the United States have expanded their multispecific peptide trial slots by 200% since 2022, forcing contract research organizations to retool patient recruitment infrastructure around combination-arm complexity.
EMA's PRIME designation scheme is accelerating European market access for peptide oncology agents demonstrating substantial benefit over existing options. The scheme mandates early scientific dialogue and rolling review, compressing regulatory assessment by 4-6 months. Developers targeting glioblastoma and pancreatic cancer indications are prioritizing PRIME qualification to secure conditional reimbursement in Germany and France ahead of full pivotal data maturity.
Integrated delivery networks are consolidating peptide therapeutic procurement under centralized pharmacy and therapeutics committees. This buyer concentration displaces individual hospital formulary autonomy, replacing it with system-wide protocol standardization. The shift is most visible in Texas and Florida, where hospital chains exceeding 50 facilities now mandate peptide regimen approval through enterprise oncology value analysis teams rather than site-specific tumor boards.
Peptide-Based Cancer Therapeutics Market Segmentation
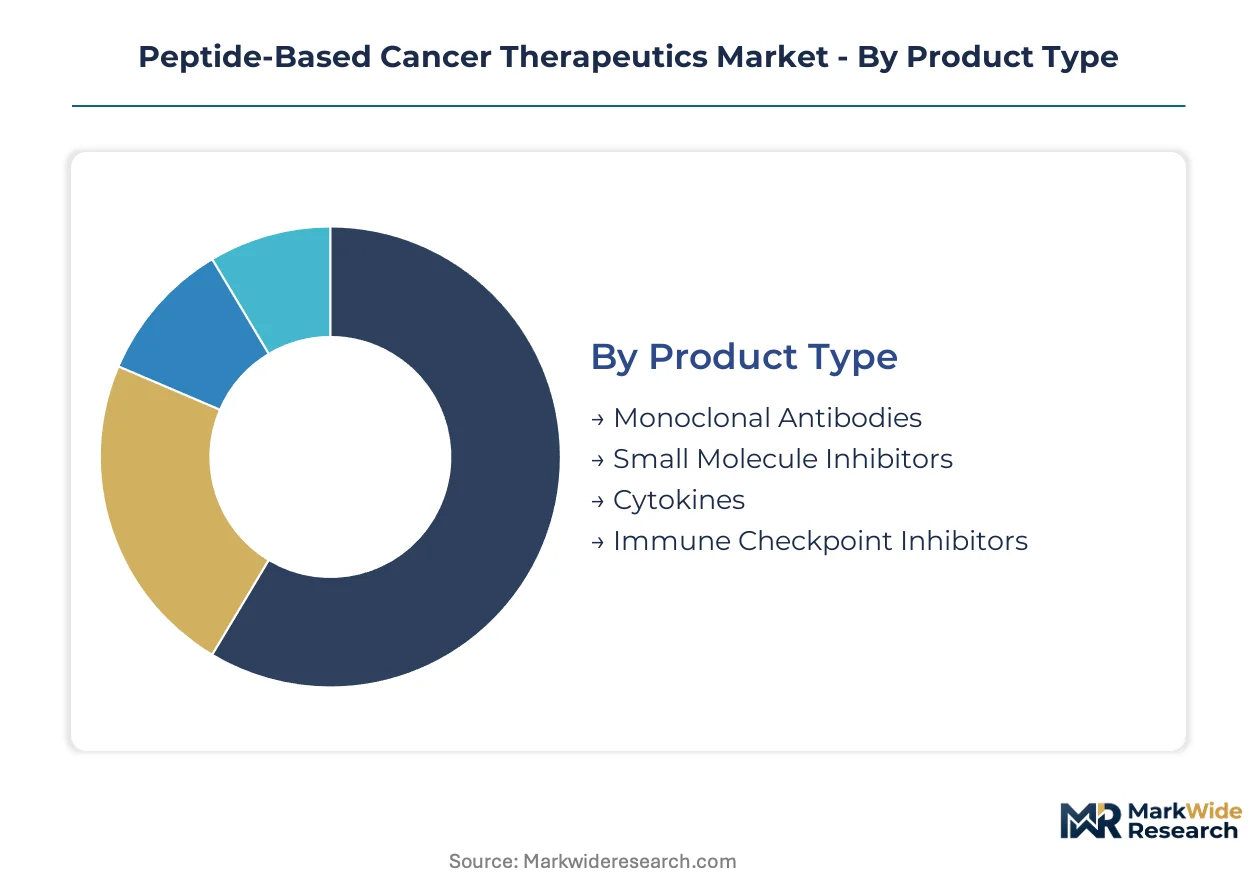
Peptide-based cancer therapeutics fragment across multiple technical and commercial dimensions. Each segmentation axis reveals distinct manufacturing requirements, reimbursement pathways, and customer procurement behaviors that reshape competitive strategy.
Product Type:
Customization intensity varies sharply across this category, from fully humanized biologics requiring mammalian cell culture to synthetic peptides amenable to solid-phase chemistry automation.
- Monoclonal Antibodies:These large-molecule biologics bind tumor-associated antigens with high specificity, demanding CHO cell manufacturing infrastructure and cold chain distribution. Demand clusters at NCI-designated cancer centers in the United States where established reimbursement codes minimize prior authorization friction. Hospital pharmacy budgets favor these agents for their predictable formulary placement despite higher per-dose costs.
- Immune Checkpoint Inhibitors:Engineered peptides disrupt PD-1/PD-L1 and CTLA-4 signaling pathways to restore T-cell cytotoxicity against tumor cells. Academic medical centers in Boston and Houston anchor adoption through investigator-initiated combination trials with existing oncology protocols. These agents command premium pricing through demonstrated survival benefits in melanoma and non-small cell lung cancer indications.
- Small Molecule Inhibitors:Synthetic peptide derivatives target intracellular signaling cascades with oral bioavailability and lower manufacturing complexity.
- Cytokines:Recombinant interleukins and interferons modulate systemic immune responses, though toxicity profiles limit first-line use.
Most installed capacity flows through Monoclonal Antibodies. Expansion is steepest in Immune Checkpoint Inhibitors.
Therapy Area:
Application maturity determines regulatory familiarity and clinical trial infrastructure availability, with oncology commanding disproportionate development resource allocation.
- Oncology:Peptide therapeutics target solid tumors and hematologic malignancies through antigen-directed cytotoxicity or immune modulation. The FDA's oncology division maintains specialized review teams for peptide-drug conjugates, compressing approval timelines compared to other therapeutic areas. Hospital infusion centers prioritize these agents for their alignment with existing chemotherapy administration workflows.
- Hematology:Peptide constructs address leukemia and lymphoma through CD19-directed and BCMA-targeted mechanisms, leveraging established bone marrow transplant referral networks.
- Immunology:Autoimmune applications remain exploratory, with fewer validated tumor antigen surrogates for target engagement.
- Neurology:Blood-brain barrier penetration challenges constrain peptide delivery to glioblastoma and metastatic brain lesions.
Clinical trial density concentrates in Oncology. Hematology is gaining share fastest through CAR-T combination protocols.
End User:
Procurement sophistication and reimbursement capture rates diverge substantially across customer types, from centralized hospital system purchasing to fragmented research grant funding.
- Hospitals:Integrated delivery networks consolidate peptide therapeutic procurement under pharmacy and therapeutics committees, replacing individual hospital formulary autonomy with enterprise-wide protocol standardization. Texas and Florida health systems exceeding 50 facilities now mandate peptide regimen approval through centralized value analysis teams.
- Pharmaceutical Companies:Contract manufacturing relationships and in-licensing agreements drive demand for peptide active pharmaceutical ingredients and linker-payload technologies.
- Clinics:Community oncology practices face reimbursement compression that limits access to high-cost peptide infusions without hospital outpatient department affiliation.
- Research Institutes:Academic laboratories source peptide reagents for preclinical validation, though volumes remain below commercial therapeutic scale.
Revenue concentration sits with Hospitals. Pharmaceutical Company partnerships are expanding most quickly through platform licensing deals.
Delivery Mode:
Administration complexity and care setting economics create sharp segmentation in patient access and margin capture.
- Intravenous:Infusion center delivery dominates current peptide therapeutic volume, requiring nursing supervision and adverse event monitoring infrastructure. Medicare reimbursement shifts toward hospital outpatient departments protect margin for this mode despite higher facility fees.
- Subcutaneous:Stability excipient advances enable self-administration, reducing infusion center overhead and aligning with ambulatory care migration incentives. CVS Specialty and Accredo are building peptide-specific clinical support infrastructure to capture adherence program revenue.
- Oral:Bioavailability challenges limit peptide uptake through gastrointestinal routes, though cyclization and lipid conjugation strategies show preclinical promise.
- Topical:Cutaneous lymphoma and melanoma applications represent niche use cases with localized delivery advantages.
Patient volume flows predominantly through Intravenous administration. Subcutaneous formulations are climbing the fastest as outpatient shift incentives intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement frameworks reward first-mover peptide protocols, while Japan's Sakigake designation offers faster exclusivity windows. Switzerland anchors contract manufacturing capacity, and Germany's hospital consolidation reshapes procurement. South Korea's bioclusters compete for peptide synthesis talent.
United States
Academic medical centers in Boston, Houston, and San Diego anchor clinical adoption through investigator-initiated trials. FDA's accelerated approval pathway compresses peptide-drug conjugate timelines by 12-18 months versus standard oncology reviews. Hospital systems in Texas and Florida exceeding 50 facilities now mandate enterprise-wide peptide regimen approval through centralized value analysis teams.
Germany
EMA's PRIME designation scheme accelerates European market access for peptide oncology agents with substantial benefit claims. Hospital system consolidation across North Rhine-Westphalia and Bavaria shifts procurement leverage toward integrated delivery networks. The country's contract research organizations retool patient recruitment infrastructure around multispecific peptide combination-arm complexity.
Switzerland
Contract manufacturing organizations control approximately 70% of GMP peptide synthesis capacity, creating single-source vulnerability for mid-stage developers. Swissmedic maintains specialized review teams for complex peptide mixtures, though evolving biosimilar guidance extends pre-approval inspection cycles. Basel and Zurich anchor linker-payload optimization expertise for peptide-drug conjugate production.
Japan
PMDA's Sakigake designation offers priority review and extended market exclusivity for peptide oncology agents with domestic clinical development. Osaka University trains solid-phase synthesis chemists whose expertise industry demand outpaces by 40%. The Kanto region's pharmaceutical clusters target a $4 billion reimbursement pool with faster access than US or EU pathways.
South Korea
CDSCO-aligned regulators and biocluster investments attract peptide chemist talent competing with Swiss and US concentrations. Seoul Capital Area contract manufacturers expand GMP peptide synthesis capacity to reduce single-source dependencies. Domestic developers leverage automated solid-phase synthesis to compress lead optimization timelines for rare tumor targets.
Peptide-Based Cancer Therapeutics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across peptide-based cancer therapeutics. Large-cap pharmaceutical companies anchor manufacturing scale and geographic distribution networks. Mid-tier biotechnology firms concentrate R&D intensity in targeted peptide platforms. The competitive terrain rewards backward integration into linker-payload technologies and strategic partnerships with contract manufacturing organizations.
Among Swiss-based pharmaceutical conglomerates, Novartis AG and Roche Holding AG occupy positions defined by deep manufacturing infrastructure in peptide-drug conjugate production. US-based Eli Lilly and Company exemplifies the R&D-intensive archetype through targeted peptide platform investments. Bristol Myers Squibb represents geographic dominance in North American infusion center networks. These three anchors illustrate how scale, specialization, and distribution access create distinct competitive moats.
| Leading Market Players |
|---|
| Novartis AG |
| AstraZeneca PLC |
| Pfizer Inc. |
| Eli Lilly and Company |
| Amgen Inc. |
| Bristol Myers Squibb Company |
| Roche Holding AG |
| Merck & Co., Inc. |
| Ipsen SA |
| Others |
Value Network & Pricing Analysis
Hospital system consolidation across Texas and Florida is forcing peptide therapeutic suppliers to restructure contract terms around outcomes-based milestones, compressing upfront margins while extending revenue recognition timelines. This buyer-side concentration elevates bargaining leverage for integrated delivery networks and redirects supplier investment toward value demonstration infrastructure.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for GMP peptide synthesis, intensifying competition with Swiss incumbents. Three-tier pricing structure across premium, standard, and economy levels segments by manufacturing complexity and regulatory filing status. Pricing pressure stems from CMS reimbursement lag post-FDA approval, straining hospital pharmacy budgets. Community oncology practices exhibit highest price sensitivity due to reimbursement compression, while NCI-designated cancer centers prioritize clinical efficacy over per-dose cost.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume peptide-drug conjugate demand from integrated delivery networks, with specialty pharmacy networks capturing subcutaneous formulation distribution. Manufacturing concentrates in Switzerland, South Korea, and the United States. Supply rests on solid-phase synthesis resins, linker-payload technologies, and cold chain logistics infrastructure. Single-source vulnerability pervades mid-stage developers dependent on Swiss CMOs. Distribution runs through hospital outpatient departments and CVS Specialty, Accredo for self-administered agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
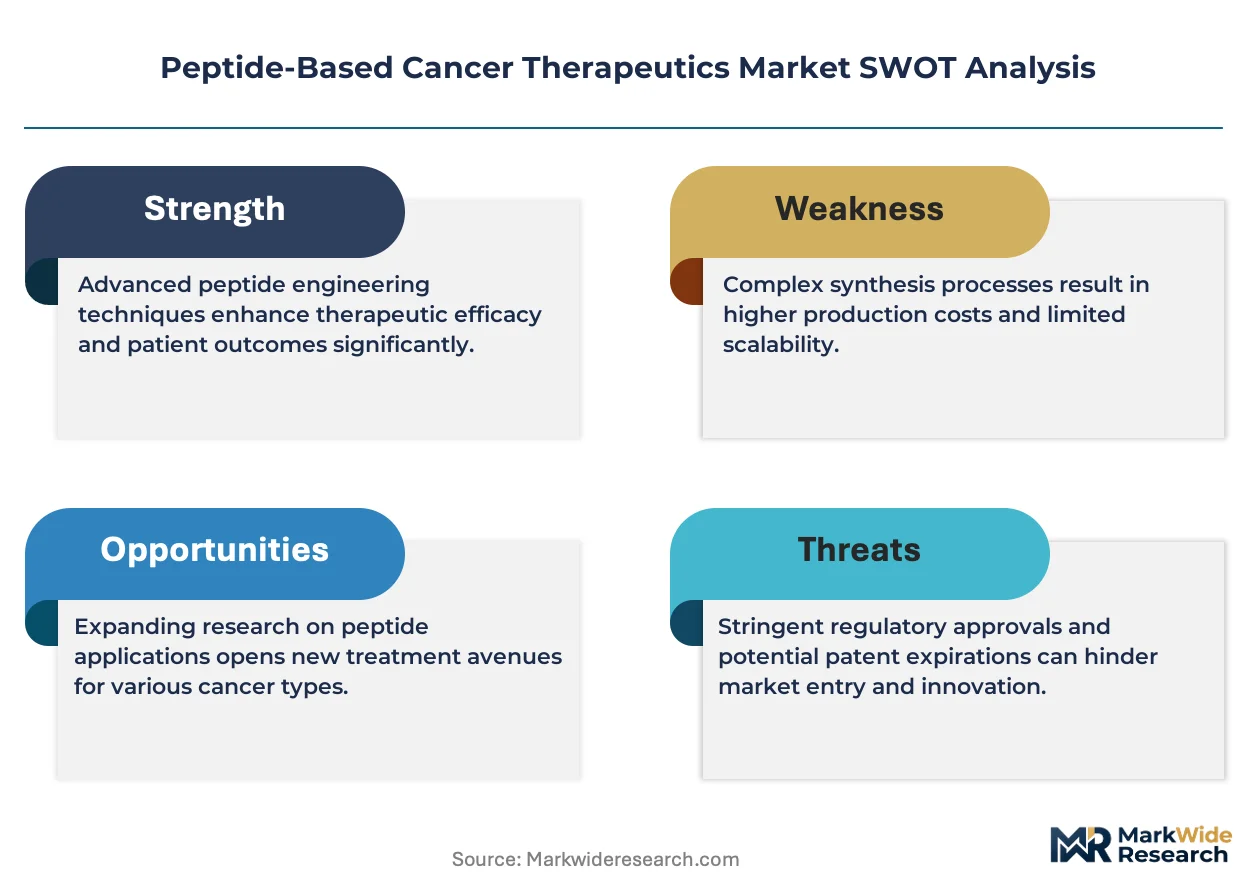
Peptide-based cancer therapeutics offer margin expansion through subcutaneous formulation premiums and automated synthesis cost reductions. The shift toward outpatient administration creates pricing power for stability-enabled products.
For Market Incumbents: Anticipate biosimilar peptide competition by deepening backward integration into linker-payload manufacturing and securing exclusive CMO capacity in Basel and Seoul. Invest in FDA breakthrough therapy designation pursuit to compress approval timelines and lock in protocol adoption ahead of reimbursement uncertainty. Prioritize hospital system partnership structures that embed peptide regimens within enterprise value analysis frameworks. For New Entrants and Emerging Players: Specialty pharmacy networks present the most penetrable channel for subcutaneous peptide formulations, bypassing hospital markup and capturing adherence program revenue. Target Japan's Sakigake designation pathway to secure faster exclusivity windows and access domestic reimbursement pools. Pursue AI-driven peptide discovery platforms to compress lead optimization timelines and enable rare tumor target economics. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-stage developers possessing proprietary linker-payload technologies and PRIME-qualified assets. Long-term viability hinges on regulatory pathway execution and manufacturing scale-up completion. Watch for FDA accelerated approval pathway utilization rates as inflection indicator for commercial traction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | CVS Specialty and Accredo infrastructure investments validate outpatient channel economics. |
| AI-Driven Peptide Discovery | Deep learning sequence prediction compresses lead optimization timelines for rare targets. |
| Japan Sakigake Designation Pursuit | PMDA priority review offers faster market access than FDA or EMA pathways. |
| Linker-Payload Manufacturing Integration | Swiss and South Korean CMO concentration creates captive supply advantages. |
| Hospital System Partnership Structuring | Texas and Florida IDN consolidation mandates enterprise-level protocol standardization. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down market sizing triangulated volume estimates across administration routes and therapy lines.
Historical reference periods anchored the forecast window to observed adoption curves for peptide-drug conjugates and immune checkpoint inhibitors. The analytical framework segmented by product type, therapy area, end user, and delivery mode, with regional regulatory clusters and reimbursement pathway maturity as cross-cutting dimensions. CAGRs derived from fitted growth curves adjusted for pipeline probability-weighted launch timing and hospital system consolidation pace.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS National Coverage Determination evolution and biosimilar peptide regulatory clarity. Assumptions reflect documented stakeholder input and published regulatory guidance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Anthelmintic Drugs Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Metformin HCL Drugs Market
Pharmaceuticals
P2X7 Receptor Antagonists Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Asia-Pacific Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Netupitant-Palonosetron FDC Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market