
 Spectrum Analyzer Market | 2026-2036
Spectrum Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Spectrum Analyzer Market Intelligence
Software-defined radio architectures and real-time digital signal processing is reshaping spectrum analyzer design, enabling faster sweep rates and deeper modulation analysis. Keysight Technologies leverages extensive calibration IP and mmWave test expertise to dominate high-frequency R&D segments. Rohde & Schwarz anchors European defense and aerospace procurement through ITAR-compliant manufacturing lines in Germany. Tektronix competes in the mid-range benchtop tier by extending oscilloscope integration into unified RF measurement platforms.
A spectrum analyzer measures signal amplitude versus frequency, typically spanning 9 kHz to 110 GHz with resolution bandwidth settings down to 1 Hz for precise interference detection. The instrument enables characterization of harmonic distortion, spurious emissions, and occupied bandwidth across wireless systems, serving as foundational equipment for RF compliance and network optimization. Real-time analyzers capture transient signals without dead time, a capability that semiconductor manufacturers prize for 5G mmWave chipset validation where swept-tuned architectures miss pulsed interferers. Handheld units now incorporate GPS tagging and automated limit-line testing, positioning field technicians to execute tower-mounted antenna system audits without transporting benchtop gear to remote sites.
The FCC enforces Part 15 unintentional radiator limits and Part 90 private land mobile rules that mandate periodic spurious emission testing, directly sustaining replacement demand for certified measurement equipment. ETSI harmonized standards under the Radio Equipment Directive require CE-marked spectrum analyzers for market access across EU member states, compelling vendors to maintain dual regulatory compliance portfolios. China's MIIT issues GB standards for radio transmission equipment that foreign manufacturers must satisfy through accredited local testing laboratories. Stakeholders must monitor evolving 6G research band allocations and corresponding measurement bandwidth requirements that will redefine instrument architecture roadmaps.
Market Dynamics
Defense procurement cycles and spectrum reallocation mandates are compressing replacement timelines for test equipment across broadcast, telecom, and military sectors. Real-time digital signal processing architectures now displace swept-tuned instruments in 5G validation workflows.
Growth Catalysts
- FCC Part 90 mandates:Private land mobile radio operators must conduct periodic spurious emission testing, sustaining certified equipment replacement demand across US infrastructure networks.
- 5G mmWave chipset validation:Semiconductor manufacturers require real-time capture capabilities for pulsed interferer detection in sub-THz frequency ranges.
- German defense procurement:ITAR-compliant manufacturing lines anchor European aerospace and electronic warfare test equipment sourcing.
Market Restraints
- Gallium nitride component costs:Front-end MMIC prices for high-frequency front-ends create margin pressure on mid-range instrument vendors.
- Calibration service concentration:Accredited metrology laboratories cluster in Germany, Japan, and the United States, extending lead times for emerging market customers.
- Software-defined radio substitution:Low-cost SDR platforms with open-source toolchains capture basic spectrum monitoring applications below 6 GHz.
Strategic Opportunities
- India telecom infrastructure:TRAI spectrum auction compliance requirements and 5G network densification create demand for field-portable analyzers with automated limit-line testing.
- 6G research pre-standardization:D-band and G-band measurement requirements above 100 GHz will necessitate entirely new instrument architectures before 2030.
- Cloud-native measurement platforms:Remote spectrum monitoring as-a-service models allow vendors to capture recurring revenue from distributed enterprise and utility networks.
Industry Challenges
- RF engineer scarcity:Millimeter-wave measurement expertise concentrates among legacy aerospace and defense contractors, constraining vendor technical support scaling.
- Multi-domain instrument integration:Customers demand unified vector network analyzer, oscilloscope, and spectrum analyzer platforms, forcing R&D portfolio complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spectrum Analyzer Market |
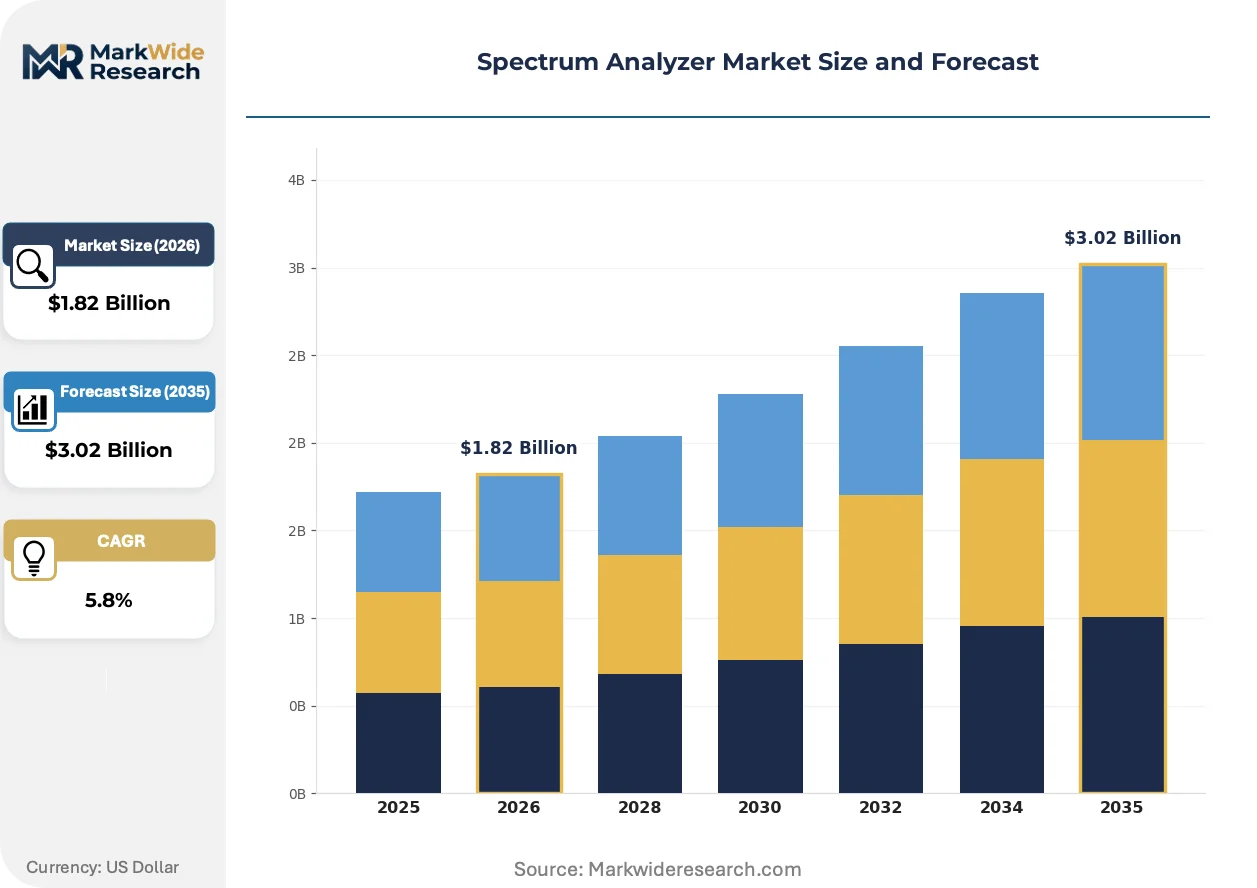
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.02 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Benchtop, Modular, Real-time, Portable Technology: Frequency Domain, Time Domain, Digital Signal Processing, Vector Signal Analysis, Swept-Tuned Application: Telecommunication Testing, Radar Monitoring, Signal Interference Analysis, Electronic Warfare, Broadcast Monitoring End User: Telecom Operators, Defense Agencies, Semiconductor Manufacturers, Research Laboratories, Broadcast Stations |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Tektronix (Fortive Corporation), Advantest Corporation, Anritsu Corporation, Yokogawa Electric Corporation, Teledyne Technologies, B&K Precision Corporation, National Instruments Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spectrum Analyzer Market Strategic Shifts & Innovations
Software-defined architectures and edge computing capabilities are collapsing the functional boundary between benchtop precision and field-portable convenience. Three developments are restructuring competitive positioning.
Deep learning-based signal classification is digitizing interference identification workflows. Cellular network operators in South Korea and Japan now deploy analyzers with on-device neural inference for automated modulation recognition. This compression of expert-dependent analysis into firmware is reducing field technician certification requirements and accelerating mean-time-to-repair metrics.
The EU Radio Equipment Directive's harmonized standards under CE marking are mandating traceable measurement uncertainty documentation for all RF equipment market access. Test laboratories in France, Germany, and Italy now require analyzers with embedded calibration certificate management. Vendors are responding by integrating automated self-test routines that generate audit-ready compliance reports without external metrology service intervention.
Acquisition patterns among tower maintenance contractors are favoring rental and lease models over capital purchase. Field service providers in Brazil and Mexico now source handheld units through regional test equipment distributors on project-based terms. This shift compresses manufacturer direct sales cycles and elevates distributor technical training capabilities as a competitive differentiator in Latin American markets.
Spectrum Analyzer Market Segmentation
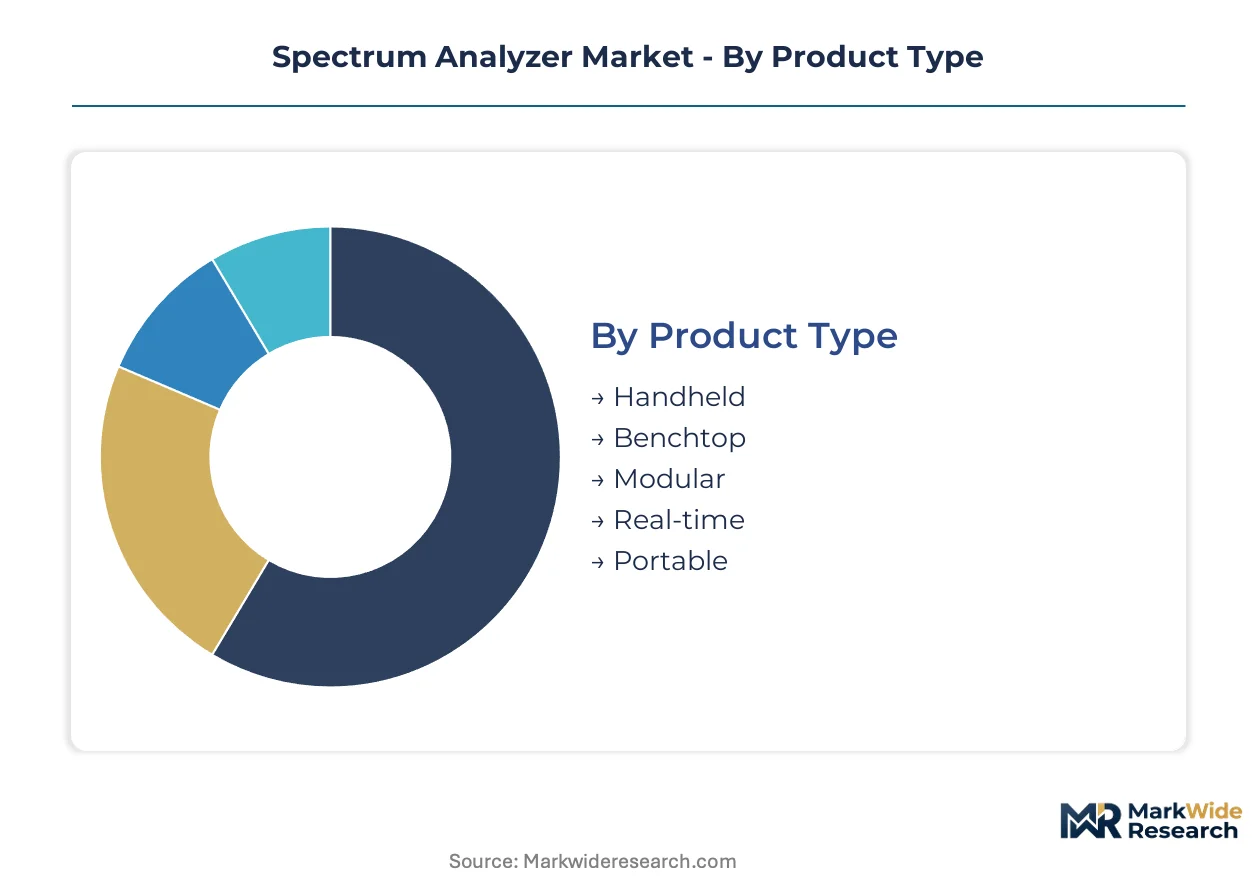
Segmentation in the spectrum analyzer market reflects divergent technical requirements across frequency ranges, portability needs, and measurement precision thresholds. Procurement patterns vary sharply between defense agencies demanding ITAR-compliant hardware and commercial operators prioritizing field-deployable units. Understanding these divides clarifies where R&D investment concentrates and which architectures face substitution pressure.
Product Type:
Cost tier determines architecture tradeoffs between measurement fidelity and deployment flexibility across laboratory, field, and embedded applications.
- Real-time:Zero-dead-time capture architectures process continuous RF streams through parallel FFT engines, enabling pulsed interferer detection in 5G mmWave validation workflows. Semiconductor manufacturers in South Korea and Japan deploy these units for sub-THz chipset characterization where swept instruments miss transient emissions.
- Benchtop:Precision instruments with sub-Hz resolution bandwidth and phase noise performance below -110 dBc/Hz anchor metrology laboratories and compliance certification facilities. Demand concentrates in Germany where Rohde & Schwarz maintains calibration-accredited manufacturing lines for European aerospace procurement.
- Handheld:Battery-operated units with GPS tagging and automated limit-line testing support tower-mounted antenna system audits without transport logistics.
- Modular:PXIe and USB-based architectures integrate into automated test systems for high-volume manufacturing environments.
- Portable:Mid-weight designs bridge field and laboratory use with reduced specifications versus benchtop equivalents.
Benchtop holds installed capacity. Real-time is rotating up the share rankings.
Technology:
Signal processing methodology defines sweep speed, dynamic range, and suitability for modulated carrier analysis versus pure spectral inspection.
- Digital Signal Processing:FPGA-based architectures implement real-time bandwidths exceeding 500 MHz with software-defined measurement personalities. Defense agencies in the United States procure DSP-heavy units for electronic warfare applications requiring rapid threat identification.
- Swept-Tuned:Superheterodyne architectures with preselector filtering deliver exceptional spurious-free dynamic range for harmonic and intermodulation distortion measurements. Broadcast stations rely on swept-tuned instruments for FCC Part 73 occupied bandwidth verification.
- Vector Signal Analysis:IQ demodulation capabilities enable error vector magnitude and constellation analysis for digital modulation formats.
- Frequency Domain:Traditional amplitude-versus-frequency presentation dominates general-purpose spectral monitoring.
- Time Domain:Time-correlated capture supports transient event analysis and pulsed RF characterization.
Swept-Tuned dominates replacement cycles. Digital Signal Processing is climbing the fastest.
Application:
End-use environment shapes instrument specifications from tower-climbing portability to anechoic chamber precision.
- Telecommunication Testing:5G NR and emerging 6G research drive demand for mmWave-capable analyzers with beamforming measurement functions. TRAI spectrum auction compliance requirements in India create field-portable demand for automated limit-line testing.
- Electronic Warfare:Real-time spectral awareness, direction-finding, and signal classification for military platforms require ruggedized units with classified firmware capabilities. German defense procurement anchors European sourcing through ITAR-compliant supply chains.
- Signal Interference Analysis:Cellular operators deploy handheld units with on-device neural inference for automated modulation recognition.
- Radar Monitoring:Pulsed RF characterization demands time-gated spectrum analysis and wide instantaneous bandwidth.
- Broadcast Monitoring:FCC Part 15 and Part 90 spurious emission mandates sustain certified equipment replacement across US infrastructure networks.
Telecommunication Testing holds installed capacity. Electronic Warfare is rotating up the share rankings.
End User:
Customer type governs procurement volume, specification stringency, and service contract structures.
- Defense Agencies:Multi-year procurement cycles emphasize cybersecurity-hardened firmware, environmental ruggedization, and long-term calibration support. The United States Department of Defense expands real-time spectrum analyzer acquisition for electronic warfare modernization programs.
- Semiconductor Manufacturers:High-volume validation workflows prioritize automation interfaces and wafer-prober integration for sub-THz device characterization.
- Telecom Operators:Tower maintenance contractors favor rental models over capital purchase, compressing manufacturer direct sales cycles.
- Research Laboratories:Academic and government research facilities drive early adoption of D-band and G-band measurement capabilities above 100 GHz.
- Broadcast Stations:FCC spectrum reallocation mandates force equipment upgrades across terrestrial television and radio transmission infrastructure.
Defense Agencies holds installed capacity. Semiconductor Manufacturers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export ITAR-compliant spectrum analyzers to United States defense agencies, while South Korean semiconductor fabs import real-time architectures for sub-THz validation workflows.
United States
Department of Defense electronic warfare modernization and FCC Part 90 spurious emission mandates drive procurement. The FCC enforces periodic testing requirements across private land mobile radio networks. Boston-area research clusters pioneer D-band measurement capabilities above 100 GHz for 6G pre-standardization.
Germany
European aerospace procurement and ITAR-compliant manufacturing anchor regional demand. CE marking under the EU Radio Equipment Directive mandates traceable measurement uncertainty documentation. Munich and Stuttgart host calibration-accredited production lines serving defense and broadcast compliance sectors.
China
MIIT GB standards for radio transmission equipment and 5G network densification sustain instrument demand. The Ministry of Industry and Information Technology requires accredited local testing for foreign manufacturer market access. Shenzhen and Shanghai clusters concentrate semiconductor validation workflows for domestic chipset producers.
India
TRAI spectrum auction compliance and 5G infrastructure rollout create field-portable analyzer demand. The Telecom Regulatory Authority of India mandates automated limit-line testing for network densification. Bangalore and Hyderabad tower maintenance contractors favor rental models over capital purchase.
Japan
METI-funded 6G research initiatives and cellular operator network optimization drive adoption. The Ministry of Economy, Trade and Industry supports D-band and G-band measurement development. Tokyo-Osaka corridor deploys on-device neural inference for automated modulation recognition in interference identification.
Spectrum Analyzer Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered price-performance segments. The vendor base clusters around three strategic archetypes: precision metrology houses with calibration-accredited manufacturing, mid-range benchtop integrators leveraging oscilloscope synergies, and field-portable specialists serving tower maintenance contractors. Dominant competitive moves include backward integration into front-end MMIC sourcing and geographic expansion through distributor technical training programs.
Within the precision metrology tier, Keysight Technologies and Rohde & Schwarz occupy positions defined by extensive calibration IP and ITAR-compliant European manufacturing respectively. Tektronix exemplifies the mid-range benchtop archetype through unified RF measurement platform strategies. These three entities anchor competitive dynamics across defense procurement, semiconductor validation, and broadcast compliance verticals without exhaustive market coverage claims.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Tektronix (Fortive Corporation) |
| Advantest Corporation |
| Anritsu Corporation |
| Yokogawa Electric Corporation |
| Teledyne Technologies |
| B&K Precision Corporation |
| National Instruments Corporation |
| Others |
Cost & Logistics Intelligence
The Hamburg-Port of Rotterdam freight corridor sets cost baselines that cascade through German manufacturing clusters and amplify price differentiation between ITAR-certified defense-grade units and standard commercial instruments. Gallium nitride MMIC sourcing constraints concentrate in accredited German and Japanese foundries, tightening supply for high-frequency front-ends while mid-range vendors absorb margin compression through simplified architectures.
Pricing Analysis
Current-generation real-time analyzers command substantial premiums over swept-tuned architectures, while next-generation D-band instruments remain pre-commercial with development-phase pricing. Three-tier pricing structure across premium, standard, and economy levels separates ITAR-certified defense procurement from broadcast compliance and field-portable rental fleets. Price differentiation rests on calibration accreditation status and embedded software measurement personalities. Cost compression in the mid-range tier is intensifying because SDR platforms capture sub-6 GHz monitoring applications. Tower maintenance contractors exhibit highest price sensitivity, prioritizing rental access over capital ownership.
Supply Chain Analysis
Export-control regimes under ITAR and EAR restrictions limit GaN MMIC and FPGA flows to accredited defense contractors, fragmenting component availability across compliance tiers. Manufacturing concentrates in Germany, the United States, and Japan, with calibration-accredited production lines anchoring European and North American demand. Raw material dependencies span GaN substrates, high-speed ADCs, and precision microwave connectors. Single-source vulnerability concentrates in metrology-grade oscillator supply. Distribution runs through authorized technical distributors with field-training capabilities in Brazil, Mexico, and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities multiply as 5G network densification and 6G pre-standardization create specialized measurement niches beyond legacy incumbents' core defense and broadcast strongholds. The demand-side shift toward rental models and cloud-native monitoring platforms fragments procurement authority away from centralized R&D budgets.
For Market Incumbents: Insulate calibration-accredited manufacturing positions by backward integration into GaN front-end sourcing and captive metrology service networks. Software-defined radio substitution in sub-6 GHz segments threatens mid-range benchtop volumes. Priority levers include ITAR-compliant firmware development and distributor technical training programs in Latin American rental markets.
For New Entrants and Emerging Players: Build out cloud-native spectrum monitoring-as-a-service platforms targeting utility and enterprise distributed networks. India's TRAI compliance requirements and tower maintenance rental demand represent the most penetrable white-space. Go-to-market angle: project-based equipment provisioning with embedded automated limit-line testing.
For Investors and Strategic Acquirers: Carve-out targets emerge from test equipment divisions of diversified industrial conglomerates seeking portfolio simplification. Long-term viability frames around recurring revenue capture from distributed monitoring services versus transactional instrument sales. Acquisition target archetype: field-portable specialists with established rental channel relationships. Signal to watch: 6G research funding allocations accelerating D-band instrument development timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN MMIC Sourcing | Captive supply of high-frequency front-ends insulates margin pressure from component cost volatility. |
| Cloud-Native Monitoring Platform Launch | Recurring revenue models capture utility network demand beyond traditional capital equipment cycles. |
| Distributor Technical Training Expansion | Authorized channel capabilities in Brazil and Mexico match tower maintenance contractor rental preferences. |
| ITAR-Compliant Firmware Development | Cybersecurity-hardened architectures sustain Department of Defense electronic warfare procurement access. |
| Automated Calibration Certificate Integration | Embedded self-test routines satisfy EU Radio Equipment Directive audit requirements without external metrology. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with RF test equipment product managers, defense procurement officers, semiconductor validation engineers, and tower maintenance contractors; and secondary validation through FCC equipment authorization databases, ETSI harmonized standards filings, MIIT GB standard registrations, and customs trade flow records. Bottom-up segment sizing triangulated against top-down industry expenditure estimates from national spectrum auction disclosures and defense modernization budget documents.
Forecast inputs considered product type evolution, technology displacement rates, application penetration patterns, and end-user procurement model shifts across the projection horizon. Segmentation dimensions modeled include frequency range tier, portability class, signal processing architecture, and regional regulatory compliance cluster. CAGRs derived from installed base replacement cycles, 5G infrastructure deployment trajectories, and 6G research funding acceleration. Industry-specific inputs encompassed GaN component cost curves and calibration service capacity expansion.
The forecast holds incumbent behavior within observed patterns; aggressive moves by SDR platform vendors or hyperscaler cloud entrants would shift outcomes. Material shifts in ITAR export control scope, 6G band allocation timelines, or GaN foundry capacity expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Benchtop Ph Meters Market
Analytical Instruments
Dissolved Gas Analyzer Market
Analytical Instruments
Ph Meters Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Analytical Balance Market
Analytical Instruments
Dew Point Analyzer Market
Analytical Instruments
Elemental Analyzer Market
Analytical Instruments
Global Particle Size Analyzer Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
Surface Plasmon Resonance Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Signal Analyzer Market