
 High-Power Objective Lens Market | 2026-2036
High-Power Objective Lens Market Size, Share, and Industry Trends Forecast 2026-2036
High-Power Objective Lens Market Insights
Semiconductor fabs are collapsing the historical pricing premium that academic institutions once commanded in high-power objective procurement. Nikon Corporation leverages its fluorite crystal supply chain to sustain apochromatic output for sub-2nm wafer inspection lines. Olympus Corporation anchors biological research demand through dedicated microscopy channels in Japanese and European academic markets. Carl Zeiss AG competes on precision assembly tolerances below 50 nanometers for lithography-adjacent metrology tools.
A high-power objective lens is a magnifying optical element engineered with numerical apertures exceeding 0.65, typically assembled from fluorite or extra-low dispersion glass and anti-reflection multi-coatings to minimize chromatic aberration across ultraviolet to near-infrared spectra. Its primary purpose is resolving sub-micron structures in semiconductor wafer inspection, live-cell fluorescence microscopy, and metallurgical failure analysis. Apochromatic designs command the dominant margin pool due to their three-wavelength correction and indispensability in semiconductor defect review. Fluorite crystal variants represent the fastest-growing technology segment as foundries demand superior transmission at 193nm and 248nm wavelengths for advanced process control. Plan achromatic categories remain mature workhorses in quality control units where cost sensitivity limits specification creep.
The US FDA regulates optical instruments used in pharmaceutical testing and clinical pathology, while Japan's METI administers JIS standards for precision optical components exported under strategic goods classifications. China's SAMR enforces GB standards on imported microscopy equipment, creating compliance barriers for uncertified suppliers. Europe's RoHS and REACH frameworks restrict hazardous substances in lens coatings and housing alloys, forcing reformulation of legacy optical cements. Stakeholders must monitor diverging certification timelines across these jurisdictions to avoid stranded inventory in multi-regional supply chains.
Market Dynamics
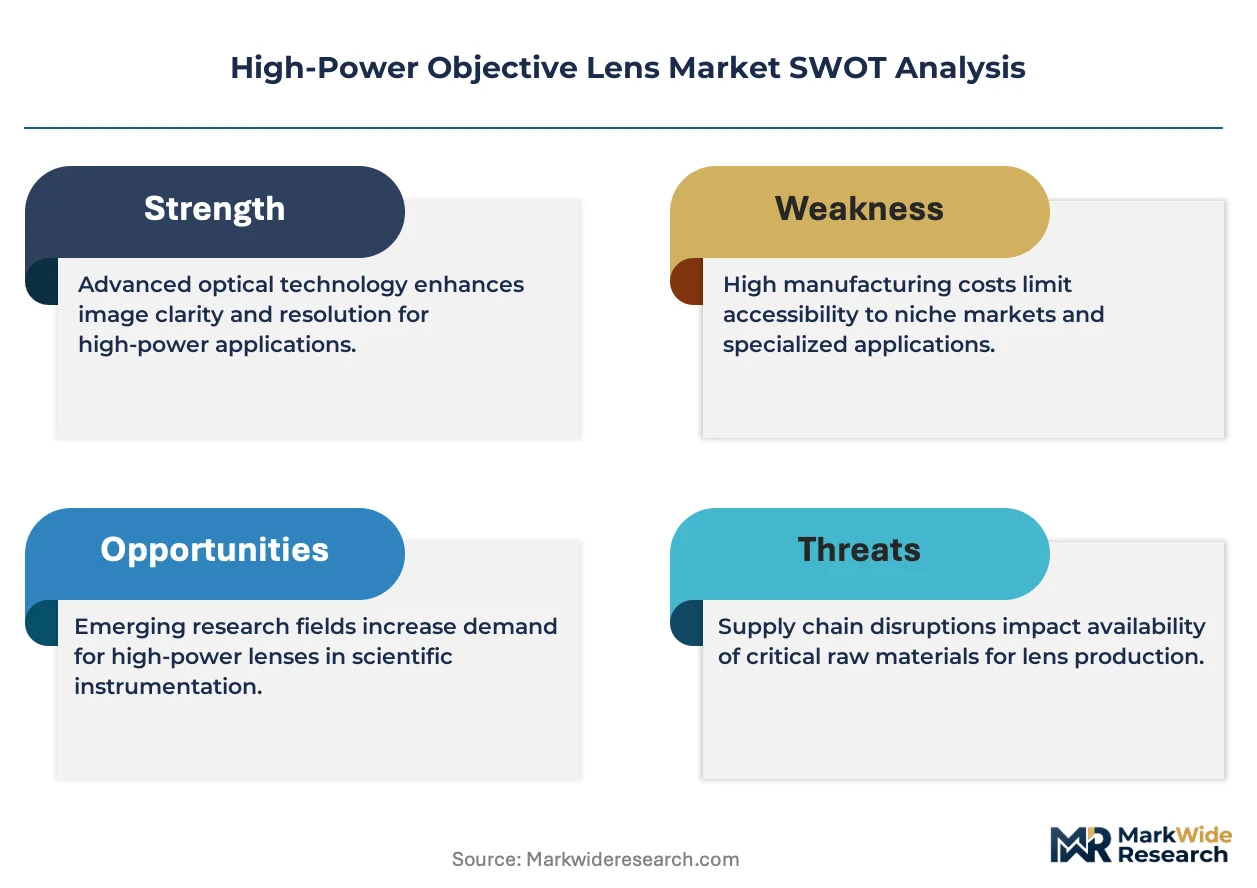
Semiconductor fabs below 3nm nodes are collapsing the traditional academic-institution pricing premium in high-power objective procurement, redirecting volume toward apochromatic and fluorite variants certified for wafer inspection lines.
Growth Catalysts
- Sub-2nm Node Expansion:Foundries in Hsinchu and Yokohama are scaling fluorite crystal consumption for extreme ultraviolet and deep ultraviolet process control, pulling premium objective specifications into mass production.
- MIIT Domestic Substitution Mandates:China's Ministry of Industry and Information Technology directives are redirecting state-backed procurement toward certified local suppliers, creating captive demand pools for indigenous lens manufacturers.
- Live-Cell Fluorescence Microscopy:Pharmaceutical R&D pipelines in Basel and Boston are demanding apochromatic correction for super-resolution imaging, sustaining biological research as a parallel demand pillar.
Market Restraints
- Fluorite Supply Concentration:Optical-grade fluorite crystal extraction concentrates in specific geological formations, exposing lens assemblers to input volatility when mining jurisdictions restrict export permits.
- Precision Assembly Bottleneck:Achieving sub-50 nanometer alignment tolerances requires specialized metrology environments that cannot be replicated without multi-year facility investments.
- REACH Reformulation Costs:Europe's Registration, Evaluation, Authorisation and Restriction of Chemicals framework is forcing reformulation of legacy optical cements and anti-reflection coatings, stranding pre-certified inventory.
Strategic Opportunities
- India Pharmaceutical Microscopy:The country's national pharmaceutical regulator is expanding good manufacturing practice inspection capacity, creating demand for certified metallurgical failure analysis systems in Mumbai and Hyderabad clusters.
- Quantum Dot Metrology Convergence:Integration of cryogenic objective designs with quantum sensing platforms is opening specifications for ultra-low thermal expansion housings in national laboratory procurement.
- METI Precision Equipment Incentives:Japan's Ministry of Economy, Trade and Industry subsidies for domestic optical component production are accelerating foundry-adjacent metrology tool development in Nagoya precision manufacturing zones.
Industry Challenges
- Optical Design Talent Scarcity:The intersection of Zemax proficiency and semiconductor process knowledge is concentrating among a narrow cohort of specialists, extending product development timelines for mid-tier assemblers.
- Multi-Jurisdiction Certification Lag:Simultaneous compliance with China's GB standards, Japan's JIS classifications, and US FDA optical instrument regulations is creating stranded inventory risk in regional distribution hubs.
- Legacy Microscope Integration Friction:Retrofitting apochromatic objectives onto existing turret systems requires mechanical adapter engineering that optical houses cannot amortize at low volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Power Objective Lens Market |
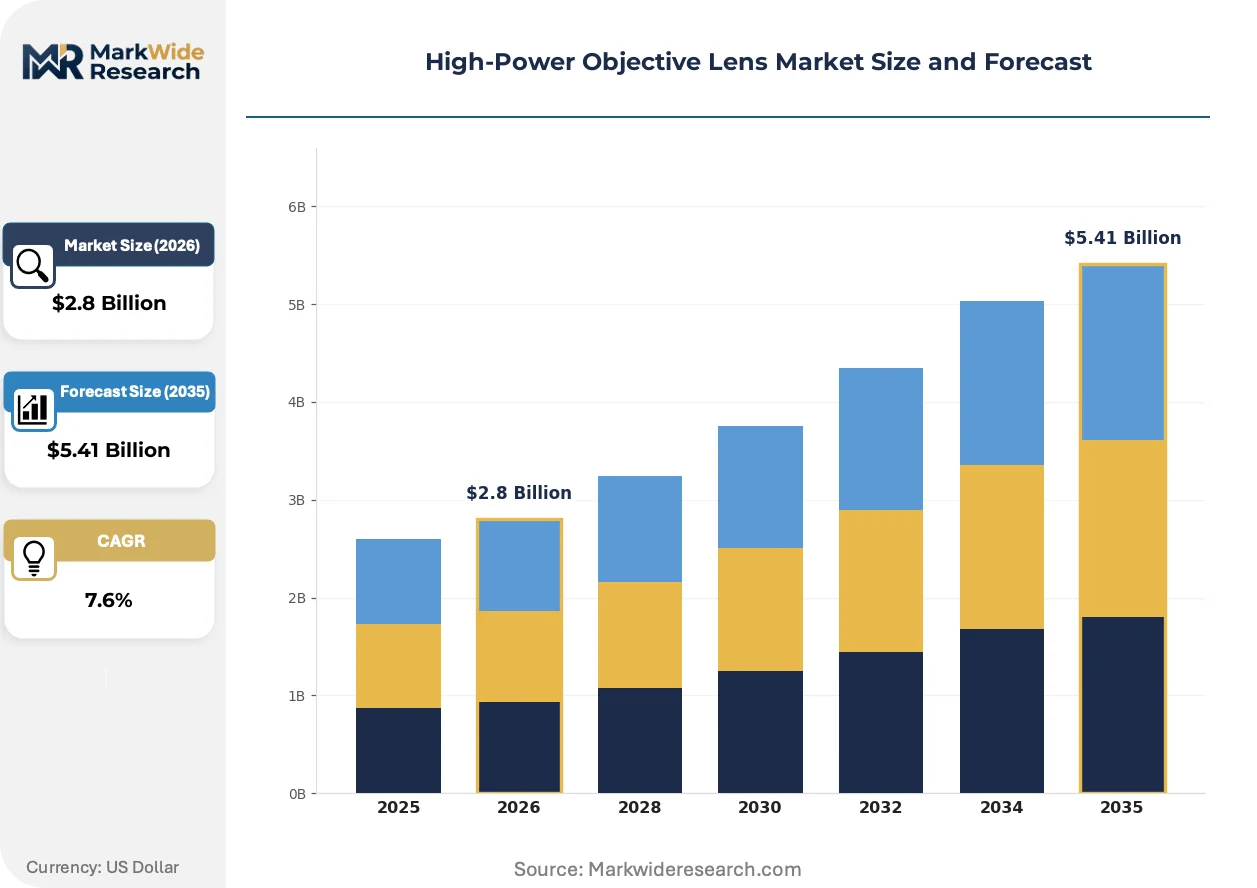
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Achromatic, Plan Achromatic, Fluorite, Apochromatic, Semi-Apochromatic Application: Biological Research, Semiconductor Inspection, Metallurgical Analysis, Pharmaceutical Testing, Forensic Examination Technology: Optical Glass, Multi-Coated Lens, Fluorite Crystal, Digital Imaging, Laser Scanning End User: Academic Institutions, Research Laboratories, Quality Control Units, Forensic Labs, Biotechnology Firms |
| Companies Covered | Olympus Corporation, Carl Zeiss AG, Leica Microsystems, Nikon Corporation, Canon Inc., Edmund Optics, Mitutoyo Corporation, Thorlabs, Jenoptik AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Power Objective Lens Market Trends and Innovations
Computational imaging pipelines and solid-state light sources are decomposing the historical monopoly of purely optical aberration correction, forcing objective manufacturers to embed software-calibrated performance guarantees alongside physical specifications.
Fluorite crystal variants with engineered ultraviolet transmission profiles are decomposing the market dominance of synthetic fused silica in 193nm wafer inspection applications. Taiwan Semiconductor Manufacturing and Samsung Foundry are qualifying these materials for high-volume defect review stations. The shift is compressing acceptable chromatic focal shift tolerances from three wavelengths toward five-wavelength correction standards.
Japan's METI-administered JIS B 7263 precision optical component standards are tightening dimensional tolerance specifications for objectives exported under strategic goods classifications. Lens houses in Yokohama are re-qualifying assembly lines to maintain export eligibility. Semiconductor metrology tool integrators are absorbing compliance costs through captive metrology investments rather than supplier audits.
Academic institutions are unbundling objective procurement from full microscopy system purchases, creating standalone lens replacement cycles independent of instrument refresh timelines. Olympus Corporation and Nikon Corporation have responded with dedicated microscopy channel programs in Japanese and European university markets. The pattern is most visible in German Max Planck Institute and French CNRS laboratory procurement frameworks.
High-Power Objective Lens Market Segmentation
High-power objective lens procurement channels diverge sharply by performance tier and end-use certification requirements. Semiconductor fabs route premium specifications through direct OEM partnerships, while academic and forensic segments distribute through microscopy specialists and institutional procurement frameworks.
Product Type:
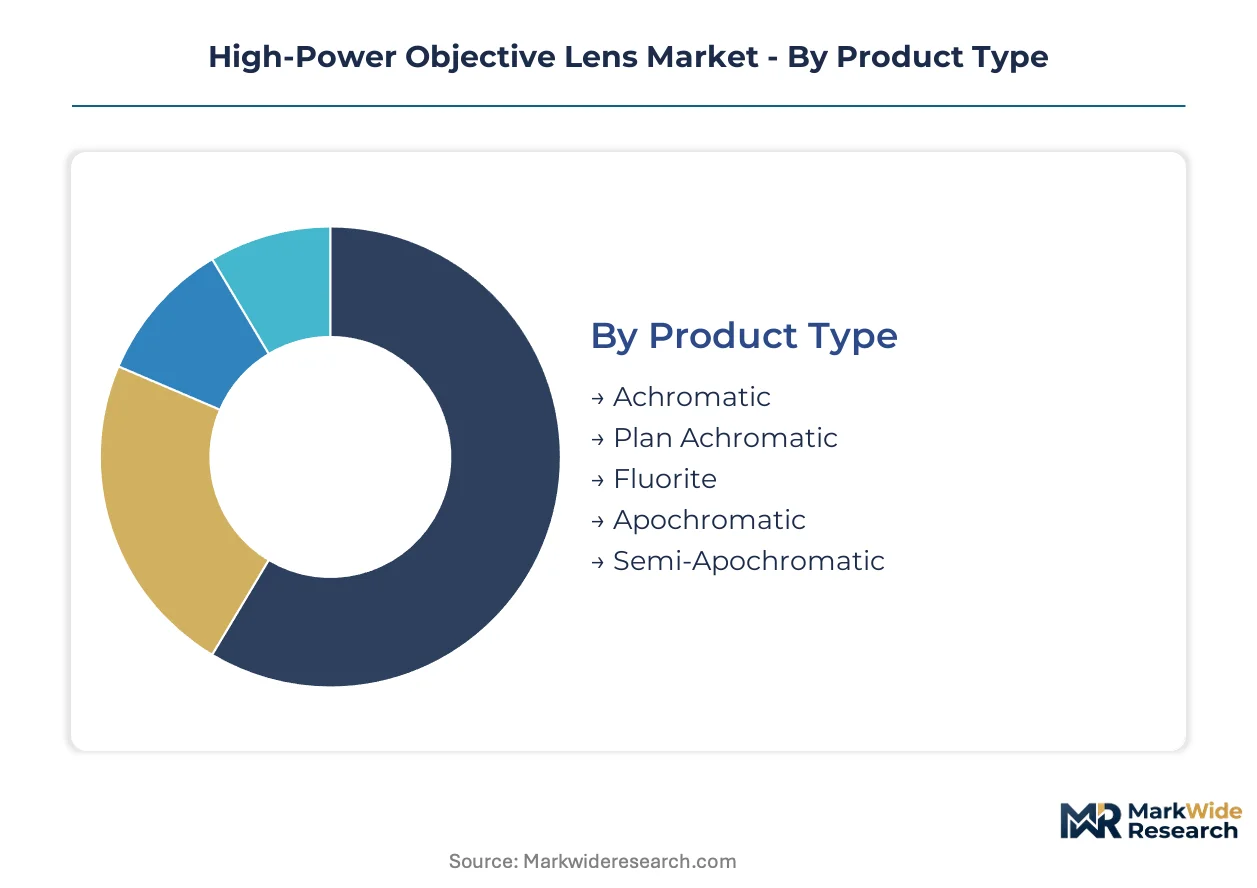
Channel mix varies by correction grade: apochromatic and fluorite variants flow predominantly through semiconductor equipment integrators, while achromatic and plan achromatic categories serve cost-sensitive quality control units via distributor networks.
- Apochromatic:Three-wavelength chromatic correction engineered from fluorite and extra-low dispersion glass combinations. Demand concentrates in Hsinchu and Yokohama foundry clusters where sub-2nm wafer inspection mandates five-wavelength focal shift tolerances. Nikon Corporation leverages captive fluorite supply chains to maintain output for these lines.
- Fluorite:Natural calcium fluoride crystal construction delivering superior ultraviolet transmission at 193nm and 248nm wavelengths. Taiwan Semiconductor Manufacturing and Samsung Foundry are qualifying these materials for high-volume defect review stations, displacing synthetic fused silica in advanced process control applications.
- Achromatic:Two-wavelength correction suitable for routine microscopy in educational settings.
- Plan Achromatic:Flat-field design serving mature quality control units where cost sensitivity limits specification creep.
- Semi-Apochromatic:Intermediate correction grade bridging performance and cost for mid-tier research applications.
By volume, plan achromatic leads. By growth pace, fluorite is ahead.
Application:
Cost tier stratification separates semiconductor inspection—where single objectives command premium pricing—from forensic and metallurgical segments operating on institutional budget cycles.
- Semiconductor Inspection:Sub-50 nanometer alignment tolerances required for lithography-adjacent metrology. Procurement concentrates in East Asian manufacturing zones with state-backed incentives redirecting volume toward certified local suppliers under China's MIIT mandates.
- Biological Research:Live-cell fluorescence microscopy demanding super-resolution imaging capabilities. Pharmaceutical R&D pipelines in Basel and Boston sustain this segment as a parallel demand pillar independent of semiconductor cycles.
- Metallurgical Analysis:Failure analysis systems for industrial quality assurance.
- Pharmaceutical Testing:US FDA-regulated optical instruments for clinical pathology applications.
- Forensic Examination:Ballistics and trace evidence microscopy operating on government procurement timelines.
Semiconductor inspection generates the highest unit margins. Biological research offers the most stable replacement demand.
Technology:
Volume concentration favors established optical glass and multi-coated architectures, while fluorite crystal and digital imaging integration are climbing the fastest.
- Fluorite Crystal:Engineered ultraviolet transmission profiles decomposing synthetic fused silica dominance in 193nm wafer inspection. Mining jurisdiction export restrictions on optical-grade fluorite concentrate create input volatility for lens assemblers.
- Digital Imaging:Computational imaging pipelines embedding software-calibrated performance guarantees alongside physical specifications, forcing manufacturers to guarantee resolution metrics through integrated sensor-lens systems.
- Optical Glass:Conventional crown and flint glass compositions for standard microscopy.
- Multi-Coated Lens:Anti-reflection layer stacks minimizing flare across ultraviolet to near-infrared spectra.
- Laser Scanning:Confocal and multiphoton integration requiring specialized objective designs.
Optical glass retains the largest installed base. Digital imaging integration is expanding most quickly.
End User:
Customer type determines contract structure: biotechnology firms negotiate volume commitments, while academic institutions unbundle objective procurement from full system purchases.
- Research Laboratories:National laboratory procurement integrating cryogenic objective designs with quantum sensing platforms. Ultra-low thermal expansion housing specifications are emerging for quantum dot metrology convergence.
- Quality Control Units:Cost-sensitive industrial settings where plan achromatic categories remain mature workhorses. India's pharmaceutical regulator expansion is creating demand for certified metallurgical failure analysis systems in Mumbai and Hyderabad clusters.
- Academic Institutions:German Max Planck Institute and French CNRS frameworks driving standalone lens replacement cycles.
- Biotechnology Firms:Commercial R&D operations with accelerated procurement timelines.
- Forensic Labs:Government-funded facilities with extended tender processes.
Academic institutions represent the deepest installed base. Biotechnology firms are scaling procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports precision optical components to semiconductor fabrication clusters in Taiwan and South Korea, while China redirects procurement toward domestic suppliers under state-backed substitution mandates.
Japan
Fluorite crystal supply chains and sub-2nm wafer inspection demand anchor objective lens production. METI-administered JIS B 7263 standards tighten dimensional tolerance specifications for strategic goods exports. Yokohama precision manufacturing zones re-qualify assembly lines to maintain foundry-adjacent metrology tool eligibility.
China
Domestic semiconductor fabs below 3nm nodes scale apochromatic and fluorite variant procurement. MIIT mandates redirect state-backed purchasing toward certified local suppliers, creating captive demand pools. Shanghai manufacturing clusters absorb compliance costs for GB standards on imported microscopy equipment.
United States
Pharmaceutical R&D pipelines in Boston demand super-resolution imaging capabilities for live-cell fluorescence microscopy. FDA regulations govern optical instruments used in clinical pathology and pharmaceutical testing. Basel-connected research networks sustain parallel demand independent of semiconductor cycles.
South Korea
Samsung Foundry qualifies fluorite crystal materials for high-volume defect review stations at 193nm wavelengths. National industrial policy supports precision equipment incentives for metrology tool development. Hsinchu-adjacent procurement patterns influence Korean foundry specification standards.
Germany
Max Planck Institute and CNRS-linked academic frameworks drive standalone lens replacement cycles independent of instrument refresh timelines. RoHS and REACH frameworks restrict hazardous substances in lens coatings and housing alloys. Precision assembly tolerances below 50 nanometers concentrate in lithography-adjacent metrology tool supply chains.
High-Power Objective Lens Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and geographic coverage. The vendor base separates into three concentration bands: precision multinationals with captive fluorite supply, mid-tier assemblers dependent on distributor networks, and regional specialists serving institutional procurement frameworks. Strategic archetypes include vertical integrators controlling crystal extraction through lens assembly, technology licensors monetizing design IP, and channel-focused houses unbundling objectives from full microscopy systems. Competitive moves concentrate on backward integration into fluorite mining jurisdictions and multi-jurisdiction certification investments to avoid stranded inventory.
Among Japan-based precision multinationals, Nikon Corporation and Olympus Corporation exemplify contrasting archetypes. Nikon anchors the fluorite-integrated tier through upstream control over optical-grade crystal supply chains. Olympus occupies a position within the academic-channel specialist tier, leveraging dedicated microscopy distribution in European and Japanese institutional markets. Carl Zeiss AG represents the precision-assembly archetype, with German GmbH structure signaling engineering-intensive positioning around sub-50 nanometer tolerance metrology.
| Leading Market Players |
|---|
| Olympus Corporation |
| Carl Zeiss AG |
| Leica Microsystems |
| Nikon Corporation |
| Canon Inc. |
| Edmund Optics |
| Mitutoyo Corporation |
| Thorlabs |
| Jenoptik AG |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Hsinchu foundries and Yokohama lens houses lock in fluorite crystal allocations while fixing unit pricing visibility across multi-year wafer inspection equipment refresh cycles. These contracts insulate premium apochromatic variants from spot-market volatility while exposing mid-tier assemblers to input cost pass-through.
Pricing Analysis
Five-wavelength correction specifications command three-generation pricing gaps against legacy three-wavelength designs and emerging seven-wavelength prototypes. Three-tier pricing structure across apochromatic, fluorite, and plan achromatic levels separates semiconductor fabs from academic and quality control buyers. Pricing pressure stems from China's MIIT domestic substitution mandates redirecting state volume toward certified local suppliers at compressed margins. Academic institutions exhibit highest price sensitivity due to unbundled procurement frameworks, while foundries absorb premiums for sub-50 nanometer alignment tolerances.
Supply Chain Analysis
Optical-grade fluorite crystal extraction in Mongolia, China, and Mexico concentrates feedstock access for lens assemblers. Assembly operations draw from fluorite mining jurisdictions, precision metrology equipment in Japan, and anti-reflection coating chemicals in Germany. Single-source vulnerability runs through Mongolian export permit regimes controlling raw crystal release volumes. Distribution runs through semiconductor equipment integrators for premium tiers and microscopy specialists for institutional segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zemax proficiency intersecting semiconductor process knowledge has collapsed to a narrow specialist cohort, extending development timelines and inflating compensation costs for mid-tier houses. This capability scarcity rewards early talent anchoring and captive training investments.
For Market Incumbents: Secure fluorite supply chain backward integration through mining jurisdiction partnerships or long-term offtake structures before export permit restrictions tighten. Anchor sub-50 nanometer metrology capabilities through captive cleanroom investments in Yokohama and Nagoya precision zones to defend against emerging Chinese lens houses capturing MIIT-mandated procurement. For New Entrants and Emerging Players: GB standards fast-track certification for Shanghai and Hsinchu foundry adjacency unlocks captive demand pools under China's domestic substitution directives. India's pharmaceutical regulator expansion in Mumbai and Hyderabad clusters offers the most penetrable white-space for metallurgical failure analysis systems. Lead with certified aftermarket objective replacement programs rather than full microscopy system competition. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists controlling fluorite extraction through lens assembly with demonstrated JIS B 7263 qualification. Long-term viability hinges on five-wavelength correction capability maturation for sub-2nm node inspection. Watch for Samsung Foundry and Taiwan Semiconductor Manufacturing qualification announcements for indigenous Chinese lens suppliers as inflection indicators of competitive displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorite Supply Anchoring | Mongolian mining concessions secure raw crystal access against export permit volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous GB, JIS, and FDA qualification eliminates stranded inventory in regional hubs. |
| Quantum Dot Metrology Partnership | Cryogenic objective integration with national laboratory procurement opens ultra-low thermal expansion specifications. |
| Academic Channel Unbundling | Standalone lens replacement programs in Max Planck and CNRS frameworks bypass full system refresh cycles. |
| Computational Imaging Integration | Software-calibrated performance guarantees alongside physical specifications defend against solid-state light source disruption. |
Research Methodology
A spread of perspectives from semiconductor metrology engineers, optical design specialists, foundry procurement directors, and microscopy channel managers converged on the working assumptions around fluorite crystal demand trajectories and certification timeline divergence. Secondary validation drew from METI precision equipment incentive disclosures, SAMR GB standards documentation, JIS B 7263 specification sheets, and SEC filings of listed precision multinationals. Bottom-up unit demand estimates from foundry capital expenditure patterns were triangulated against top-down market value reconstructions.
Segmentation dimensions modeled include correction grade tier, application end-use, technology type, and end-user category across the analysis window. CAGRs were derived from growth driver quantification and constraint boundary analysis. Forecast inputs incorporated wafer inspection equipment shipment patterns, pharmaceutical R&D pipeline microscopy spend, and national laboratory quantum sensing platform procurement timelines.
Underlying assumptions cover sustained sub-2nm node expansion, stable Mongolian fluorite export permit regimes, and continued MIIT domestic substitution enforcement, with deviation risk concentrated in multi-jurisdiction certification lag and REACH coating reformulation stranding. Practitioners should keep alternative scenarios live as Chinese indigenous lens supplier qualification timelines and Japanese METI incentive recalibrations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
2D and 3D Machine Vision Systems Market
Imaging
Gel Imaging Documentation Market
Imaging
Industrial Camera Market
Imaging
Europe CT Market
Imaging
Hybrid Imaging Market
Imaging
Handheld Imaging Devices Market
Imaging
Machine Vision Camera Market
Imaging
Wide Field Imaging Devices Market
Imaging
Global Image Sensors Market
Imaging
Infrared Imaging Market
Imaging
Camcorder Market
Imaging
SWIR Camera Market
Imaging
Widefield Imaging Systems Market
Imaging
Mobile Imaging Market
Imaging
Global Trail Camera Market
Imaging
Video Processing Solutions Market