
 Japan Lithium Niobate Modulator Market | 2026-2036
Japan Lithium Niobate Modulator Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Lithium Niobate Modulator Market Insights
Domestic procurement channels for electro-optic components is tilting toward qualified local vendors as carriers prioritize supply security. Fujitsu Optical Components Ltd leverages its captive optical device fabrication to sustain long-term contracts with NTT and regional carriers. Sumitomo Osaka Cement anchors the upstream lithium niobate crystal supply through its advanced ceramic material platforms. Oxide Corporation competes on specialized bulk modulator designs for defense and research buyers.
Lithium niobate modulators are electro-optic devices fabricated from LiNbO3 crystals, typically operating at wavelengths near 1550 nm with half-wave voltages below 5 V, converting electrical signals into optical phase or intensity modulation for fiber optic communication systems. Optical modulators dominate volume shipments to telecommunications and data center end users where coherent DSP interfaces require high-bandwidth external modulation. Waveguide modulators represent the fastest-expanding technology segment as thin-film lithium niobate on insulator processes enable compact, low-drive-voltage devices. Integrated modulators command premium positioning by combining multiple optical functions on single chips for next-generation transceivers.
METI's semiconductor and digital industry strategies, alongside JIS standards for optical communication components, shape domestic qualification requirements and procurement preferences for lithium niobate devices. PMDA oversight of medical laser systems and NICT's spectrum management rules for optical wireless links create adjacent compliance pathways that influence component specifications. Stakeholders must monitor thin-film lithium niobate process yields and METI subsidy eligibility criteria to calibrate capacity commitments against evolving domestic content thresholds.
Market Dynamics
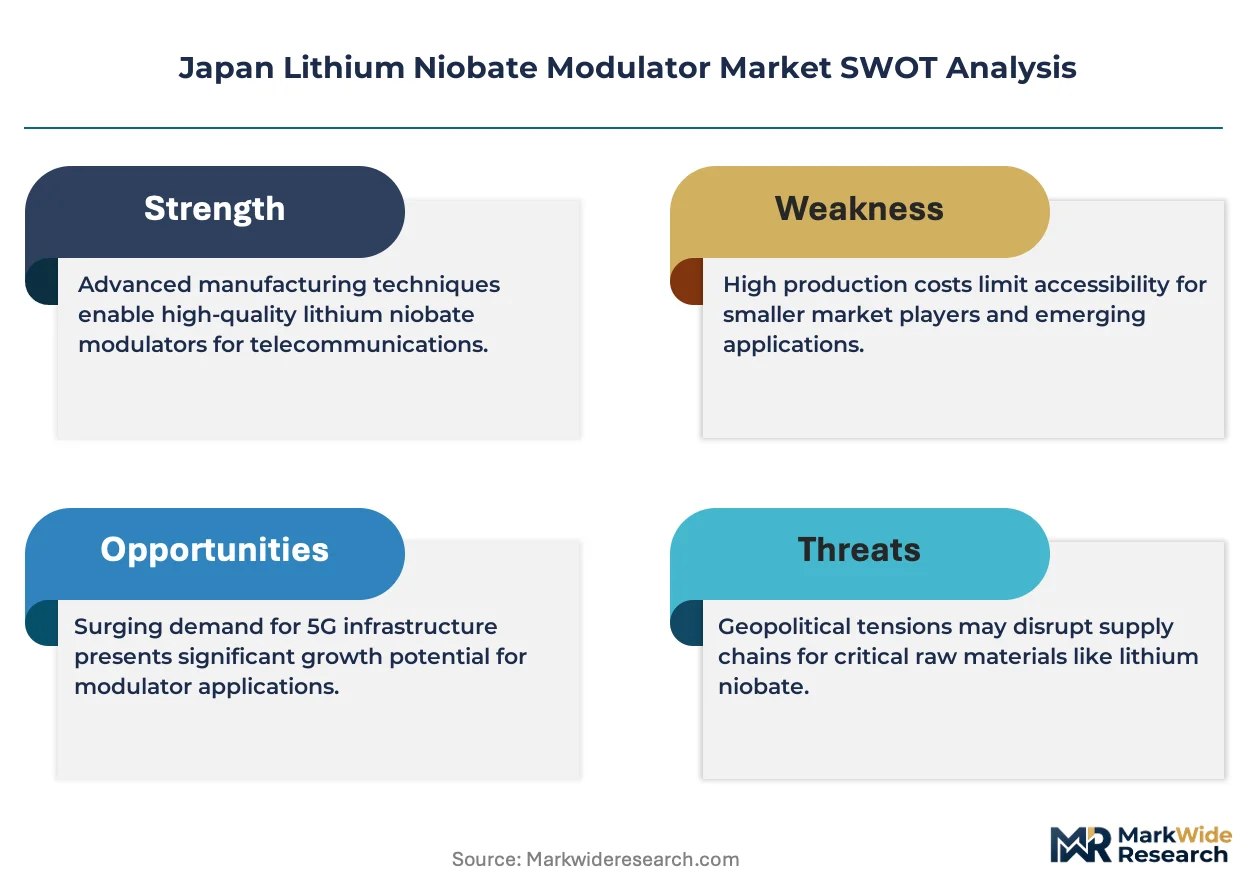
Thin-film lithium niobate on insulator processes are collapsing device footprints and drive voltages, forcing incumbent bulk-crystal suppliers to retool fabrication lines or cede coherent optical transceiver sockets to foundry-integrated competitors.
Growth Catalysts
- Coherent transmission expansion:NTT and regional carriers are upgrading fiber backbone infrastructure to support 800G and 1.6T wavelengths, requiring external modulators with bandwidth exceeding 100 GHz.
- METI supply chain localization:Japan's Ministry of Economy, Trade and Industry is directing subsidy eligibility toward domestic photonics component sourcing, creating procurement preference for qualified local vendors.
- Hyperscale data center buildouts:Greater Tokyo metropolitan clusters are anchoring procurement volumes as cloud operators deploy AI training infrastructure requiring low-latency optical interconnects.
Market Restraints
- Upstream crystal concentration:High-purity lithium niobate substrate supply concentrates among a handful of advanced ceramic specialists, creating single-source vulnerability for modulator fabricators.
- Thin-film yield volatility:TFLN wafer processing exhibits defect rates that elevate unit economics above bulk modulator alternatives, constraining price-competitive positioning in cost-sensitive segments.
- Silicon photonics substitution:Integrated silicon photonic modulators are capturing volume in intra-data center links below 10 km, squeezing lithium niobate addressable market at the edge.
Strategic Opportunities
- Defense and aerospace applications:Specialized bulk modulator designs for radar and electronic warfare systems offer premium pricing outside telecommunications procurement cycles.
- Medical laser systems:PMDA oversight of surgical and diagnostic laser equipment creates adjacent compliance pathways for electro-optic components with reliability certifications.
- Thin-film foundry services:Technology convergence between CMOS fabrication and TFLN processing enables fabless modulator designers to access advanced node capabilities without captive wafer investments.
Industry Challenges
- Packaging and fiber coupling expertise:TFLN devices require sub-micron alignment tolerances and hermetic sealing that strain Japan's legacy optical component assembly workforce.
- JIS certification timelines:Standard qualification protocols for optical communication components extend development cycles, delaying revenue recognition for new modulator variants.
- Legacy system integration friction:Coherent DSP interfaces demand precise impedance matching and thermal management when retrofitting existing transceiver platforms.
Report Scope
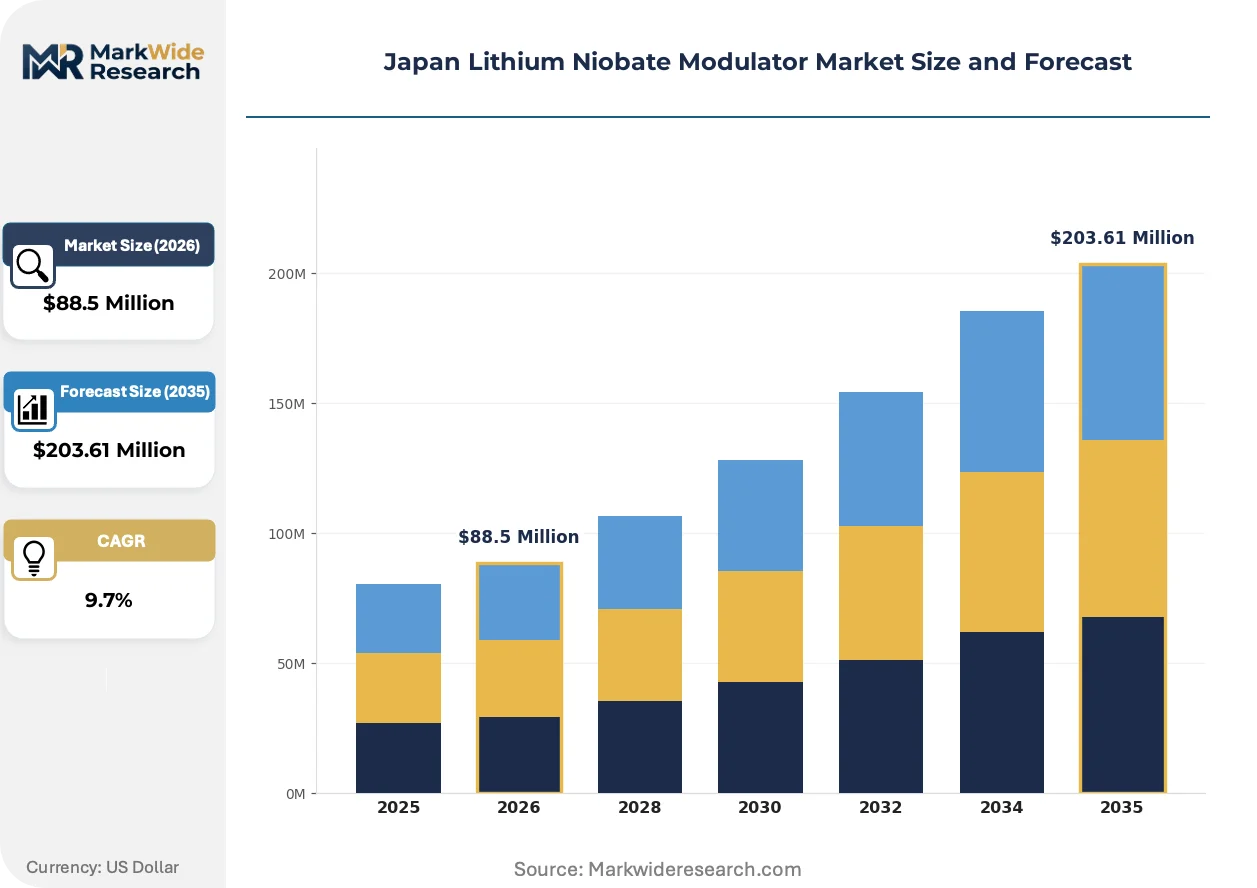
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Lithium Niobate Modulator Market |
| Market Size in 2026 | $88.5 Million |
| Market Size in 2035 | $203.61 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Modulators, Waveguide Modulators, Bulk Modulators, Integrated Modulators End User: Telecommunications, Data Centers, Military, Research Institutions Technology: Electro-Optic, Acousto-Optic, Hybrid, All-Optical Application: Signal Processing, Data Transmission, Light Modulation, Sensing |
| Companies Covered | Fujitsu Optical Components Ltd, Shin-Etsu Chemical, Sumitomo Osaka Cement, NGK Insulators, Oxide Corporation, Covalent Materials Corporation, Fujifilm, iXblue Group, THORLABS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Lithium Niobate Modulator Market Trends and Innovations
Process innovation and procurement model evolution are compressing traditional supplier hierarchies while regulatory mandates accelerate domestic qualification requirements for critical photonics components.
Thin-film lithium niobate on insulator technology is collapsing the size and power consumption tradeoffs that previously favored bulk crystal modulators. Telecommunications equipment manufacturers are adopting TFLN devices for 800G coherent transceivers at accelerating pace. This technology is collapsing the addressable gap between performance-optimized lithium niobate and cost-optimized silicon photonics, enabling lithium niobate to reclaim sockets in intermediate-reach applications.
METI's semiconductor and digital industry strategies are tightening domestic content thresholds for subsidy-eligible procurement. Component vendors must demonstrate in-country fabrication or advanced packaging to qualify for public infrastructure contracts. Optical modulator suppliers are responding by localizing thin-film processing and backend assembly within Japan's designated semiconductor clusters.
Carrier procurement patterns are consolidating vendor relationships around qualified local sources with demonstrated supply security. Long-term framework agreements are displacing spot-market purchasing for coherent optical components. This behavioral shift is most visible in NTT's central office and regional carrier procurement, where multi-year contracts now dominate high-bandwidth modulator acquisition.
Japan Lithium Niobate Modulator Market Segmentation
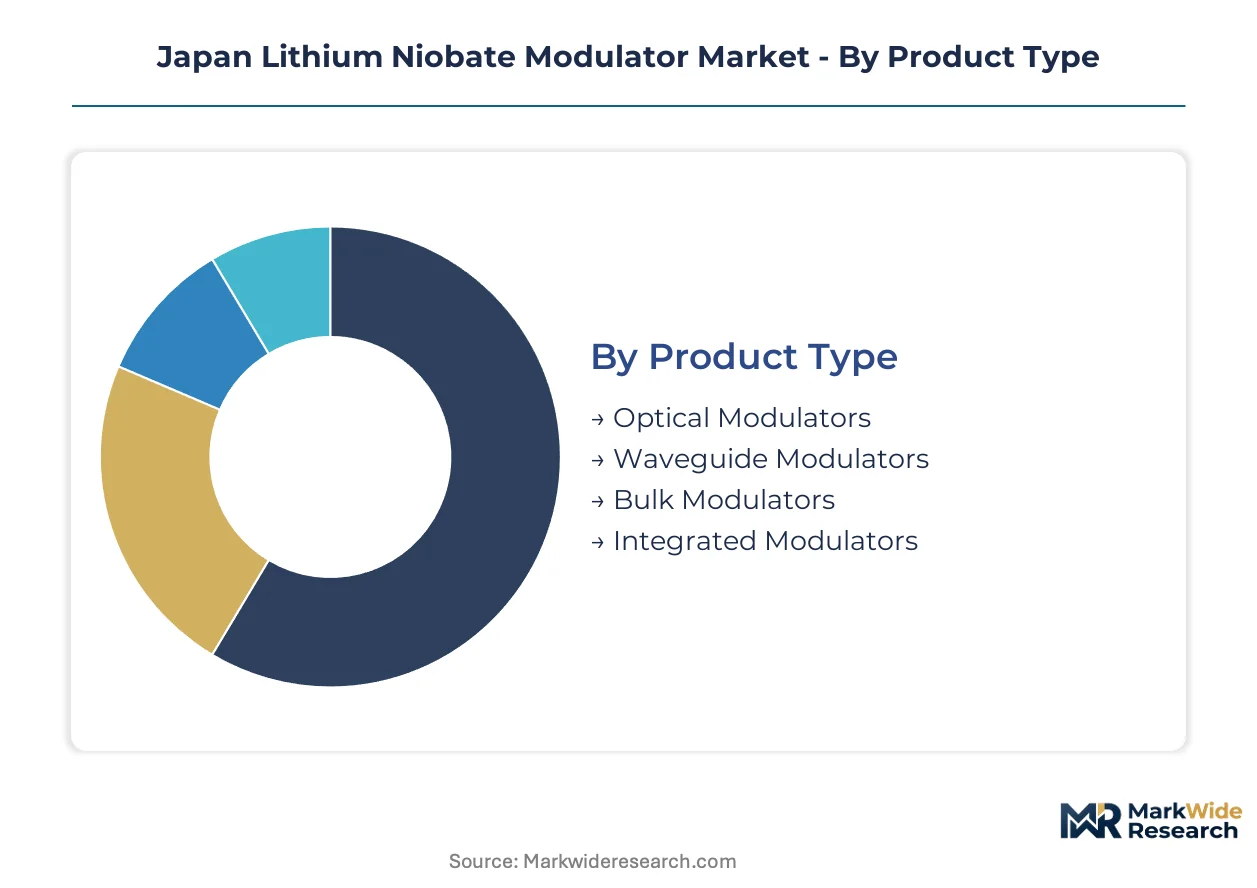
Japan's lithium niobate modulator market fragments across four critical dimensions that determine procurement priorities, qualification requirements, and technology roadmaps. Each segmentation layer reveals distinct competitive dynamics shaped by METI localization mandates and carrier infrastructure deployment cycles.
Product Type:
Use-case spectrum spans high-volume coherent transmission to specialized defense applications, with fabrication complexity and unit economics varying dramatically across architectures.
- Optical Modulators:These devices convert electrical signals into optical phase or intensity modulation at 1550 nm wavelengths, typically featuring half-wave voltages below 5 V. NTT and regional carriers anchor procurement volumes in Greater Tokyo as 800G coherent deployments accelerate across fiber backbone infrastructure.
- Waveguide Modulators:Thin-film lithium niobate on insulator processes enable compact footprints and reduced drive voltages. Hyperscale data center clusters in the Greater Tokyo metropolitan corridor are driving fastest adoption as cloud operators deploy AI training infrastructure requiring low-latency optical interconnects.
- Bulk Modulators:Conventional crystal-based designs serve legacy coherent systems and specialized applications.
- Integrated Modulators:Single-chip solutions combining multiple optical functions command premium positioning in next-generation transceivers.
The dominant share belongs to Optical Modulators, while Waveguide Modulators is closing the gap fastest.
End User:
Customer concentration tilts toward infrastructure owners with multi-year procurement frameworks and stringent domestic qualification requirements.
- Telecommunications:NTT and regional carriers deploy external modulators for 800G and 1.6T coherent transmission upgrades. METI subsidy eligibility criteria favor qualified local vendors, consolidating procurement around domestic fabricators with demonstrated supply security.
- Data Centers:Hyperscale operators in Greater Tokyo metropolitan clusters require high-bandwidth modulation for AI training infrastructure. Low-latency optical interconnect specifications favor thin-film devices with reduced power consumption and compact form factors.
- Military:Defense applications demand specialized bulk modulator designs with reliability certifications outside commercial procurement cycles.
- Research Institutions:Academic and national laboratory buyers prioritize experimental performance specifications over volume economics.
Telecommunications commands the largest procurement volumes, though Data Centers exhibits the steepest expansion trajectory.
Technology:
Process maturity and integration compatibility determine competitive positioning against silicon photonics alternatives.
- Electro-Optic:Pockels effect-based modulation in lithium niobate crystals delivers bandwidth exceeding 100 GHz for coherent DSP interfaces. This technology anchors volume shipments to telecommunications carriers upgrading fiber backbone infrastructure.
- Acousto-Optic:Ultrasonic wave interaction with optical signals serves frequency-shifting and deflection applications. Specialized defense and sensing applications in Japan's research ecosystem sustain niche demand despite limited scalability.
- Hybrid:Combined electro-optic and photonic integration approaches address intermediate-reach connectivity requirements.
- All-Optical:Pure optical signal processing without electrical conversion remains experimental for telecommunications deployment.
Electro-Optic processes hold established production scale, while Hybrid architectures are gaining share fastest in data center interconnect applications.
Application:
Functional requirements diverge between high-speed communication infrastructure and precision measurement systems.
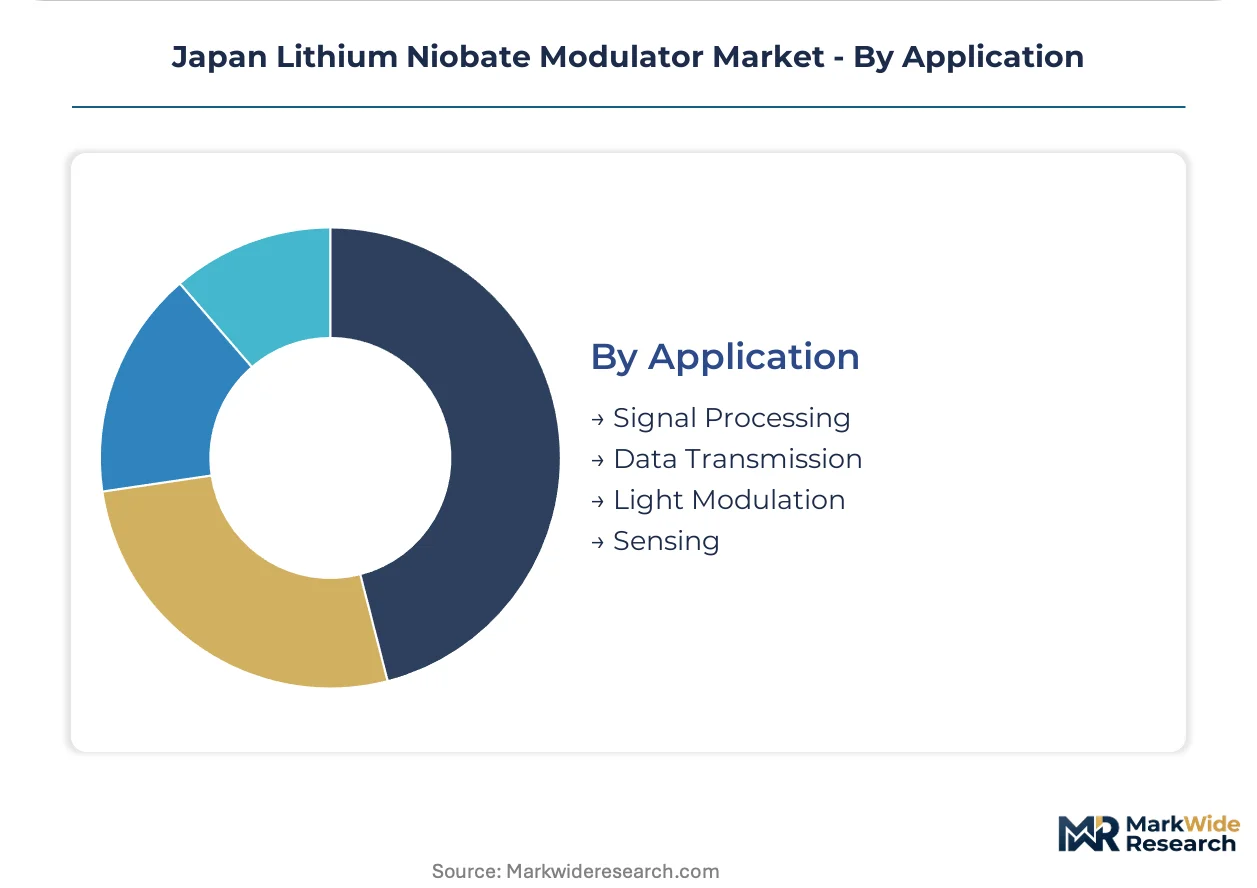
- Signal Processing:Real-time manipulation of optical carrier signals for coherent transmission systems. NTT's central offices and regional carrier facilities in Greater Tokyo anchor procurement volumes as 800G wavelength deployments accelerate.
- Data Transmission:Long-haul and metro fiber links requiring external modulation for dispersion management. Hyperscale data center clusters drive specification evolution toward lower drive voltages and reduced power consumption.
- Light Modulation:Intensity and phase control for industrial and medical laser systems under PMDA oversight.
- Sensing:Interferometric and spectroscopic applications in research and defense environments.
Data Transmission captures the dominant procurement volume, while Signal Processing is expanding most quickly through coherent transceiver upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's fiber optic backbone infrastructure, anchored by NTT's nationwide transmission network, underwrites the country's dominance in coherent optical component demand. The Greater Tokyo metropolitan corridor concentrates procurement volumes for lithium niobate modulators as hyperscale data center clusters and carrier central offices drive specification evolution.
Kanto/Tokyo
NTT's central offices and regional carrier facilities anchor procurement volumes for 800G coherent transmission upgrades. METI's semiconductor subsidy programs direct public infrastructure contracts toward qualified domestic vendors with demonstrated supply security. The Yokohama-Kawasaki industrial corridor hosts advanced packaging operations serving telecommunications equipment manufacturers.
Kansai/Osaka
Specialized ceramic material platforms supply high-purity lithium niobate substrates to downstream modulator fabricators. JIS standards for optical communication components shape qualification timelines for components entering carrier procurement frameworks. The Osaka Science and Technology Center cluster supports research institutions demanding experimental performance specifications.
Chubu/Nagoya
Automotive and industrial laser applications sustain niche demand for bulk modulator designs outside telecommunications procurement cycles. PMDA oversight of medical laser systems creates adjacent compliance pathways for electro-optic component suppliers. The Nagoya manufacturing belt integrates photonics assembly into precision equipment supply chains.
Kyushu
Defense and aerospace applications drive specialized procurement for radar and electronic warfare systems requiring reliability certifications. National laboratory buyers in the region prioritize performance specifications over volume economics for research-grade modulators. The Kitakyushu industrial zone hosts legacy optical component assembly operations.
Tohoku
Semiconductor material suppliers anchor upstream lithium niobate crystal production for the domestic modulator ecosystem. METI's push for supply chain resilience incentivizes geographic diversification of fabrication capacity beyond the Tokyo-Osaka axis. The Sendai technology corridor hosts thin-film processing research initiatives.
Japan Lithium Niobate Modulator Market Competitive Landscape
On the supply side, the industry is consolidating around qualified domestic vendors with captive optical device fabrication and advanced ceramic material platforms. The vendor base stratifies across three tiers: integrated telecommunications equipment suppliers with captive component operations, specialized electro-optic component fabricators, and upstream crystal growth specialists. Dominant competitive moves include backward integration into substrate supply and strategic partnerships with thin-film foundry services.
Among Japan-based fabricators, Fujitsu Optical Components Ltd and Sumitomo Osaka Cement exemplify the integrated-tier archetype combining downstream modulation expertise with upstream material control. Oxide Corporation occupies a position within the specialization tier focused on defense and research market segments. These three entities represent the competitive core around which carrier procurement frameworks and METI subsidy eligibility criteria are calibrating.
| Leading Market Players |
|---|
| Fujitsu Optical Components Ltd |
| Shin-Etsu Chemical |
| Sumitomo Osaka Cement |
| NGK Insulators |
| Oxide Corporation |
| Covalent Materials Corporation |
| Fujifilm |
| iXblue Group |
| THORLABS |
| Others |
Pricing and Supply Chain Analysis
The Yokohama-Kawasaki freight corridor's logistics cost dynamics amplify pricing power for Sumitomo Osaka Cement and other upstream crystal suppliers while forcing downstream modulator fabricators into volume-discount tiering structures that separate NTT framework contracts from spot-market transactions.
Pricing Analysis
Volume-discount tiering structures separate premium thin-film lithium niobate modulators for 800G coherent transceivers from standard bulk-crystal designs and economy-grade legacy components. Price differentiation hinges on JIS certification grade and METI subsidy eligibility, with certified domestic fabricators commanding substantial premiums over unqualified imports. Cost compression in the standard tier is intensifying because silicon photonics substitutes are squeezing lithium niobate sockets in intra-data center links below 10 km. Hyperscale data center operators exhibit the highest price sensitivity due to AI training infrastructure capex pressures, while defense procurement cycles show the least sensitivity to unit economics.
Supply Chain Analysis
Tariff exposure between Japan and China for rare-earth processing equipment dominates supply chain risk calculations for domestic modulator fabricators. High-purity lithium niobate substrate production concentrates in Japan, China, and the United States, with Japanese fabricators drawing from domestic crystal growth specialists and selective Chinese chemical processing partners. Raw material dependencies include lithium carbonate feedstock, niobium pentoxide, and specialized ceramic crucibles for Czochralski crystal pulling. Single-source vulnerability persists in thin-film lithium niobate on insulator wafer supply where foundry capacity concentrates among a handful of qualified vendors. Distribution runs through direct long-term framework agreements with NTT and regional carriers, supplemented by specialized distributors serving defense and research segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Japan lithium niobate modulator market sits at a platform-economics inflection where thin-film lithium niobate on insulator process standardization is collapsing the interoperability gap between discrete component suppliers and coherent transceiver module vendors.
For Market Incumbents: Insulate captive supply positions by deepening backward integration into lithium niobate crystal growth and securing dedicated thin-film foundry capacity before METI subsidy windows tighten domestic content thresholds further. Prioritize JIS certification investments for 1.6T coherent interface variants to defend framework contract renewals against emerging fabless competitors leveraging CMOS-compatible TFLN processes. For New Entrants and Emerging Players: Kyushu's defense and aerospace procurement channels offer the most penetrable entry vector given premium pricing tolerance and limited incumbent specialization outside telecommunications cycles. Target radar and electronic warfare system integrators with reliability-certified bulk modulator designs before attempting NTT qualification pathways. Pursue thin-film foundry partnerships rather than captive wafer investments to compress capital requirements and accelerate time-to-revenue. For Investors and Strategic Acquirers: Specialized electro-optic component fabricators with demonstrated METI qualification and thin-film process partnerships represent the optimal acquisition target archetype for exposure to coherent transmission upgrade cycles. Frame long-term viability around the 5-10 year displacement timeline for silicon photonics in intermediate-reach applications where lithium niobate bandwidth advantages persist. Monitor thin-film lithium niobate wafer yield trajectories at domestic foundries as the critical inflection signal for unit economics convergence against bulk-crystal alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Film Foundry Partnership | Enables fabless modulator designers to access advanced node capabilities without captive wafer investments. |
| JIS Certification Acceleration | Compresses qualification timelines for optical communication components entering NTT procurement frameworks. |
| Backward Integration into Crystal Supply | Secures lithium niobate substrate access against single-source vulnerability in upstream ceramic material platforms. |
| Defense Segment Diversification | Captures premium pricing outside telecommunications procurement cycles through radar and electronic warfare applications. |
| Hyperscale Data Center Channel Development | Positions thin-film devices for AI training infrastructure procurement in Greater Tokyo metropolitan clusters. |
Research Methodology
A standing panel of coherent transmission system architects, optical device procurement managers at NTT and regional carriers, thin-film process engineers, and METI industrial strategy officers provided ongoing calibration across primary interview cycles. Secondary validation drew from NICT spectrum management filings, JIS standards documentation, METI subsidy program disclosures, and customs trade data for electro-optic component imports. Bottom-up demand modeling from carrier capex disclosures and hyperscaler data center expansion announcements was triangulated against top-down market sizing from semiconductor and photonics industry associations.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product architecture, end-user vertical, modulation technology, and application function. CAGRs were derived from installed base replacement cycles for 400G-to-800G coherent upgrades and thin-film lithium niobate penetration assumptions in data center interconnects. Industry-specific forecast inputs included NTT's disclosed fiber backbone modernization timelines and METI's evolving domestic content thresholds for subsidy eligibility.
Practitioners should monitor thin-film lithium niobate wafer yield improvements, METI subsidy program revisions, and silicon photonics bandwidth advancements for early signals requiring forecast recalibration. Forecasts reflect documented assumptions about carrier deployment cadence and foundry capacity expansion commitments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Fiber-Optic Attenuator Market
Optical Components
CMP Polishing Machine Market
Optical Components
Photomask Pellicle Market
Optical Components
Pancake Optical Module Market
Optical Components
Europe Tunable Laser Market
Optical Components
Optical Film Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Optical Encoder Market
Optical Components
Liquid Lenses Market
Optical Components
Optical Isolator Market
Optical Components
Prism Coupler Market
Optical Components
VCSEL for Data Communication Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Optical Image Stabilization (OIS) Actuators Market