
 Canada Electric Space Heater Market | 2026-2036
Canada Electric Space Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Electric Space Heater Market Insights
Ontario-based manufacturing capacity is rebalancing toward higher-efficiency electric heating platforms. Honeywell leverages its digital thermostat integration to anchor premium positioning across Canadian retail channels. Brant Radiant Heaters Limited sustains industrial-grade specialization with infrared and radiant product lines for commercial warehouses. Ouellet Canada dominates the baseboard and construction heater segment through deep distribution in Quebec and Ontario electrical supply chains.
An electric space heater converts electrical energy into thermal output through resistive heating elements, ceramic plates, or oil-filled thermal mass, typically delivering between 500W and 2000W for zone-specific temperature control in residential, commercial, and industrial environments. Convection heaters and oil-filled units remain the volume backbone in Canadian residential applications due to silent operation and compatibility with standard 120V/240V circuits, while smart control technology represents the fastest-expanding margin pool as Wi-Fi-enabled scheduling and utility demand-response integration gain traction among efficiency-conscious households.
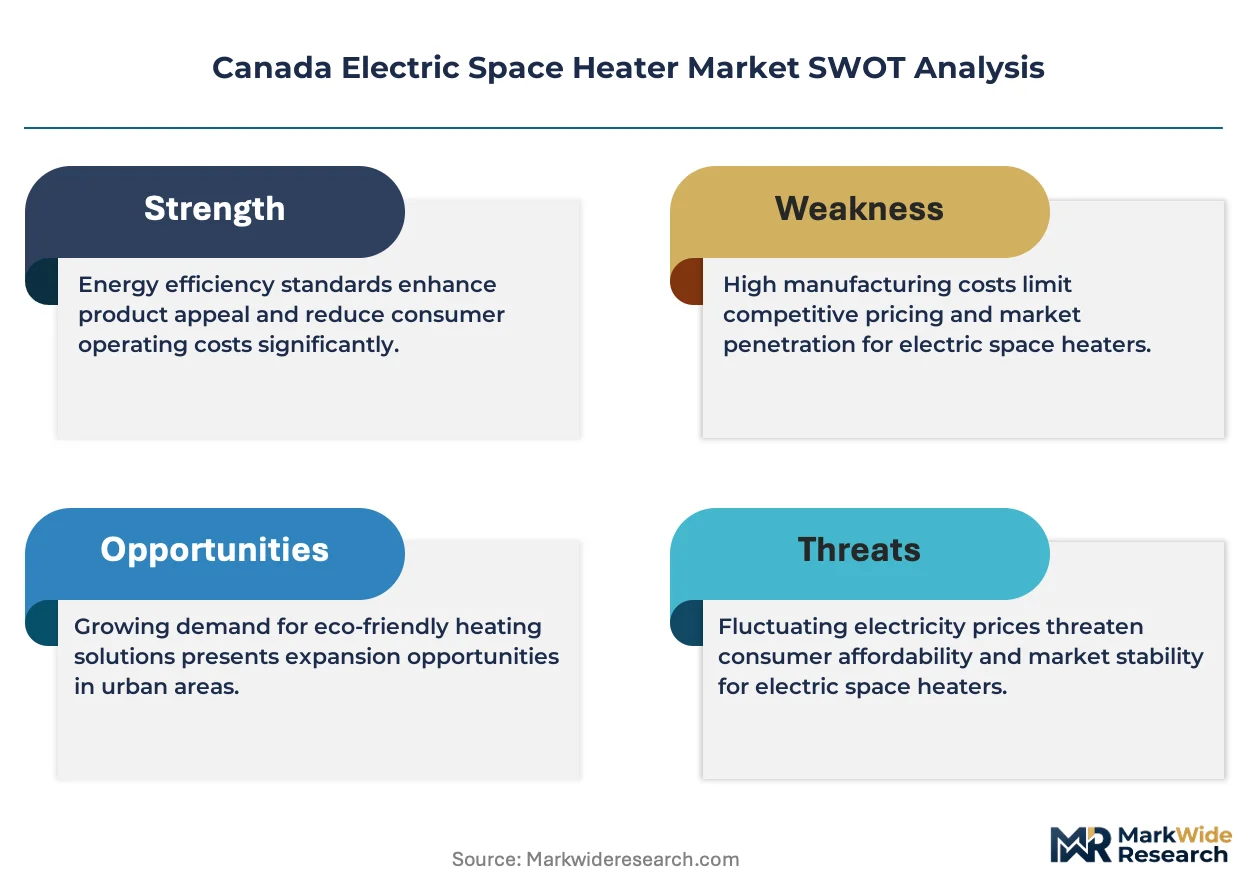
Health Canada's Radiation Emitting Devices Act and the Canadian Standards Association CSA C22.2 No. 46 standard govern product safety certification and tip-over protection requirements for all units sold domestically. Natural Resources Canada administers EnerGuide labeling and minimum energy performance standards that progressively disqualify lower-efficiency models from federal incentive programs. Stakeholders must monitor provincial carbon pricing trajectories and building code electrification mandates, as these policy levers will determine whether electric resistance heating retains cost competitiveness against heat pump alternatives in new construction and deep retrofit decisions.
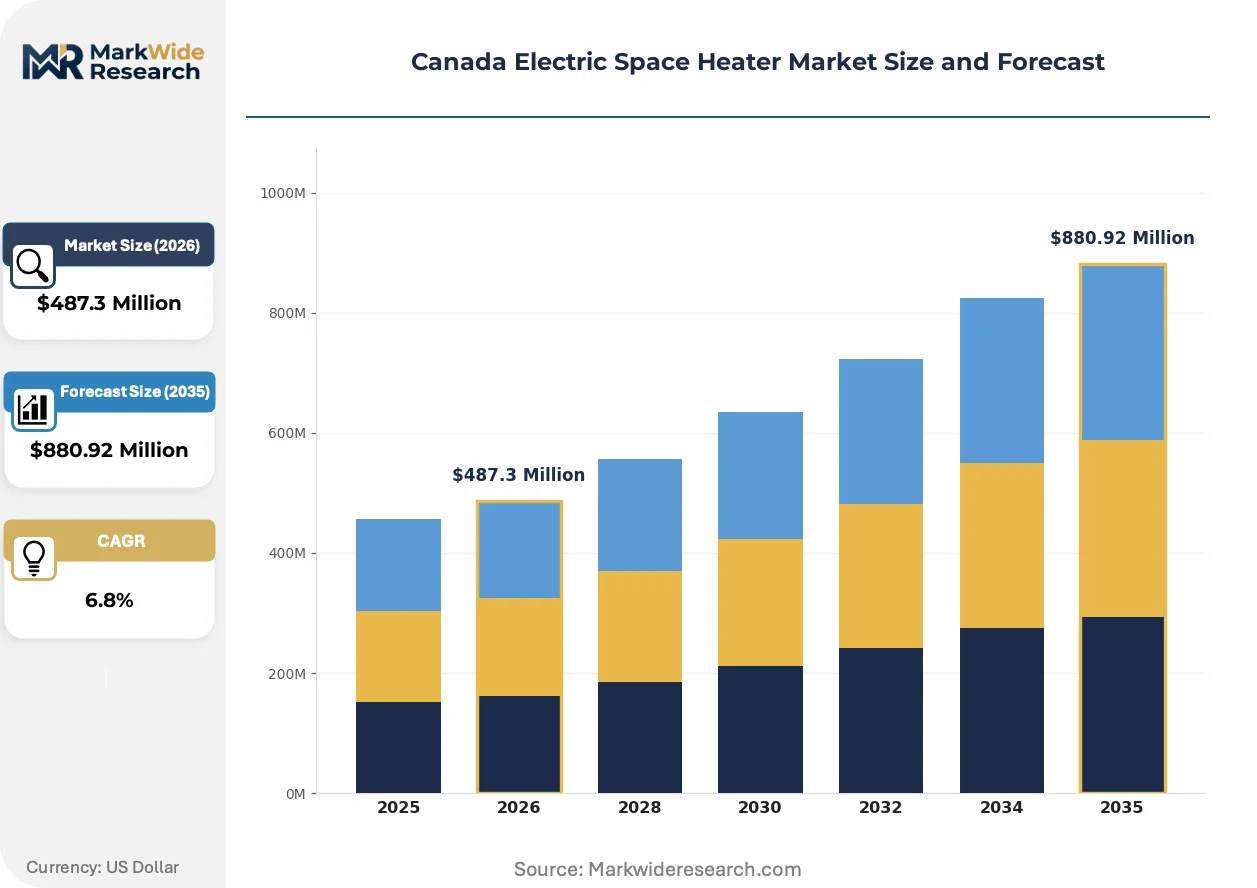
Market Dynamics
The Canada Electric Space Heater Market is being fundamentally restructured by provincial building code electrification mandates that progressively disqualify electric resistance heating from new construction eligibility, forcing manufacturers to pivot toward smart-enabled, high-efficiency platforms that can integrate with utility demand-response programs.
Growth Catalysts
- Natural Resources Canada EnerGuide tightening:Minimum energy performance standards are accelerating replacement cycles as older models lose federal incentive eligibility, pulling forward demand in Ontario and Quebec retrofit markets.
- Atlantic Canada housing stock age:Pre-1990s residential structures in Nova Scotia and New Brunswick require supplemental heating solutions that electric space heaters address without ductwork modifications.
- Wi-Fi thermostat convergence:Integration with smart home ecosystems is expanding addressable market into tech-forward urban households seeking zone-level climate control.
Market Restraints
- Heat pump substitution economics:Cold-climate air-source heat pumps achieving coefficient of performance above 2.0 at minus 25°C are displacing electric resistance in deep retrofit decisions across Prairie provinces.
- Copper and aluminum input volatility:Heating element and chassis manufacturing faces margin compression from base metal price swings that resist full pass-through in mass-market retail channels.
- CSA C22.2 No. 46 certification timelines:Tip-over protection and thermal cutoff testing protocols extend product launch cycles by four to six months for new entrants.
Strategic Opportunities
- Manitoba and Saskatchewan grid decarbonization:Provincial utilities expanding hydroelectric capacity create marketing white space for carbon-neutral positioning of electric heating against natural gas alternatives.
- Commercial warehouse radiant specialization:Infrared platforms for spot heating in logistics facilities remain underpenetrated relative to convection-dominated residential saturation.
- Utility demand-response program integration:Alberta's capacity market reforms and Ontario's peak saver initiatives create regulatory tailwinds for grid-interactive heater deployments.
Industry Challenges
- Firmware and embedded systems talent scarcity:Smart control development requires software engineering capabilities that traditional heating equipment manufacturers lack in-house.
- Legacy electrical infrastructure compatibility:Aging 60-amp service panels in rural Quebec and Atlantic Canada limit 240V high-wattage unit penetration without costly electrical upgrades.
- Cross-provincial efficiency standard fragmentation:British Columbia's step code and Quebec's Novoclimat create divergent product specification requirements that complicate national SKU strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Electric Space Heater Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection Heater, Radiant Heater, Fan Heater, Oil-Filled Heater Power Rating: 500W, 1000W, 1500W, 2000W Control Technology: Manual Control, Digital Control, Smart Control, Remote Control End User: Residential, Commercial, Industrial, Construction |
| Companies Covered | Dyson, Honeywell, Black + Decker, Brant Radiant Heaters Limited, Ouellet Canada, Kelray Heating, Envi Heater, ICON, AirNmore, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Electric Space Heater Market Trends and Innovations
Canadian electric space heater innovation is pivoting from thermal output efficiency toward system-level integration, with digital connectivity and grid-interactive capabilities now determining competitive positioning rather than wattage ratings alone.
Machine learning-enabled predictive heating is automating occupancy-based temperature modulation in premium residential units. Multi-unit residential building operators in Toronto and Vancouver are piloting these systems to reduce peak demand charges. The technology is automating load-shifting responses that were previously manually managed, compressing the operational advantage of programmable thermostats into embedded heater intelligence.
Natural Resources Canada's proposed 2025 amendments to EnerGuide minimum energy performance standards will disqualify single-setting resistive models from federal Greener Homes grant eligibility. This regulatory tightening is accelerating R&D investment in ceramic and infrared element efficiency. The Prairie provinces face the steepest compliance burden due to higher heating-degree-day requirements that strain efficiency thresholds.
Direct-to-contractor distribution through electrical supply houses is displacing big-box retail as the dominant channel for commercial and new construction specification. Master electricians in Ontario and Quebec increasingly source through dedicated HVAC-R wholesalers that bundle heaters with control systems. This channel migration is most visible in Quebec's construction heater segment, where contractor loyalty programs and technical support services override price-based purchasing.
Canada Electric Space Heater Market Segmentation
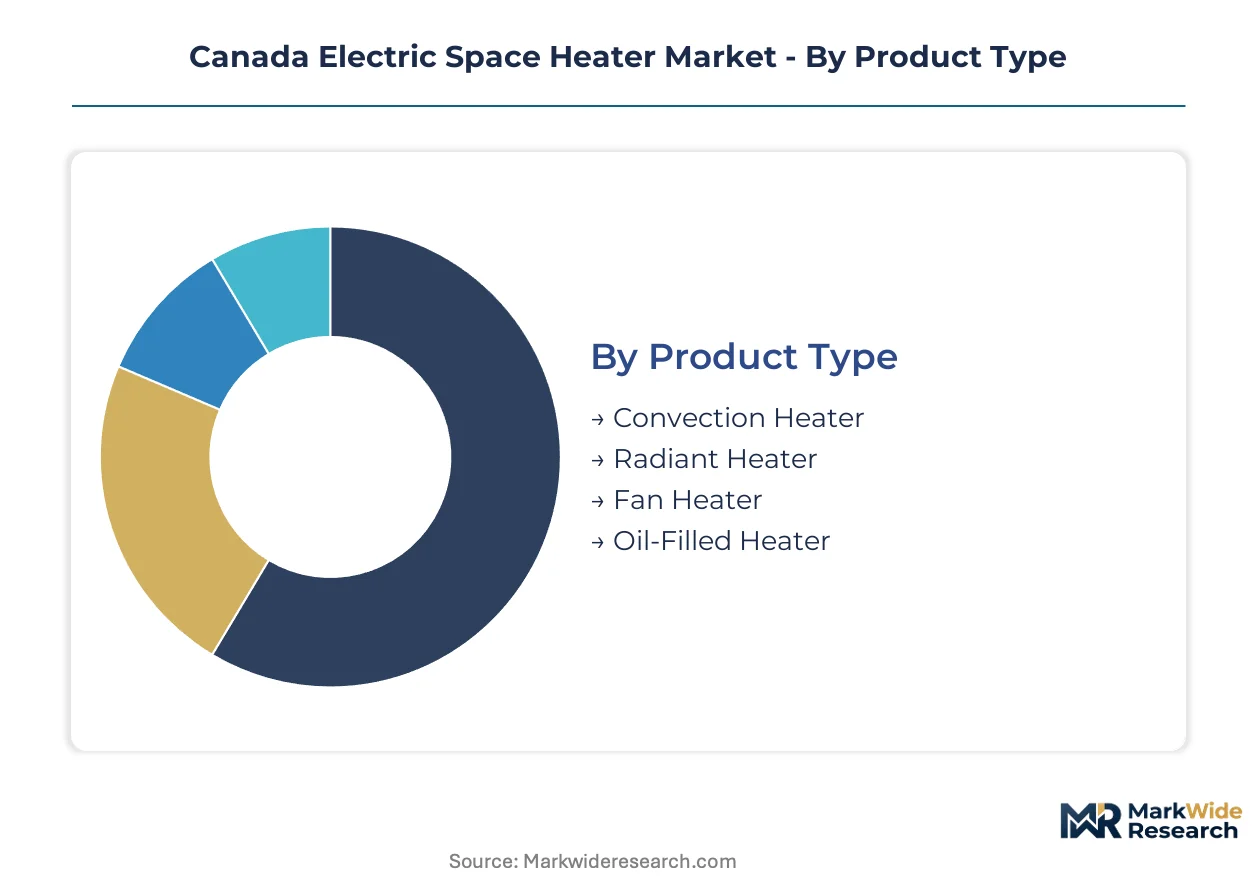
Canada's electric space heater market segments along four functional dimensions that determine integration depth with building systems and utility programs. Product type and control technology classifications reveal which units operate as standalone appliances versus embedded climate infrastructure.
Product Type:
Standalone convection and oil-filled units dominate residential retrofit applications, while radiant systems embed more deeply into commercial building automation.
- Convection Heater:Ceramic and coil-based elements heat air through natural circulation without forced airflow. Silent operation drives demand in Ontario and Quebec bedroom and basement retrofits where noise sensitivity limits fan-based alternatives.
- Oil-Filled Heater:Diathermic oil thermal mass retains heat after power cycling, reducing peak draw. Atlantic Canada's pre-1990s housing stock with limited electrical panel capacity favors these lower-wattage thermal storage units.
- Radiant Heater:Infrared quartz or carbon elements deliver directional spot heating. Commercial warehouses in Alberta and Saskatchewan logistics corridors specify these for loading dock zones.
- Fan Heater:Forced-air ceramic elements provide rapid space conditioning. Construction sites across Manitoba deploy these for temporary enclosure heating during winter building phases.
Convection heaters lead volumes today; smart-enabled radiant systems are gaining share fastest.
Power Rating:
Wattage tiers stratify by circuit capacity constraints and heating load requirements, with 120V/15A compatibility determining addressable household penetration.
- 1500W:The standard residential ceiling for 120V circuits without dedicated wiring. Quebec's Novoclimat program and Ontario's peak saver initiatives target this segment for demand-response enrollment.
- 2000W:Requires 240V or 20A dedicated circuits, limiting deployment to newer construction or electrical upgrades. British Columbia's step code electrification mandates in multi-unit residential buildings specify these for primary heating zones.
- 1000W:Compact units for supplemental zone heating in apartments and secondary rooms. Urban Toronto and Vancouver condominium markets favor these for space-constrained installations.
- 500W:Personal-scale units for desk-side or bathroom spot heating. Lowest absolute energy consumption appeals to Saskatchewan and Manitoba households managing winter electricity bills.
1500W units dominate unit shipments; 2000W models climb the fastest as new construction electrical standards tighten.
Control Technology:
Control sophistication determines utility program eligibility and margin capture, separating commodity appliances from grid-interactive assets.
- Smart Control:Wi-Fi-enabled scheduling, geofencing, and utility API integration. Alberta's capacity market reforms and Ontario's Independent Electricity System Operator peak events create regulatory pull for these enrollable devices.
- Digital Control:Programmable thermostats with LCD interfaces but no connectivity. Mid-market positioning in Prairie provinces where broadband infrastructure limits smart home penetration.
- Manual Control:Rotary dials or rocker switches with no automation. Baseboard replacements in rural Quebec and Atlantic Canada where price sensitivity dominates and electrical contractor labor is scarce.
- Remote Control:Infrared or RF handheld units for basic distance operation. Warehouse and industrial applications in Ontario manufacturing corridors where operator mobility matters.
Manual control retains volume leadership; smart control expands most quickly as utility incentive programs mature.
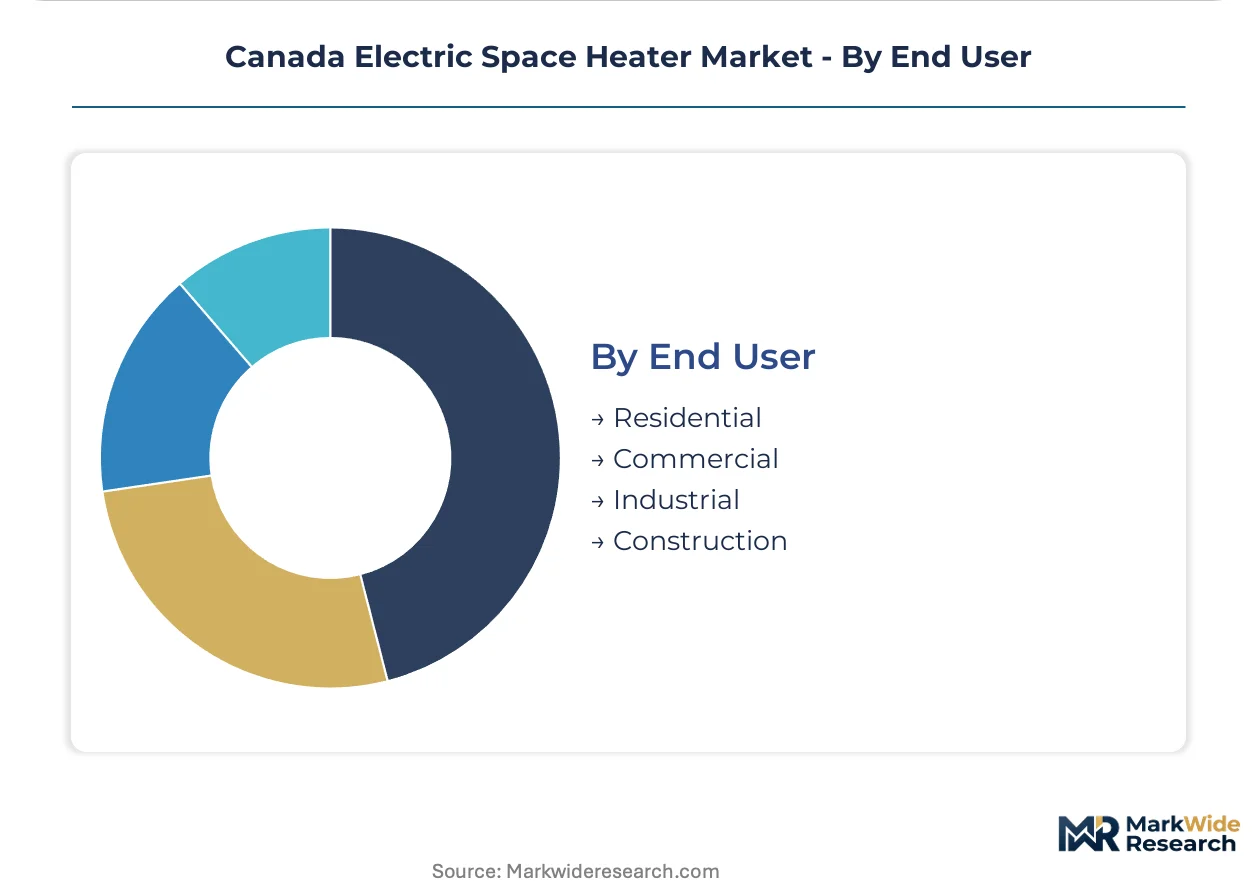
End User:
Customer type determines specification authority, channel structure, and replacement cycle length.
- Residential:Individual household purchases through retail and electrical supply channels. Retrofit-driven demand concentrates in Ontario and Quebec where EnerGuide labeling influences replacement timing.
- Commercial:Office, retail, and hospitality facilities sourcing through HVAC-R wholesalers. Toronto and Vancouver property management firms prioritize smart-controlled units for peak demand charge management.
- Industrial:Manufacturing and processing facilities requiring heavy-duty enclosures and explosion-rated elements. Alberta oil sands support facilities and Saskatchewan potash operations specify industrial-grade radiant platforms.
- Construction:Temporary heating for building sites and renovation projects. Quebec's year-round construction season and Ontario's winter concrete curing requirements sustain seasonal demand spikes.
Residential captures the largest volume base; commercial applications show the steepest expansion trajectory as building automation deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario and Quebec generate stronger retrofit demand than Alberta or British Columbia, where heat pump substitution advances faster. Provincial electrification timelines and housing stock age create divergent replacement cycles across Canadian markets.
Ontario
Toronto's pre-1980s housing stock drives baseboard heater replacements through EnerGuide-influenced purchasing decisions. Natural Resources Canada's Greener Homes grant eligibility requirements accelerate淘汰 of single-setting resistive models. The Greater Toronto Area electrical supply chain concentrates contractor-grade specification authority.
Quebec
Novoclimat program standards tighten minimum efficiency thresholds for new construction and deep retrofits alike. Hydro-Québec's peak demand management initiatives create enrollment pathways for grid-interactive heating platforms. Montreal-area master electricians source increasingly through dedicated HVAC-R wholesalers bundling controls with hardware.
Alberta
Calgary and Edmonton logistics corridors sustain commercial warehouse radiant heating specifications for loading dock zones. The province's capacity market reforms establish regulatory frameworks for utility demand-response program participation. Oil sands support facilities anchor industrial-grade heavy-duty enclosure demand.
British Columbia
Vancouver's step code electrification mandates in multi-unit residential buildings specify higher-wattage units for primary heating zones. BC Hydro's grid decarbonization trajectory supports carbon-neutral positioning against natural gas alternatives. The Lower Mainland's building automation adoption outpaces Prairie provinces.
Atlantic Canada
Halifax and Moncton pre-1990s residential structures require supplemental heating without ductwork modifications. Aging 60-amp service panels in rural Nova Scotia and New Brunswick limit 240V high-wattage penetration. Seasonal construction heating sustains temporary enclosure demand through winter building phases.
Canada Electric Space Heater Market Competitive Landscape
Ontario and Quebec producers anchor one tier; international specialists with Canadian distribution partnerships hold another. The market exhibits moderate concentration with domestic incumbents controlling electrical supply channel access while global brands capture premium retail positioning. Three archetypes dominate: established domestic manufacturers with deep contractor relationships, multinational appliance brands leveraging smart home ecosystems, and industrial-grade specialists serving commercial warehousing segments. Competitive moves center on utility program certification acquisition and direct-to-contractor distribution expansion.
Among domestic incumbents, Brant Radiant Heaters Limited and Ouellet Canada exemplify the industrial-specialist and construction-heater archetypes respectively, while Honeywell occupies a position representing multinational smart-control integration. These three entities illustrate how geographic origin and company structure correlate with channel strategy—Brant Radiant Heaters Limited's name indicating specialized industrial focus, Ouellet Canada's Quebec-rooted positioning, and Honeywell's global scale enabling thermostat convergence plays.
| Leading Market Players |
|---|
| Dyson |
| Honeywell |
| Black + Decker |
| Brant Radiant Heaters Limited |
| Ouellet Canada |
| Kelray Heating |
| Envi Heater |
| ICON |
| AirNmore |
| Others |
Pricing and Supply Chain Analysis
Captive distribution through Ontario and Quebec electrical supply houses anchors both procurement efficiency and contractor-facing pricing power for domestic incumbents. This backward integration into wholesale channels insulates margin structures from retail price erosion while creating switching costs that resist multinational retail entrants.
Pricing Analysis
Capacity additions in Ontario-based manufacturing corridors are reshaping price floors for mid-tier convection units as localized production reduces cross-border logistics burden. Three-tier pricing structure across premium smart-enabled, standard programmable, and economy manual tiers separates buyers by utility program eligibility and control sophistication. Pricing pressure stems from copper and aluminum input volatility that resists full pass-through in mass-market retail channels. Residential retrofit buyers in Atlantic Canada exhibit highest price sensitivity due to aging electrical infrastructure upgrade costs, while Toronto commercial property managers prioritize demand-response enrollment value over unit acquisition price.
Supply Chain Analysis
Regional distribution centers in Mississauga and Montreal anchor hub-and-spoke patterns that feed electrical supply houses across Ontario and Quebec. Manufacturing concentrates in Canada, China, and Mexico with ceramic heating element sourcing from East Asian foundries and steel chassis fabrication in domestic facilities. Raw material dependencies span copper wire from Chilean mines, aluminum extrusions from Quebec smelters, and semiconductor components from Taiwan. Single-source vulnerability in Wi-Fi module supply creates disruption risk for smart control product lines. Distribution runs through master electrician networks and HVAC-R wholesalers rather than big-box retail for commercial and new construction specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quebec's Novoclimat efficiency premiums against Saskatchewan's grid-decarbonization positioning create a geographic-arbitrage play for manufacturers with cross-provincial SKU flexibility. Regulatory divergence between provincial building codes rewards players who can navigate fragmented certification requirements.
For Market Incumbents: Deepen contractor loyalty programs in Ontario and Quebec electrical supply channels to defend against multinational smart-home ecosystem entrants. Acquire CSA C22.2 No. 46 pre-certification capacity for accelerated product launch cycles. Invest in firmware development partnerships to address embedded systems talent scarcity threatening smart control roadmaps. For New Entrants and Emerging Players: Begin with underpenetrated commercial warehouse radiant heating segments in Alberta and Saskatchewan logistics corridors where spot-heating specifications remain convection-dominated. Target construction heater rentals in Quebec's year-round building season through equipment-leasing partnerships. Pursue direct-to-contractor distribution bundling controls with hardware to bypass retail margin compression. For Investors and Strategic Acquirers: Roll-up economics work for regional electrical supply distributors because contractor specification authority concentrates procurement decisions among fragmented local players. Mid-cap manufacturing assets with established Health Canada certification pathways offer defensive positioning as EnerGuide standards tighten. Watch Natural Resources Canada amendment timing as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Utility Demand-Response Certification | Enrolment eligibility in Ontario's peak saver and Alberta's capacity market programs secures premium positioning. |
| Direct-to-Contractor Distribution Expansion | Master electrician channel control in Quebec and Ontario insulates margin from retail price competition. |
| Smart Control Platform Integration | Wi-Fi-enabled scheduling and geofencing capabilities capture tech-forward urban household segments. |
| Ceramic Element Efficiency R&D | Natural Resources Canada EnerGuide tightening rewards higher-efficiency thermal output platforms. |
| Regional Manufacturing Footprint Optimization | Ontario-based production reduces cross-border logistics exposure and accelerates CSA certification timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both shipment volumes and specification authority dynamics. Primary engagement spanned product managers at heating equipment manufacturers, procurement leads at Ontario electrical supply houses, master electricians in Quebec's Novoclimat program, and utility demand-response program officers at Hydro-Québec and Alberta's AESO. Secondary validation drew from Natural Resources Canada EnerGuide databases, CSA certification registries, provincial building code amendments, and customs trade records for heating element imports. Bottom-up channel shipment estimates triangulated against top-down residential construction and retrofit spending data.
Segment-weighting approaches applied differential growth assumptions across product type, control technology, power rating, and end-user dimensions over the projection horizon. Product type stratification modeled convection, oil-filled, radiant, and fan heater categories with distinct replacement cycle lengths. Control technology tiers captured manual, digital, remote, and smart-enabled penetration trajectories. CAGRs derived from regression analysis against heating-degree-day indices, provincial electrification policy timelines, and housing stock age distributions. Industry-specific inputs included EnerGuide standard amendment schedules and utility peak demand management program enrollment targets.
Several conditions sit outside the modeled scope, including extreme weather event frequency impacts on replacement timing, copper price spike scenarios beyond historical volatility bands, and heat pump technology cost curves that could accelerate substitution beyond baseline assumptions. Forecasts reflect documented assumption sets around regulatory implementation schedules and provincial carbon pricing trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Power Line Carrier System Market
Electrical Power Equipment
Protective Relay Market
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
Latin America Hazardous Location Motor Starters Market
Electrical Power Equipment
Electric Insulator Market
Electrical Power Equipment
Alternate Current (AC) Drives Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market