
 Germany Data Center Construction Market | 2026-2036
Germany Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Data Center Construction Market Insights
Market Context
A capital-intensity divergence between design-build specialists and general contractors is rotating procurement strategies toward integrated delivery models. M+W Group leverages its process engineering heritage to anchor hyperscale campus developments across industrial zones near Frankfurt. Exyte sustains competitive positioning through its cleanroom construction expertise translated into controlled-environment data halls. Arup differentiates via digital engineering workflows that compress commissioning timelines for cloud operators.
Technical Definition and Segment Structure
Germany data center construction encompasses the engineering, fabrication, and assembly of mission-critical facilities housing IT infrastructure, with specifications typically requiring tiered redundancy, power usage effectiveness below 1.3 for new builds, and seismic isolation in active zones. Hyperscale deployments concentrate the largest capital pools, while edge construction fragments across distributed sites requiring modular prefabrication. Liquid cooling segments are capturing accelerated investment as power densities exceed 50 kilowatts per rack, displacing legacy air-cooled architectures in Frankfurt's flagship developments.
Regulatory Framework and Outlook
The EU Green Deal's energy efficiency targets intersect with Germany's Federal Emission Control Act and KBA-adjacent building codes to mandate heat reuse planning and renewable power sourcing for new facilities. ECHA chemical restrictions and national fire safety regulations govern coolant selection and structural material compliance. Stakeholders must monitor evolving F-Gas Regulation phase-down schedules and their impact on cooling technology procurement decisions.
Market Dynamics
The EU Green Deal's energy efficiency mandates are compressing commissioning timelines and forcing liquid cooling retrofits across Frankfurt's hyperscale corridor. Federal emission controls now require heat reuse planning at the design phase, elevating capital requirements for new entrants.
Growth Catalysts
- F-Gas Regulation phase-down:The EU's scheduled hydrofluorocarbon restrictions are accelerating adoption of natural refrigerant cooling systems in Bavaria's data hall developments.
- Hyperscale cloud expansion:Frankfurt Rhine-Main's fiber density and power grid capacity are attracting multi-hundred-megawatt campus commitments from cloud service providers.
- Modular prefabrication:Factory-built power and cooling modules are compressing on-site construction schedules by eliminating weather-dependent concrete pours.
Market Restraints
- Copper and electrical steel volatility:Transformer and busway procurement faces input cost swings tied to commodity exchange pricing.
- Specialized contractor scarcity:Mission-critical MEP installation expertise concentrates among a limited pool of German and Dutch firms.
- Grid interconnection queues:Tennet and 50Hertz transmission upgrade timelines extend power delivery schedules by eighteen to thirty-six months in industrial zones.
Strategic Opportunities
- Eastern industrial brownfields:Saxony and Thuringia's decommissioned manufacturing sites offer grid-connected land parcels at sub-Frankfurt cost bases.
- Waste heat district integration:Berlin's municipal heating networks present offtake partnerships that satisfy Federal Emission Control Act requirements.
- Direct liquid cooling convergence:Immersion and cold-plate technologies are opening density configurations exceeding eighty kilowatts per rack for AI training clusters.
Industry Challenges
- Commissioning engineer shortage:Tier-IV certification expertise for electrical and mechanical systems outpaces vocational pipeline output.
- Legacy air-cooled retrofit complexity:Existing Frankfurt facilities face structural constraints on coolant distribution infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Data Center Construction Market |
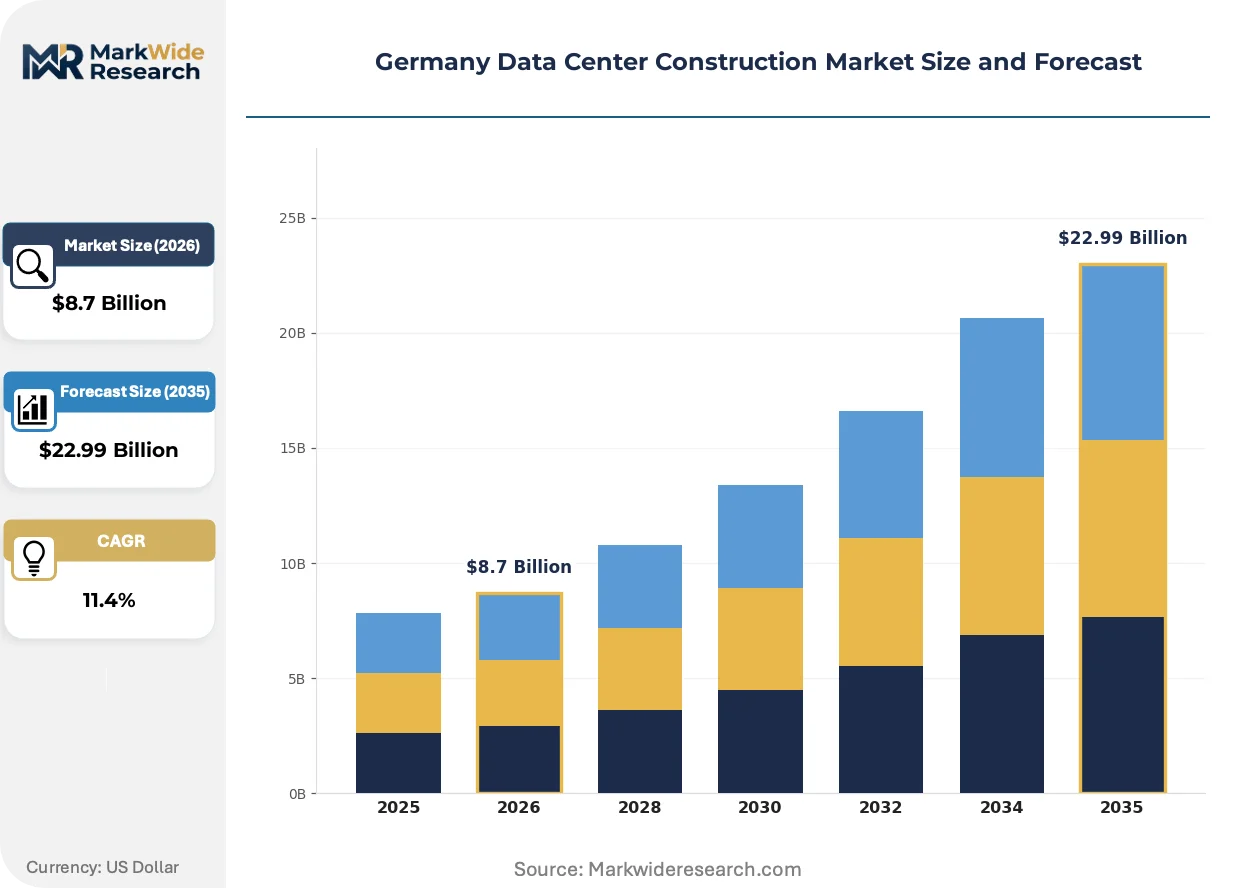
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Colocation, Hyperscale, Enterprise, Edge Power Rating: Low Power, Medium Power, High Power, Ultra High Power Cooling Technology: Air Cooling, Liquid Cooling, Green Cooling, Hybrid Cooling Construction Material: Concrete, Steel, Modular, Pre-fabricated |
| Companies Covered | AECOM, Arup, Collen Construction, DPR Construction, Lupp Group, STS Group, M+W Group, Exyte, SPIE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Data Center Construction Market Trends and Innovations
Liquid cooling architectures are compressing facility footprints and altering mechanical contracting scopes across Germany's primary data center clusters. These shifts intersect with procurement model evolution and tightening chemical regulations.
Direct-to-chip liquid cooling is supplanting raised-floor air distribution in hyperscale deployments. Cloud operators in Frankfurt's Industrial Park West are specifying cold-plate manifolds as standard for compute densities above fifty kilowatts per rack. This transition is collapsing the traditional CRAC-dominated mechanical hierarchy and elevating plumbing contractor roles in project delivery.
The EU F-Gas Regulation's stepped phase-down is restricting hydrofluorocarbon refrigerant volumes available for new chiller procurement. German facility operators are pivoting toward ammonia and CO2-based systems despite higher capital costs and safety zoning requirements. Bavarian developments face the tightest compliance timelines as the 2030 reduction targets approach.
Design-build contracting is consolidating fragmented mechanical, electrical, and architectural scopes under single-point accountability. Hyperscale tenants in Munich's Unterschleissheim corridor are mandating fixed-price, guaranteed-maximum contracts that transfer commissioning risk to construction partners. This compression is visible most acutely in projects targeting rapid deployment for AI infrastructure demand.
Germany Data Center Construction Market Segmentation
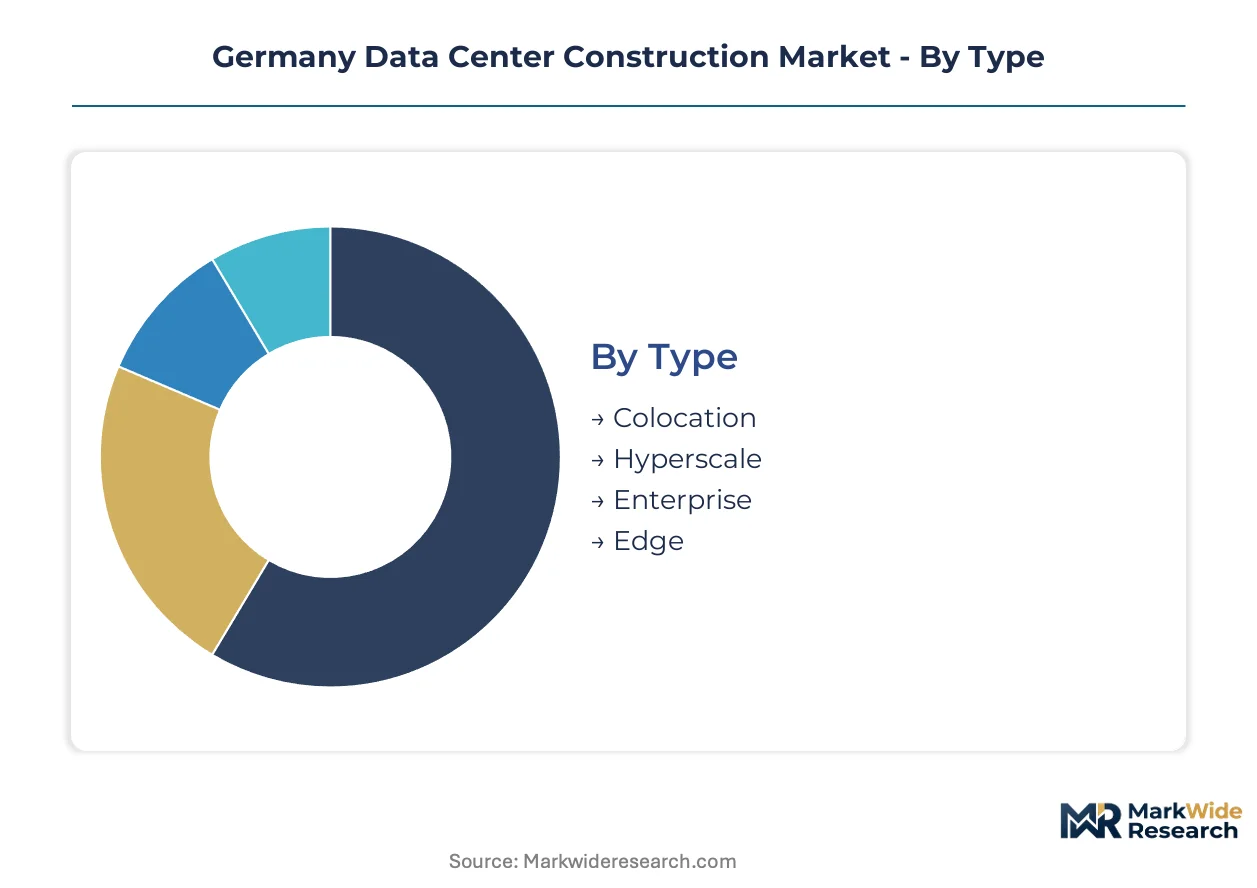
Facility typology, power density thresholds, and thermal management approaches define procurement patterns across Germany's data center construction landscape. Segment boundaries determine contractor specialization, equipment vendor selection, and commissioning complexity for mission-critical infrastructure.
Type:
Margin pools concentrate in hyperscale campus developments where scale economies offset fixed engineering costs.
- Hyperscale:Multi-megawatt facilities exceeding 50 megawatts of critical IT load, built to cloud operator specifications with tiered redundancy. Frankfurt Rhine-Main corridor attracts the largest capital commitments from cloud service providers seeking fiber density and grid capacity.
- Colocation:Multi-tenant facilities offering wholesale and retail space with standardized power and connectivity. Berlin and Munich markets show accelerating demand from financial services firms requiring proximity to trading infrastructure.
- Enterprise:Single-occupant facilities built to corporate IT specifications, often with customized security and compliance architectures. German automotive manufacturers anchor this segment with captive data halls near manufacturing footprints.
- Edge:Distributed micro-facilities positioned for latency-sensitive applications, typically below 1 megawatt. Saxony and Thuringia industrial zones present brownfield conversion opportunities for edge node deployment.
Hyperscale holds installed capacity. Edge is rotating up the share rankings.
Power Rating:
Capital intensity escalates non-linearly as density thresholds cross infrastructure upgrade boundaries.
- Ultra High Power:Facilities exceeding 100 kilowatts per rack, requiring liquid cooling manifolds and specialized electrical distribution. Frankfurt's Industrial Park West developments specify these densities for AI training clusters.
- High Power:Racks drawing 30-100 kilowatts, demanding enhanced busway and transformer capacity. Munich Unterschleissheim corridor concentrates this tier for enterprise cloud migration.
- Medium Power:Standard enterprise densities of 10-30 kilowatts per rack with conventional air-cooled architectures. Colocation providers in Berlin target this segment for mid-market tenants.
- Low Power:Legacy densities below 10 kilowatts, still prevalent in retrofitted industrial buildings. Eastern German brownfield conversions often begin at this tier before phased upgrades.
Medium Power dominates current completions. Ultra High Power is gaining share fastest.
Cooling Technology:
Regulatory pressure on refrigerant chemistry is resequencing technology adoption curves.
- Liquid Cooling:Direct-to-chip and immersion systems for densities above 50 kilowatts per rack. Cold-plate manifolds are becoming standard in Frankfurt hyperscale specifications.
- Green Cooling:Natural refrigerant systems using ammonia or CO2 to satisfy EU F-Gas Regulation phase-down. Bavarian developments face the tightest compliance timelines.
- Air Cooling:Conventional raised-floor CRAC architectures for legacy and low-density facilities. Existing Frankfurt buildings face structural constraints on retrofit feasibility.
- Hybrid Cooling:Combined air and liquid systems offering transitional density accommodation. Modular prefabrication suppliers are integrating these configurations for rapid deployment.
Air Cooling retains installed base. Liquid Cooling is climbing the fastest.
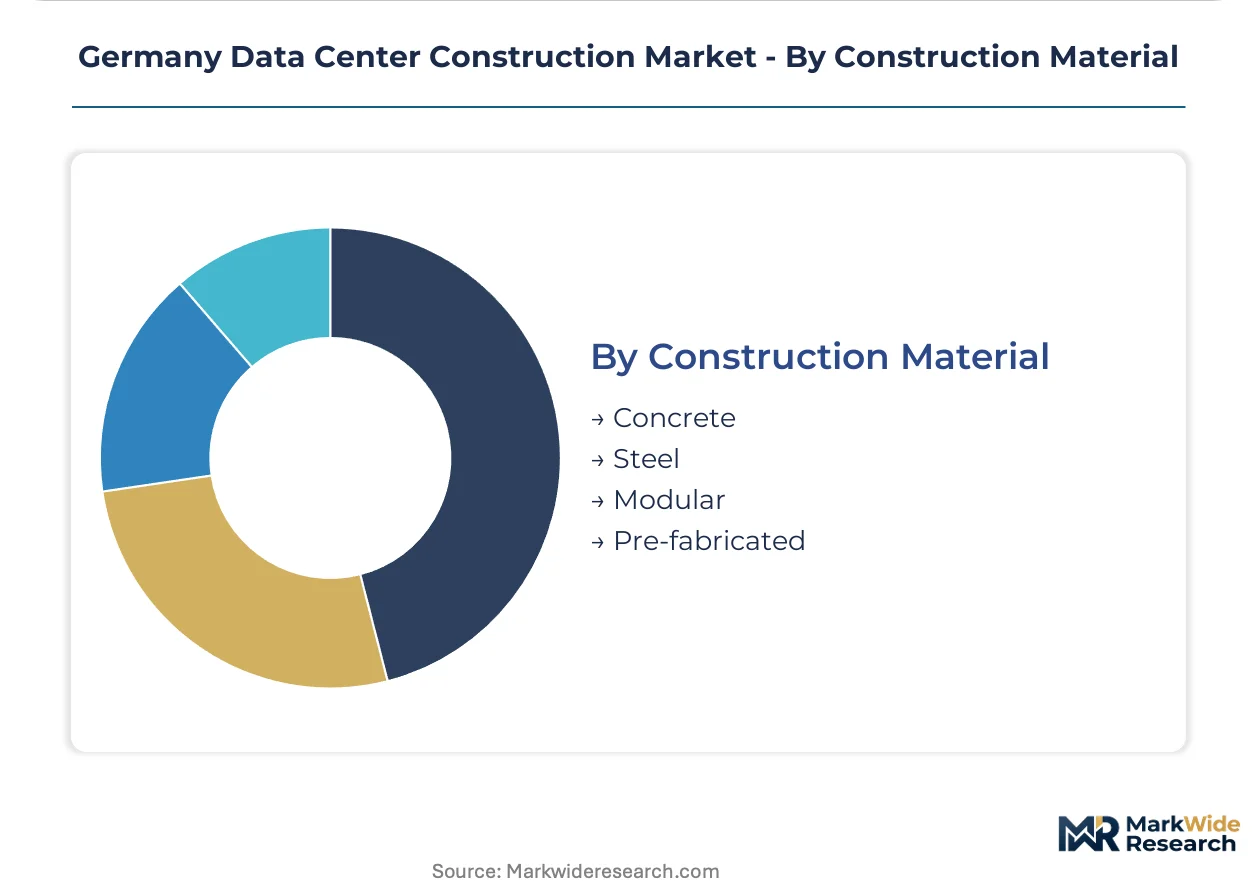
Construction Material:
Speed-to-market requirements are elevating factory fabrication over site-built methods.
- Modular:Factory-built power and cooling modules delivered as integrated skids. Weather-independent construction compresses commissioning schedules by eliminating concrete pour dependencies.
- Pre-fabricated:Pre-cast structural elements and pre-assembled MEP racks for rapid on-site assembly. Hyperscale tenants in Munich mandate these methods for guaranteed-maximum contracts.
- Concrete:Traditional cast-in-place structural systems for large-footprint facilities. Grid interconnection queues in industrial zones reduce the penalty of longer construction timelines.
- Steel:Structural steel framing for seismic zones and rapid vertical expansion. Frankfurt's geological stability reduces this requirement compared to other European clusters.
Concrete holds legacy stock. Modular is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt Rhine-Main commands premium pricing for data center land and power, while eastern German industrial zones offer cost bases below half those levels. This asymmetry is redirecting hyperscale investment toward Saxony and Thuringia brownfields.
Frankfurt Rhine-Main
Cloud service providers anchor multi-hundred-megawatt campus commitments here, drawn by fiber density and grid capacity. The Federal Emission Control Act mandates heat reuse planning for all new builds, elevating capital requirements. Industrial Park West developments specify liquid cooling manifolds for AI training clusters exceeding eighty kilowatts per rack.
Berlin-Brandenburg
Financial services firms drive colocation demand requiring proximity to trading infrastructure. Municipal heating networks present waste heat offtake partnerships that satisfy KBA-adjacent building code requirements. Spandau and Adlershof districts concentrate new facility announcements from modular prefabrication specialists.
Bavaria
Enterprise cloud migration fuels Munich Unterschleissheim corridor development. The EU F-Gas Regulation's 2030 reduction targets impose the tightest compliance timelines here, accelerating natural refrigerant adoption. Erding and Freising industrial zones host ammonia-based cooling deployments for hyperscale tenants.
North Rhine-Westphalia
Automotive manufacturers anchor captive data halls near manufacturing footprints in Cologne and Düsseldorf. Grid interconnection queues from Tennet extend power delivery schedules by eighteen to thirty-six months. Dortmund and Essen brownfields attract edge node deployment for latency-sensitive industrial IoT applications.
Germany Data Center Construction Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Germany's data center construction market. Design-build specialists with process engineering heritage command premium positioning for hyperscale campuses, while general contractors compete on speed and regional access. Three archetypes dominate: integrated delivery specialists, cleanroom construction transplants, and digital engineering boutiques. Competitive moves concentrate on fixed-price guaranteed-maximum contracting and modular prefabrication partnerships that compress commissioning risk.
Among integrated delivery specialists, M+W Group and Exyte occupy positions reflecting their industrial construction lineages. M+W Group exemplifies the process engineering archetype applied to mission-critical facilities, while Exyte represents cleanroom expertise translated into controlled-environment data halls. Arup sits within the digital engineering tier, anchoring workflows that compress commissioning timelines for cloud operators. These three players illustrate how heritage capabilities determine competitive positioning without overlapping scope.
| Leading Market Players |
|---|
| AECOM |
| Arup |
| Collen Construction |
| DPR Construction |
| Lupp Group |
| STS Group |
| M+W Group |
| Exyte |
| SPIE |
| Others |
Pricing and Supply Chain Analysis
Fixed-price guaranteed-maximum contracts lock in supply access for hyperscale tenants while compressing price visibility for German contractors facing copper and electrical steel volatility. This structure transfers commissioning risk to construction partners and anchors procurement around modular prefabrication methods that eliminate weather-dependent concrete pour dependencies.
Pricing Analysis
The customization-premium spread separates configured-to-order hyperscale campuses from standardized colocation builds. Project-based pricing dominates, with differentiation driven by tiered redundancy certification and geographic delivery cost to eastern industrial zones. Pricing pressure stems from specialized contractor scarcity concentrating among limited German and Dutch mission-critical MEP firms. Enterprise automotive captive facilities show highest price sensitivity; cloud service providers absorb premiums for speed-to-market.
Supply Chain Analysis
Transformer and busway procurement chokepoints tether German data center builds to Chinese and South Korean electrical steel output. Copper winding stock, specialized refrigerants, and pre-cast concrete modules draw from Belgium, the Netherlands, and domestic suppliers. Single-source vulnerability concentrates in liquid cooling manifold fabrication. Distribution runs through integrated design-build specialists rather than fragmented general contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's data center construction market sits in early-cycle expansion as AI training cluster demand accelerates liquid cooling retrofits across Frankfurt's hyperscale corridor. Cloud operator capital commitments are outstripping available commissioning engineer supply.
For Market Incumbents: Compound design-build expertise through captive plumbing and electrical contractor relationships to defend against emerging modular prefabrication specialists. Prioritize vertical integration into factory-built power module production. Lock in long-term copper and electrical steel offtake agreements before commodity volatility intensifies. For New Entrants and Emerging Players: Commissioning engineer shortage presents service-layer white space where incumbents under-serve Tier-IV certification demand. Target Saxony and Thuringia brownfield conversions for lowest cost-base entry. Pursue direct partnerships with Tennet and 50Hertz to bypass grid interconnection queue delays. For Investors and Strategic Acquirers: Cleanroom construction transplants with ammonia cooling expertise represent the most defensible acquisition target archetype as EU F-Gas Regulation phase-down tightens. Watch Bavarian compliance timeline acceleration as inflection indicator for natural refrigerant system demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Partnership | Factory-built power modules compress commissioning schedules for Frankfurt hyperscale tenants. |
| Liquid Cooling Technology Licensing | Cold-plate manifold expertise unlocks densities exceeding eighty kilowatts per rack for AI clusters. |
| Waste Heat District Integration | Berlin municipal heating offtake partnerships satisfy Federal Emission Control Act mandates. |
| Backward Integration into Electrical Steel | Captive transformer core supply hedges against copper and steel commodity volatility. |
| Eastern Brownfield Site Acquisition | Saxony and Thuringia grid-connected parcels offer sub-Frankfurt cost bases for edge deployment. |
Research Methodology
The analysis maps hyperscale campus, colocation, enterprise, and edge facility typologies, each validated through EPC contractor executives, data center operator procurement leads, Tennet grid planning officers, and cooling technology vendors. Primary interview insights triangulate against customs trade data for copper and electrical steel, EU F-Gas Regulation filings, KBA-adjacent building code documentation, and hyperscaler capital expenditure disclosures. Bottom-up project pipeline enumeration cross-checks with top-down construction spending estimates.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. Segmentation models incorporate facility type, power density tier, cooling technology, and construction material dimensions. CAGRs derive from fitted growth curves applied to disclosed project capacities and contractor backlog data. Grid interconnection queue timelines and refrigerant phase-down schedules anchor scenario-specific forecast inputs.
Forecasts assume regulatory continuity in EU Green Deal implementation and German Federal Emission Control Act enforcement; material policy shifts would require re-modeling. Copper price volatility, specialized labor pipeline constraints, and transmission upgrade delays represent specific risk factors that could revise trajectory. Practitioners should keep alternative scenarios live as F-Gas Regulation compliance deadlines and AI infrastructure demand curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Virtual Infrastructure Manager Market
Data Center Infrastructure
Delhi-NCR Data Center Market
Data Center Infrastructure
Asia-Pacific Hyperscale Data Center Market
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Global Data Center Rack and Enclosure Market
Data Center Infrastructure
Chicago Data Center Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
United States (US) Data Center Construction Market
Data Center Infrastructure
Data Center Containment Solution Market