
 User Research Repositories Software Market | 2026-2036
User Research Repositories Software Market Size, Share, and Industry Trends Forecast 2026-2036
User Research Repositories Software Market Insights
The capability gap between venture-backed platform builders and bootstrapped specialists is collapsing as cloud infrastructure commoditizes core storage and search functions. Dovetail leverages extensive API ecosystems to anchor enterprise workflows across design and analytics stacks. Maze sustains dominance in unmoderated testing linkages that feed directly into repository pipelines. Stravito specializes in consumer insights translation for product marketing teams, occupying a niche between raw research data and executive decision dashboards.
User research repositories software constitutes a centralized digital infrastructure for ingesting, tagging, retrieving, and distributing qualitative and quantitative research artifacts across organizational boundaries. Platforms typically employ semantic search indexing, automated transcription alignment, and permission-based access tiers to preserve data fidelity while enabling cross-functional collaboration. Cloud-Based deployment leads solution type adoption as enterprises prioritize elastic scaling over capital-intensive on-premise maintenance, though Hybrid configurations are gaining traction among financial services buyers with segmented compliance requirements. UX/UI Teams represent the fastest-expanding user type as design-ops functions formalize research-ops counterparts, while Integration Capability centered on API Access and Project Management Software connectivity captures the highest margin pools through recurring integration service fees.
The EU AI Act and GDPR impose strict constraints on automated insight generation and cross-border data residency, compelling vendors to architect region-specific instance isolation. The US lacks unified federal privacy legislation, though sectoral HIPAA and state-level frameworks create a patchwork compliance burden for health-tech and financial research deployments. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized platform architecture or federated deployment models better align with evolving enforcement patterns.
Market Dynamics
API-first architectures are collapsing the moat between integrated platform suites and point solutions, forcing vendors to compete on workflow embedding depth rather than standalone feature breadth.
Growth Catalysts
- GDPR-compliant automation:The EU AI Act mandates explainable insight generation, creating procurement pull for vendors with built-in audit trails and consent management layers.
- Design-ops formalization:UX/UI teams at SaaS enterprises are establishing dedicated research-ops functions that require centralized ingestion pipelines for unmoderated testing data.
- Cloud infrastructure maturation:Elastic storage and serverless indexing are commoditizing core repository functions, lowering barriers for mid-market buyers to adopt enterprise-grade platforms.
Market Restraints
- Cross-border data residency:GDPR's data-localization requirements force vendors to maintain region-specific instances, fragmenting engineering resources and inflating operational overhead.
- Transcription API concentration:Dependency on a narrow set of speech-to-text providers creates input cost volatility and service continuity exposure for automated artifact processing.
- Legacy CRM integration friction:On-premise Salesforce and Microsoft Dynamics deployments resist real-time API synchronization, limiting repository penetration in regulated financial services.
Strategic Opportunities
- Underpenetrated health-tech vertical:HIPAA-covered entities lack purpose-built research repositories that satisfy minimum necessary access controls and audit logging mandates.
- Consumer insights convergence:Product marketing teams require translation layers between raw qualitative data and executive dashboards, a white space between analytics and repository platforms.
- Hybrid deployment architectures:Financial services buyers with segmented compliance requirements seek on-premise data lakes with cloud-based collaboration frontends.
Industry Challenges
- Research-ops talent scarcity:Organizations struggle to hire professionals who bridge UX methodology, data governance, and platform administration.
- Semantic indexing standardization delays:Absence of industry-wide taxonomy frameworks forces bespoke tagging implementations that impede cross-organizational data portability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | User Research Repositories Software Market |
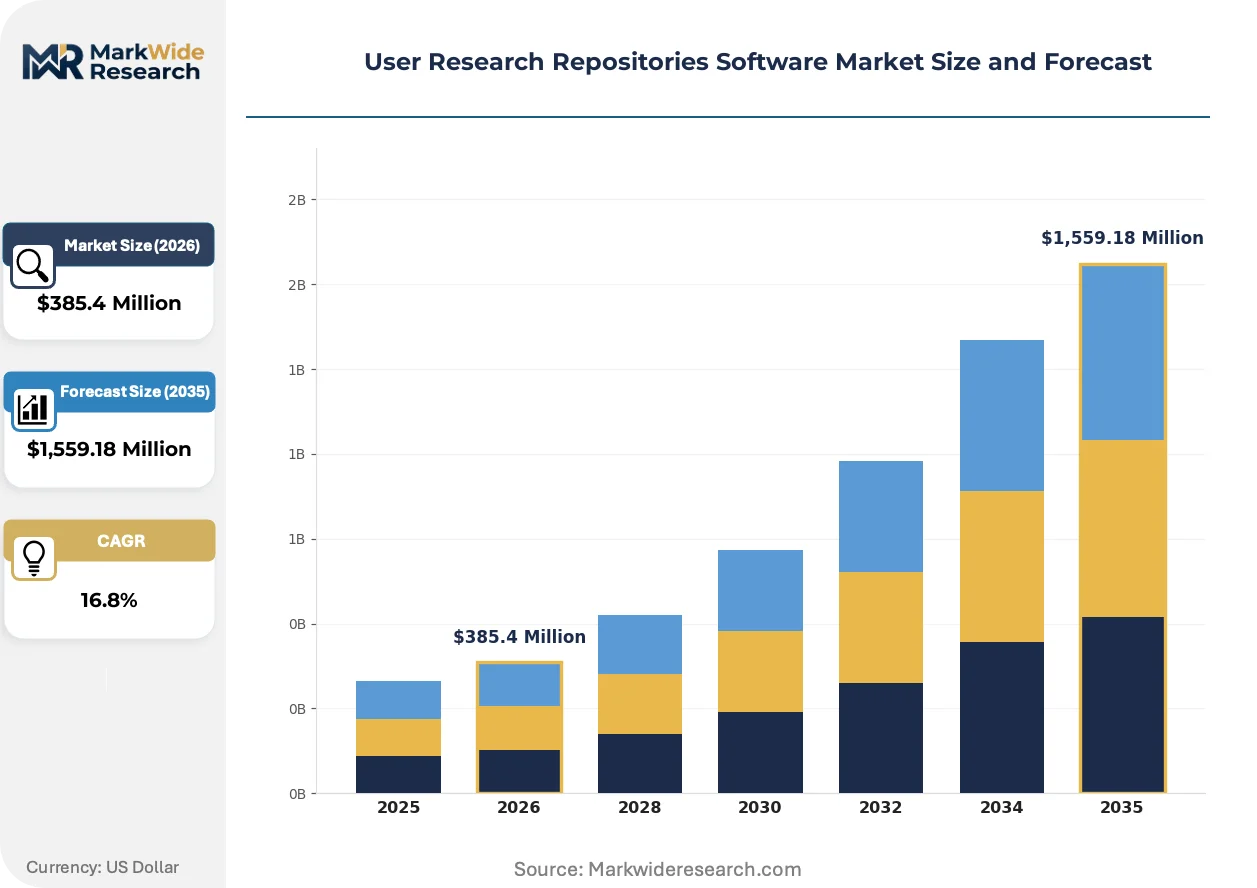
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,559.18 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-Based, On-Premise, Hybrid, Enterprise User Type: Individual Researchers, UX/UI Teams, Product Managers, Market Analysts Functionality: Data Organization, Collaboration Tools, Analysis Features, Reporting Options Integration Capability: API Access, Third-Party Tools, CRM Systems, Project Management Software |
| Companies Covered | Dovetail, Chisel, HeyMarvin, Condens, Stravito, Maze, Aurelius, EnjoyHQ, Tetra Insights, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
User Research Repositories Software Market Trends and Innovations
Workflow automation is compressing the latency between research execution and insight distribution, reshaping how product teams consume qualitative evidence.
Natural language processing for automated insight extraction is fragmenting the traditional analyst intermediary role. Enterprise UX teams at technology firms are deploying these tools to surface patterns across hundreds of interview transcripts without manual coding. This compression is collapsing the distinction between raw repository storage and synthesized reporting layers.
The EU AI Act's risk-based classification system is imposing documentation burdens on automated insight generation features. Vendors must now maintain technical files demonstrating human oversight mechanisms and bias mitigation protocols. High-risk deployments in hiring and credit decision support face mandatory conformity assessments, pushing vendors toward modular architectures that isolate algorithmic components.
Enterprise buying committees are consolidating vendor relationships around platforms that embed directly into Figma, Jira, and Slack workflows. Procurement evaluation criteria now weight API depth and webhook configurability above standalone interface quality. This behavioral shift is most pronounced among Series C and later SaaS companies with distributed product teams across multiple time zones.
User Research Repositories Software Market Segmentation
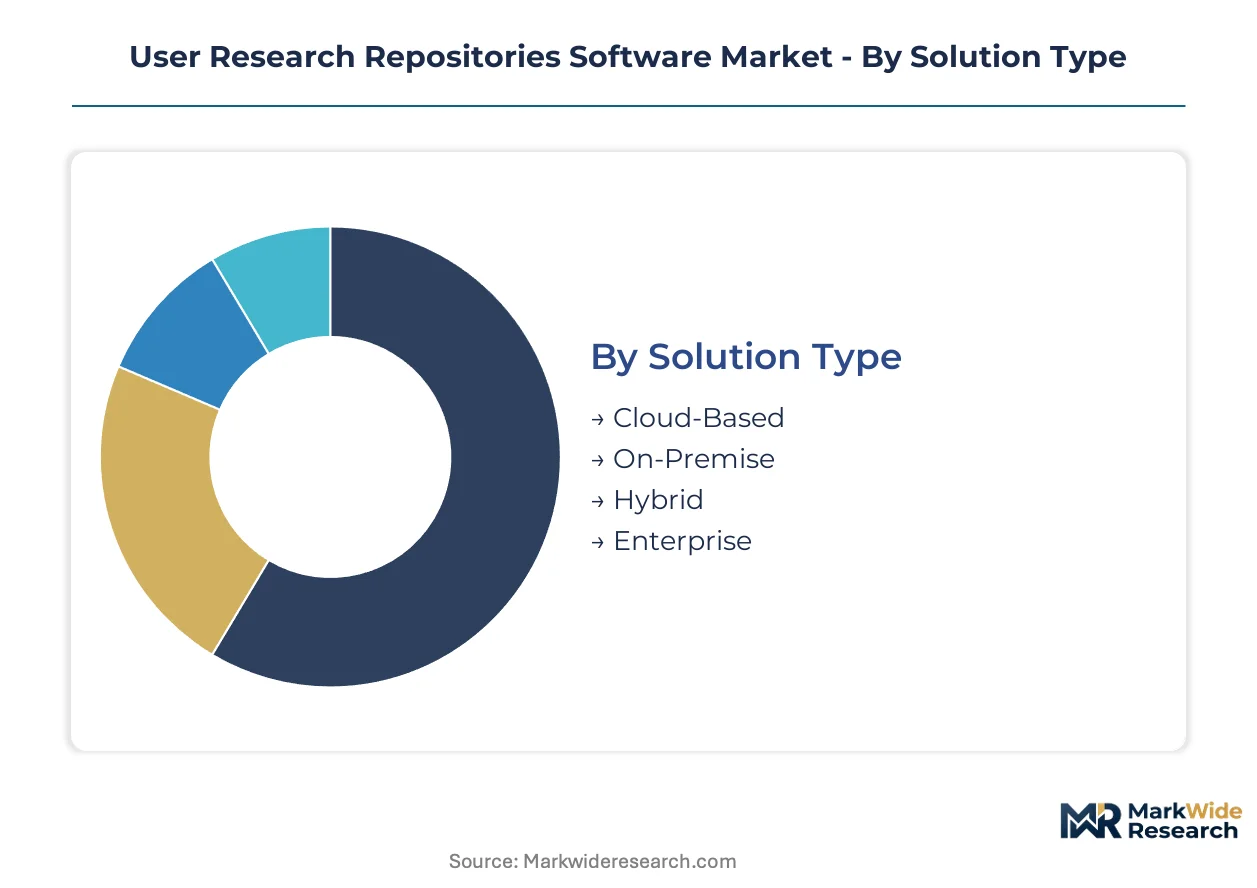
Segmentation reveals how procurement criteria diverge across technical environments and organizational roles. Buyers prioritize deployment flexibility, workflow embedding depth, and compliance posture differently based on team structure and regulatory exposure.
Solution Type:
Substitution pressure from serverless architectures and managed data lakes threatens traditional on-premise offerings most severely, while cloud-native platforms defend through ecosystem lock-in.
- Cloud-Based:Elastic storage and serverless indexing eliminate capital expenditure barriers for mid-market buyers. Demand concentrates among Series C and later SaaS enterprises with distributed product teams across multiple time zones, driven by API-first architectures that embed directly into Figma and Slack workflows.
- Hybrid:Segmented compliance architectures pair on-premise data lakes with cloud-based collaboration frontends. Financial services buyers in Frankfurt and Singapore drive procurement, constrained by GDPR data-localization mandates and MAS technology risk management guidelines.
- On-Premise:Capital-intensive maintenance models face displacement from managed infrastructure services.
- Enterprise:Custom instance isolation and dedicated support tiers address multi-tenant security requirements.
Cloud-Based deployments anchor the volume base while Hybrid configurations gain share at the steepest rate.
User Type:
Cost tier stratification separates individual practitioners from enterprise buyers with formalized research-ops budgets and procurement committees.
- UX/UI Teams:Design-ops formalization creates dedicated research-ops counterparts requiring centralized ingestion pipelines. Technology firms in San Francisco and Berlin expand headcount fastest, compelled by unmoderated testing data volumes that overwhelm spreadsheet-based tracking.
- Product Managers:Cross-functional accountability demands translation layers between raw qualitative evidence and executive dashboards. Demand clusters at growth-stage SaaS companies, shaped by pressure to compress insight-to-decision latency.
- Individual Researchers:Freelance and academic practitioners favor lightweight, pay-per-seat pricing.
- Market Analysts:Consumer insights teams require convergence between repository platforms and analytics suites.
UX/UI Teams dominate current procurement volume while Product Managers show the steepest expansion trajectory.
Functionality:
Application-specific depth determines margin capture, with analysis and reporting modules commanding premium pricing against commoditized storage functions.
- Analysis Features:Automated insight extraction through natural language processing fragments the traditional analyst intermediary role. Enterprise UX teams deploy semantic indexing to surface patterns across interview transcript libraries without manual coding.
- Collaboration Tools:Permission-based access tiers and real-time annotation preserve data fidelity across organizational boundaries. Demand concentrates in regulated health-tech verticals where HIPAA minimum necessary access controls mandate granular entitlement systems.
- Data Organization:Automated transcription alignment and tagging taxonomies form the foundational layer.
- Reporting Options:Executive dashboard exports bridge qualitative repositories and quantitative business intelligence platforms.
Data Organization anchors installed base volume while Analysis Features capture the steepest share gains.
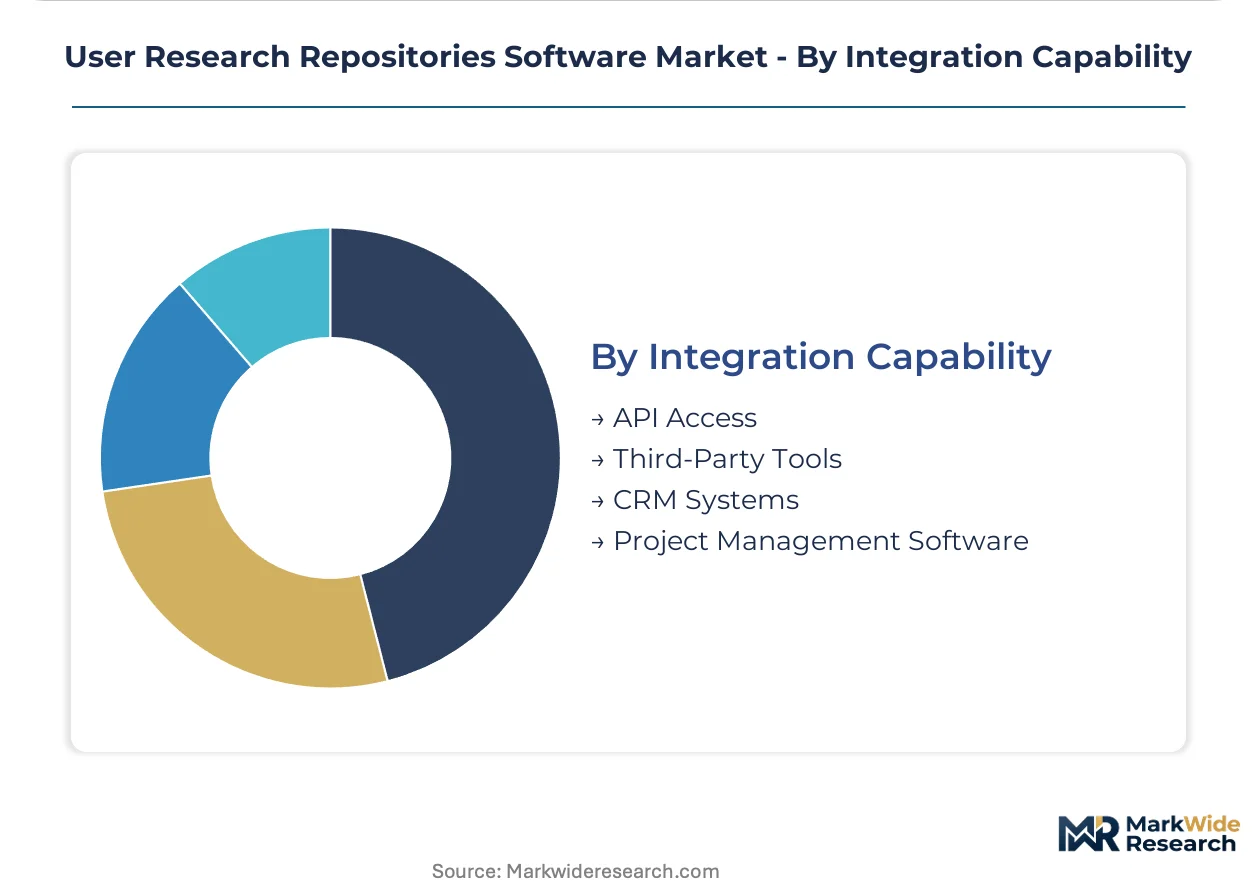
Integration Capability:
Customer type segmentation separates API-native buyers seeking workflow embedding from tool-agnostic purchasers prioritizing standalone interface quality.
- API Access:Webhook configurability and depth of endpoint documentation now outweigh standalone interface quality in procurement evaluations. Series C and later SaaS companies mandate bidirectional synchronization with design and analytics stacks.
- Project Management Software:Jira and Asana connectivity compresses the latency between research execution and backlog prioritization. Product operations teams in London and Toronto drive adoption, compelled by agile sprint cycles that demand rapid evidence injection.
- Third-Party Tools:Design system and prototyping platform linkages extend repository reach into creative workflows.
- CRM Systems:Salesforce and HubSpot integration faces friction from on-premise legacy deployments resisting real-time synchronization.
API Access anchors enterprise contract value while Project Management Software connectivity expands most quickly among mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States exhibit the lowest price elasticity as SaaS enterprises prioritize workflow embedding depth over licensing costs, while procurement teams in India and Southeast Asia remain highly sensitive to per-seat pricing tiers.
United States
Technology firms in San Francisco and New York maintain the highest density of UX research investments, driving premium procurement budgets for API-first platforms. HIPAA and sectoral state privacy frameworks create compliance complexity for health-tech deployments. Seattle's cloud infrastructure cluster accelerates adoption of serverless indexing architectures among Series C and later SaaS companies.
Germany
Automotive and industrial software sectors in Munich and Stuttgart generate concentrated demand for GDPR-compliant automation with built-in audit trails. The EU AI Act mandates explainable insight generation, pulling procurement toward vendors with consent management layers. Berlin's design-ops community formalizes research-ops functions faster than any other European hub.
United Kingdom
London's fintech and product operations teams drive adoption of Jira and Asana connectivity to compress insight-to-decision latency. The UK GDPR framework imposes cross-border data residency constraints similar to EU standards. Product managers at growth-stage SaaS companies in Manchester and Bristol expand headcount for centralized repository procurement.
India
Bangalore and Hyderabad-based SaaS enterprises prioritize elastic cloud storage over capital-intensive on-premise maintenance, though per-seat pricing sensitivity remains acute. The country's data localization directives under draft privacy legislation compel vendors to evaluate region-specific instance isolation. Design-ops formalization lags Western markets but accelerates among venture-backed startups.
Japan
Enterprise UX teams in Tokyo and Osaka deploy semantic indexing to surface patterns across interview transcript libraries without manual coding. METI guidelines on AI governance shape vendor selection criteria for automated insight extraction. Osaka's manufacturing software cluster shows emerging interest in hybrid deployment architectures for segmented compliance requirements.
User Research Repositories Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with API-first platform builders defending position through ecosystem lock-in while point solutions compete on workflow embedding depth. The capability gap between venture-backed consolidators and bootstrapped specialists collapses as cloud infrastructure commoditizes core storage functions. Three archetypes dominate: integrated workflow platforms, unmoderated testing specialists, and consumer insights translators. Competitive moves concentrate on strategic partnerships with design tool ecosystems and geographic expansion through region-specific instance isolation.
Within the integrated platform tier, Dovetail and Maze exemplify divergent embedding strategies, with the former anchoring enterprise workflows across analytics stacks and the latter sustaining dominance in unmoderated testing linkages. Stravito occupies a distinct position between raw research data and executive decision dashboards, representing the consumer insights convergence archetype.
| Leading Market Players |
|---|
| Dovetail |
| Chisel |
| HeyMarvin |
| Condens |
| Stravito |
| Maze |
| Aurelius |
| EnjoyHQ |
| Tetra Insights |
| Others |
Pricing and Supply Chain Analysis
GDPR and the EU AI Act's compliance certification tiers gate both vendor qualification and price differentiation simultaneously, forcing platforms to maintain region-specific engineering overhead that stratifies pricing across data-residency requirements. HIPAA's minimum necessary access controls in the US health-tech vertical create parallel certification premiums that separate purpose-built repository vendors from generalist competitors.
Pricing Analysis
Integration service fees and extended API support contracts drive lifetime value beyond base subscription tiers. Three-tier pricing structure across enterprise, mid-market, and individual practitioner levels reflects deployment complexity and compliance posture rather than raw storage volume. Cost compression in the mid-market tier is intensifying because cloud infrastructure commoditizes core indexing functions. Individual researchers and freelance practitioners exhibit acute per-seat price sensitivity, while Series C and later SaaS enterprises prioritize workflow embedding depth over licensing costs.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes and container availability constraints inflate inbound logistics costs for hardware-dependent hybrid deployment components. Engineering talent concentrates in the United States, Germany, and India, with cloud infrastructure services drawing from hyperscaler data center networks in Ireland, Singapore, and Virginia. Single-source vulnerability sits with transcription API providers—AWS Transcribe, Google Cloud Speech-to-Text, and Azure Speech Services—whose pricing volatility feeds directly into platform cost structures. Distribution runs through direct enterprise sales teams and cloud marketplace listings with implementation partner overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organizations struggle to hire professionals who bridge UX methodology, data governance, and platform administration, creating a persistent capability gap that shapes competitive outcomes. This scarcity concentrates value capture with vendors who bundle implementation services and training curricula.
For Market Incumbents: Compound ecosystem lock-in through deeper Figma and Jira embedding while accelerating region-specific instance isolation for GDPR and emerging data-localization mandates. Defend against API-first challengers by acquiring specialist transcription or semantic indexing firms to control input costs. Certification investment in HIPAA and EU AI Act conformity assessments creates switching costs that protect renewal rates. For New Entrants and Emerging Players: Anchor in the underpenetrated health-tech vertical where HIPAA-covered entities lack purpose-built research repositories with minimum necessary access controls. Target product marketing teams requiring translation layers between raw qualitative data and executive dashboards—a white space between analytics and repository platforms. Pursue a services-led go-to-market that bundles implementation with research-ops talent provision. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment architectures as serverless indexing commoditizes core storage functions. Long-term viability favors platforms with durable API ecosystem relationships and recurring integration revenue streams. Acquisition target archetype: bootstrapped specialists with deep workflow embedding in design tools but limited geographic footprint. Monitor hyperscaler transcription API pricing announcements as an inflection indicator for platform margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Figma and Jira embedding compresses insight-to-decision latency for distributed product teams. |
| Geographic Expansion | Region-specific instance isolation satisfies GDPR data-localization mandates in Frankfurt and Singapore. |
| Acquisition of Specialist Firm | Transcription or semantic indexing targets control input costs and reduce API concentration risk. |
| Strategic Partnership | Hyperscaler alliances secure preferential cloud infrastructure pricing and co-selling access. |
| Product Launch | HIPAA-compliant modules address minimum necessary access controls in health-tech deployments. |
Research Methodology
Initial hypotheses were tested against primary input from UX research directors, platform engineering leads, procurement officers at SaaS enterprises, and research-ops practitioners and refined through secondary validation against SEC filings, hyperscaler capex disclosures, App Annie integration tracking data, and EU regulatory filings. Bottom-up sizing of vendor-reported seat counts and top-down triangulation against enterprise software spending patterns converged on segment-level estimates.
Variance decomposition across the projection horizon isolates contribution from deployment model shifts, user type expansion, and integration complexity tiers. Modeled dimensions span cloud-based, hybrid, and on-premise deployments; UX/UI teams, product managers, and individual researchers; and API access depth against standalone functionality. CAGRs were derived from segment-level growth rate reconciliation with aggregate market expansion. Forecast inputs include unmoderated testing data volume growth and design-ops formalization rates at Series C and later SaaS companies.
Decision-makers should treat outputs as directional under assumptions of sustained cloud infrastructure cost declines and stable transcription API pricing; material deviation would warrant model refresh. Specific risks include regulatory divergence between EU AI Act enforcement and US sectoral privacy frameworks, and research-ops talent scarcity constraining platform adoption velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Application Release Automation Market
Software & Services
Proxy Services and Software Market
Software & Services
Global CMDB Software Market
Software & Services
Global Auto Dealer Software Market
Software & Services
Global CMMS Software Market
Software & Services
Data Migration Software Services Market
Software & Services
File Sharing Software Market
Software & Services
Relational Database Management System Market
Software & Services
Global Electronic Data Capture Software Market
Software & Services
Retail Core Banking Solution Market
Software & Services
Equipment Management Software Market
Software & Services
Queue Manager Market
Software & Services
Content Distribution Software Market
Software & Services
Asia-Pacific Accounting Software Market
Software & Services
Audio Editing Software Market
Software & Services
Device Tracking Software Market