
 Global Handyman Software Market | 2026-2036
Global Handyman Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Handyman Software Market Foresight
API-first architecture is rebalancing the economics of handyman software by displacing monolithic legacy systems with modular, integratable components. Jobber leverages its Canadian origins to anchor North American contractor workflows through deep QuickBooks and payment gateway integrations. Synchroteam competes on geographic reach with localized tax and compliance engines across France, Australia, and the United Kingdom. Housecall Pro dominates brand recognition in the United States residential segment through intensive field sales and contractor community building.
Handyman software denotes field service management platforms engineered for independent tradespeople and small service businesses, typically incorporating GPS dispatch algorithms, real-time inventory synchronization, and automated quote-to-cash workflows to streamline job scheduling and payment collection. Cloud-based deployment leads the product type spectrum due to minimal upfront capital requirements and automatic security patching, while mobile apps represent the fastest-expanding access layer as Android and iOS devices become standard field equipment. SaaS deployment models concentrate margin pools through recurring subscription revenue, whereas self-managed installations retain niche traction among facilities management entities with stringent data sovereignty requirements.
FDA oversight of medical device servicing documentation intersects with handyman software when facilities management contractors maintain healthcare equipment, while GDPR and the EU AI Act impose algorithmic transparency and data residency obligations on European deployments. OSHA recordkeeping mandates in the United States push commercial service providers toward platforms with integrated incident reporting and safety compliance modules. Stakeholders must evaluate whether their vendor's roadmap prioritizes embedded fintech capabilities or vertical specialization in regulated end-use environments.
Market Dynamics
API-first architecture is compressing vendor margins by fragmentating monolithic suites into modular, interoperable components that contractors assemble rather than buy as integrated packages. This structural shift rewards platforms with embedded payment infrastructure and penalizes standalone scheduling tools.
Growth Catalysts
- Residential renovation volume:United States housing stock aging past 40 years median age triggers sustained maintenance demand. Contractors digitize workflows to manage higher job throughput without proportional headcount expansion.
- GDPR Article 32 technical safeguards:European contractors face mandatory encryption and access-log requirements for customer data. Compliance-driven software procurement accelerates cloud migration among French and German tradespeople previously using paper systems.
- Embedded finance convergence:Field service platforms integrate instant payout rails and trade credit facilities. Payment float revenue subsidizes subscription pricing, expanding addressable market to margin-constrained solo operators.
Market Restraints
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud host over 80 percent of field service platform workloads. Single-region outages cascade into contractor downtime with no on-premise fallback.
- Interoperability tax:Legacy ERP systems in commercial facilities management require expensive middleware for bidirectional sync. Integration project costs often exceed annual software subscription fees.
- Skilled technician scarcity:Plumbing, electrical, and HVAC trades face 23,000 annual retirements in the United States against 15,000 new apprentices. Labor shortage caps job volume regardless of software efficiency gains.
Strategic Opportunities
- India unpenetrated base:63 million micro-enterprises in construction and repair services operate with minimal digitization. Localized Hindi and Marathi interfaces plus UPI payment integration unlock first-mover positioning.
- OSHA 300A automation:United States employers with 250+ employees must electronically submit injury records. Incident-reporting modules bundled with scheduling software create compliance-adjacent revenue streams.
- Voice-to-work-order interfaces:Natural language processing converges with field mobility. Spanish-speaking crews in Texas and Florida complete job documentation without keyboard interaction, reducing administrative friction.
Industry Challenges
- API versioning fragmentation:QuickBooks, Xero, and Sage release breaking updates on mismatched cycles. Development teams maintain parallel integration branches, inflating engineering overhead.
- State-level contractor licensing heterogeneity:California, New York, and Texas maintain incompatible continuing education requirements. Platforms must map 147 distinct license types to automated renewal alerts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Handyman Software Market |
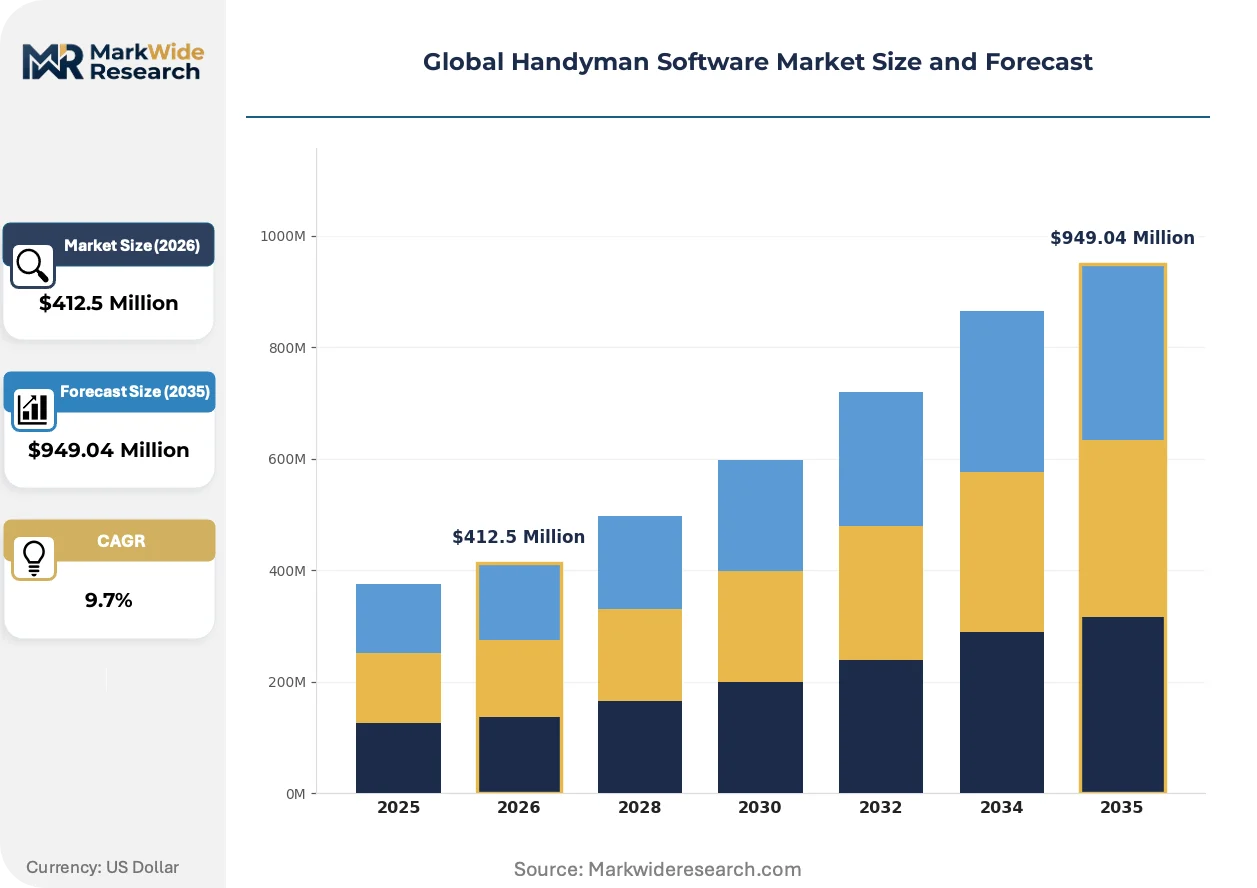
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $949.04 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Mobile Apps, Web Applications Deployment: SaaS, Hosted, Self-Managed, Hybrid Cloud Application: Scheduling, Billing & Invoicing, Customer Management, Inventory Tracking, Quote Estimation End User: Individual Contractors, Small Businesses, Property Maintenance, Commercial Service Providers, Facilities Management |
| Companies Covered | Synchroteam, RazorSync, Housecall Pro, Repsly, ServiceBridge, Jobber, Ai Field Management, Connecteam, Workiz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Handyman Software Market Shifts & Advancements
Generative AI is compressing the quote-to-cash cycle by auto-drafting scope documents from voice notes and photograph analysis. This capability is rapidly becoming table stakes rather than premium differentiation.
Mobile-native architectures are overtaking responsive web wrappers as the dominant field interface. Android and iOS SDKs enable offline-first job execution with background synchronization when cellular coverage resumes. Independent electricians in rural Texas and plumbing crews in suburban Atlanta now expect full functionality without continuous connectivity. Native performance is overtaking browser-based convenience in vendor selection criteria.
EU AI Act risk classification mandates are forcing algorithmic transparency in automated dispatch systems. High-risk categorization applies to AI determining worker availability and customer pricing. French and German vendors must document training data provenance and maintain human-in-the-loop override capabilities. Compliance engineering consumes 15-20 percent of product development capacity.
Subscription fatigue among small contractors is fragmentating purchasing authority to individual technicians. Crew leads procure single-user licenses with personal credit cards rather than centralized IT procurement. This shadow-IT pattern concentrates in the United States residential segment where turnover exceeds 40 percent annually and formal vendor management is absent.
Global Handyman Software Market Segmentation
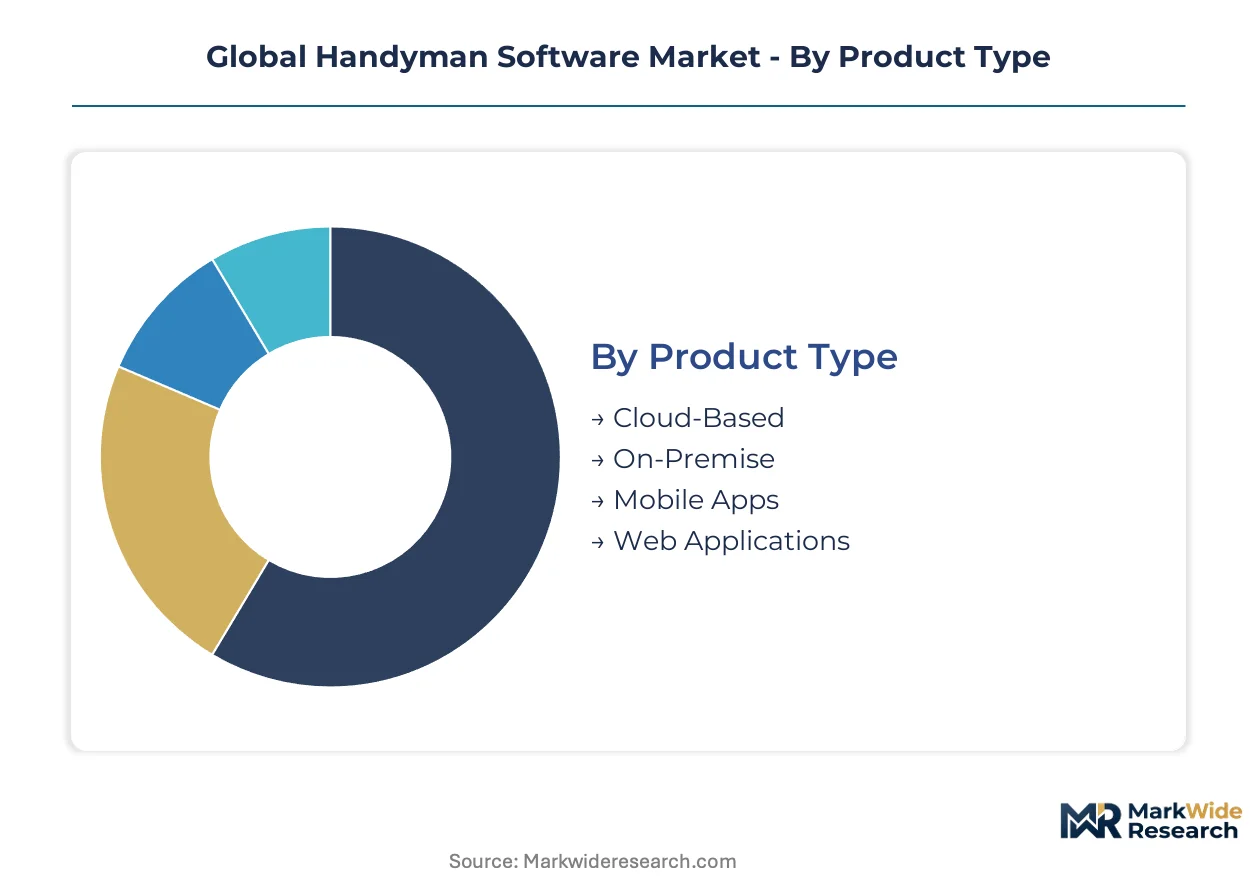
Segmentation in handyman software reveals how contractor workflows fragment across technical architectures and operational priorities. Distinct buyer profiles—from solo electricians to multi-site facilities managers—demand incompatible feature bundles and pricing models.
Product Type:
Standalone deployments dominate budget-conscious segments, while embedded modules integrate with broader enterprise systems. Cloud infrastructure maturity has compressed the performance gap between browser-native and installed applications.
- Cloud-Based:Multi-tenant architectures with automatic patching and elastic compute scaling serve contractors lacking dedicated IT staff. Demand clusters among United States residential renovators managing seasonal workload spikes without capital expenditure. AWS, Azure, and Google Cloud host the majority of these workloads, creating concentration risk during regional outages.
- Mobile Apps:Offline-first execution with background synchronization enables full functionality during cellular dead zones. Adoption accelerates fastest among plumbing and HVAC crews in rural Texas and suburban Atlanta where continuous connectivity fails. Native SDK performance now exceeds responsive web wrappers in vendor selection criteria.
- On-Premise:Facilities management entities with stringent data sovereignty requirements retain these installations despite higher total cost of ownership.
- Web Applications:Browser-based access layers persist in back-office dispatch operations where keyboard-intensive data entry dominates.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Mobile Apps.
Deployment:
Cost tier structures separate recurring subscription models from capital-intensive ownership arrangements. Margin pools redistribute based on payment float capture and integration depth.
- SaaS:Subscription revenue concentrates margin pools through predictable recurring streams. Embedded fintech capabilities—instant payout rails and trade credit facilities—subsidize base pricing to reach margin-constrained solo operators. United States gig-economy expansion sustains this model's dominance.
- Self-Managed:Complete infrastructure control satisfies GDPR Article 32 technical safeguard mandates for German and French contractors requiring encryption and access-log documentation. Healthcare facilities management contractors maintaining FDA-regulated equipment documentation favor this deployment for audit trail integrity.
- Hosted:Single-tenant managed infrastructure splits the difference between SaaS convenience and data isolation requirements.
- Hybrid Cloud:Sensitive customer data resides on-premise while dispatch algorithms execute in public cloud environments.
Revenue concentration sits with SaaS; steepest expansion trajectory belongs to Self-Managed among compliance-driven European procurement.
Application:
Functional modules map to specific workflow friction points in the contractor job cycle. Maturity varies sharply across quote-to-cash automation versus basic calendaring.
- Scheduling:GPS dispatch algorithms with real-time route optimization address the core pain point for multi-crew operations. United States residential renovation volume—driven by housing stock aging past 40 years median age—pushes demand for higher job throughput without proportional headcount expansion.
- Billing & Invoicing:Automated quote-to-cash workflows with integrated payment collection compress days-sales-outstanding for cash-constrained small businesses. Generative AI auto-drafting scope documents from voice notes and photograph analysis is becoming table stakes rather than premium differentiation.
- Customer Management:CRM functionality tracks homeowner preferences and warranty histories for repeat business cultivation.
- Inventory Tracking:Real-time parts synchronization prevents job delays from stockouts in van-based operations.
- Quote Estimation:AI-assisted pricing engines leverage historical job data to reduce bid preparation time.
Adoption depth concentrates in Scheduling; the gaining share fastest category is Billing & Invoicing as embedded finance convergence accelerates.
End User:
Customer type determines procurement authority centralization and price sensitivity thresholds. Shadow-IT patterns fragment purchasing to individual technicians in high-turnover segments.
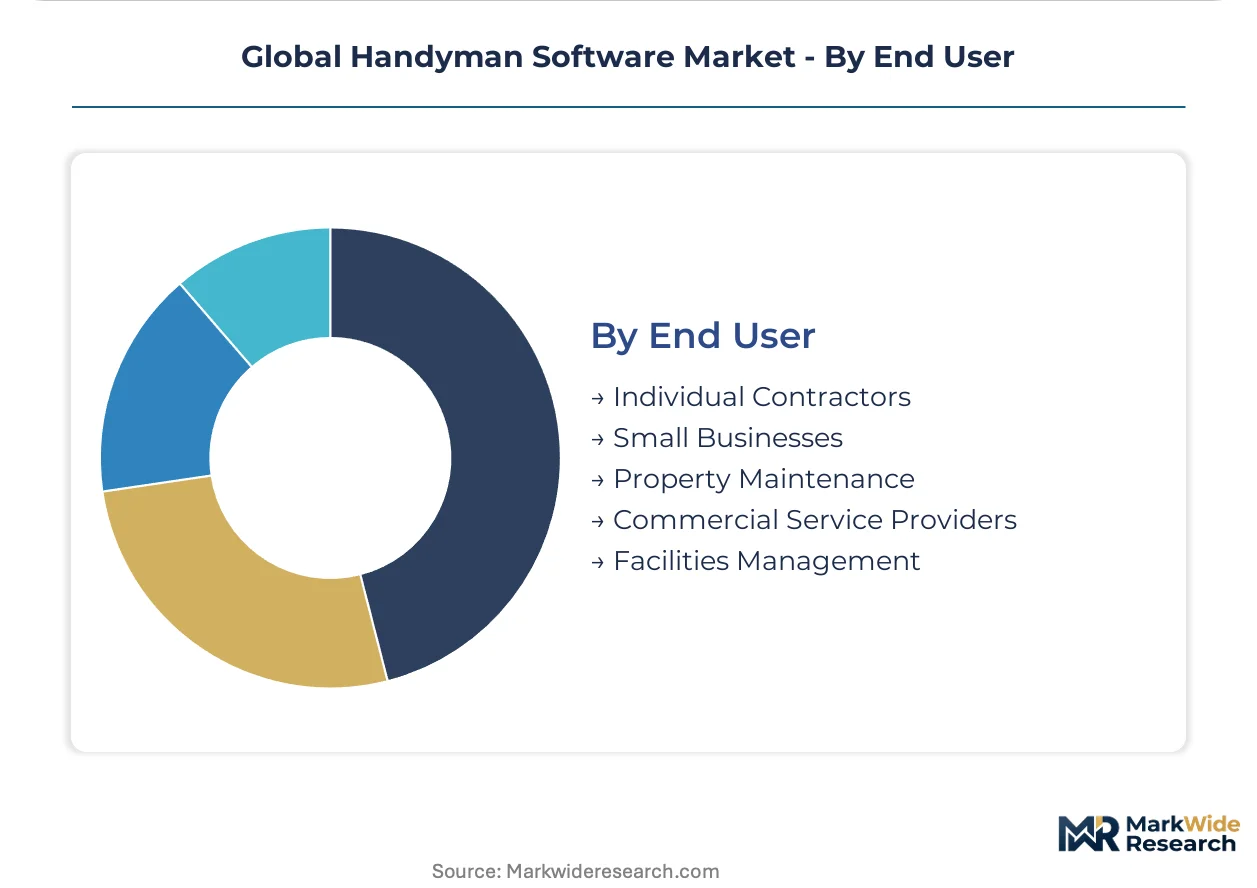
- Small Businesses:Formal vendor management with centralized IT procurement characterizes this segment. OSHA 300A automation requirements for United States employers with 250+ employees drive bundled incident-reporting module adoption alongside core scheduling functionality.
- Individual Contractors:Subscription fatigue and 40 percent annual turnover in United States residential segments push purchasing authority to crew leads using personal credit cards. Single-user licenses bypass centralized procurement entirely.
- Property Maintenance:Multi-site residential portfolio operators demand tenant communication portals integrated with work order dispatch.
- Commercial Service Providers:Legacy ERP interoperability requirements in facilities management inflate integration project costs beyond annual subscription fees.
- Facilities Management:FDA oversight of medical device servicing documentation intersects with platform selection when healthcare equipment maintenance is involved.
Current revenue concentration rests with Small Businesses; the expanding most quickly segment is Individual Contractors as gig-economy workforce expansion outpaces formal business formation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States residential renovation activity concentrates the highest platform uptake, with aging housing stock and gig-economy workforce expansion sustaining demand. Cloud infrastructure maturity accelerates small business adoption across all tracked geographies.
United States
OSHA 300A electronic submission mandates for employers with 250-plus employees drive bundled incident-reporting module procurement. The Department of Labor enforces strict recordkeeping standards that push commercial service providers toward integrated safety compliance platforms. Dallas-Fort Worth and suburban Atlanta clusters show dense contractor concentration where offline-first mobile execution dominates vendor selection.
Germany
GDPR Article 32 technical safeguard requirements accelerate cloud migration among tradespeople previously reliant on paper systems. The Federal Office for Information Security audits encryption and access-log documentation for customer data handling. Munich and Stuttgart industrial corridors host facilities management contractors prioritizing self-managed deployments for audit trail integrity.
United Kingdom
Post-Brexit regulatory divergence creates demand for localized tax engines and compliance modules distinct from EU frameworks. HMRC digital service requirements push VAT-registered contractors toward automated quote-to-cash workflows. London and Southeast England concentrate property maintenance operators seeking tenant communication portals integrated with dispatch systems.
India
Sixty-three million micro-enterprises in construction and repair services operate with minimal digitization, representing substantial first-mover opportunity. RBI UPI payment integration mandates and BIS data localization guidelines shape vendor architecture decisions. Maharashtra and Karnataka technology corridors emerge as early adoption clusters for Hindi and Marathi interface localization.
Australia
TGA documentation requirements intersect with handyman software when facilities management contractors maintain healthcare equipment servicing records. The Australian Taxation Office's single-touch payroll compliance drives automated workforce management module adoption. Sydney and Melbourne metropolitan areas concentrate demand for real-time inventory synchronization in van-based plumbing and HVAC operations.
Global Handyman Software Market Competitive Landscape
API-first platform consolidation dominates the current landscape as vendors displace monolithic legacy systems with modular, integratable components. The vendor base fragments across three strategic tiers: embedded fintech specialists capturing payment float revenue, vertical compliance platforms serving regulated end-use environments, and geographic localization engines addressing tax heterogeneity. M&A activity concentrates on payment infrastructure acquisition, while strategic partnerships with accounting software providers lock in workflow integration.
Within the embedded finance tier, Jobber leverages its Canadian origins to anchor North American contractor workflows through deep accounting integrations. Housecall Pro occupies a position exemplifying brand-intensive field sales approaches in United States residential segments. Synchroteam represents the geographic reach archetype with localized compliance engines across multiple European and Asia-Pacific markets. These three entities collectively illustrate how origin-based positioning and integration depth determine competitive differentiation in contractor-facing platforms.
| Leading Market Players |
|---|
| Synchroteam |
| RazorSync |
| Housecall Pro |
| Repsly |
| ServiceBridge |
| Jobber |
| Ai Field Management |
| Connecteam |
| Workiz |
| Others |
Supply & Pricing Matrix
API-first architecture migration simultaneously compresses vendor engineering costs and fragments platform pricing power by enabling modular component assembly. Cloud infrastructure maturation concentrates compute supply among three hyperscalers while embedded finance capabilities subsidize subscription tiers for cash-constrained solo operators.
Pricing Analysis
Volume concentration in SaaS tiers subsidizes margin capture through payment float revenue rather than subscription uplift alone. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration depth and embedded fintech access, with solo contractors exhibiting highest price sensitivity. Pricing pressure stems from API commoditization of core scheduling modules. Enterprise facilities managers demonstrate lowest price sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Cloud compute supply rests on AWS, Azure, and Google Cloud infrastructure concentrated in United States, Ireland, and Singapore regions. Raw material dependencies span semiconductor fabrication for mobile chipsets, rare earth elements for device batteries, and fiber optic cable for data transmission. Single-region outage vulnerability creates cascading contractor downtime risk. Distribution runs through direct vendor-to-subscriber digital channels with minimal intermediary layering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled technician scarcity caps job volume regardless of software efficiency gains, propping pricing power for platforms that compress administrative burden per crew member.
For Market Incumbents: Deploy embedded payment infrastructure to capture float revenue that subsidizes base subscription pricing against standalone scheduling tool competitors. Deepen QuickBooks and Xero integration maintenance to defend against API versioning fragmentation eroding workflow stickiness. Prioritize OSHA 300A automation module development for United States commercial service provider retention. For New Entrants and Emerging Players: Launch via UPI-integrated mobile-first platforms targeting India's 63 million micro-enterprises in construction and repair services with Hindi and Marathi localization. Voice-to-work-order interfaces for Spanish-speaking crews in Texas and Florida represent the most penetrable white-space segment. Pursue field sales density in suburban Atlanta and Dallas-Fort Worth contractor clusters. For Investors and Strategic Acquirers: Exit pathways concentrate in payment infrastructure acquisition by vertical SaaS consolidators seeking embedded finance capabilities. Long-term viability favors platforms with compliance-engineered architectures for EU AI Act and GDPR mandates. Watch OSHA electronic submission deadline enforcement as inflection indicator for incident-reporting module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Payment Integration | Payment float revenue subsidizes subscription pricing to reach margin-constrained solo operators. |
| API-First Platform Migration | Modular architecture displaces monolithic legacy systems and fragments vendor margin pools. |
| Compliance Module Bundling | OSHA 300A automation creates adjacent revenue streams among United States commercial providers. |
| Voice Interface Localization | Natural language processing reduces administrative friction for Spanish-speaking field crews. |
| Geographic Expansion | UPI payment integration unlocks first-mover positioning among India's construction micro-enterprises. |
Research Methodology
Independent corroboration across platform engineering leads, contractor operations managers, and embedded fintech product directors underwrites the qualitative findings. Primary interviews with SaaS procurement officers at multi-site facilities management entities, integration specialists at accounting software providers, and field technicians in residential renovation segments combined with secondary validation from SEC SaaS company filings, hyperscaler capex disclosures, and OSHA regulatory guidance. Bottom-up subscriber counts triangulate against top-down addressable market estimates.
Rate-of-change decomposition across deployment model, organization size, vertical specialization, and regional adoption pattern segments informs the analytical framework. CAGRs derive from segment-level growth rate reconciliation with aggregate market trajectory. Forecast inputs incorporate cloud infrastructure maturity curves and contractor workforce demographic projections across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for generative AI quote-to-cash automation would alter the outlook. Forecasts reflect assumptions regarding GDPR Article 32 compliance acceleration and gig-economy workforce expansion persistence. Regulatory enforcement intensity around EU AI Act risk classification and OSHA electronic submission mandates warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Global Nosql Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
Workshop Management Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Train Reservation Software Market
Software & Services
Automotive Design Software Market
Software & Services
Servicenow Tech Services Market
Software & Services
Waterway Transportation Software Solutions Market
Software & Services
Neurodiverse Workforce Productivity Tools Market
Software & Services
Office Software Market
Software & Services
Augmented Reality Software Development Kit Market
Software & Services
Global Offshore Software Development Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market