
 Labor Management Software Market | 2026-2036
Labor Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Labor Management Software Market Analytics
The split between premium enterprise suites and commodity point solutions is realigning around integration depth and real-time data orchestration. ADP leverages its payroll-to-workforce data backbone to anchor mid-market expansion. SAP competes through embedded HANA analytics that unify labor metrics with supply chain execution.
Labor management software comprises applications that schedule, track, optimize, and analyze workforce activities against operational targets, typically processing time-clock feeds, task completion signals, and labor standards at sub-second intervals to generate productivity variance reports. Cloud-based deployment leads in new contract value as manufacturers and retailers abandon server maintenance overhead, while workforce planning functionality captures the fastest expansion as algorithmic scheduling replaces manual shift boards. Compliance management modules command premium pricing in aerospace and healthcare verticals where fatigue-rule adherence carries liability exposure.
FDA scrutiny of time-tracking accuracy in pharmaceutical manufacturing, EU GDPR constraints on biometric clock-in data retention, and OSHA recordkeeping mandates for injury-correlated labor hours collectively elevate compliance functionality from optional module to procurement prerequisite. Stakeholders must weigh whether to consolidate around full-suite vendors or assemble best-of-breed stacks as API interoperability becomes the decisive architectural bet.
Market Dynamics
Algorithmic scheduling transparency mandates under the EU AI Act are forcing vendors to re-engineer workforce planning modules, while cloud migration in logistics hubs accelerates real-time labor orchestration demands.
Growth Catalysts
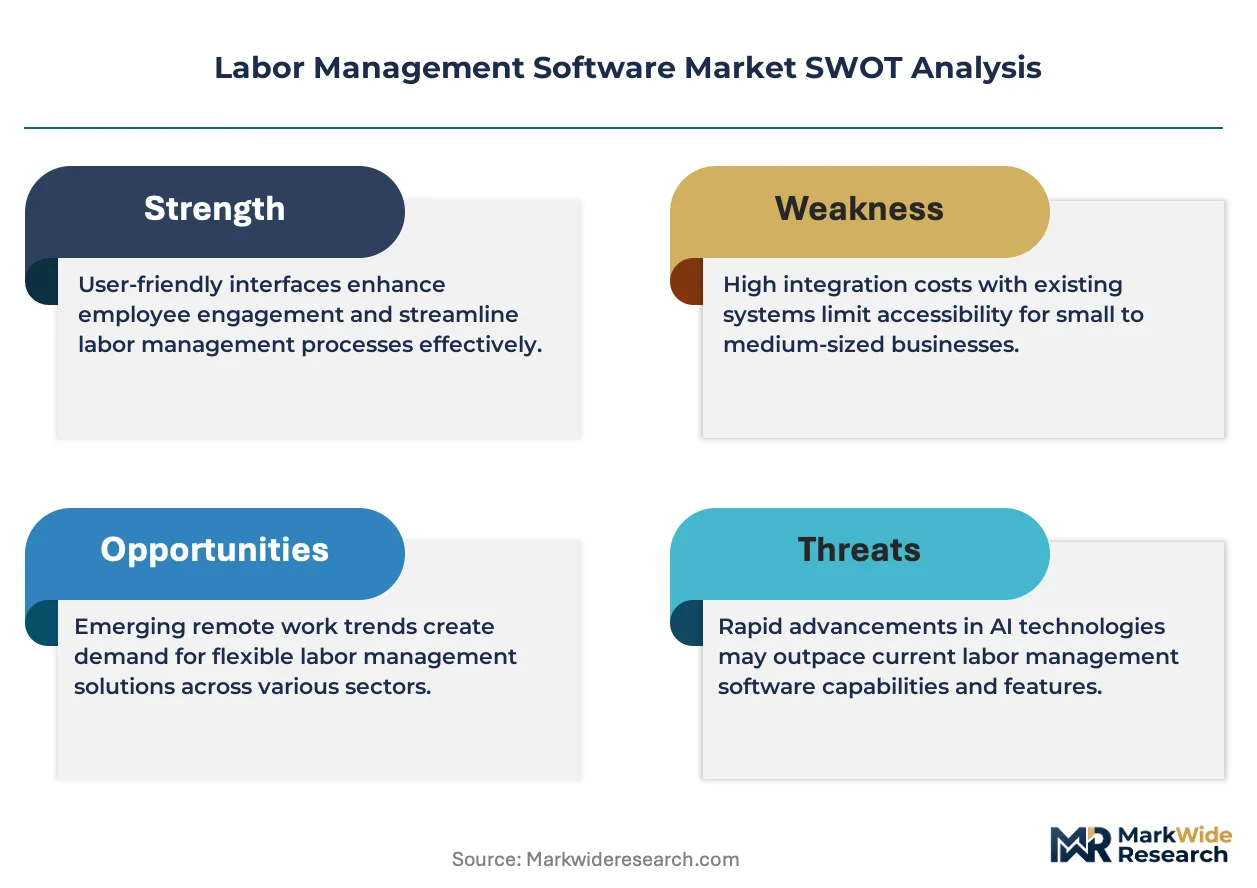
- EU AI Act compliance mandates:Algorithmic scheduling transparency requirements drive replacement cycles in European retail and manufacturing operations.
- Biometric time-clock adoption:Pharmaceutical manufacturers deploy fingerprint and facial recognition systems to meet FDA time-tracking accuracy standards.
- Seasonal workforce volatility:Retail chains invest in predictive staffing modules to manage holiday surge capacity across distribution networks.
Market Restraints
- GDPR biometric data constraints:EU member states impose strict retention limits on fingerprint and facial recognition templates, complicating multi-national deployment architectures.
- Legacy system integration costs:On-premise ERP installations in aerospace and defense require expensive middleware to connect with cloud-native workforce platforms.
- Substitution by native payroll modules:Large enterprises extend existing HCM suites rather than purchasing standalone labor optimization tools.
Strategic Opportunities
- OSHA injury-correlated analytics:New recordkeeping mandates create demand for modules linking labor hour patterns to incident rates in warehousing and manufacturing.
- Healthcare fatigue-rule adherence:Aerospace and hospital systems seek premium compliance tools to manage shift limits and rest-period calculations.
- API-first architecture convergence:Best-of-breed vendors combine workforce data with supply chain execution platforms through standardized integration layers.
Industry Challenges
- Data science talent scarcity:Vendors struggle to hire machine learning engineers capable of building predictive scheduling models for complex shift environments.
- Multi-jurisdiction compliance fragmentation:Software must simultaneously satisfy FDA pharmaceutical rules, EU biometric restrictions, and OSHA safety mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Labor Management Software Market |
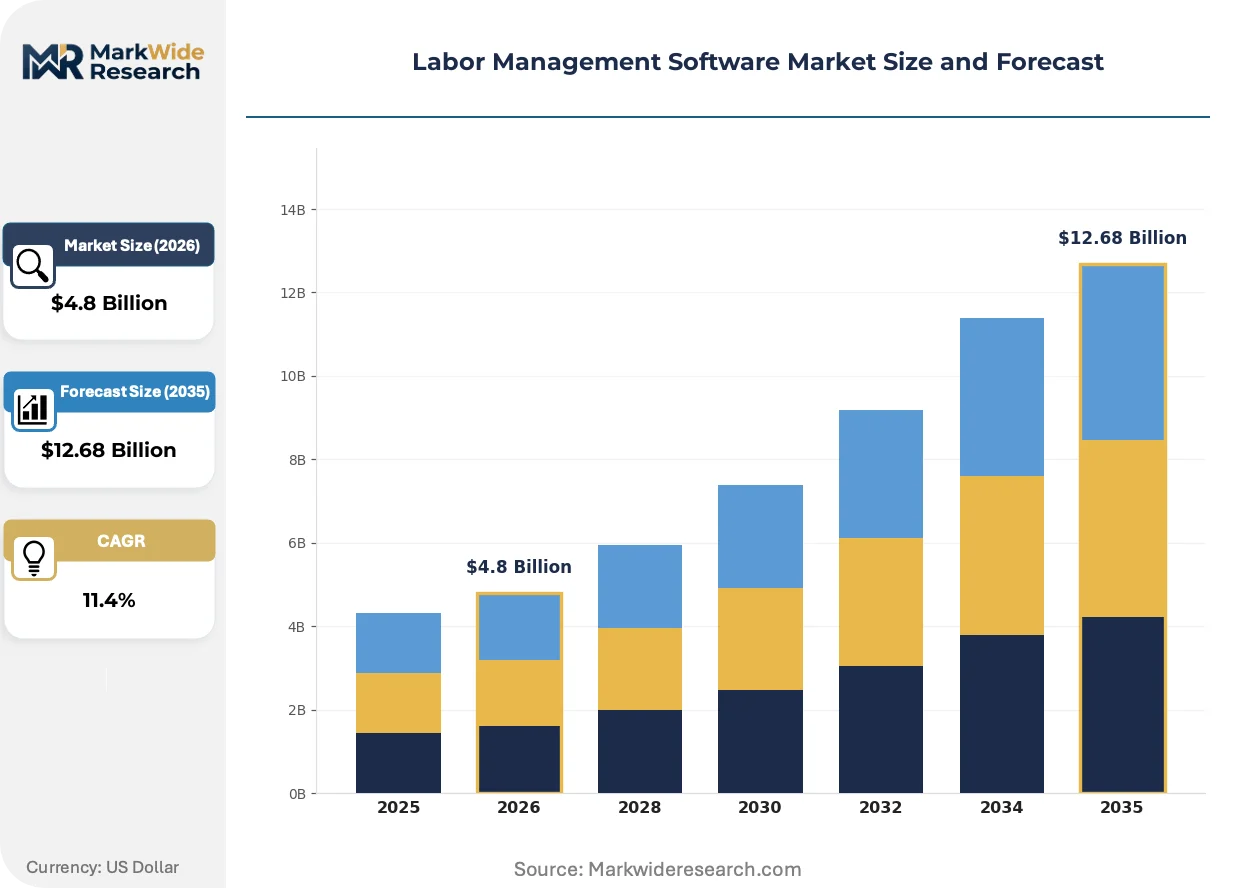
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Manufacturing, Retail, Logistics, Healthcare Functionality: Time Tracking, Workforce Planning, Analytics, Compliance Management Industry Vertical: Aerospace, Construction, Education, Hospitality |
| Companies Covered | ADP, SAP, UKG, Oracle, Workday, Blue Yonder, Kronos, Manhattan Associates, Infor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Labor Management Software Market Evolving Landscape
Real-time data orchestration capabilities are separating competitive positions, with edge computing and embedded analytics redefining how labor signals translate into operational decisions.
Edge computing infrastructure is integrating time-clock feeds and task completion signals directly at warehouse floor level, eliminating latency to central servers. Third-party logistics providers in the United States deploy these architectures to support sub-second productivity variance calculations. This compression of data processing is integrating labor metrics with automated material handling systems for synchronized workflow control.
The EU AI Act establishes mandatory documentation standards for algorithmic scheduling systems, requiring vendors to explain automated shift allocation logic to workers and regulators. Industrial consequence includes elevated R&D spending on explainable AI frameworks and audit trail capabilities. Healthcare and retail sectors in Germany and France face the steepest compliance timelines, with procurement teams now requiring algorithmic transparency certifications before contract award.
Subscription pricing for workforce planning modules is displacing perpetual license models as mid-market buyers prioritize operational expenditure treatment. Value-added resellers and systems integrators capture margin by bundling implementation services with recurring software fees. This shift concentrates most visibly among United States-based logistics operators and regional retail chains seeking predictable cost structures without capital approval cycles.
Labor Management Software Market Segmentation
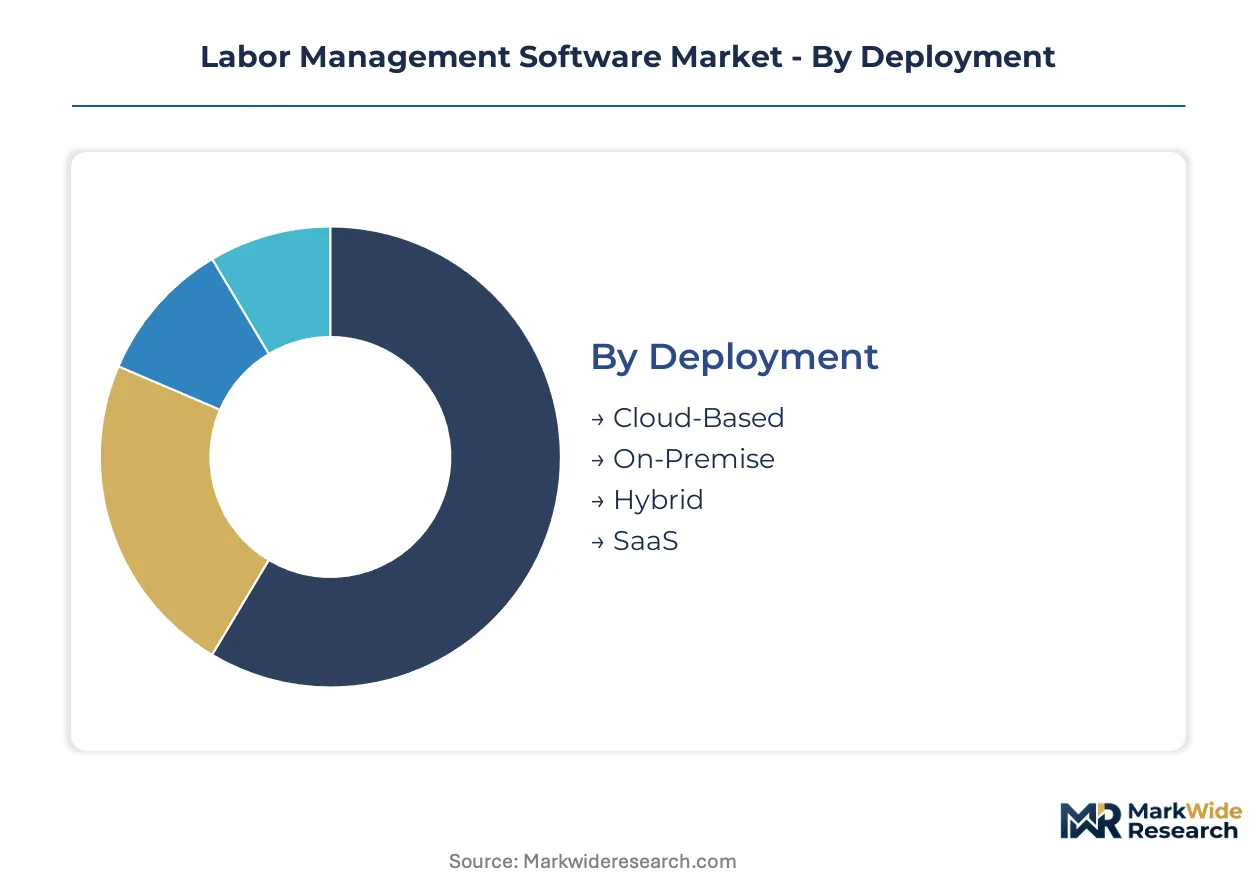
Deployment architecture determines regulatory exposure and integration complexity across labor management implementations. End-user concentration and functionality depth shape vendor pricing power and contract duration.
Deployment:
Certification burdens concentrate in cloud-based and SaaS segments, where SOC 2 Type II and ISO 27001 compliance satisfy FDA audit requirements for pharmaceutical time-tracking accuracy. On-premise installations in defense and aerospace face CMMC and ITAR constraints that hybrid architectures must bridge.
- Cloud-Based:Multi-tenant architectures process time-clock feeds and task completion signals through distributed data centers, eliminating server maintenance overhead for manufacturers and retailers. Demand concentrates in United States logistics hubs where real-time labor orchestration requires sub-second latency.
- SaaS:Subscription models bundle workforce planning modules with automatic compliance updates for EU AI Act algorithmic transparency mandates. Mid-market retail chains in Germany and France prioritize operational expenditure treatment over capital approval cycles.
- On-Premise:Legacy ERP installations in aerospace and defense require expensive middleware for cloud-native platform connectivity.
- Hybrid:Edge computing nodes at warehouse floors synchronize with central compliance repositories to satisfy GDPR biometric data retention limits.
Cloud-Based sits at the top of the volume ranking, with SaaS climbing the fastest.
End User:
Cost tier stratification separates enterprise manufacturing deployments from mid-market retail implementations, with logistics operators occupying the premium middle ground for real-time orchestration capabilities.
- Logistics:Third-party providers deploy edge computing infrastructure to support sub-second productivity variance calculations across automated material handling systems. United States distribution networks drive contract value through seasonal surge capacity requirements.
- Manufacturing:FDA scrutiny of pharmaceutical time-tracking accuracy elevates biometric clock-in adoption, with fingerprint and facial recognition systems capturing premium pricing.
- Retail:Predictive staffing modules manage holiday surge capacity across distribution networks, with algorithmic scheduling replacing manual shift boards.
- Healthcare:Fatigue-rule adherence tools command premium pricing for shift limit and rest-period calculations in hospital systems.
Logistics commands the highest contract values, with Healthcare expanding most quickly on compliance-driven procurement.
Functionality:
Application maturity varies sharply, with workforce planning representing the newest algorithmic frontier while time tracking consolidates around biometric hardware integration.
- Workforce Planning:Algorithmic scheduling modules replace manual shift boards through predictive models for complex multi-skill environments. EU AI Act transparency mandates force re-engineering of automated shift allocation logic in German and French retail operations.
- Compliance Management:Modules linking labor hour patterns to OSHA injury rates capture premium pricing in warehousing verticals.
- Time Tracking:Biometric clock-in systems satisfy FDA pharmaceutical accuracy standards while navigating GDPR retention constraints.
- Analytics:Embedded HANA architectures unify labor metrics with supply chain execution for variance reporting at sub-second intervals.
Time Tracking holds the largest installed base, with Workforce Planning gaining share fastest on AI Act replacement cycles.
Industry Vertical:
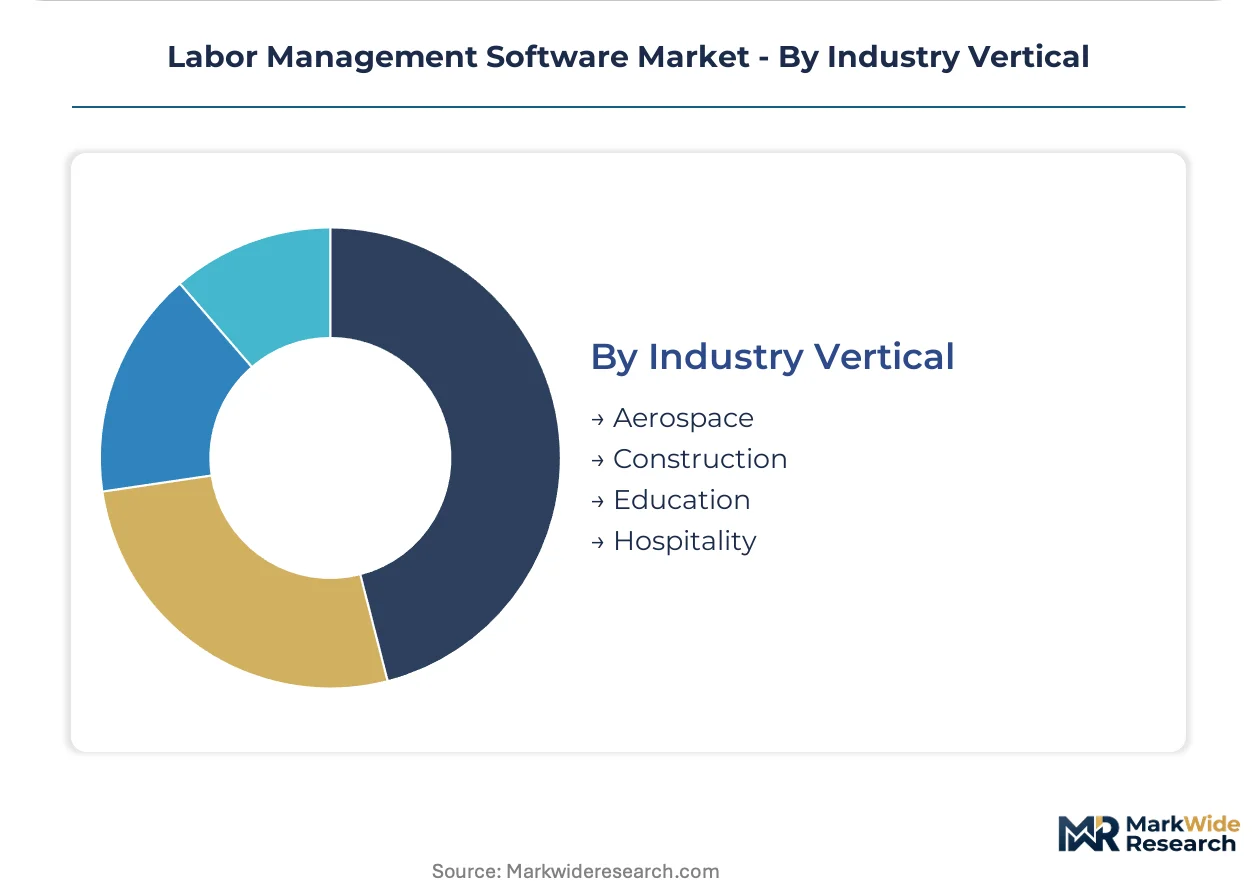
Customer type concentration shapes procurement patterns, with aerospace and construction representing capital-intensive long-cycle buyers versus hospitality's fragmented mid-market.
- Aerospace:Fatigue-rule adherence carries liability exposure that drives premium compliance tool procurement for shift limit management. Defense contractors face ITAR and CMMC constraints that complicate cloud migration.
- Construction:Project-based staffing volatility creates demand for mobile time-tracking across dispersed job sites.
- Hospitality:Seasonal workforce fluctuations drive adoption of predictive staffing modules for event-driven capacity.
- Education:Union-negotiated scheduling rules require configurable compliance engines for substitute teacher allocation.
Aerospace leads vertical pricing premiums, with Construction accelerating fastest on mobile workforce expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany operate on divergent procurement timelines, with American logistics hubs prioritizing real-time edge computing while German manufacturers navigate EU AI Act compliance deadlines. Cloud contract values concentrate in North American distribution networks. European procurement teams now mandate algorithmic transparency certifications before award.
United States
Third-party logistics providers drive cloud-based deployment across automated distribution networks in Memphis and Louisville. OSHA recordkeeping mandates for injury-correlated labor hours elevate compliance module demand in warehousing verticals. Chicago and Dallas-Fort Worth logistics clusters deploy edge computing nodes for sub-second productivity variance calculations.
Germany
Automotive manufacturers in Stuttgart and Wolfsburg re-engineer workforce planning modules for EU AI Act algorithmic transparency requirements. The country's national labor regulator enforces strict documentation standards for automated shift allocation systems. Bavarian industrial clusters prioritize hybrid architectures bridging on-premise ERP with cloud-native compliance repositories.
France
Retail chains in Paris and Lyon accelerate predictive staffing module adoption for seasonal surge capacity management. CNIL biometric data retention limits complicate fingerprint clock-in deployments across multi-national operations. Auvergne-Rhône-Alpes manufacturing hubs integrate fatigue-rule adherence tools for aerospace subcontractor compliance.
United Kingdom
Post-Brexit regulatory divergence creates procurement complexity for workforce platforms serving EU and domestic operations simultaneously. The Information Commissioner's Office enforces GDPR constraints on facial recognition template storage in London distribution centers. Midlands logistics corridors invest in API-first architectures linking labor data with supply chain execution platforms.
Japan
Automotive and electronics manufacturers in Toyota City and Osaka deploy embedded analytics unifying labor metrics with production execution systems. METI guidelines on workplace digitization accelerate biometric time-clock standardization. Kanto region distribution networks adopt subscription workforce planning models to avoid capital approval cycles.
Labor Management Software Market Competitive Landscape
Top-tier vendors anchor full-suite enterprise platforms, while mid-market specialists compete through API-first integration depth. The vendor base stratifies around payroll-to-workforce data backbones, embedded analytics engines, and vertical-specific compliance modules. Strategic archetypes include HCM suite extenders, best-of-breed workforce optimizers, and logistics-focused real-time orchestrators. Dominant competitive moves encompass M&A for data backbone consolidation and strategic partnerships for edge computing infrastructure.
Within the payroll-anchored tier, ADP and UKG occupy positions exemplifying mid-market expansion through workforce data integration. SAP and Oracle sit within the enterprise analytics tier, representing embedded HANA and cloud infrastructure approaches to labor metric unification. Blue Yonder and Manhattan Associates anchor the logistics-specialist vector, exemplifying real-time orchestration capabilities for automated material handling environments.
| Leading Market Players |
|---|
| ADP |
| SAP |
| UKG |
| Oracle |
| Workday |
| Blue Yonder |
| Kronos |
| Manhattan Associates |
| Infor |
| Others |
Value Network & Pricing Analysis
EU AI Act algorithmic transparency mandates gate qualified supply and premium-tier pricing access, as vendors must re-engineer workforce planning modules to meet documentation standards before serving German automotive manufacturers or French retail chains. Buyers seeking real-time labor orchestration with embedded compliance engines face extended procurement cycles and elevated cost structures compared to commodity time-tracking implementations.
Pricing Analysis
Capacity additions in United States logistics hubs are reshaping price floors for cloud-native workforce platforms as third-party providers scale edge computing infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates full-suite enterprise deployments with embedded HANA analytics from mid-market SaaS subscriptions and basic time-tracking point solutions. Price differentiation centers on certification grade for FDA pharmaceutical accuracy and EU GDPR biometric compliance, with aerospace and healthcare buyers showing least price sensitivity due to liability exposure. Cost compression in standard-tier subscriptions is intensifying because native HCM suite extensions substitute standalone labor optimization tools.
Supply Chain Analysis
Freight cost volatility across transatlantic data center interconnects shapes vendor deployment architecture decisions for European manufacturers seeking hybrid edge-to-cloud labor orchestration. Software development concentrates in the United States, Germany, and India, with cloud infrastructure provisioning drawing from hyperscaler nodes in Virginia, Frankfurt, and Mumbai. Raw material dependencies span semiconductor chips for biometric time-clock hardware, server-grade memory for real-time analytics engines, and specialized sensors for task completion tracking. Single-source vulnerability in edge computing node manufacturing creates procurement risk for logistics operators requiring sub-second latency. Distribution runs through value-added resellers and systems integrators bundling implementation services with recurring software fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement teams shift demand toward algorithmic transparency certifications and fatigue-rule compliance engines that command premium pricing in aerospace and hospital systems.
For Market Incumbents: Anticipate replacement cycles triggered by EU AI Act compliance deadlines in German and French manufacturing operations. Consolidate data backbone capabilities through payroll-to-workforce integration depth to defend against native HCM suite substitution. Prioritize R&D investment in explainable AI frameworks for automated shift allocation logic to maintain contract renewal rates with European retail chains. For New Entrants and Emerging Players: API-first middleware architectures offer technology-first wedge positioning between legacy on-premise ERP installations and cloud-native workforce platforms in aerospace and defense verticals. Target mid-market construction operators with mobile time-tracking solutions for dispersed job site deployment. Pursue white-label partnerships with regional systems integrators serving hospitality and education sectors. For Investors and Strategic Acquirers: Roll-up economics work for vertical-specific compliance module specialists because multi-jurisdiction regulatory fragmentation prevents full-suite vendors from capturing niche fatigue-rule and OSHA injury-correlation functionality. Focus acquisition screening on healthcare and aerospace labor management tools with embedded shift-limit calculation engines. Watch for inflection signals in German automotive procurement requiring algorithmic transparency documentation as mandatory contract terms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies labor metrics with SAP HANA supply chain execution for variance reporting. |
| Acquisition of Specialist Firm | Consolidates fatigue-rule compliance capabilities for aerospace contractor procurement. |
| Strategic Partnership | Links edge computing infrastructure with automated material handling system vendors. |
| Geographic Expansion | Establishes EU AI Act certification pathways for German automotive manufacturer contracts. |
| Product Launch | Introduces predictive staffing modules for seasonal retail surge capacity management. |
Research Methodology
Bottom-up workforce planning modeling reconciled against top-down cloud deployment tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists combine with secondary validation from SEC filings, hyperscaler capex disclosures, EU regulatory filings, and hospital procurement databases. Triangulation between demand-side adoption patterns and supply-side vendor capacity announcements ensures cross-verification of market sizing assumptions.
Input-output matrices map deployment architecture choices to end-user vertical requirements across the projection horizon. Segmentation dimensions span deployment model, organization size, functionality depth, integration complexity, and regional regulatory cluster. CAGRs derive from fitted growth curves against historical contract value trajectories, with forecast inputs incorporating EU AI Act compliance timeline acceleration and OSHA recordkeeping mandate expansion.
The model holds under steady regulatory enforcement timelines; deviation in EU member state implementation speed or FDA pharmaceutical audit intensity would shift replacement cycle assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Landscape Software Market
Software & Services
Intellectual Property Software Market
Software & Services
Africa Sports Management Software Market
Software & Services
Product Analytics Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Global Technical Illustration Software Market
Software & Services
United Kingdom IT Services Market
Software & Services
Scanning and Migration Software Market
Software & Services
Document Capture Software Market
Software & Services
Automotive Customization Software Market
Software & Services
RFP Software Market
Software & Services
Global Intellectual Property Management Software Market
Software & Services
Team Collaboration Tools Market
Software & Services
Commerce As a Service (Caas) Market
Software & Services
Movie Editing Software Market
Software & Services
Global Claims Processing Software Market