
 Content Creation Software Market | 2026-2036
Content Creation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Content Creation Software Market Analysis
Platform licensing revenue is tilting away from perpetual desktop licenses toward recurring cloud subscriptions. Adobe leverages its Creative Cloud ecosystem to sustain high retention among professional video editors and motion designers. Canva anchors the mid-market with template-driven graphic design tools that compete aggressively on price against legacy suites. Microsoft extends its position through Teams-integrated collaboration features that occupy the corporate productivity layer.
Content creation software encompasses applications for producing, editing, and distributing digital media across video, image, text, and animation formats, typically supporting timeline-based editing, layer compositing, and codec rendering at resolutions up to 8K. These tools serve commercial purposes ranging from broadcast television production to social media marketing and e-learning module development. Video editing commands the largest revenue pool among product types due to streaming platform content budgets, while cloud-based deployment grows fastest as remote production workflows displace on-premises render farms. Freelancer adoption of template-rich graphic design platforms concentrates margin pools at the entry-level tier, whereas enterprise corporations drive premium pricing for collaboration tools with role-based access controls and brand governance features.
The EU AI Act and GDPR impose transparency and data-processing obligations on generative features within European-deployed tools, compelling vendors to document training data provenance and enable opt-out mechanisms. The FCC in the United States monitors broadband infrastructure quality that underpins cloud-based rendering and real-time collaboration performance. China's SAMR and GB standards govern content filtering capabilities required for software distributed through domestic app stores. Stakeholders must monitor how divergent AI disclosure mandates across jurisdictions fragment feature parity and inflate compliance engineering costs.
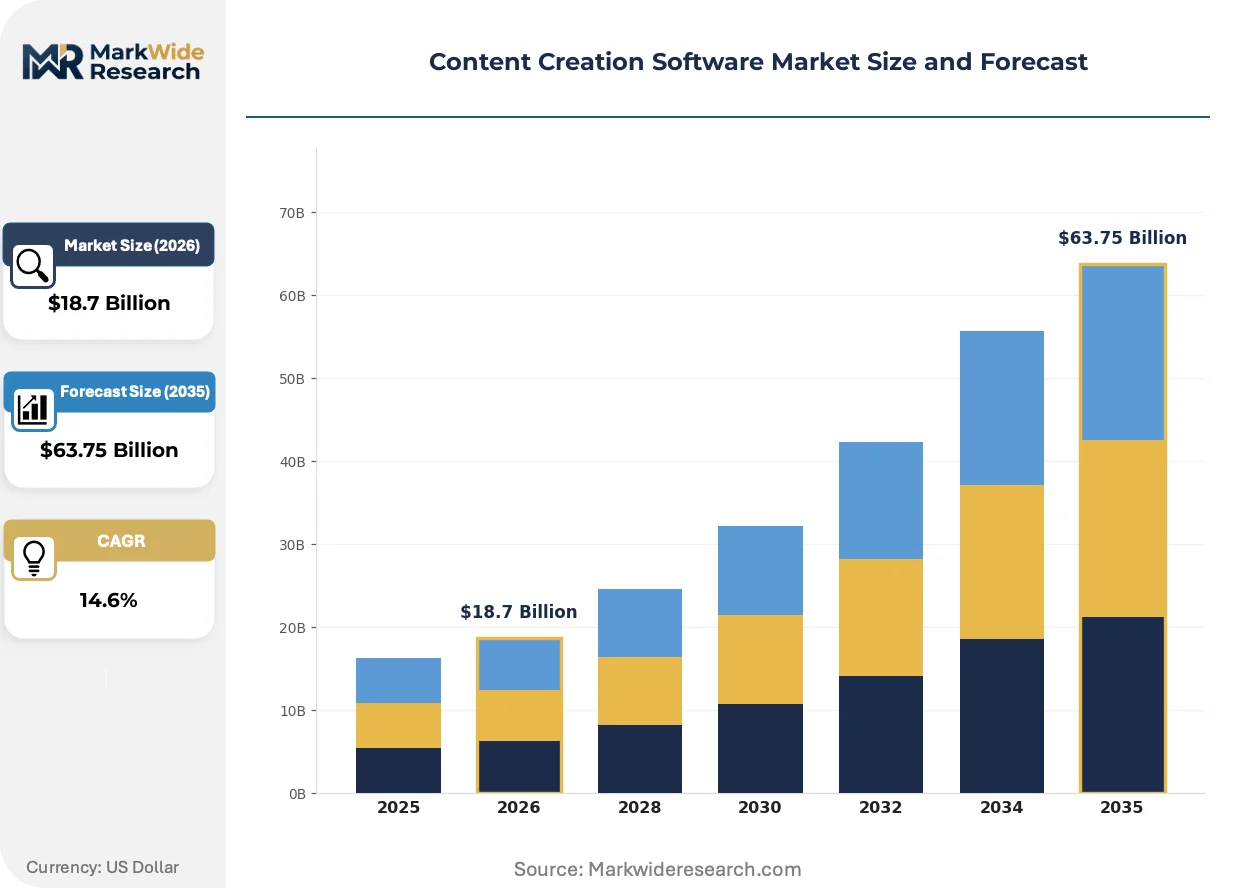
Market Dynamics
The migration from perpetual desktop licenses to cloud-native subscription models constitutes the central structural force reshaping competitive economics and customer lifetime value calculations across the content creation software sector.
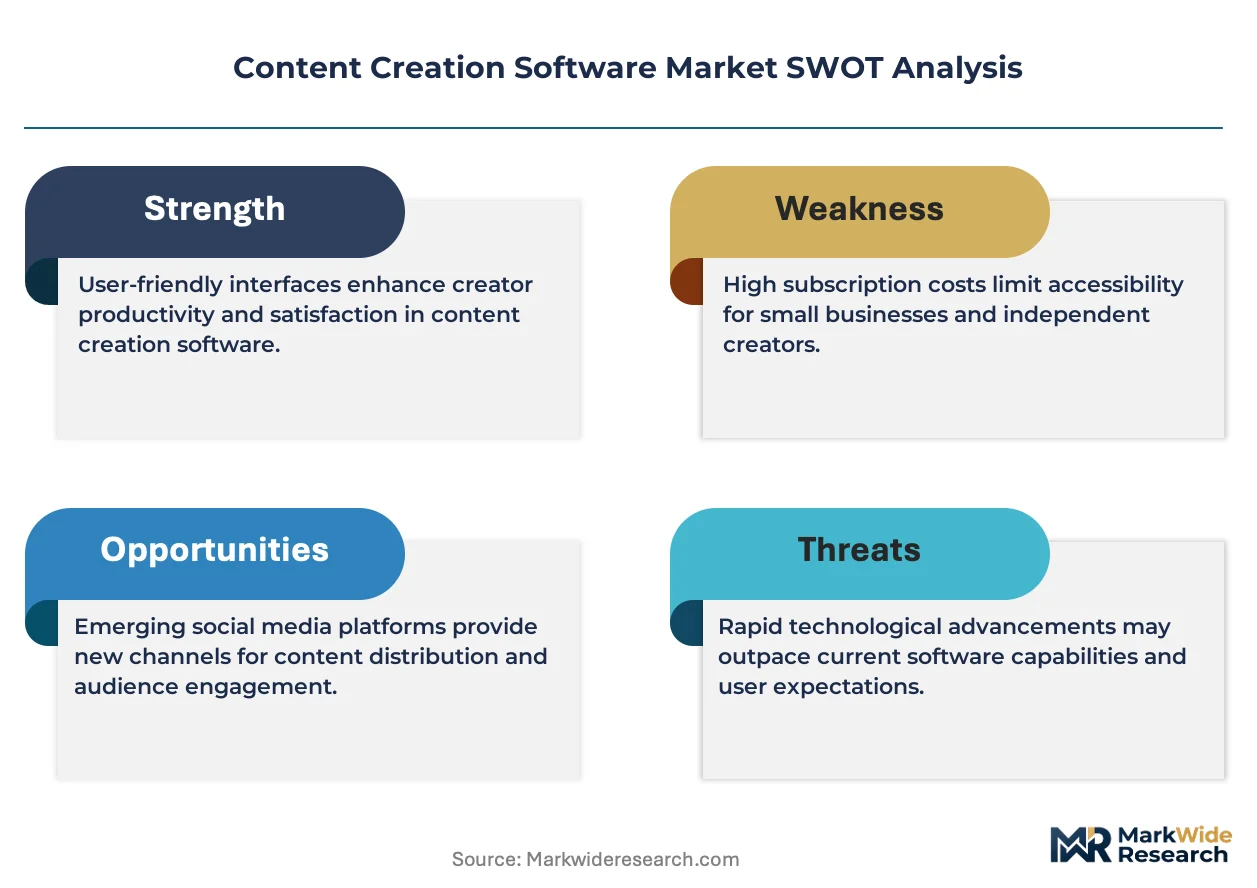
Growth Catalysts
- EU AI Act transparency mandates:European publishers now require documented training data provenance and opt-out mechanisms, creating compliance-driven upgrade cycles for vendors with robust governance tooling.
- Streaming platform content budgets:Netflix, Disney+, and Amazon Prime Video sustain demand for professional video editing suites capable of 8K rendering and real-time collaboration.
- Remote production workflows:Cloud-based render farms displace on-premises infrastructure, enabling distributed teams across Los Angeles, London, and Mumbai to collaborate without geographic constraint.
Market Restraints
- Compute cost volatility:GPU and cloud storage pricing fluctuations squeeze margins for vendors offering unlimited cloud rendering in fixed-price subscriptions.
- Regulatory fragmentation:Divergent AI disclosure mandates across the EU, China, and the United States inflate engineering costs and fragment feature parity across regional deployments.
- Template commoditization:Free and low-cost graphic design platforms erode entry-level pricing power for established suites targeting freelancer segments.
Strategic Opportunities
- Enterprise brand governance:Role-based access controls and centralized asset libraries address Fortune 500 marketing teams managing distributed creator networks.
- India creator-economy infrastructure:YouTube and Instagram monetization growth drives demand for localized, mobile-first editing tools among regional content producers.
- ISO 27001 certification tailwinds:Information security management standards unlock procurement pathways into regulated industries including financial services and healthcare communications.
Industry Challenges
- Motion design talent scarcity:Shortages of skilled After Effects and Cinema 4D operators constrain enterprise team scaling and project velocity.
- Legacy codec integration:Broadcast television archives in proprietary formats require expensive transcoding pipelines that complicate cloud migration roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Creation Software Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Editing, Graphic Design, Blogging, Animation End User: Freelancers, Agencies, Corporations, Educational Institutions Deployment: Cloud-Based, On-Premises, Hybrid, Local Software Feature: Collaboration Tools, Templates, SEO Optimization, Social Media Integration |
| Companies Covered | Adobe, Microsoft, Canva, Apple, Corel Corporation, Autodesk, Wix, Acrolinx GmbH, Quark Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Creation Software Market Emerging Trajectories
Generative AI capabilities are compressing production timelines while regulatory frameworks force architectural redesigns, and procurement patterns favor integrated collaboration ecosystems over point solutions.
Neural rendering engines are collapsing the distinction between real-time preview and final output quality. Broadcast post-production houses in Burbank and London now deploy AI-assisted rotoscoping and inpainting that previously required frame-by-frame manual correction. This compression of the VFX pipeline enables smaller studios to bid on theatrical-grade projects without expanding headcount proportionally.
The EU AI Act's risk classification system for generative features imposes documentation burdens on training data sourcing and model explainability. Vendors serving European publishers must engineer audit trails and user opt-out mechanisms that add months to product release cycles. Enterprise marketing teams in Germany and France now prioritize vendors with pre-certified compliance frameworks over feature-rich alternatives lacking regulatory clearance.
Corporate buyers increasingly bundle content creation procurement within Microsoft Teams or Slack ecosystem contracts, displacing standalone software evaluations. Marketing operations leaders at technology and financial services firms negotiate enterprise-wide seats that integrate project management, review workflows, and asset distribution. This concentration of purchasing authority within IT procurement functions favors vendors with deep platform integration over best-of-breed specialists.
Content Creation Software Market Segmentation
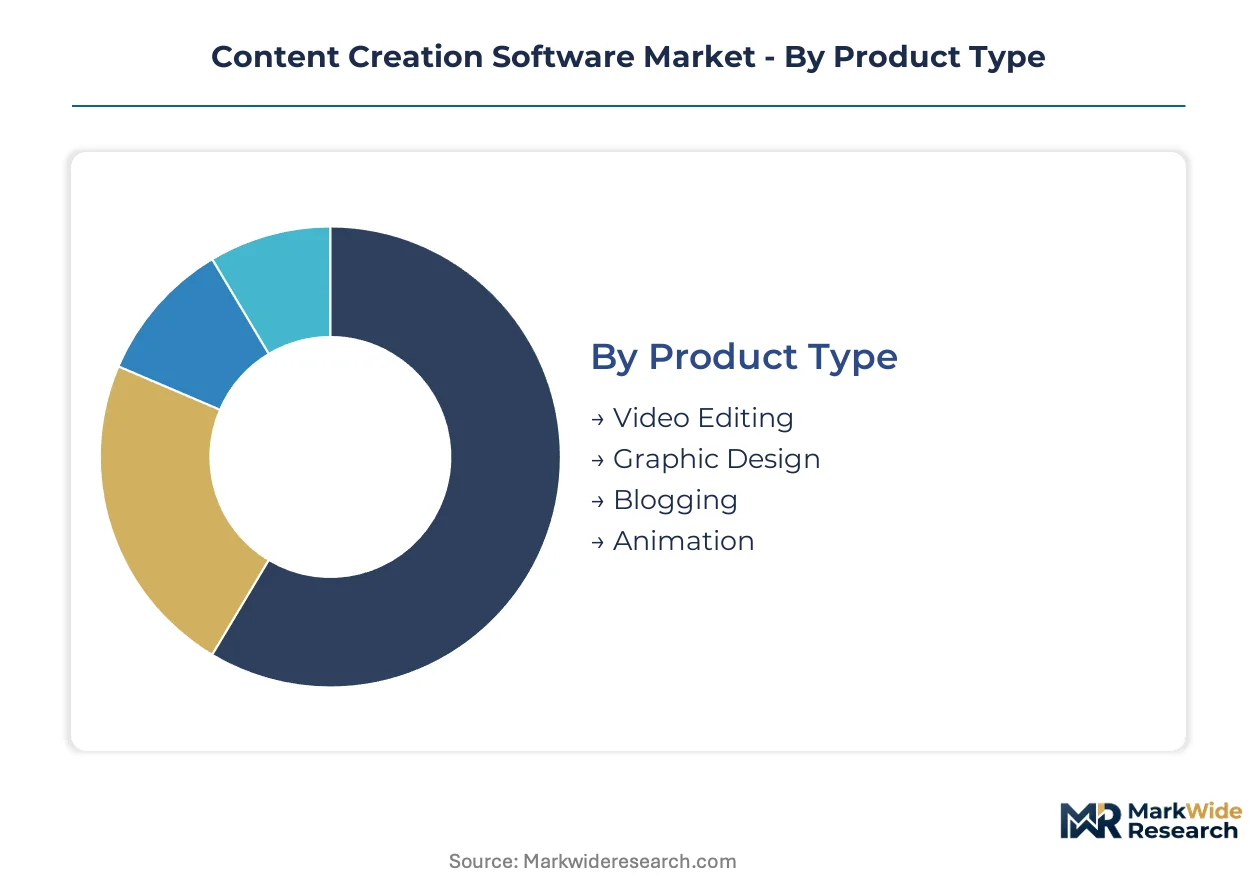
Segmentation in content creation software reveals divergent margin structures across deployment modes and user sophistication levels. Cloud-native architectures command recurring revenue premiums while on-premises installations retain price inelasticity among broadcast compliance environments. Template-driven entry tiers compress pricing power for graphic design incumbents serving freelancer segments.
Product Type:
After-sales service intensity varies sharply across product categories, with video editing suites demanding continuous codec support and render farm troubleshooting while blogging platforms require minimal technical intervention.
- Video Editing:Timeline-based applications supporting 8K rendering, multi-camera synchronization, and real-time collaboration dominate enterprise procurement. Netflix and Disney+ content budgets in Los Angeles and London sustain premium pricing for professional suites with GPU-accelerated encoding pipelines.
- Graphic Design:Layer-compositing tools with template libraries anchor the mid-market accessibility tier. Canva's freemium model in the United States and Australia has compressed entry-level pricing, forcing Adobe to defend Creative Cloud retention through ecosystem lock-in rather than standalone feature superiority.
- Blogging:Text-first platforms with markdown editors and SEO metadata automation serve solo publishers and content marketing teams.
- Animation:Keyframe and motion graphics applications including 2D vector animation and 3D rigging tools for character animation pipelines.
By volume, graphic design leads due to template-driven freelancer adoption. By growth pace, video editing is ahead on streaming platform infrastructure investment.
End User:
Cost tier stratification separates enterprise procurement with centralized IT governance from self-serve freelancer subscriptions with minimal sales touch.
- Freelancers:Individual creators purchasing single-seat subscriptions through app stores or direct-to-consumer channels. YouTube and Instagram monetization growth in India and Brazil drives mobile-first editing tool demand among this price-sensitive cohort.
- Agencies:Multi-seat creative shops requiring client review workflows and brand asset libraries. Project-based billing models in London and New York creative districts favor month-to-month subscription flexibility over annual enterprise commitments.
- Corporations:Fortune 500 marketing operations with role-based access controls and ISO 27001 compliance requirements. Teams-integrated procurement in the United States and Germany increasingly bundles content creation within broader Microsoft ecosystem contracts.
- Educational Institutions:Volume-licensed campus deployments with student onboarding and curriculum integration needs.
By volume, freelancers lead through mass-market template platform adoption. By growth pace, corporations are ahead on brand governance and compliance tooling investment.
Deployment:
Application criticality determines infrastructure choice, with real-time broadcast workflows tolerating no latency while asynchronous social content production embraces full cloud portability.
- Cloud-Based:Browser-native or desktop-synced applications with unlimited cloud storage and distributed render queues. Remote production teams across Los Angeles, London, and Mumbai collaborate without geographic constraint on the same project files.
- On-Premises:Local server installations with air-gapped security for broadcast television archives and classified government communications. Proprietary codec transcoding pipelines in legacy Burbank post-production houses complicate migration roadmaps.
- Hybrid:Split architectures with local editing workstations and cloud-based review or asset distribution layers.
- Local Software:Perpetual-license desktop applications with no network dependency for offline production environments.
By volume, cloud-based leads on remote workflow normalization. By expansion trajectory, hybrid is gaining share fastest as enterprises balance latency sensitivity with collaboration demands.
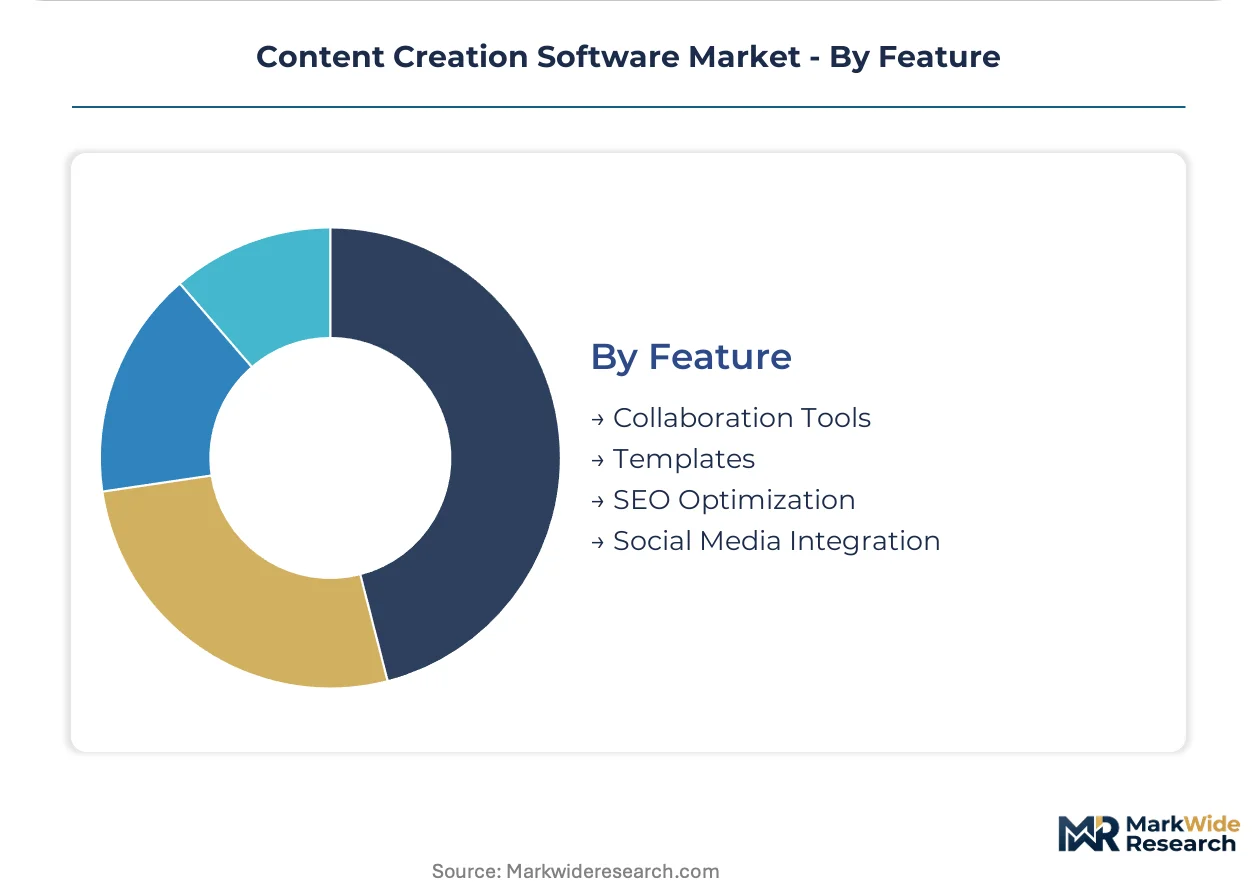
Feature:
Customer maturity separates basic template users from sophisticated teams requiring governance and distribution integration.
- Collaboration Tools:Real-time co-editing, version control, and role-based approval workflows. Slack and Microsoft Teams integration now functions as a procurement gate for enterprise marketing operations in the United States and Germany.
- Templates:Pre-designed layouts for social posts, presentations, and video intros with drag-and-drop customization. Free platform proliferation has commoditized this feature tier, eroding pricing power for paid alternatives.
- SEO Optimization:Keyword research integration, readability scoring, and search ranking analytics for content marketing teams.
- Social Media Integration:Direct publishing APIs, scheduling queues, and performance analytics for multi-platform distribution.
By volume, templates lead on entry-tier accessibility. By growth pace, collaboration tools are ahead on enterprise distributed team requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Brazil exhibit acute price sensitivity toward template-driven graphic design tools, while enterprise procurement teams in Germany and the United States demonstrate minimal elasticity for compliance-certified collaboration suites. This demand bifurcation shapes divergent go-to-market architectures across national markets.
United States
Streaming platform content budgets from Netflix, Disney+, and Amazon Prime Video sustain premium demand for 8K video editing suites with real-time collaboration. FCC broadband infrastructure monitoring underpins cloud-based rendering performance requirements. Post-production clusters in Los Angeles and New York anchor professional tool adoption among broadcast and theatrical production houses.
Germany
Fortune 500 marketing operations prioritize ISO 27001-certified vendors with pre-built GDPR and EU AI Act compliance frameworks. The national data protection authority enforces strict transparency mandates on generative AI features. Berlin and Munich host dense concentrations of enterprise SaaS procurement teams bundling content creation within Microsoft ecosystem contracts.
India
YouTube and Instagram monetization growth drives mobile-first editing tool demand among price-sensitive individual creators. The central bank's digital payment infrastructure supports micro-transaction subscription models. Mumbai and Bengaluru creator-economy clusters favor localized, low-cost template platforms over premium international suites.
United Kingdom
London creative agencies require month-to-month subscription flexibility aligned with project-based billing models. The Information Commissioner's Office enforces GDPR-aligned data processing standards for cloud-deployed tools. Soho post-production houses maintain hybrid workflows balancing latency-sensitive local editing with cloud-based client review layers.
China
Domestic short-video platform ecosystems sustain demand for localized editing tools with government-mandated content filtering. SAMR and GB standards govern distribution through domestic app stores. Beijing and Shenzhen technology corridors concentrate development of AI-assisted production tools with built-in compliance architectures.
Content Creation Software Market Vendor Landscape
Capability concentration sits with specialized creative tool developers; scale advantage sits with platform ecosystem incumbents. The market structures around three tiers: integrated creative suites commanding ecosystem lock-in, mid-market template platforms competing on accessibility, and enterprise collaboration tools bundling within productivity contracts. Dominant competitive moves include strategic partnerships with cloud infrastructure providers and portfolio diversification into adjacent workflow automation segments.
Within the integrated creative suite tier, Adobe and Autodesk exemplify vendors defending position through deep tool interoperability and professional user retention. Microsoft occupies a distinct position anchoring enterprise procurement through Teams-embedded collaboration features. Canva represents the mid-market accessibility archetype, compressing entry-level pricing through template-driven design democratization. These three anchors illustrate divergent paths: ecosystem depth versus platform integration versus freemium scale.
| Leading Market Players |
|---|
| Adobe |
| Microsoft |
| Canva |
| Apple |
| Corel Corporation |
| Autodesk |
| Wix |
| Acrolinx GmbH |
| Quark Software |
| Others |
Supply Flow & Price Mechanics
Bengaluru's cloud infrastructure cluster anchors GPU compute capacity for real-time rendering pipelines, concentrating pricing power among hyperscaler-backed vendors while squeezing margins for independent software providers absorbing spot-price volatility.
Pricing Analysis
Extended service contracts and tiered support subscriptions drive lifetime value more than initial license fees. Three-tier pricing structure across premium, standard, and economy levels segments enterprise buyers with ISO 27001 certification needs from price-sensitive freelancers. Cost compression in the entry tier intensifies because Canva's freemium model and open-source alternatives erode standalone tool pricing. Freelancers in India and Brazil exhibit acute price sensitivity, whereas Fortune 500 marketing operations in Germany and the United States demonstrate minimal elasticity for compliance-certified collaboration suites.
Supply Chain Analysis
Upstream GPU silicon and cloud storage feedstock draws from Taiwan Semiconductor Manufacturing, South Korean memory foundries, and United States hyperscaler data centers. NVIDIA's CUDA ecosystem and AWS Graviton instances constitute critical component dependencies. Single-source vulnerability around NVIDIA's AI training chips creates procurement bottlenecks for vendors building generative features. Distribution runs through direct-to-enterprise sales teams, app store marketplaces, and Microsoft Teams ecosystem bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Fortune 500 procurement teams bundle content creation within Microsoft ecosystem contracts, reducing standalone software evaluations and compressing vendor negotiation leverage.
For Market Incumbents: Harden ecosystem lock-in through deeper Creative Cloud interoperability and pre-certified GDPR and EU AI Act compliance frameworks. Cloud infrastructure partnerships with AWS and Azure reduce compute cost exposure. Motion design talent scarcity threatens enterprise team scaling velocity. For New Entrants and Emerging Players: India's mobile-first creator economy offers underpenetrated white space for localized, low-cost template platforms with micro-transaction subscription models. Brazil's Instagram monetization growth creates parallel entry opportunity. Partner with domestic payment infrastructure providers to bypass credit-card friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among collaboration-tool vendors with Teams-integrated procurement pathways and ISO 27001 certification tailwinds. Long-term viability rests on compliance engineering differentiation rather than feature velocity. Watch for EU AI Act enforcement actions as inflection indicator for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Teams embedding unlocks Fortune 500 procurement pathways and reduces customer acquisition costs. |
| Compliance Certification | Pre-built GDPR and EU AI Act frameworks accelerate German enterprise sales cycles against feature-rich competitors. |
| Geographic Expansion | Localized mobile-first tools capture India's YouTube and Instagram monetization growth among price-sensitive creators. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure secure GPU capacity allocation and reduce rendering cost volatility. |
| Acquisition of Specialist Firm | Motion design talent pools in Burbank and London address scarcity constraining enterprise team scaling. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, App Annie mobile analytics, and EU regulatory databases. Primary interviews engaged CTOs at streaming platforms, IT procurement officers at Fortune 500 marketing operations, platform engineers at creative tool vendors, and channel partners distributing through Microsoft marketplace. Bottom-up sizing of subscriber bases and top-down triangulation against reported revenue segments validate volume estimates.
Forecast inputs include deployment model transitions, organization size adoption curves, vertical integration complexity, and regional regulatory enforcement patterns across the analysis window. Modeled segmentation spans product type, end user tier, deployment architecture, and feature sophistication. CAGRs derive from trend extrapolation of cloud migration velocity and generative AI capability diffusion. GPU cost trajectories and broadband infrastructure investment serve as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem bundling moves by Microsoft or Adobe would shift outcomes beyond modeled ranges. Regulatory fragmentation across the EU, China, and United States introduces revision risk for compliance engineering cost assumptions. Cross-checking against hyperscaler earnings call commentary on creative workload growth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Multiexperience Development Platforms Market
Software & Services
Deck Software Market
Software & Services
Global Diagram Software Market
Software & Services
Applicant Tracking System (ATS) Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
Russian IT Software and Services Market
Software & Services
Classified Platform Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Global Gamification Software Market
Software & Services
Global IVR Software Market
Software & Services
Output Management Software Market
Software & Services
Self-Storage Software Market
Software & Services
Global Data Mining Software Market
Software & Services
Global User Interface Service Market
Software & Services
Japan IT Services Market
Software & Services
Solar Rooftop Design Software Market