
 Construction Project Management Software Market | 2026-2036
Construction Project Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Project Management Software Market Analysis
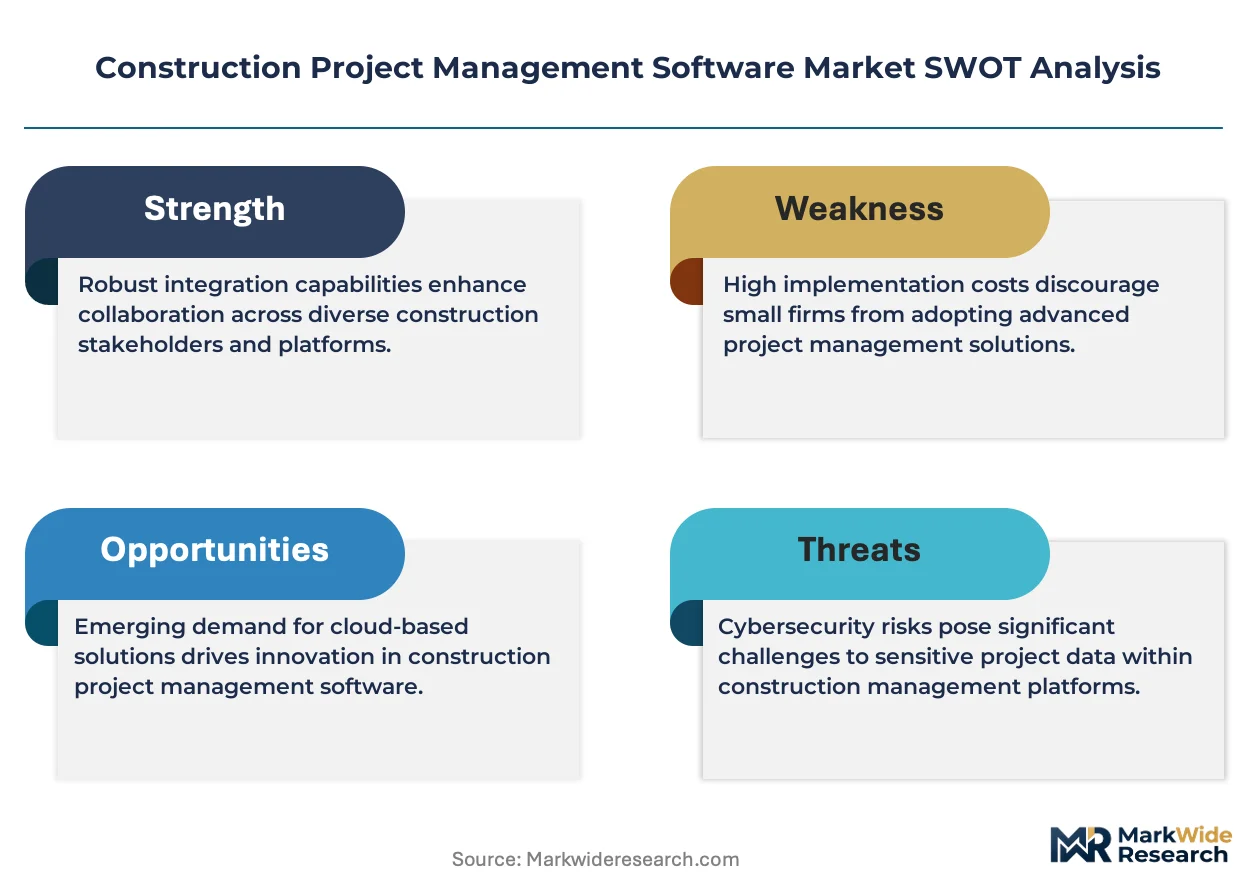
The gap between premium enterprise suites and stripped-down commodity tools is realigning how vendors structure pricing and feature depth. Procore leverages its ecosystem breadth to anchor mid-market and large contractor accounts. Autodesk Construction Cloud competes through deep interoperability with design authoring tools. Buildertrend specializes in residential and specialty trade workflows, occupying a defensible niche below the commercial tier.
Construction project management software coordinates scheduling, resource allocation, budget control, and document workflows across distributed job sites through centralized digital platforms. Core systems integrate Gantt-based scheduling engines, real-time cost ledger synchronization, and RFI/submittal tracking to compress project delivery timelines and reduce variance from baseline budgets. Cloud-based deployment leads adoption momentum among multi-site contractors seeking zero-install field access, while collaboration platforms capture expanding margin pools as stakeholder networks extend beyond single-firm boundaries. Budgeting tools sustain steady replacement cycles among public works agencies with strict appropriation compliance requirements.
OSHA recordkeeping mandates, EPA stormwater construction permits, and ISO 19650 BIM standards collectively elevate software requirements for audit trails and environmental documentation. FDA-regulated pharmaceutical construction and ESG disclosure frameworks under CSRD further fragment compliance templates across jurisdictions. Stakeholders must monitor which regulatory layers their project portfolios trigger before committing to platform architectures.
Market Dynamics
Cloud-native deployment architectures are compressing implementation timelines from months to weeks, forcing incumbent vendors to restructure professional services revenue models around subscription retention rather than upfront configuration fees.
Growth Catalysts
- OSHA recordkeeping mandates:US federal requirements for digitized incident documentation are compelling mid-sized contractors to replace paper-based field reporting with integrated safety modules.
- Green building certification workflows:LEED and BREEAM documentation automation is electrifying demand among commercial developers seeking streamlined credit tracking across multi-phase projects.
- Australia infrastructure modernization:Federal digitization grants for state-level transport agencies are accelerating platform procurement for rail and highway portfolios.
Market Restraints
- Input cost volatility in cloud infrastructure:AWS and Azure pricing fluctuations are squeezing vendor gross margins and forcing mid-tier providers toward multi-cloud arbitrage strategies.
- Technical limitation in offline synchronization:Remote job sites with intermittent cellular coverage experience data latency that undermines real-time dashboard reliability for field supervisors.
- Regulatory friction from fragmented data residency laws:Germany's BSI IT-Grundschutz requirements and Australia's OAIC guidelines create architectural complexity for vendors pursuing cross-border deployments.
Strategic Opportunities
- Underpenetrated specialty trade segment:Mechanical and electrical subcontractors in the United States remain underserved by vertically focused tools optimized for their procurement-to-closeout workflows.
- Technology convergence of BIM and IoT sensor streams:Real-time structural health monitoring integration is opening premium pricing tiers for bridge and tunnel operators.
- Distribution innovation through construction equipment OEM channels:Caterpillar and Komatsu dealer networks represent untapped software resale infrastructure for penetrating asset-heavy contractor segments.
Industry Challenges
- Integration complexity with legacy ERP systems:SAP and Oracle on-premise instances at major general contractors require costly middleware development for bidirectional cost ledger synchronization.
- Talent gap in construction-technology hybrid roles:Project managers with simultaneous field experience and platform administration certification command compensation premiums that strain implementation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Project Management Software Market |
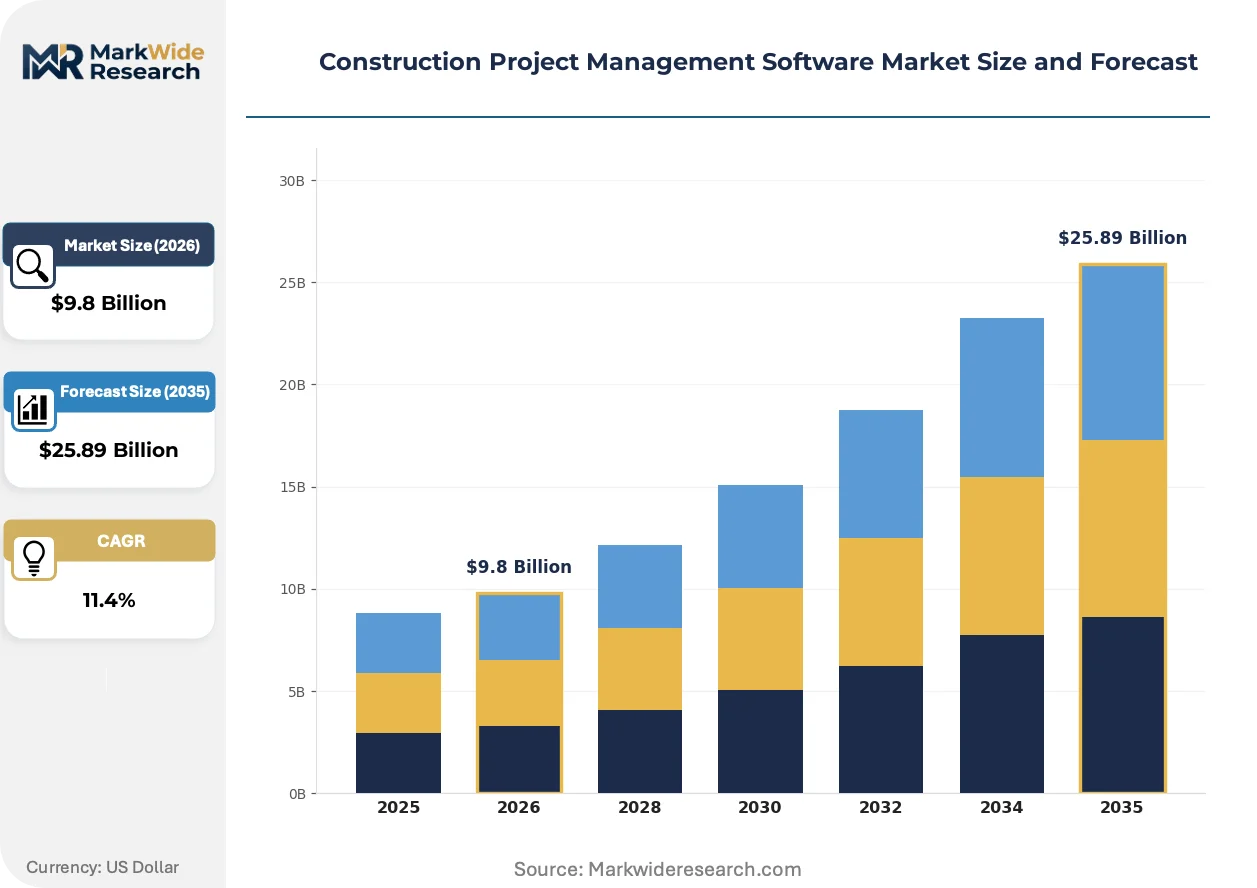
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scheduling Software, Budgeting Tools, Collaboration Platforms, Reporting Solutions Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Contractors, Architects, Engineers, Project Managers Feature: Time Tracking, Document Management, Budget Management, Risk Assessment |
| Companies Covered | Fieldwire, RedTeam Flex, Procore, Jonas Construction Software, ProjectMates, Autodesk Construction Cloud, PlanGrid, LetsBuild, Buildertrend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Project Management Software Market Emerging Trajectories
Artificial intelligence is compressing decision cycles across preconstruction and execution phases, with machine learning models now predicting schedule slippage from weather patterns and supply chain telemetry rather than historical averages alone.
Generative AI copilots embedded in scheduling interfaces are electrifying how superintendents resequence critical path activities. Large language models trained on historical RFIs now draft submittal packages in seconds. Tier-one contractors in Texas and Florida are piloting these tools for high-velocity multifamily developments where traditional planning cycles cannot match permitting acceleration.
The EU CSRD disclosure framework is mandating granular carbon accounting across construction supply chains. Asset owners in Germany and France must now report embodied carbon per building component, forcing project management platforms to integrate environmental product declaration databases. Software vendors are responding with procurement modules that flag high-carbon alternatives before purchase orders finalize.
Subscription fatigue among smaller contractors is fragmenting purchasing authority from central IT to project-level expense accounts. Individual superintendents now procure single-project licenses through app stores rather than enterprise procurement channels. This pattern concentrates in the United States residential market where general contractor employee counts fluctuate seasonally and capital commitment to annual contracts carries unacceptable risk.
Construction Project Management Software Market Segmentation
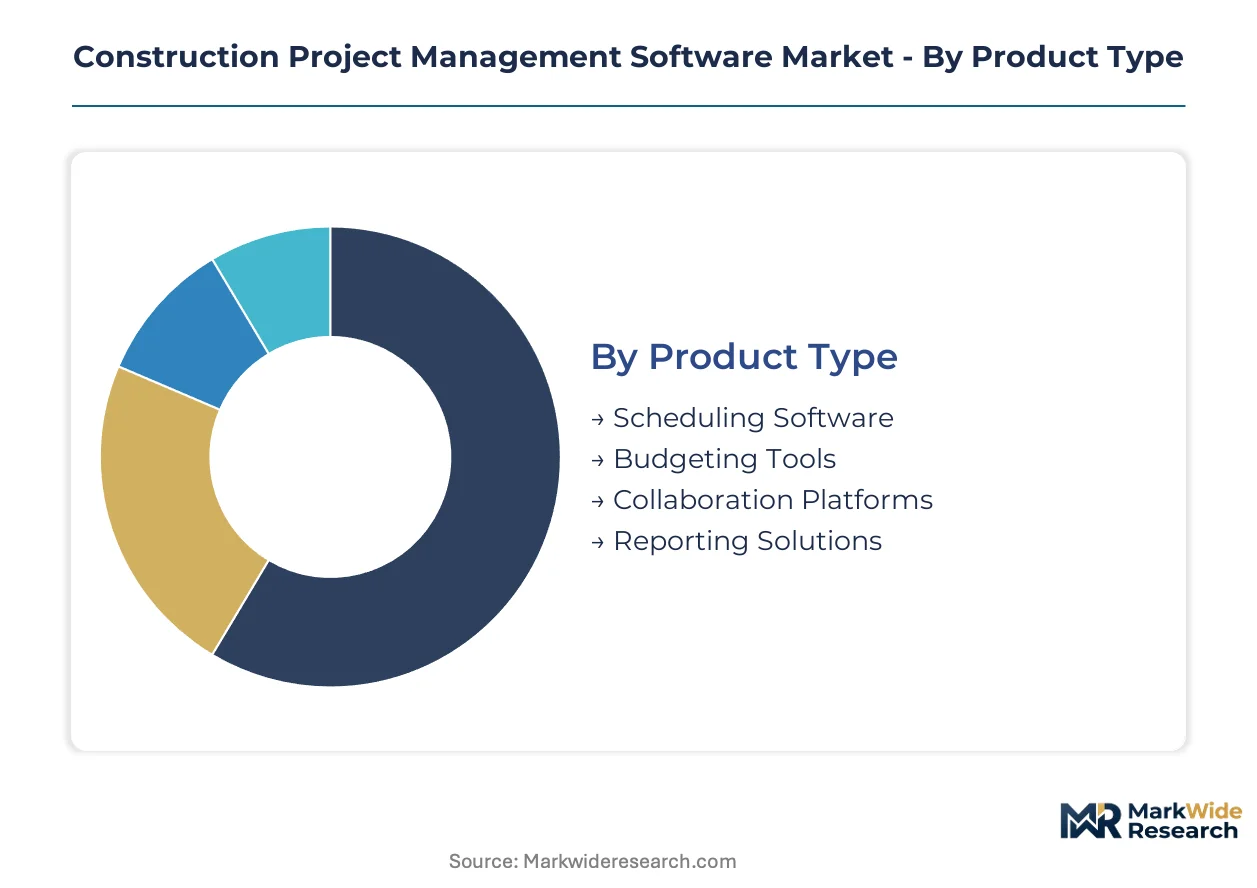
Segmentation in construction project management software reveals how technical specifications, delivery architectures, and user workflows diverge across project scales. Understanding these divides helps vendors align development roadmaps with procurement patterns that vary sharply between residential builders and infrastructure agencies.
Product Type:
Technical sophistication separates tools optimized for single-function depth from integrated suites spanning multiple project phases.
- Scheduling Software:Gantt-based engines with critical path methodology anchor commercial and infrastructure portfolios. Demand concentrates among United States general contractors modernizing field-to-office coordination under tightening BIM documentation mandates.
- Budgeting Tools:Real-time cost ledger synchronization with ERP systems serves public works agencies with strict appropriation compliance. Germany's federal infrastructure programs drive replacement cycles as BSI IT-Grundschutz audit requirements harden.
- Collaboration Platforms:Stakeholder network extensions beyond single-firm boundaries capture expanding margin pools in multi-contractor developments.
- Reporting Solutions:Automated dashboard generation compresses variance analysis cycles for project managers tracking distributed job sites.
Mature deployment sits with Scheduling Software. Newer deployment is concentrated in Collaboration Platforms.
Deployment:
Architecture choices trade implementation speed against data sovereignty requirements and field connectivity constraints.
- Cloud-Based:Zero-install field access dominates multi-site contractor adoption. Australia's infrastructure modernization grants accelerate state-level transport agency procurement for rail and highway digitization.
- On-Premise:Air-gapped installations persist where data residency laws or classified project requirements override convenience. Germany's OAIC-aligned guidelines and defense-adjacent construction sustain this segment.
- Hybrid:Split configurations synchronize sensitive financial data on-premise while pushing field collaboration to cloud nodes.
- Mobile:Native applications for intermittent cellular coverage address remote job site latency that undermines real-time supervisor dashboards.
Cloud-Based architectures claim the steepest expansion trajectory. On-Premise retains footholds where regulatory friction fragments cross-border deployments.
End User:
Professional role determines feature prioritization, with field operatives demanding simplicity and back-office staff requiring analytical depth.
- Contractors:General and specialty trade firms drive volume, with residential builders in the United States showing subscription fatigue and shifting purchasing authority to project-level expense accounts.
- Project Managers:Hybrid construction-technology roles command compensation premiums as platform administration certification becomes mandatory for complex implementations.
- Architects:Design-to-construction handoff workflows demand deep interoperability with BIM authoring tools.
- Engineers:Structural and MEP specialists require procurement modules flagging high-carbon alternatives under EU CSRD disclosure frameworks.
Contractor segment penetration is deepest. Project Manager adoption is climbing the fastest as certification requirements spread.
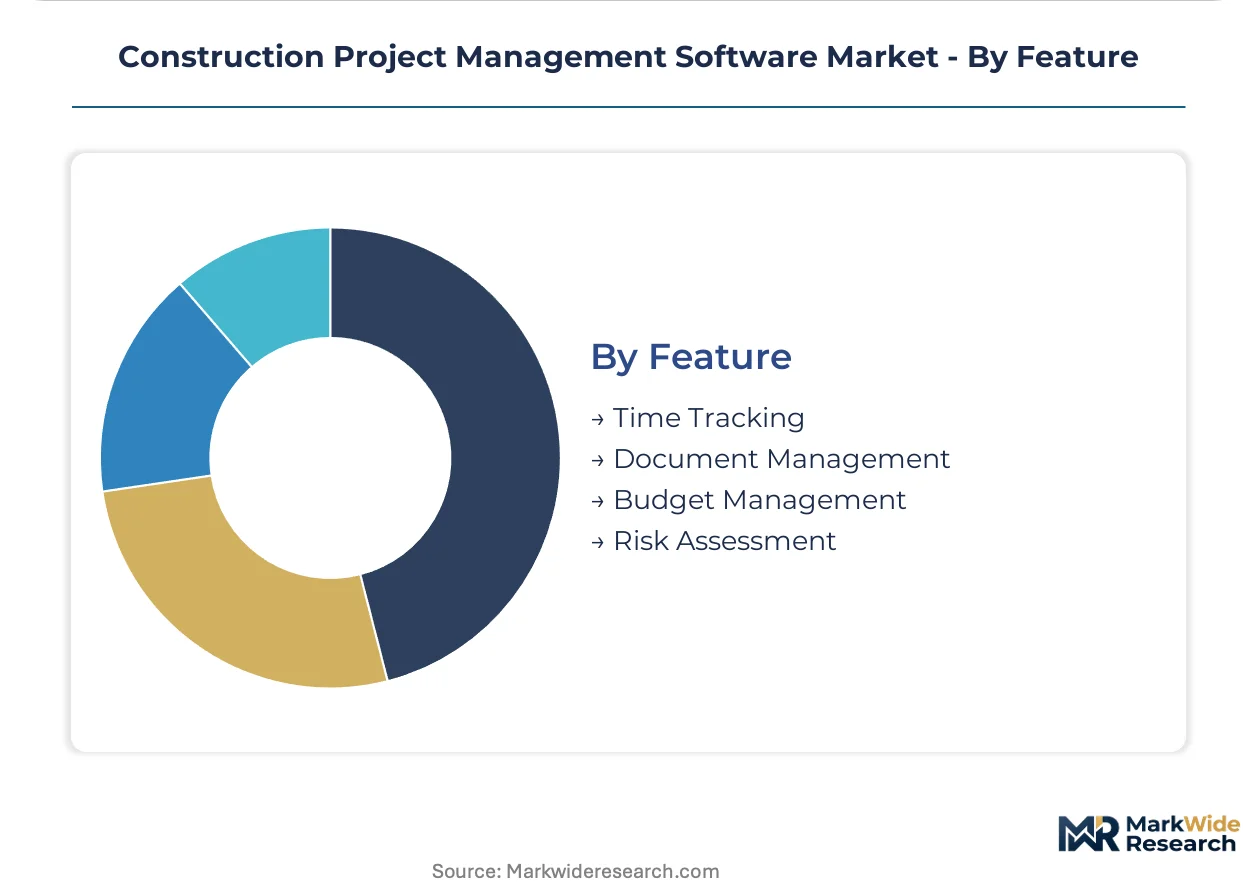
Feature:
Functional modules align with compliance pressures and risk management priorities that vary by project type and jurisdiction.
- Document Management:RFI and submittal tracking with audit trails satisfies OSHA recordkeeping mandates and EPA stormwater construction permit requirements in United States federal projects.
- Budget Management:Appropriation compliance and cost variance alerts sustain steady replacement cycles among public works agencies.
- Time Tracking:Labor hour capture with payroll integration addresses seasonal workforce fluctuations in residential construction.
- Risk Assessment:Predictive models incorporating weather patterns and supply chain telemetry compress decision cycles in preconstruction phases.
Document Management features show widest installed base. Risk Assessment capabilities are gaining share fastest as AI integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors software innovation for construction technology, with Austin and Boston corridors expanding cloud-native platform development for field-to-office coordination.
United States
Federal infrastructure modernization and OSHA digitization mandates drive platform procurement among mid-sized general contractors. The Bipartisan Infrastructure Law channels funding toward state transport agencies requiring integrated project controls. Dallas-Fort Worth metroplex contractors pilot AI-enabled scheduling tools for multifamily developments.
Germany
BSI IT-Grundschutz certification requirements and EU CSRD carbon disclosure rules elevate software specifications for public works agencies. Green building codes tighten documentation workflows for commercial developers. Munich engineering clusters demand deep BIM interoperability for complex infrastructure portfolios.
Australia
Federal digitization grants accelerate state-level transport procurement for rail and highway modernization. OAIC data residency guidelines shape cloud architecture decisions for cross-border contractors. Sydney and Melbourne construction hubs lead adoption of mobile-first field collaboration platforms.
United Kingdom
Building Safety Regulator mandates for digital golden threads compel platform upgrades across residential and commercial portfolios. Government Construction Strategy targets level-2 BIM compliance for public projects. London development consortia integrate environmental product declaration tracking for embodied carbon reporting.
Canada
Provincial infrastructure banks fund municipal digitization programs for water and transit asset management. Canadian Construction Documents Committee standards influence specification templates for project controls. Toronto and Vancouver metropolitan contractors consolidate fragmented software stacks into unified cloud platforms.
Construction Project Management Software Market Vendor Landscape
Premium-margin players sit above commodity-margin players across ecosystem breadth and vertical specialization depth. The vendor base organizes into three tiers: full-suite platforms spanning preconstruction through closeout, trade-specific tools optimized for residential or specialty workflows, and point solutions addressing single functions like safety documentation or equipment tracking. Dominant competitive moves include strategic partnerships with design software providers and vertical integration into payment processing and insurance adjacency services.
Within the full-suite tier, Procore and Autodesk Construction Cloud anchor ecosystem-centric positioning, while Buildertrend exemplifies defensible niche specialization below the commercial tier. Fieldwire and PlanGrid occupy mobile-first field coordination positions. RedTeam Flex and Jonas Construction Software represent mid-market configurability archetypes serving specialty contractors with hybrid deployment needs.
| Leading Market Players |
|---|
| Fieldwire |
| RedTeam Flex |
| Procore |
| Jonas Construction Software |
| ProjectMates |
| Autodesk Construction Cloud |
| PlanGrid |
| LetsBuild |
| Buildertrend |
| Others |
Supply Flow & Price Mechanics
Captive cloud infrastructure investments by hyperscalers anchor both supply security and pricing power for construction software vendors serving multi-site contractors. AWS and Azure data center commitments in Virginia and Frankfurt compress latency for field-to-office synchronization while locking in committed-use discounts that stabilize subscription pricing for enterprise accounts.
Pricing Analysis
Outcome-based pricing tied to project completion velocity anchors enterprise SaaS contracts for general contractors managing billion-dollar portfolios. Three-tier pricing structure across premium, standard, and economy levels separates full-suite platforms from trade-specific tools and single-function point solutions. Cost compression in the mid-market tier is intensifying because AWS and Azure pricing fluctuations squeeze vendor gross margins. Residential builders show highest price sensitivity, while infrastructure agencies with federal digitization grants demonstrate lowest sensitivity due to appropriation-backed procurement cycles.
Supply Chain Analysis
Freight costs for edge computing hardware and IoT sensor deployments add geographic premiums to field kit provisioning for remote job sites. Software supply concentrates in the United States, Germany, and Australia where infrastructure modernization programs drive platform demand. Component dependencies span cloud compute instances, mobile device management licenses, and BIM authoring tool APIs. Single-source vulnerability sits with hyperscaler concentration for core infrastructure. Distribution runs through direct enterprise sales teams and construction equipment OEM dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native deployment architectures are displacing on-premise legacy systems as the dominant delivery model, with AI-enabled scheduling copilots accelerating replacement cycles among tier-one contractors.
For Market Incumbents: Lock in ecosystem breadth through deep BIM interoperability investments that raise switching costs for Autodesk Construction Cloud and Procore accounts. Defend against point-solution disaggregation by embedding generative AI modules that compress RFI drafting cycles. Prioritize certification compliance for EU CSRD carbon disclosure frameworks to capture green building procurement mandates in Germany and France. For New Entrants and Emerging Players: The pricing gap between premium enterprise suites and stripped-down mobile-first tools opens white-space targeting for specialty trade subcontractors in mechanical and electrical segments. Penetrate the underserved United States residential market through project-level subscription models that align with seasonal workforce fluctuations. Pursue distribution partnerships with Caterpillar and Komatsu dealer networks for asset-heavy contractor segments. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by design software providers seeking construction execution capabilities. Long-term viability favors platforms with proven field-to-office workflow integration and established compliance module depth. Watch AI copilot adoption rates among Texas and Florida multifamily developers as inflection indicators for scheduling tool replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep BIM interoperability with Autodesk Revit anchors ecosystem switching costs for commercial contractors. |
| Geographic Expansion | Australia infrastructure modernization grants accelerate state-level transport agency procurement for rail digitization. |
| Product Launch | Generative AI copilots for RFI drafting capture premium pricing from high-velocity multifamily developers. |
| Strategic Partnership | Construction equipment OEM dealer networks unlock penetration into asset-heavy contractor segments. |
| Acquisition of Specialist Firm | Trade-specific workflow tools for mechanical and electrical subcontractors fill portfolio gaps below commercial tier. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this construction software market assessment. Primary interviews with platform engineering directors, IT procurement officers at general contractors, and integration specialists at BIM consultancies combined with secondary validation from OSHA digitization mandate documentation, EPA stormwater permit filings, and federal infrastructure grant disclosures. Bottom-up project pipeline enumeration and top-down SaaS spend aggregation provided triangulation across analysis approaches.
Reconciliation of vendor-reported subscription bookings, public sector procurement databases, and hyperscaler construction vertical revenue disclosures shaped the analytical framework. Segmentation dimensions modeled span deployment architecture, organization size by employee count, vertical specialization, integration complexity with legacy ERP systems, and regional adoption pattern tied to infrastructure modernization programs. CAGRs derived from compounding annual subscription growth rates adjusted for churn and expansion revenue. Forecast inputs incorporated BIM mandate implementation timelines and green building certification acceleration curves.
Underlying measurement precision varies by segment; cloud-based deployment and contractor end-user categories carry tighter precision than on-premise and hybrid configurations where data residency law fragmentation obscures visibility. Forecasts reflect assumptions about regulatory compliance acceleration and AI copilot adoption velocity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Supplier Relationship Management Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Configure Price and Quote (CPQ) Market
Software & Services
Cloud-Based ERP Software Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
Global Student Information System Market
Software & Services
Email Marketing Software Market
Software & Services
Sourcing Software Market
Software & Services
Change Control Management Software Market
Software & Services
Server Operating System Market
Software & Services
Product Analytics Software Market
Software & Services
Sales Platforms Software Market
Software & Services
France Digital Marketing Software Market
Software & Services
Global Programming Software Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
Global Virtual Desktop Market