
 Asia-Pacific Text to Speech (TTS) Software Market | 2026-2036
Asia-Pacific Text to Speech (TTS) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Text to Speech (TTS) Software Market Outlook
The capital-intensity divergence between neural infrastructure builders and lightweight application developers is reorganizing competitive tiers across the Asia-Pacific Text to Speech landscape. Microsoft leverages its Azure cloud backbone to sustain inference-scale deployments across Southeast Asian enterprises. iFLYTEK Corporation anchors its position through deep vertical integration into Mandarin and minority-language acoustic modeling. Baidu, Inc. competes aggressively on edge-device optimization for automotive and IoT clients.
Asia-Pacific Text to Speech software converts written text into synthesized speech through computational linguistics, acoustic modeling, and vocoding pipelines operating at sampling rates typically between 16 kHz and 48 kHz. Its primary commercial purpose is enabling human-machine voice interaction for accessibility tools, automated customer service, and content consumption platforms. Cloud-Based deployment is capturing the dominant margin pool as telecommunications carriers and media platforms prioritize elastic scaling over fixed infrastructure. Neural TTS technology leads growth velocity, displacing concatenative methods in enterprise procurement due to superior prosody control and reduced storage overhead for multilingual corpora.
China's MIIT and SAMR enforce algorithmic recommendation and deep synthesis provisions that mandate disclosure of AI-generated voice content, directly shaping product architecture for domestic vendors. India's TRAI accessibility directives and Japan's JIS standards for information and communications technology create layered compliance obligations that filter market access for foreign platforms. South Korea's MFDS and KISA frameworks extend governance into healthcare voice applications and data security for biometric speech processing. Stakeholders must monitor how divergent national AI governance trajectories reshape localization requirements and partnership structures across the region.
Market Dynamics
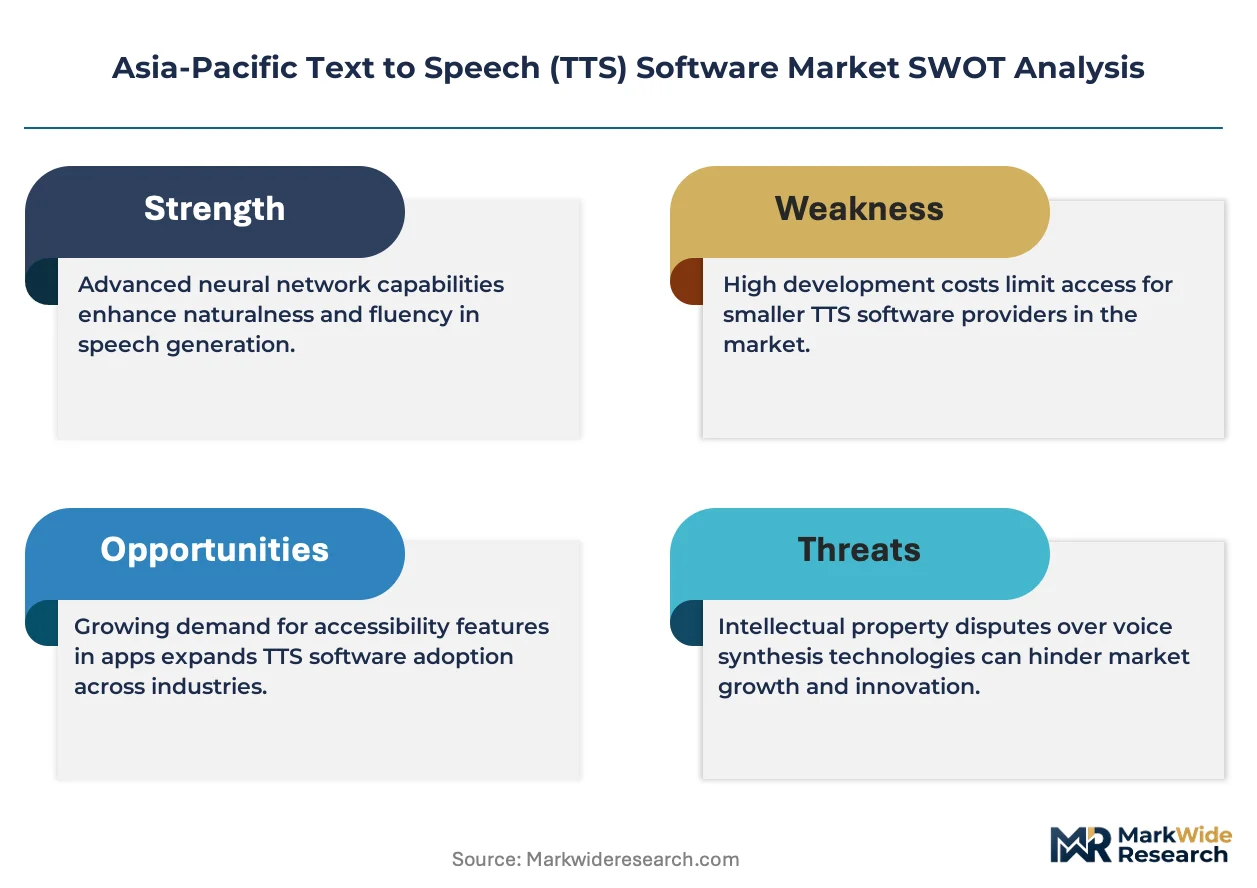
Neural TTS architectures are compressing the cost-per-voice-hour for multilingual deployment, forcing infrastructure consolidation among cloud providers serving Asia-Pacific enterprises. This technological shift redistributes margin capture from acoustic data collectors to inference-optimized platform operators.
Growth Catalysts
- MIIT deep synthesis disclosure mandates:China's algorithmic recommendation provisions compel domestic developers to embed provenance tracking, accelerating compliance tooling procurement across Mandarin-language platforms.
- Healthcare voice automation:Japan's patient communication systems and South Korea's clinical documentation workflows are expanding TTS deployment in acute care settings.
- Regional language corpora expansion:India's education technology procurement now weights Dravidian and Indo-Aryan language support as a mandatory technical criterion.
Market Restraints
- GPU cluster cost volatility:Training runs for neural vocoders require sustained access to H100 or equivalent accelerators, concentrating capability among hyperscale cloud tenants.
- Phonetic data concentration:High-quality annotated speech corpora for tonal languages remain concentrated in Beijing, Shanghai, and Seoul data markets.
- Concatenative TTS lock-in:Legacy telephony infrastructure in Southeast Asian financial services resists neural migration due to embedded storage investments.
Strategic Opportunities
- Indonesian archipelago penetration:Bahasa Indonesia and Javanese language gaps in current vendor portfolios create first-mover openings for localized acoustic model development.
- Edge-device automotive integration:In-vehicle infotainment systems across Japan and South Korea are requesting sub-50MB neural vocoder footprints for offline operation.
- TRAI accessibility directives:India's mandate for voice-enabled public services creates procurement pipelines for regional language TTS in government technology stacks.
Industry Challenges
- Prosody engineering talent scarcity:The intersection of computational linguistics and perceptual audio evaluation requires specialists concentrated in Beijing, Tokyo, and Bangalore research clusters.
- Cross-border data residency friction:Biometric voiceprint storage for healthcare applications triggers conflicting MFDS, PMDA, and TRAI localization requirements.
- Legacy telephony codec integration:Narrowband PCM compatibility in Southeast Asian banking infrastructure forces redundant vocoder maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Text to Speech (TTS) Software Market |
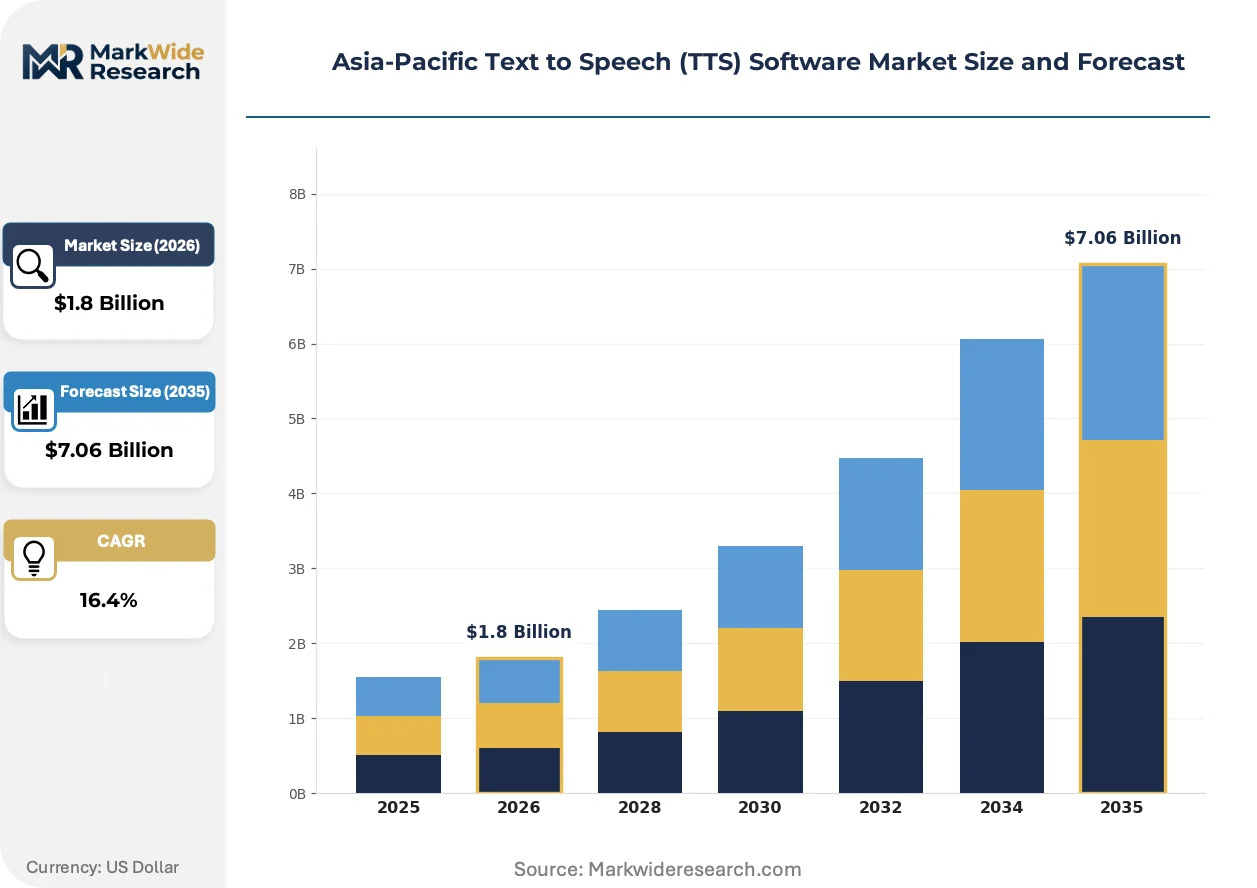
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Virtual Appliance End User: Education, Telecommunications, Media, Healthcare Technology: Deep Learning, Neural TTS, Concatenative, Formant-based Application: Assistive Technology, Voice Assistants, Audiobooks, Language Learning |
| Companies Covered | Microsoft, IBM, iFLYTEK Corporation, ReadSpeaker Holding B.V., Nuance Communications, Inc., Baidu, Inc., Amazon Web Services, Inc., Sensory Inc., Google, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Text to Speech (TTS) Software Market Strategic Shifts
Diffusion-based neural vocoders are collapsing the latency-accuracy tradeoff that previously segmented cloud and edge deployment strategies. This architectural shift enables unified model serving across Asia-Pacific telecommunications and automotive supply chains.
End-to-end neural TTS is decomposing the traditional pipeline of text analysis, prosody prediction, and waveform generation into single-pass latent diffusion. Japanese automotive tier-1 suppliers are piloting these architectures for real-time navigation prompts. The compression of inference steps from hundreds to under twenty is decomposing the cost structure that previously favored concatenative methods for low-latency applications.
China's MIIT and SAMR enforcement of deep synthesis disclosure is mandating watermarking infrastructure for all commercially distributed voice models. Domestic developers must embed detectable provenance signals in synthetic audio outputs. Healthcare and media platforms in China are responding by restructuring product architecture to separate generation from distribution layers.
Subscription-based API access is displacing perpetual licensing for enterprise TTS procurement across India and Southeast Asia. Telecommunications carriers and edtech platforms now prioritize consumption-scaled pricing over fixed infrastructure commitments. This shift is most visible in Bangalore and Jakarta, where mid-market SaaS vendors are unbundling voice generation from broader customer experience suites.
Asia-Pacific Text to Speech (TTS) Software Market Segmentation
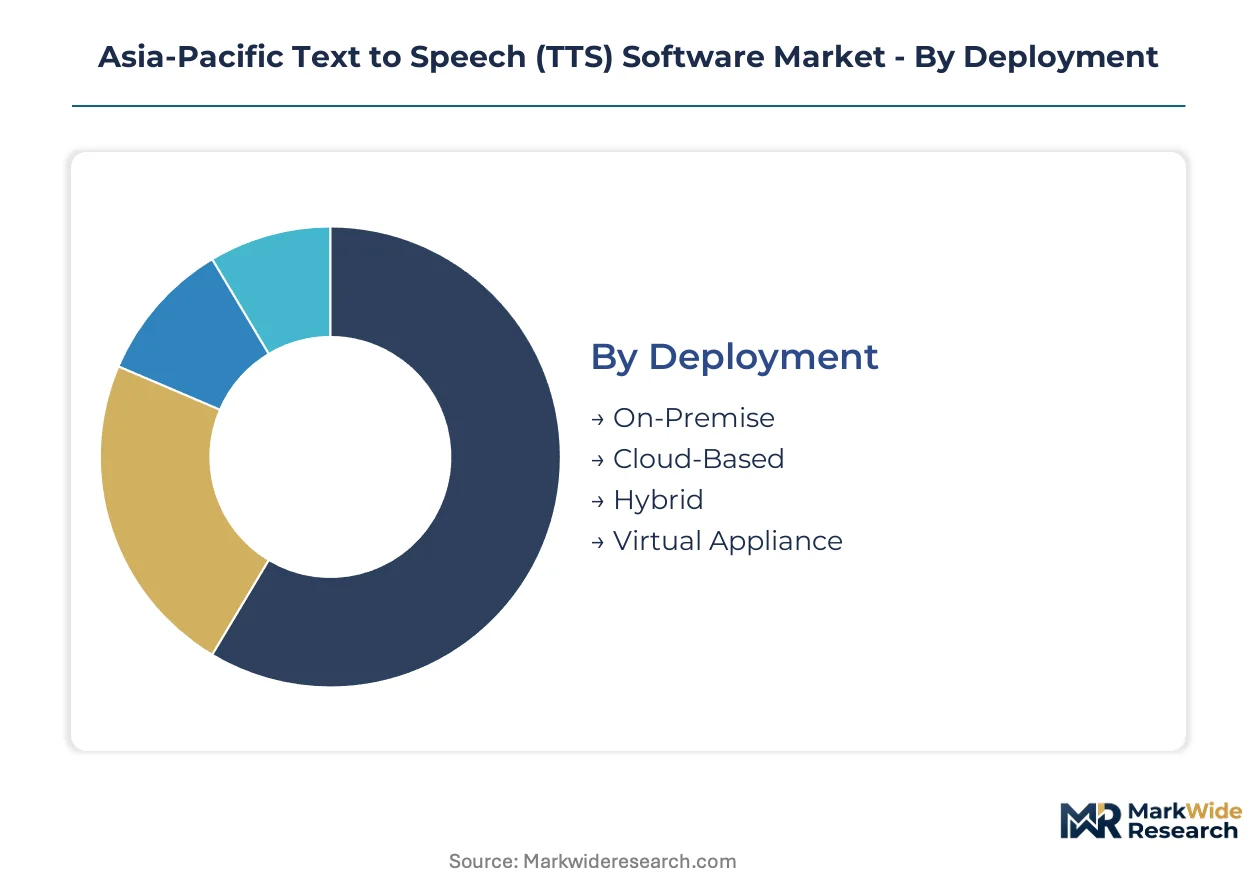
Segmentation in the Asia-Pacific Text to Speech market reveals how deployment economics, regulatory boundaries, and acoustic modeling requirements reshape vendor strategies across national markets. Understanding these divides exposes where margin pools concentrate and where localization investments deliver competitive separation.
Deployment:
Domestic data residency requirements in China and South Korea favor on-premise and hybrid configurations, while export-oriented SaaS vendors from Singapore and India push cloud-native delivery across Southeast Asian markets.
- On-Premise:Deployed within enterprise data centers to satisfy MFDS healthcare voiceprint storage rules in Seoul and MIIT algorithmic audit requirements in Beijing. Japanese financial institutions in Osaka and Tokyo maintain on-premise concatenative systems for legacy trading floor compatibility.
- Cloud-Based:Elastic inference scaling serves Indonesian edtech platforms and Philippine call center operators. Telecommunications carriers in Bangkok and Kuala Lumpur prioritize consumption-based API pricing over fixed infrastructure commitments.
- Hybrid:Sensitive preprocessing occurs on local edge nodes before cloud-based neural vocoding. Australian healthcare networks and New Zealand government agencies deploy this architecture for patient data segmentation.
- Virtual Appliance:Containerized TTS engines run on virtualized infrastructure within sovereign cloud zones. Vietnam's banking sector and Thailand's retail conglomerates favor this model for rapid disaster recovery.
On-Premise commands the established base. The steepest expansion runs through Cloud-Based.
End User:
Customer procurement criteria diverge sharply between regulated healthcare voice applications and high-volume media content generation, with education technology emerging as the most price-sensitive vertical.
- Education:Regional language support determines vendor selection for Indian edtech procurement in Bangalore, Hyderabad, and Chennai. Dravidian corpus availability separates competitive bids for government digital literacy programs.
- Telecommunications:IVR modernization and voicebot deployment drive TTS adoption across Reliance Jio, Singtel, and Telstra networks. Latency requirements under 200 milliseconds constrain architectural choices.
- Media:Automated audiobook production and news narration scale fastest in Mandarin and Japanese markets. Content platforms in Shanghai and Tokyo demand emotional prosody control for fiction genres.
- Healthcare:Patient communication systems in Osaka and clinical documentation workflows in Seoul require HIPAA-equivalent and MFDS-compliant voice data handling. Accessibility mandates accelerate procurement.
Telecommunications captures the highest voice-hour volumes. Education is gaining share fastest through government technology tenders.
Technology:
Cost structures and talent availability concentrate neural TTS development in Beijing, Shanghai, and Shenzhen, while legacy concatenative methods persist where phonetic inventory stability outweighs naturalness requirements.
- Deep Learning:End-to-end architectures compress text-to-waveform pipelines into single neural networks. Research clusters in Bangalore and Singapore pilot transformer-based approaches for code-mixed language handling.
- Neural TTS:Dominates enterprise procurement due to superior prosody control and reduced storage overhead for multilingual corpora. Chinese developers leverage domestic GPU cloud infrastructure to sustain training scale.
- Concatenative:Unit selection from recorded speech segments serves legacy telephony in Southeast Asian banking infrastructure where narrowband PCM compatibility is non-negotiable.
- Formant-based:Parametric synthesis using vocal tract modeling persists in embedded automotive applications across Japan and South Korea where sub-50MB footprints enable offline operation.
Concatenative retains the installed base in financial services. Neural TTS is climbing the fastest across all new procurement.
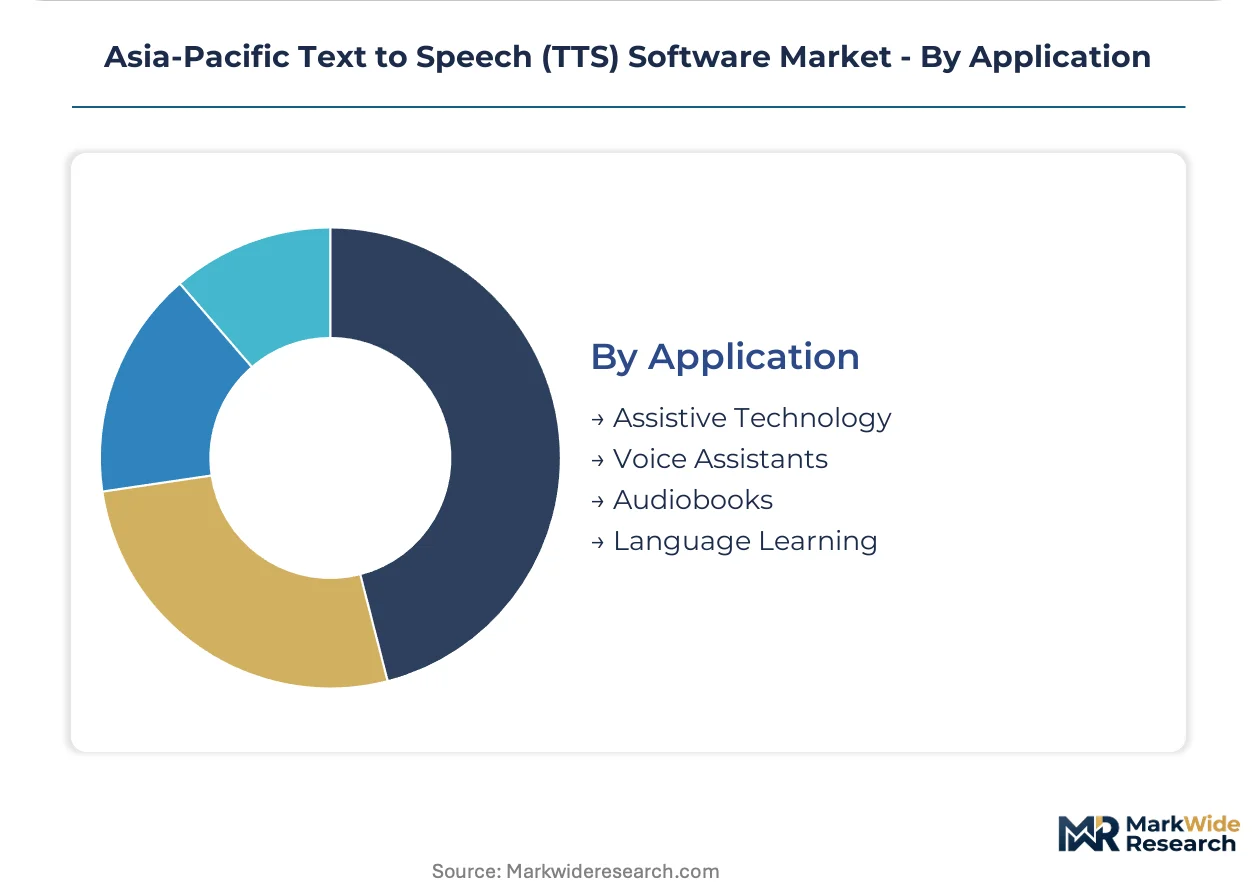
Application:
Regulatory accessibility mandates and consumer platform economics create divergent growth trajectories, with assistive technology procurement governed by national disability standards while voice assistants compete on conversational latency.
- Assistive Technology:Screen readers and communication aids for vision-impaired users fall under Japan's JIS standards and India's TRAI accessibility directives. Government reimbursement shapes pricing ceilings.
- Voice Assistants:Smart speaker and automotive integration demand real-time response below 150 milliseconds. Korean and Japanese OEMs specify edge-optimized neural vocoders for in-vehicle deployment.
- Audiobooks:Automated narration scales through subscription platforms in China and Japan. Emotional range and character voice separation differentiate premium offerings.
- Language Learning:Pronunciation feedback applications require phoneme-level alignment accuracy. Southeast Asian markets prioritize tonal language handling for Mandarin, Thai, and Vietnamese instruction.
Assistive Technology anchors the compliance-driven segment. Voice Assistants show the steepest expansion trajectory through consumer electronics integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese and Japanese metropolitan clusters where neural TTS training infrastructure anchors premium service tiers, while Indian and Southeast Asian markets compete on regional language coverage at compressed margins.
China
Domestic cloud hyperscalers and AI developers drive procurement volume through MIIT-mandated deep synthesis compliance tooling. SAMR disclosure requirements for AI-generated voice content reshape product architecture across Beijing and Shanghai development clusters. Shenzhen acoustic modeling labs concentrate GPU training capacity for Mandarin and minority-language corpora.
Japan
Automotive OEMs and healthcare providers anchor demand through JIS standards compliance for accessibility and in-vehicle voice systems. METI industrial policy supports edge-device neural vocoder development for offline operation. Osaka and Tokyo host patient communication system deployments in acute care networks.
India
Education technology procurement from Bangalore, Hyderabad, and Chennai elevates Dravidian and Indo-Aryan language support to mandatory technical criteria. TRAI accessibility directives create government technology pipelines for voice-enabled public services. Domestic developers compete on consumption-scaled API pricing against foreign platform entrants.
South Korea
Clinical documentation workflows and healthcare voice applications expand under MFDS biometric speech processing rules and KISA data security frameworks. Seoul medical centers deploy patient communication systems requiring HIPAA-equivalent voice data handling. Busan-Ulsan automotive suppliers request sub-50MB neural vocoder footprints for infotainment integration.
Indonesia
Bahasa Indonesia and Javanese language gaps in incumbent vendor portfolios create first-mover openings for localized acoustic model development. Jakarta edtech platforms and telecommunications carriers prioritize elastic cloud scaling over fixed infrastructure commitments. Domestic developers exploit archipelago-wide connectivity investments to bypass legacy telephony lock-in.
Asia-Pacific Text to Speech (TTS) Software Market Competitive Environment
Concentration sits with hyperscale cloud providers and vertically integrated acoustic modeling specialists. The vendor base stratifies across three tiers: infrastructure-backed platform operators, language-specific modeling experts, and edge-optimized automotive suppliers. Dominant competitive moves include compliance-driven product architecture restructuring and regional language corpus expansion through academic partnerships.
Among infrastructure-backed operators, Microsoft and Amazon Web Services exemplify cloud-native deployment scale across Southeast Asian enterprises. iFLYTEK Corporation anchors the language-specialist tier through deep integration into Mandarin acoustic modeling. Baidu occupies a position within the edge-optimization vector for automotive and IoT client segments.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| iFLYTEK Corporation |
| ReadSpeaker Holding B.V. |
| Nuance Communications, Inc. |
| Baidu, Inc. |
| Amazon Web Services, Inc. |
| Sensory Inc. |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation contracts with Chinese hyperscalers lock in GPU cluster access and neural training cost visibility for domestic TTS developers navigating MIIT compliance mandates. These arrangements tether price stability to infrastructure commitment depth across Beijing and Shanghai development clusters.
Pricing Analysis
The customization-premium spread separates configured-to-order acoustic modeling from standard API tiers across Asia-Pacific procurement. Subscription-based SaaS pricing dominates Indian edtech and Southeast Asian telecommunications, while project-based licensing persists in Japanese healthcare and automotive verticals. Price differentiation hinges on regional language corpus depth and MIIT/SAMR compliance certification tier. Cost compression in standard API tiers intensifies as domestic Chinese vendors exploit captive GPU cloud infrastructure. Education technology buyers in Bangalore and Jakarta exhibit highest price sensitivity; Japanese automotive OEMs and Seoul medical networks show lowest sensitivity due to offline operation and data residency requirements.
Supply Chain Analysis
Just-in-time phonetic data sourcing dominates neural TTS development, though strategic stockpiling of annotated tonal language corpora occurs in Beijing and Seoul research clusters. GPU accelerator supply concentrates in China, Taiwan, and South Korea, with H100-equivalent training capacity anchored in Shenzhen and Shanghai data centers. Raw material dependencies span high-bandwidth memory modules, specialized AI training chips, and precision acoustic recording facilities. Single-source vulnerability in advanced GPU foundry access constrains training scale for non-hyperscale developers. Distribution runs through sovereign cloud zones in China and South Korea, direct API provisioning in India and Southeast Asia, and hybrid edge-cloud architectures in Japan and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in cyclical recovery driven by MIIT-mandated compliance tooling procurement cycles that refresh enterprise infrastructure every three to four years.
For Market Incumbents: Consolidate through backward integration into Mandarin and minority-language acoustic data collection to defend against emerging GPU-rich domestic challengers. Lock in long-term capacity reservation with Beijing and Shanghai hyperscalers to secure training cost visibility. Prioritize certification investment for SAMR deep synthesis watermarking standards to maintain platform eligibility. For New Entrants and Emerging Players: Differentiate on Bahasa Indonesia and Javanese acoustic model development where incumbent portfolios show coverage gaps. Target Jakarta edtech platforms and archipelago telecommunications carriers as the most penetrable buyer segment. Pursue academic partnership go-to-market angles with Indonesian universities for corpus development legitimacy. For Investors and Strategic Acquirers: Capital is best deployed toward edge-optimized neural vocoder specialists with automotive OEM validation in Japan and South Korea. Long-term viability over the next decade rests on offline operation capability and sub-50MB footprint engineering. Watch for inflection when diffusion-based architectures achieve sub-twenty inference step compression at production scale.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Language Corpus Expansion | Dravidian and Indo-Aryan coverage unlocks Indian government technology procurement pipelines under TRAI directives. |
| Edge-Device Neural Vocoder Optimization | Sub-50MB footprints enable offline automotive infotainment deployment across Japanese and Korean OEM specifications. |
| MIIT Compliance Architecture Restructuring | Deep synthesis watermarking integration separates eligible vendors from excluded platforms in Chinese public tenders. |
| Academic Partnership for Phonetic Data | Indonesian university collaborations bypass concentrated Beijing and Seoul annotated speech markets. |
| Hybrid Deployment Infrastructure | Local edge preprocessing with cloud vocoding satisfies Australian healthcare data segmentation requirements. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with TTS platform engineers, enterprise IT procurement officers, healthcare biomedical informatics leads, and automotive Tier 1 supplier software architects; and secondary validation against MIIT regulatory filings, SAMR disclosure guidance documents, hyperscaler capex disclosures, and Indian TRAI accessibility directive implementation reports. Bottom-up voice-hour demand modeling triangulated against top-down neural infrastructure capacity estimates across the Asia-Pacific region.
The forecasting boundary spans deployment model, end-user vertical, technology architecture, and application type segmentation dimensions throughout the projection horizon. CAGRs were derived from inference cost compression curves and enterprise procurement cycle analysis. Industry-specific inputs included GPU cluster availability timelines, regional language corpus development schedules, and national AI governance implementation trajectories.
Forecasts assume regulatory continuity in Chinese MIIT/SAMR, Indian TRAI, Japanese JIS, and South Korean MFDS regimes; material policy shifts would require re-modeling. Revision becomes warranted when neural vocoder latency-accuracy tradeoffs cross thresholds enabling unified cloud-edge deployment at scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Pension Administration Software Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Commercial Drone Software Market
Software & Services
Productivity Management Software Market
Software & Services
Category Management Software Market
Software & Services
Data Conversion Services Market
Software & Services
India Sports Management Software Market
Software & Services
Asia-Pacific Printing Software Market
Software & Services
Truck Dispatch Software Market
Software & Services
Software Testing Tools Market
Software & Services
Application Platform As a Service Market
Software & Services
Course Authoring Software Market
Software & Services
Europe Servicenow Store Apps Market
Software & Services
MES Software Market
Software & Services
Global Help Desk Software Market