
 Online Gambling Market | 2026-2036
Online Gambling Market Size, Share, and Industry Trends Forecast 2026-2036
Online Gambling Market Analysis
The EU AI Act is hardening compliance obligations for algorithm-driven player monitoring across European jurisdictions. Entain leverages its proprietary technology stack to sustain responsible gaming certifications in regulated markets. Flutter Entertainment anchors its portfolio through geographic diversification across the Americas, Europe, and Australia. DraftKings dominates the North American sports betting landscape through direct-to-consumer mobile platforms and state-by-state market access.
Online gambling encompasses digital wagering platforms that enable real-money betting on games of chance, skill-based contests, and sporting events through internet-connected devices, typically requiring encrypted payment processing, geolocation verification, and random number generation certification to ensure fair outcomes. Its primary commercial purpose is to monetize user engagement through house-edge mechanics, subscription models, or transaction fees while maintaining regulatory compliance across fragmented licensing regimes. Sports betting captures the largest share of operator revenue due to high event frequency and in-play wagering velocity, while esports betting represents the fastest-expanding product type as younger demographics migrate from traditional casino formats. Cryptocurrency payment methods are gaining structural traction where banking restrictions limit fiat-channel access, though credit cards and e-wallets still command the deepest liquidity pools.
The UK Gambling Commission, state-level gaming control boards across the United States, and Brazil's SPA lottery secretariat collectively shape market access through divergent licensing timelines, tax-rate structures, and advertising restrictions. These frameworks force operators to maintain modular compliance architectures capable of adapting to jurisdiction-specific player-protection mandates, deposit limits, and self-exclusion registry integrations. Stakeholders must monitor the pace of U.S. state legislative sessions and emerging market privatization schedules to calibrate capital deployment against regulatory clarity timelines.
Market Dynamics
The EU AI Act is forcing operators to rebuild player-monitoring infrastructure around automated risk-detection algorithms, creating immediate compliance costs while locking out vendors lacking modular certification architectures. This regulatory pressure cascades through licensing timelines, advertising restrictions, and self-exclusion registry integrations across fragmented jurisdictions.
Growth Catalysts
- Mobile-first sports betting penetration:Smartphone wagering apps are drawing casual gamblers across Brazil and Mexico through frictionless onboarding and micro-betting formats.
- State-level authorization waves:Brazil's SPA lottery secretariat is licensing online sportsbooks, unlocking Latin America's largest addressable digital gambling population.
- Cryptocurrency payment rails:Blockchain settlement methods bypass fiat banking restrictions in jurisdictions with limited card-network access, expanding operator reach.
Market Restraints
- Geolocation verification costs:Real-time location authentication infrastructure requires continuous capital deployment to satisfy state gaming control boards.
- Advertising restriction fragmentation:Divergent marketing bans across Germany's Glücksspielneuregulierungsstaatsvertrag, UK Gambling Commission codes, and US state laws force redundant creative production.
- Random number generation certification delays:ISO/IEC 17025 laboratory testing backlogs extend platform launch timelines by 4-8 months in newly regulated markets.
Strategic Opportunities
- Esports betting vertical expansion:Skill-based wagering on competitive video gaming captures migration of younger demographics from traditional casino formats.
- In-play wagering velocity optimization:Real-time odds adjustment during live sporting events drives higher transaction frequency than pre-match markets.
- Responsible gaming technology exports:Proprietary risk-detection algorithms developed for EU AI Act compliance can be licensed to operators entering newly regulated Latin American markets.
Industry Challenges
- Machine learning engineer scarcity:Automated player-monitoring system development requires specialized talent pools concentrated in fintech and cybersecurity sectors.
- Multi-jurisdiction compliance architecture complexity:Modular systems must simultaneously satisfy UK Gambling Commission affordability checks, US state deposit limits, and Brazilian SPA technical standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Gambling Market |
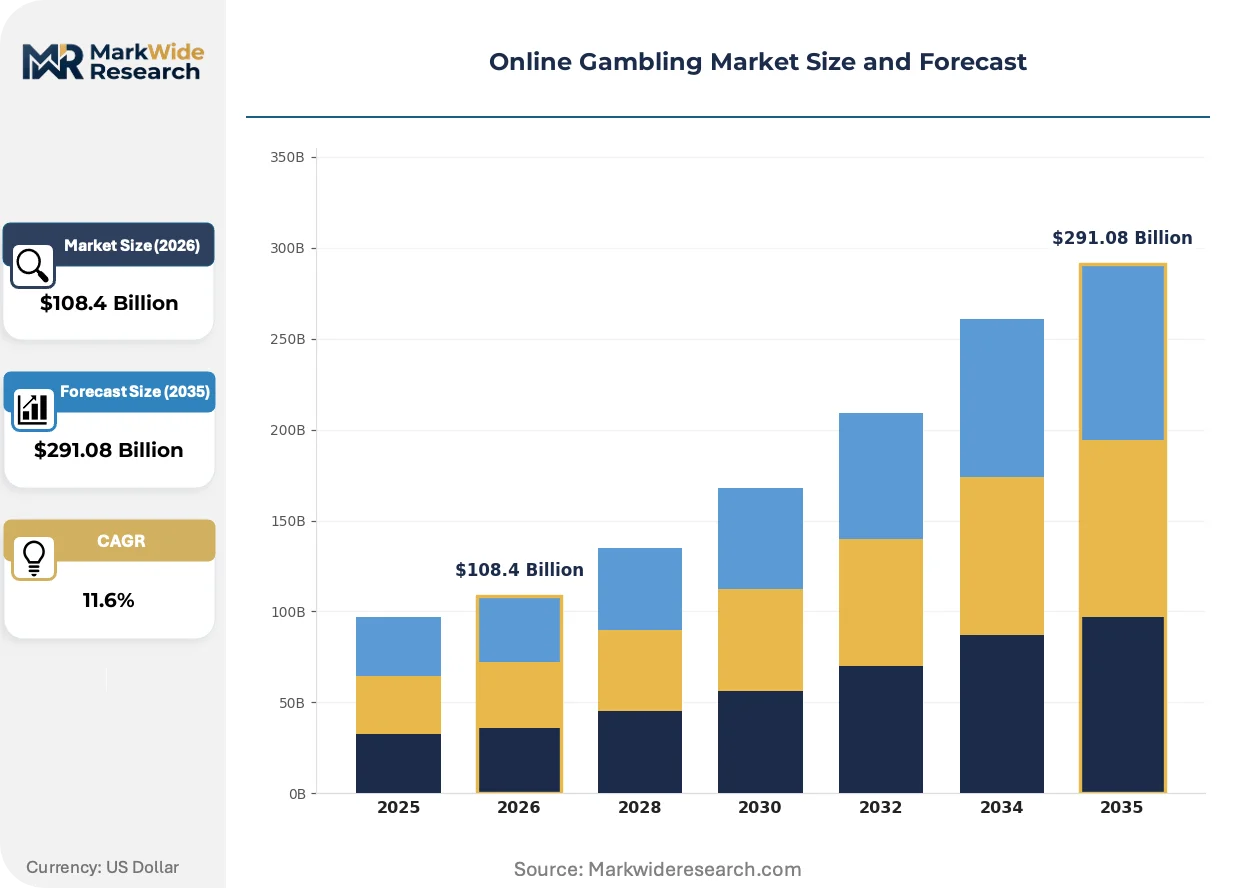
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $291.08 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casino Games, Sports Betting, Poker, Esports Betting Payment Method: Credit Cards, E-Wallets, Bank Transfers, Cryptocurrency Device Type: Desktop, Mobile, Tablet, Smart TV Customer Type: Casual Gamblers, High Rollers, Professional Gamblers, New Players |
| Companies Covered | Entain, Bet365 Group, Flutter Entertainment, Super Group, Betsson, DraftKings, Evoke, Kindred Group, Evolution Gaming, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Gambling Market Emerging Trajectories
Algorithmic player protection is rewriting operator technology roadmaps as regulators mandate real-time behavioral intervention. Three interconnected developments are compressing competitive timelines and reshaping capital allocation priorities.
Artificial intelligence-driven risk scoring is rewriting how operators identify problematic gambling patterns before financial harm materializes. Tier-one platforms are deploying neural networks trained on deposit velocity, session duration, and loss-chasing indicators. This capability is compressing the window between at-risk behavior detection and mandatory cooling-off periods, fundamentally altering customer lifetime value calculations.
The EU AI Act is mandating algorithmic transparency documentation for all automated decision systems affecting player access or limits. Operators must now maintain technical files demonstrating human oversight mechanisms and bias testing protocols. European jurisdictions are responding with accelerated procurement of explainable AI tooling, while US state regulators are monitoring these precedents for potential adoption.
Social betting formats are displacing solitary casino-style engagement among cohorts under 35. Peer-to-peer wager pools, influencer-hosted prediction markets, and community-driven parlay construction are capturing share from traditional slot and table game revenue. Brazil and Colombia represent the most visible adoption geographies, where mobile-native demographics favor interactive formats over legacy product designs.
Online Gambling Market Segmentation
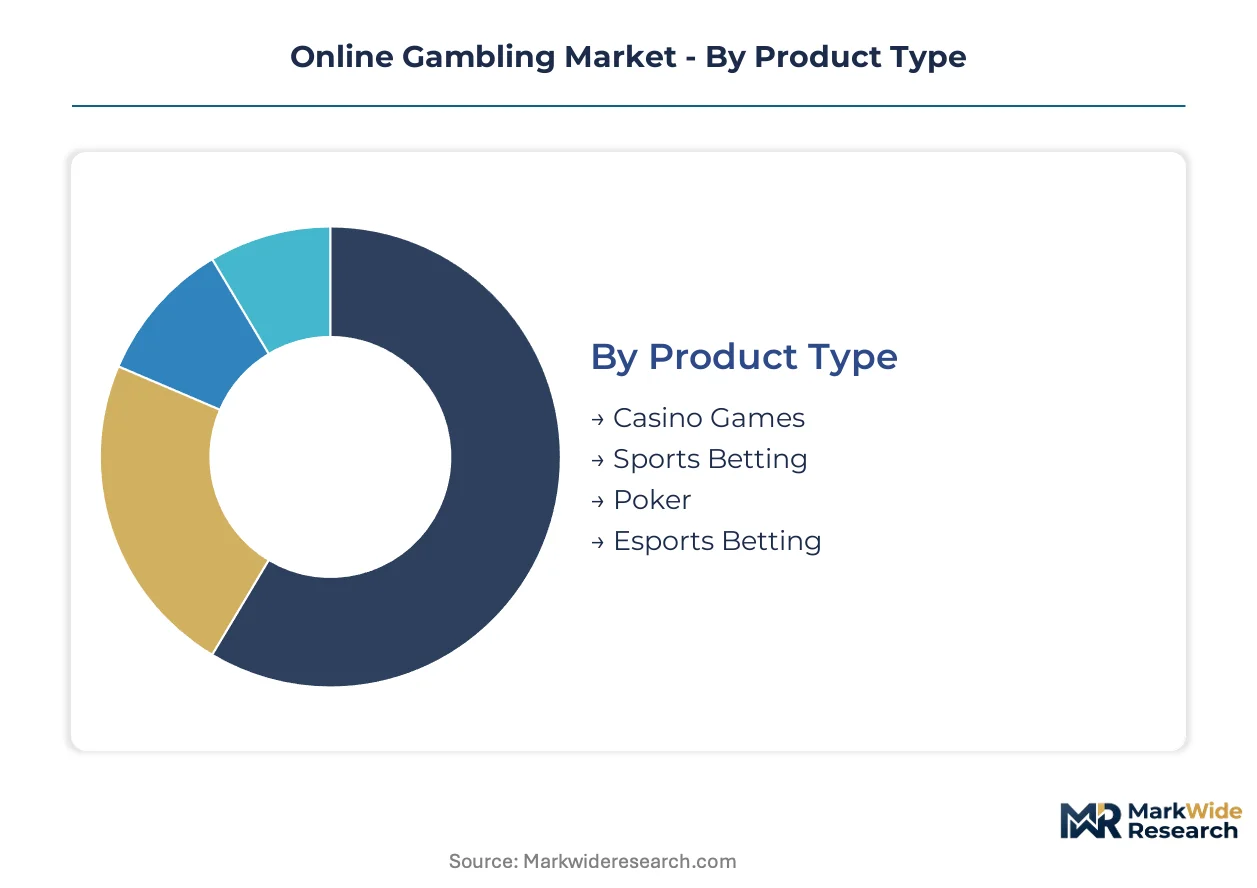
Segmentation in online gambling reveals how distinct user behaviors, technical preferences, and risk profiles create divergent monetization pathways. Operators calibrate platform architecture, payment integration, and promotional spend against these divides to optimize customer lifetime value and regulatory compliance costs.
Product Type:
Sports betting commands the deepest liquidity pools through high-frequency event schedules, while casino games deliver more predictable house-edge economics.
- Sports Betting:Real-time odds adjustment during live events drives transaction velocity far beyond pre-match markets. Demand concentrates in Brazil as state-level SPA authorizations expand licensed operator access to Latin America's largest digital gambling population.
- Casino Games:Random number generation certification requirements from ISO/IEC 17025 laboratories create 4-8 month launch delays in newly regulated markets. Player preference clusters in European jurisdictions with established slot and table game heritage.
- Poker:Skill-based formats attract professional player cohorts seeking peer-to-peer competition rather than house-edge mechanics.
- Esports Betting:Wagering on competitive video gaming captures demographic migration from traditional casino formats among users under 35.
Mature deployment sits with Casino Games. Newer deployment is concentrated in Esports Betting.
Payment Method:
Friction at the deposit layer directly determines geographic reach where banking infrastructure varies sharply.
- Credit Cards:Dominant liquidity source in mature markets with established card network penetration. UK Gambling Commission and US state gaming control boards impose strict chargeback monitoring that elevates compliance overhead.
- E-Wallets:PayPal, Skrill, and regional equivalents intermediate transactions where direct card acceptance faces regulatory friction. Adoption accelerates in Germany under Glücksspielneuregulierungsstaatsvertrag advertising restrictions that favor less visible payment trails.
- Bank Transfers:Preferred by high-value players seeking deposit limits above card thresholds.
- Cryptocurrency:Blockchain settlement bypasses fiat restrictions in jurisdictions with limited banking access.
Established markets favor Credit Cards. Cryptocurrency adoption is climbing the fastest in restricted banking environments.
Device Type:
Screen size and portability trade off against session depth and simultaneous wagering capability.
- Mobile:Smartphone apps deliver frictionless onboarding and micro-betting formats that expand casual gambler participation. Brazil and Mexico show the steepest expansion trajectory as mobile-native demographics bypass desktop entirely.
- Desktop:Larger screens support multi-tab in-play wagering and complex statistical analysis tools. Professional gamblers and high rollers maintain preference for desktop interfaces where simultaneous event monitoring drives decision quality.
- Tablet:Intermediate form factor captures home-based casual sessions without full desktop commitment.
- Smart TV:Emerging interface for communal viewing-integrated wagering during major sporting events.
Desktop retains professional user concentration. Mobile is gaining share fastest across Latin American markets.
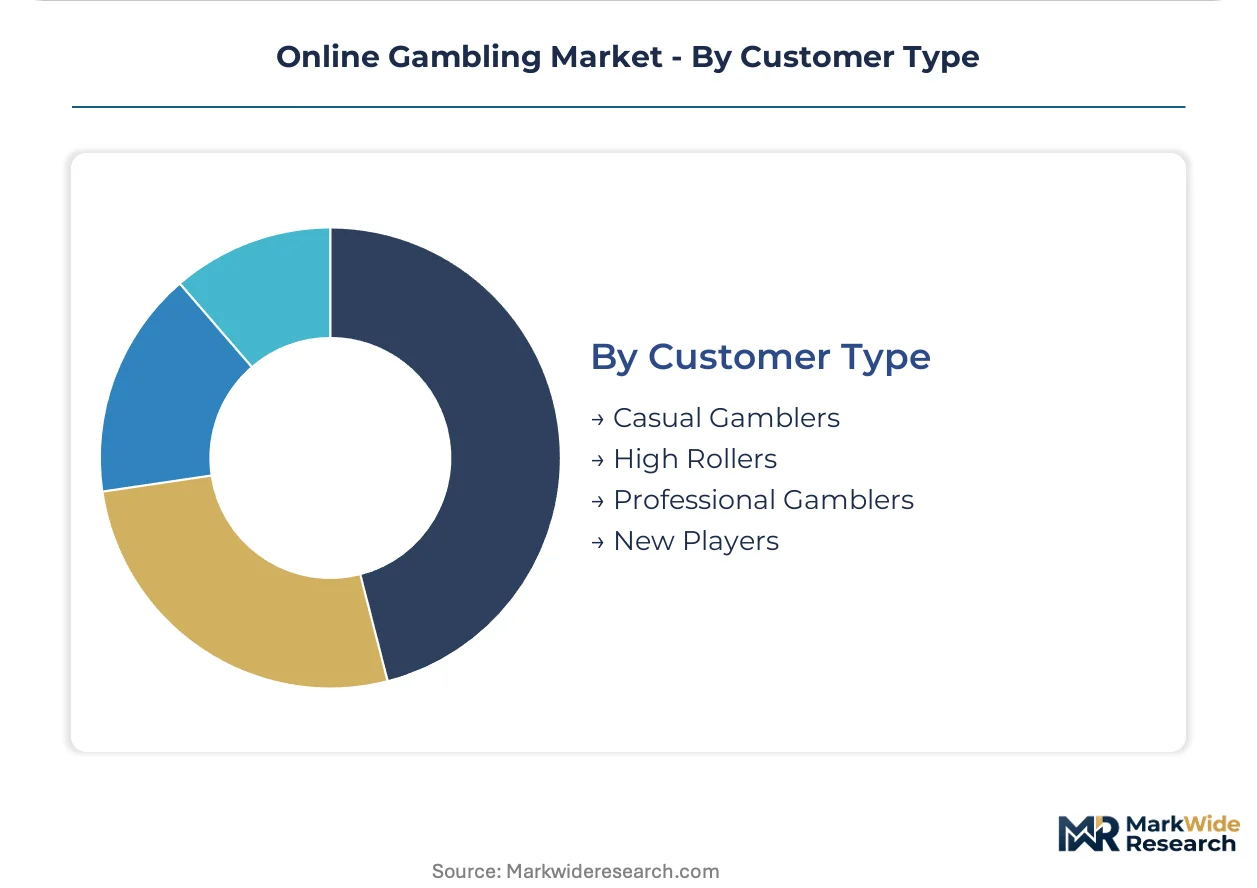
Customer Type:
Risk tolerance and session frequency create four distinct acquisition and retention economics.
- Casual Gamblers:Low-stakes, irregular participation driven by major sporting events or social engagement. Mobile sports betting apps in Brazil and Mexico target this cohort through simplified onboarding and micro-bet minimums.
- High Rollers:Large deposit velocity triggers EU AI Act-mandated automated monitoring for affordability checks. European operators deploy proprietary risk-detection algorithms to maintain compliance without excessive friction.
- Professional Gamblers:Positive expected-value players whose winnings compress operator margins. Geolocation verification and identity confirmation costs are amortized across lower per-user profitability.
- New Players:First-time depositors requiring responsible gaming education and cooling-off period protocols.
High Roller economics dominate revenue per user. New Player acquisition is expanding most quickly in recently regulated state markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London anchors European operator headquarters concentration, while São Paulo drives Latin American market expansion through state-level licensing waves.
United States
State-by-state authorization creates patchwork market access with New Jersey and Pennsylvania hosting dense operator clusters. The SEC monitors publicly traded gaming companies for financial disclosure compliance. DraftKings maintains Boston headquarters while pursuing state gaming control board approvals across the Midwest and Southeast.
Brazil
SPA lottery secretariat licensing unlocks Latin America's largest addressable digital gambling population. The country's national gaming regulator enforces technical standards for geolocation verification and payment processing. São Paulo operators deploy mobile-first platforms targeting mobile-native demographics across the Southeast region.
United Kingdom
UK Gambling Commission affordability checks and advertising codes shape European compliance architecture. The Gambling Commission mandates self-exclusion registry integrations and deposit limit protocols. London hosts Entain and Flutter Entertainment headquarters, anchoring responsible gaming technology development for export markets.
Germany
Glücksspielneuregulierungsstaatsvertrag advertising restrictions favor less visible payment trails and subdued marketing approaches. The KBA and state-level regulators enforce divergent tax-rate structures across federal jurisdictions. Berlin and Hamburg operators navigate fragmented licensing timelines while adapting to EU AI Act algorithmic transparency requirements.
Australia
TGA and state gaming authorities impose strict in-play wagering restrictions and credit card deposit bans. The national regulator monitors advertising compliance during live sporting broadcasts. Melbourne and Sydney operators concentrate on sports betting liquidity pools while facing pressure from emerging responsible gaming mandates.
Online Gambling Market Vendor Landscape
Premium-margin players sit above commodity-margin players across proprietary technology differentiation and regulatory certification depth. Tier-one operators maintain consolidated positions through geographic diversification and modular compliance architectures. Three archetypes dominate: integrated platform owners with in-house risk-detection systems, pure-play sportsbook specialists with direct-to-consumer mobile apps, and B2B technology licensors supplying algorithmic player-monitoring tools. Competitive moves concentrate on strategic partnerships for market access and portfolio diversification into esports and social betting formats.
Within the integrated platform tier, Entain and Flutter Entertainment exemplify operators sustaining responsible gaming certifications across fragmented European and Americas jurisdictions. DraftKings occupies a distinct position as a North American specialist leveraging state-by-state regulatory momentum. These three companies represent divergent geographic diversification strategies while confronting common EU AI Act compliance cost pressures.
| Leading Market Players |
|---|
| Entain |
| Bet365 Group |
| Flutter Entertainment |
| Super Group |
| Betsson |
| DraftKings |
| Evoke |
| Kindred Group |
| Evolution Gaming |
| Others |
Supply Flow & Price Mechanics
Captive integration into proprietary risk-detection algorithm development anchors both supply positioning and pricing power for tier-one operators confronting EU AI Act compliance mandates. This vertical control over player-monitoring technology insulates premium operators from vendor certification delays while locking in margin structures that commodity-margin competitors cannot replicate.
Pricing Analysis
Outcome-based pricing tied to player lifetime value metrics anchors operator revenue models, with platforms charging transaction fees scaled to wagering velocity rather than flat subscription rates. Price differentiation stratifies across certification grade, with EU AI Act-compliant operators commanding premium positioning against uncertified competitors. Pricing pressure stems from state-level tax-rate fragmentation forcing margin compression in newly regulated markets. Casual gamblers exhibit highest price sensitivity to deposit minimums, while high rollers demonstrate inelastic demand for personalized limit structures.
Supply Chain Analysis
Random number generation certification rests on ISO/IEC 17025 laboratory testing capacity concentrated in the United Kingdom, Germany, and Australia. Core inputs span geolocation verification hardware, encrypted payment processing middleware, and neural network training datasets for behavioral risk scoring. Supply chain risk centers on single-source vulnerability in explainable AI tooling procurement for EU algorithmic transparency mandates. Distribution runs through direct-to-consumer mobile app stores and white-label B2B platform licensing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
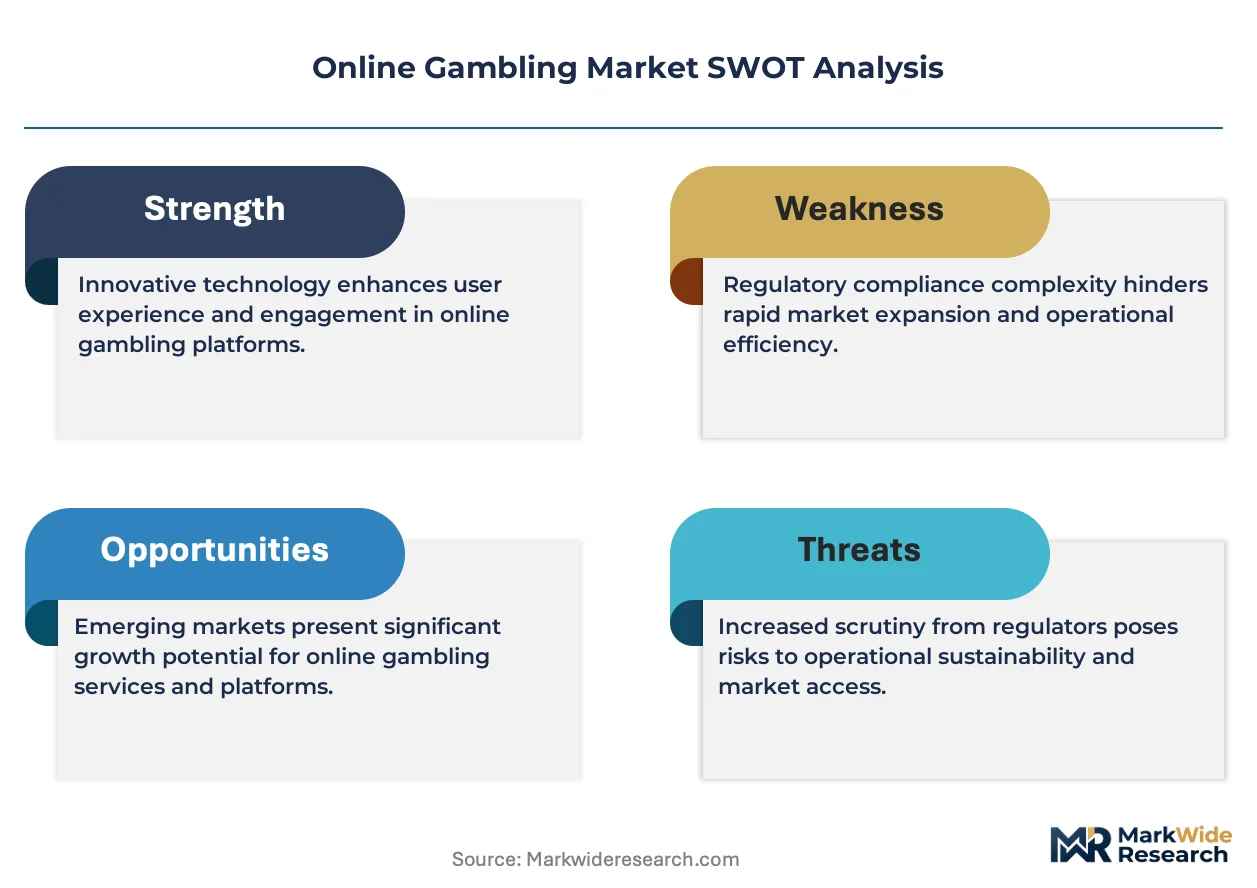
This market reads as a cost-of-compliance story where EU AI Act algorithmic transparency requirements erect barrier-to-entry moats favoring operators with pre-built certification architectures.
For Market Incumbents: Acquire specialized machine learning engineering teams to fortify proprietary risk-detection capabilities against fintech-sector talent poaching. Consolidate position through backward integration into geolocation verification infrastructure, reducing dependency on third-party authentication vendors facing state gaming control board approval bottlenecks. For New Entrants and Emerging Players: White-label platform providers offer the most penetrable entry channel for operators lacking modular compliance architectures. Target Brazil's SPA-licensed market through mobile-first sports betting partnerships with established local payment processors. Pursue esports betting verticals where legacy operators maintain weaker product positioning among under-35 demographics. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated platform owners seeking geographic expansion. Long-term viability hinges on regulatory certification depth rather than user scale alone. Watch EU AI Act enforcement consistency as the critical inflection signal for compliance cost trajectories across European jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Risk-Detection Development | EU AI Act compliance mandates automated player-monitoring systems with explainable AI documentation. |
| Geographic Diversification | Brazil's SPA licensing unlocks Latin America's largest addressable digital gambling population. |
| Esports Betting Vertical Launch | Competitive video gaming wagering captures demographic migration from traditional casino formats. |
| Cryptocurrency Payment Integration | Blockchain settlement bypasses fiat banking restrictions in jurisdictions with limited card-network access. |
| Responsible Gaming Technology Licensing | Proprietary algorithms developed for EU compliance can be exported to newly regulated Latin American markets. |
Methodological Framework
Document review covered SEC filings from publicly traded gaming operators, UK Gambling Commission enforcement actions, and Brazil's SPA technical standards, complemented by interviews with platform engineering directors, regulatory compliance officers, and payment processing specialists. Secondary validation drew from state gaming control board licensing databases, ISO/IEC 17025 laboratory accreditation records, and EU AI Act implementation guidance. Bottom-up segment sizing triangulated against top-down market aggregation.
Market value and volume projections incorporate wagering transaction velocity, player acquisition cost trajectories, and regulatory licensing timeline assumptions across the analysis window. Segmentation modeling spans product type, payment method, device platform, and customer risk profile. CAGRs derive from historical state authorization patterns and mobile penetration curves calibrated against comparable market maturation sequences.
Several conditions sit outside the modeled scope, including unannounced regulatory enforcement actions, cryptocurrency payment method bans, and major sporting event cancellations. Forecasts reflect documented assumptions about state legislative session outcomes and EU AI Act implementation consistency. A small set of named triggers warrants ongoing watch: Brazil SPA licensing velocity, US state authorization waves, and algorithmic transparency standard adoption timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Europe Anime Merchandising Market
Digital Media
Projection Mapping Market
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
3D Anaglyph Glasses Market
Digital Media
United Kingdom Webtoons Market
Digital Media
Global Music Video Production Market
Digital Media
Art App Market
Digital Media
IP in Media and Entertainment Market
Digital Media
Digital Media Production Software Market
Digital Media
Global ACGN Market
Digital Media
Global Animation Market
Digital Media
Multichannel Network Market
Digital Media
Germany Animation, VFX and Post Production Market
Digital Media
Anime Streaming Tool Market
Digital Media
Information Short Video Market
Digital Media
Digital Music Content Market