
 Indoor LCD Advertising Players Market | 2026-2036
Indoor LCD Advertising Players Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor LCD Advertising Players Market Analytics
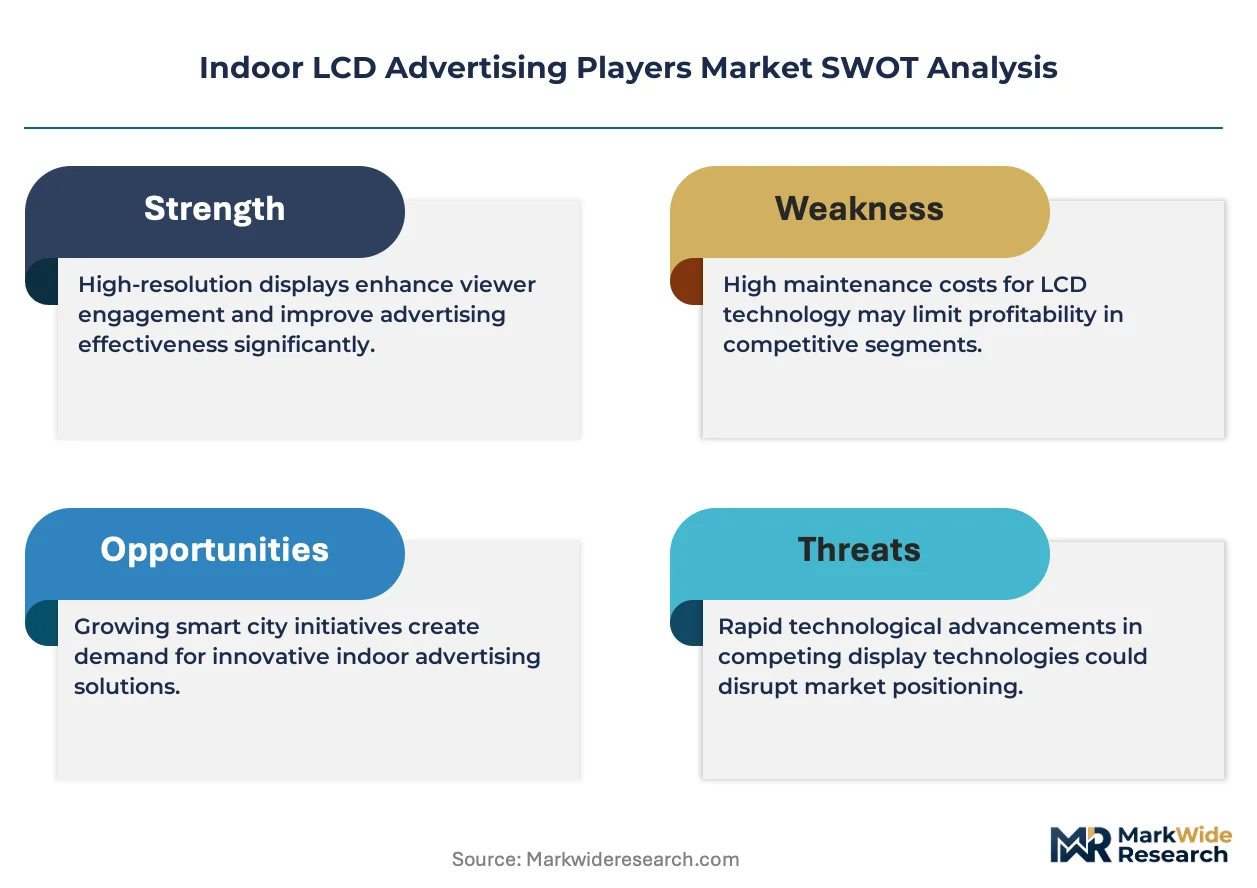
The gap between premium and commodity tiers is broadening. High-brightness, narrow-bezel configurations with integrated content management now command substantially different procurement budgets than basic loop-play units. Samsung Electronics leverages vertical integration across panel and system-on-chip production to sustain margin control at the premium end. LG Electronics anchors its position through OLED-adjacent LCD hybrid lines that differentiate on color performance. Barco specializes in mission-critical installations where reliability specifications dominate purchasing criteria.
Indoor LCD advertising players are commercial display systems built around thin-film-transistor liquid crystal panels, typically ranging from 32 to 98 inches diagonal with brightness ratings between 350 and 2500 nits, designed for continuous operation in climate-controlled environments where static or dynamic promotional content replaces traditional print media. Digital signage occupies the largest installed base among product type segments, though transparent displays represent the fastest-growing niche as retailers experiment with window-facing installations that preserve sightlines. Wall-mounted installations dominate volume due to lower total cost of ownership, while freestanding units capture disproportionate margin in high-traffic corporate and hospitality settings.
FCC equipment authorization requirements in the United States govern electromagnetic emissions from networked players, while the EU's CE marking and RoHS substance restrictions shape material selection and market access for imported units. China's GB standards for electronic display energy efficiency create compliance thresholds that filter lower-tier domestic assemblers from government and state-enterprise procurement channels. Stakeholders must monitor how fragmented certification requirements across major economies affect platform standardization and service interoperability.
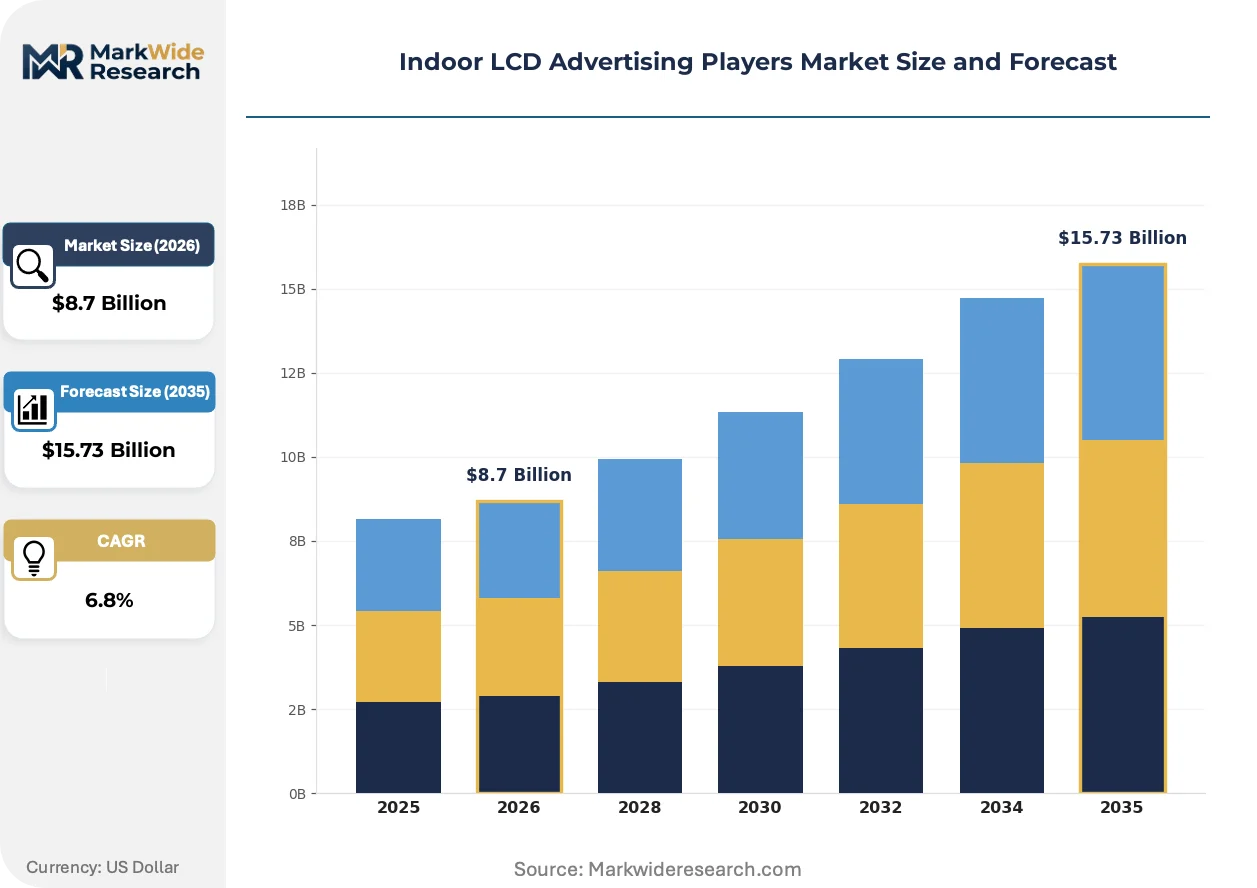
Market Dynamics
The Indoor LCD Advertising Players Market is experiencing structural compression as display panel commoditization collides with software-defined content management differentiation. Buyers now separate hardware procurement from content platform subscriptions, fragmenting vendor control over lifetime customer value.
Growth Catalysts
- Retail digital transformation mandates:Flagship store networks in the United States and Germany are replacing static signage with networked LCD arrays that enable real-time promotional adjustments.
- EU Ecodesign Directive:Energy efficiency thresholds for electronic displays are accelerating replacement cycles in European commercial installations.
- Transparent display glass bonding:Advanced optical bonding processes are enabling window-facing installations that preserve retail sightlines while delivering dynamic content.
Market Restraints
- Panel supply concentration:TFT-LCD substrate production clusters in South Korea and Taiwan create geographic vulnerability to regional disruption.
- LED direct-view substitution:Fine-pitch LED walls are capturing premium indoor applications above 150-inch equivalent viewing areas.
- RoHS substance compliance:EU restrictions on lead and cadmium in electronic components increase material qualification costs for imported units.
Strategic Opportunities
- India tier-two commercial districts:Shopping mall construction in cities like Pune and Ahmedabad is outpacing installed display infrastructure.
- Healthcare wayfinding systems:Hospital networks are deploying interactive LCD directories to replace static directional signage.
- China dual carbon policy:National energy efficiency targets are subsidizing low-power display retrofits in state-owned commercial properties.
Industry Challenges
- Embedded systems engineering shortage:Firmware development for SOC-integrated players lags hardware commoditization timelines.
- Multi-certification burden:Simultaneous FCC, CE, and GB standard compliance extends product launch cycles by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor LCD Advertising Players Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Signage, Transparent Displays, Video Walls, Outdoor Kiosks End User: Retail Stores, Corporate Offices, Restaurants, Airports Technology: LED, OLED, QLED, LCD Installation Type: Wall-mounted, Freestanding, Ceiling-mounted, Integrated Systems |
| Companies Covered | Samsung Electronics Co., Ltd., LG Electronics, Panasonic Corporation, Leyard, Daktronics, Barco, Unilumin, Absen, Liantronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor LCD Advertising Players Market Evolving Landscape
Display technology convergence with edge computing and computer vision is redefining what indoor advertising hardware delivers beyond passive content playback. The category is shifting from AV equipment to data-capture infrastructure.
Mini-LED backlighting is absorbing the brightness-performance gap between conventional LCD and emissive display technologies. Luxury automotive showrooms and high-end cosmetics retailers are adopting these configurations for color-critical product presentation. The technology is absorbing margin compression at the premium tier by justifying hardware premiums through demonstrable visual performance deltas.
The EU's Corporate Sustainability Reporting Directive is mandating embodied carbon disclosure for electronic equipment procurement above defined contract thresholds. Large retail chains must now document supply chain environmental impact across display hardware purchases. French and German multinational retailers are prioritizing vendors with ISO 14001-certified manufacturing facilities to preempt audit complexity.
Content management platform unbundling is separating hardware procurement from software subscription decisions. Corporate real estate teams now specify open-platform players compatible with multiple CMS providers rather than accepting vendor-locked ecosystems. This pattern is most pronounced in United States enterprise deployments where IT governance committees mandate interoperability standards.
Indoor LCD Advertising Players Market Segmentation
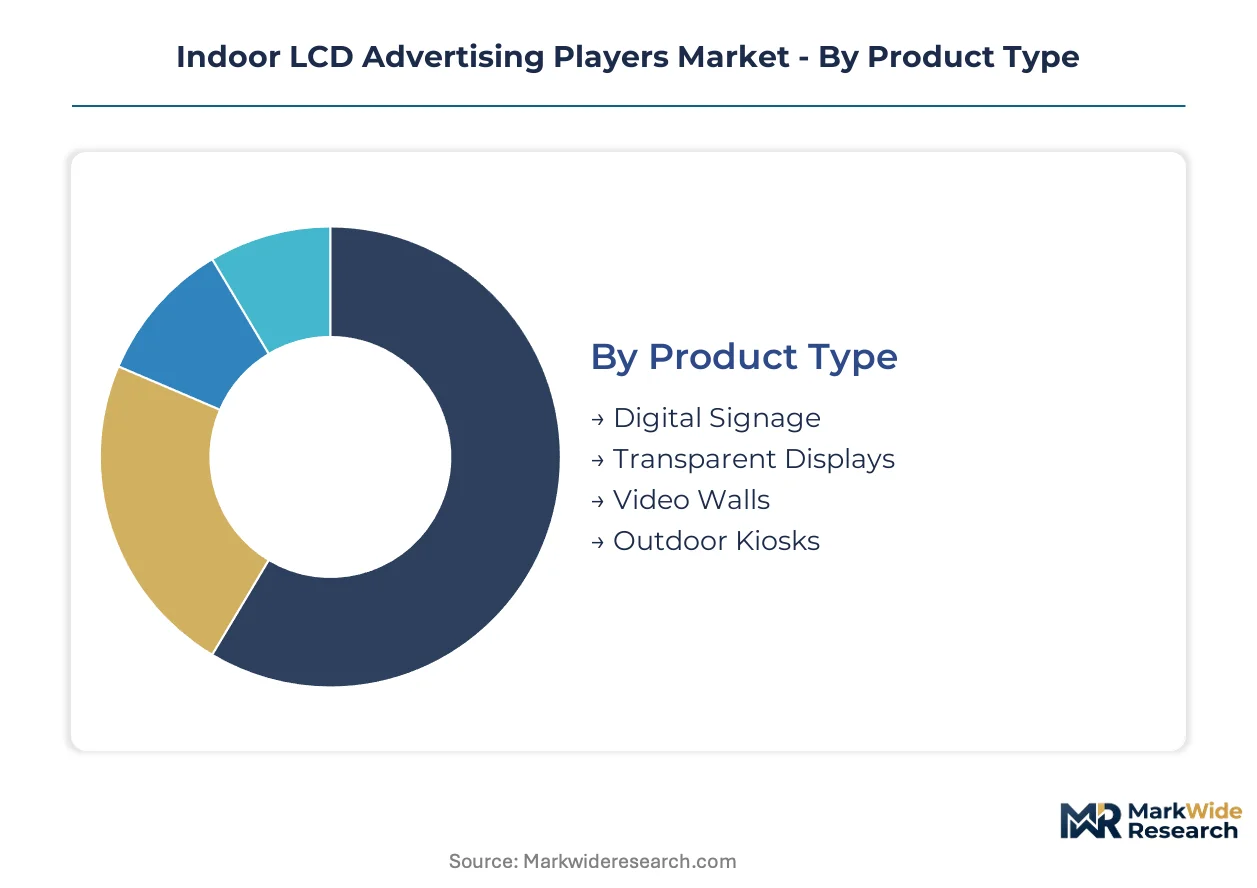
Segmentation in indoor LCD advertising players determines procurement workflows, service contracts, and total cost of ownership calculations. Buyers separate hardware specifications from content management requirements, creating distinct vendor selection criteria across product configurations and deployment environments.
Product Type:
Standalone units dominate retrofit installations where existing infrastructure limits integration depth, while embedded systems penetrate new construction where developers pre-wire advertising infrastructure during build-out.
- Digital Signage:Networked LCD panels with integrated media players and remote management capabilities, typically 43 to 75 inches diagonal. Retail chains in the United States and Germany are replacing static signage with these networked arrays that enable real-time promotional adjustments based on inventory data.
- Transparent Displays:LCD panels with partial light transmission enabling window-facing installations that preserve retail sightlines. China's tier-one commercial districts are absorbing these units as property developers pre-install advertising infrastructure in new retail complexes to maximize lease premiums.
- Video Walls:Tiled multi-panel configurations for large-format visual impact.
- Outdoor Kiosks:Weather-hardened interactive units for exterior deployment.
Volume placements concentrate in Digital Signage; the faster expansion belongs to Transparent Displays.
End User:
Customer procurement sophistication varies sharply, with enterprise real estate teams separating hardware from software decisions while independent retailers accept bundled vendor ecosystems.
- Retail Stores:Flagship networks demand high-brightness, narrow-bezel configurations with open-platform CMS compatibility. EU Ecodesign requirements are pushing these buyers toward lower-power panel architectures that accelerate replacement cycles in European installations.
- Corporate Offices:High-traffic lobby and conference installations prioritize freestanding units with premium finishes. FCC equipment authorization requirements govern electromagnetic emissions from networked players in United States deployments, extending product qualification timelines.
- Restaurants:Menu board and promotional display applications.
- Airports:Wayfinding and advertising concession networks.
Procurement volume clusters in Retail Stores; margin capture concentrates in Corporate Offices.
Technology:
Display technology selection tracks brightness requirements, color accuracy demands, and energy efficiency thresholds across deployment environments.
- LED:Direct-view emissive technology capturing premium indoor applications above 150-inch equivalent viewing areas. Fine-pitch LED walls are displacing LCD in luxury automotive showrooms where color-critical product presentation justifies hardware premiums.
- OLED:Self-emissive panels with perfect black levels and wide viewing angles. LG Electronics anchors market position through OLED-adjacent LCD hybrid lines that differentiate on color performance in high-end cosmetics retail.
- QLED:Quantum dot-enhanced LCD configurations.
- LCD:Thin-film-transistor liquid crystal panels forming the installed base majority.
LCD retains volume dominance; OLED commands the steepest expansion trajectory in premium tiers.
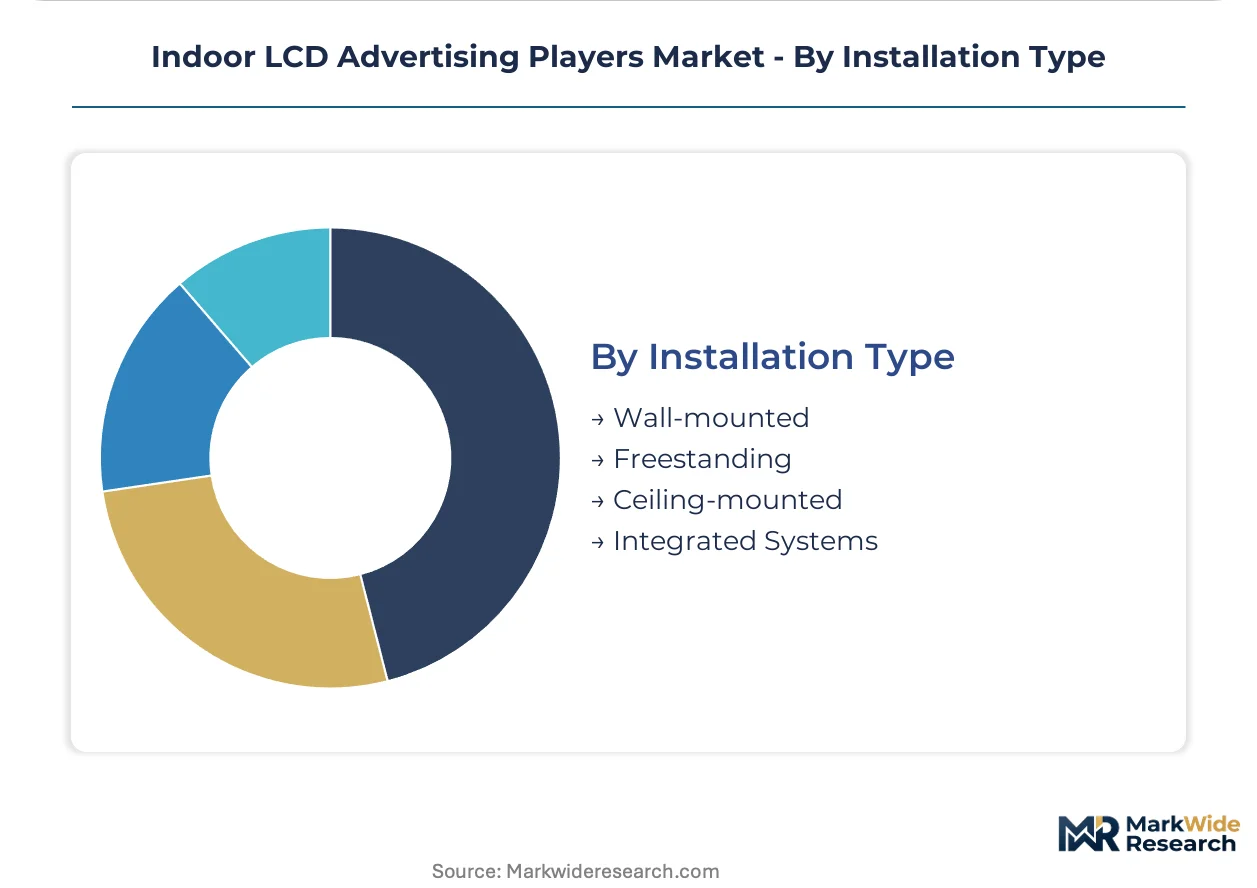
Installation Type:
Mounting configuration determines total cost of ownership, with integrated systems requiring specialized contractor relationships while standard mounts enable competitive sourcing.
- Wall-mounted:Standard bracket installations dominating volume due to lower hardware and labor costs. India's tier-two commercial districts in cities like Pune and Ahmedabad are absorbing these units as shopping mall construction outpaces installed display infrastructure.
- Freestanding:Kiosk and totem configurations capturing disproportionate margin in high-traffic corporate and hospitality settings. These units require reinforced flooring and power trenching that extend deployment timelines.
- Ceiling-mounted:Suspended installations for wayfinding and directional applications.
- Integrated Systems:Custom architectural embedments requiring millwork coordination.
Wall-mounted configurations absorb unit volume; Freestanding systems extract premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors procurement activity for indoor LCD advertising players, with the city's display panel foundries and system integrators feeding retail infrastructure buildouts across China's tier-one commercial districts.
United States
Flagship store networks in Manhattan and Los Angeles are replacing static signage with networked LCD arrays that enable real-time promotional adjustments. FCC equipment authorization requirements govern electromagnetic emissions from networked players, extending product qualification timelines by 4-8 months. Dallas-Fort Worth and Atlanta retail corridors are absorbing wall-mounted installations as shopping mall construction outpaces installed display infrastructure.
Germany
Corporate real estate teams in Frankfurt and Munich prioritize freestanding units with premium finishes for high-traffic lobby installations. The EU's Ecodesign Directive establishes energy efficiency thresholds for electronic displays, accelerating replacement cycles in European commercial installations. Bavaria's automotive showrooms are adopting high-brightness configurations for color-critical product presentation.
China
Property developers in Shanghai and Beijing pre-install advertising infrastructure in new retail complexes to maximize lease premiums. GB standards for electronic display energy efficiency create compliance thresholds that filter lower-tier domestic assemblers from government procurement channels. The Yangtze River Delta manufacturing cluster supplies transparent display glass bonding for window-facing installations.
India
Shopping mall construction in Pune and Ahmedabad is outpacing installed display infrastructure, creating absorption opportunities for wall-mounted configurations. The Bureau of Indian Standards certification requirements shape material selection for imported units entering commercial channels. Mumbai's corporate headquarters conversions are driving demand for open-platform players compatible with multiple content management systems.
Japan
Luxury cosmetics retailers in Tokyo's Ginza district are adopting OLED-adjacent LCD hybrid lines that differentiate on color performance. METI energy efficiency guidelines influence procurement specifications for state-owned commercial properties. Osaka's healthcare networks are deploying interactive LCD directories to replace static directional signage in hospital wayfinding systems.
Indoor LCD Advertising Players Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the indoor LCD advertising players market, with integrated panel manufacturers sustaining margin control through captive supply chains while specialist assemblers compete on customization velocity. The vendor base separates into three tiers: premium-tier specialists commanding hardware premiums through visual performance differentiation, mid-tier system integrators bundling hardware with content management subscriptions, and commodity assemblers competing on unit cost for standardized loop-play configurations. Dominant competitive moves include backward integration into panel and system-on-chip production to defend manufacturing economics, and geographic expansion into underpenetrated tier-two commercial districts to capture first-mover positioning.
Within the premium-tier vector, Samsung Electronics Co., Ltd. exemplifies the vertically integrated archetype through its control across panel and semiconductor production. LG Electronics occupies a position representing display technology diversification strategies, while Barco sits within the mission-critical installation specialists tier where reliability specifications dominate purchasing criteria.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Electronics |
| Panasonic Corporation |
| Leyard |
| Daktronics |
| Barco |
| Unilumin |
| Absen |
| Liantronics |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up display integrators now control substantial procurement volume across North American retail chains, tightening payment terms for panel assemblers while extracting volume rebates that compress upstream margins. This ownership concentration feeds back into supply chain decisions, as consolidated buyers demand captive production capacity commitments from Taiwanese and South Korean substrate foundries.
Pricing Analysis
Uptime guarantees anchor value-based pricing for mission-critical installations in healthcare and corporate lobby deployments. Three-tier pricing structure across premium, standard, and economy levels separates narrow-bezel high-brightness configurations from basic loop-play units. Price differentiation hinges on ISO 14001 certification status and integrated CMS platform bundling. Cost compression in commodity tiers is intensifying because panel oversupply from Chinese Gen 10.5 fabs floods spot markets. Independent retailers exhibit highest price sensitivity; flagship corporate real estate teams prioritize interoperability over unit cost.
Supply Chain Analysis
TFT-LCD glass substrate supply rests on Corning's precision fusion draw capacity in Kentucky and South Korea, with secondary sourcing from AGC and Nippon Electric Glass in Japan. TFT backplane fabrication draws from Taiwan Semiconductor Manufacturing and Samsung Display foundries in South Korea and China. Polarizer films and driver ICs feed from Japanese and Taiwanese specialty chemical producers. Single-source vulnerability concentrates in Gen 8.5+ motherglass capacity, where earthquake exposure in Taiwan's Hsinchu Science Park threatens regional output. Distribution runs through Shenzhen-based system integrators for Asia-Pacific, with Rotterdam and Los Angeles hubs serving European and North American retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gen 8.5+ TFT-LCD motherglass capacity constraints in Taiwan and South Korea prop pricing discipline, as display panel foundries prioritize long-term supply agreements over spot market exposure.
For Market Incumbents: To counter LED direct-view substitution in premium indoor applications above 150-inch viewing areas, Samsung Electronics and LG Electronics should deepen backward integration into system-on-chip design to defend firmware differentiation. Captive supply of Mini-LED backlighting components from Taiwanese specialist foundries secures color-critical performance tiers against commoditization. For New Entrants and Emerging Players: Enter via India's tier-two commercial districts in Pune and Ahmedabad, where shopping mall construction outpaces installed display infrastructure and procurement standards remain fluid. Target open-platform CMS compatibility as the primary go-to-market angle, as corporate IT governance committees in Mumbai and Bangalore mandate interoperability standards that legacy vendors struggle to meet. For Investors and Strategic Acquirers: China's dual carbon policy subsidy disbursement acceleration is the leading indicator that low-power display retrofit demand will concentrate in state-owned commercial properties. Over the medium-term horizon, vertically integrated panel producers with ISO 14001-certified manufacturing facilities command acquisition premiums from European retail chains facing CSRD-mandated embodied carbon disclosure. Watch transparent display glass bonding yield rates as the signal for window-facing installation cost curves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SOC Design | Firmware differentiation defends premium positioning against LED substitution in automotive showrooms. |
| Transparent Display Glass Bonding Scale-Up | Advanced optical bonding from Yangtze River Delta suppliers enables window-facing retail installations. |
| Open-Platform CMS Certification | Interoperability compliance unlocks United States enterprise procurement governed by IT governance committees. |
| ISO 14001 Manufacturing Certification | Environmental audit readiness preempts French and German retailer supply chain disclosure requirements. |
| Tier-Two Geographic Expansion | First-mover positioning in India's Pune and Ahmedabad corridors captures mall construction absorption gaps. |
Research Methodology
Document review covered SEC 10-K filings from display equipment manufacturers, EU Ecodesign Directive implementation guidance, and China's GB standards documentation, complemented by interviews with commercial real estate technology procurement directors, retail chain visual merchandising executives, display panel foundry operations managers, and healthcare facilities wayfinding system integrators. Secondary validation drew from FCC equipment authorization databases, customs trade data for TFT-LCD substrate movements, and Shenzhen electronics manufacturing cluster export records. Bottom-up unit shipment estimates triangulated against top-down display panel area consumption forecasts.
Historical panel pricing trajectories cross-referenced against primary interview input on procurement budget cycles and replacement timelines. Segmentation modeling tracked product type, installation configuration, end-use vertical, and regional regulatory cluster throughout the forecast period. CAGRs derived from fitted trend extrapolation validated against panel foundry capacity expansion announcements and retail square footage construction permits. Industry-specific inputs included Mini-LED backlighting adoption curves in luxury automotive showrooms and transparent display yield rate improvements from Chinese optical bonding specialists.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Taiwan seismic disruption or EU Ecodesign threshold acceleration scenarios. Projections reflect assumptions on panel commoditization velocity and software-platform unbundling persistence. A small set of named triggers warrants ongoing watch: Gen 10.5+ fab utilization rates, LED fine-pitch cost parity milestones, and India's BIS certification requirement enforcement timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Digital Ad Spending Market
Advertising and Marketing Media
Europe Public Relation Services Market
Advertising and Marketing Media
Brand Licensing Market
Advertising and Marketing Media
Latin America Programmatic Advertising Market
Advertising and Marketing Media
Spain OOH and DOOH Market
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
Native Video Advertising Market
Advertising and Marketing Media
Indonesia OOH and DOOH Market
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
Thailand OOH and DOOH Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Nigeria OOH and DOOH Market
Advertising and Marketing Media
India OOH and DOOH Market
Advertising and Marketing Media
Argentina OOH and DOOH Market
Advertising and Marketing Media
Programmatic Advertising Market
Advertising and Marketing Media
Italy OOH and DOOH Market