
 Australia OOH and DOOH Market | 2026-2036
Australia OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Australia OOH and DOOH Market Insights
Digital screen networks across Australian transit hubs is fragmenting as programmatic buying and real-time data integration redraw legacy media planning. oOh!media leverages its airport and retail precinct dominance to sustain premium inventory rates, while JCDecaux Australia anchors its position through exclusive street furniture contracts with major metropolitan councils. QMS Media competes aggressively in the roadside billboard segment, extending its reach into regional arterial corridors.
Out-of-home and digital out-of-home advertising encompasses physical and electronic display media deployed in public spaces to deliver brand messaging to audiences outside their homes, with digital screens utilizing LED and LCD technologies operating at luminance levels between 1500 and 5000 nits for daylight visibility. The primary commercial purpose centers on capturing consumer attention during transit, dwell, and purchase-intent moments across urban environments. Digital screens command disproportionate margin pools due to dynamic creative capabilities and programmatic addressability, while street furniture remains a mature, contract-secured revenue base. Transit advertising represents the fastest-expanding channel as rail and bus network digitization accelerates audience measurement precision.
ACCC advertising standards enforcement shapes competitive conduct around misleading claims in health and financial services campaigns displayed on DOOH networks. Australian Classification Board content guidelines intersect with TGA therapeutic goods regulations to restrict pharmaceutical messaging on public digital displays, creating compliance complexity for media owners. Local council planning schemes under state environmental laws further constrain billboard placement and illumination thresholds in residential zones. Stakeholders must monitor the convergence of privacy law reform with location data collection practices embedded in programmatic DOOH platforms.
Market Dynamics
Programmatic trading infrastructure is collapsing the traditional reservation-based inventory model across Australian out-of-home networks, forcing media owners to restructure yield management systems and sales operations around real-time bidding protocols.
Growth Catalysts
- Transit network digitization:Rail and bus infrastructure upgrades across Sydney and Melbourne are expanding addressable digital inventory. Transport for New South Wales and Public Transport Victoria procurement frameworks favor connected screen deployments.
- ACCC consumer protection enforcement:Stricter substantiation requirements for health and financial advertising are elevating DOOH's trusted environment status. Premium inventory commands verification advantages over unregulated digital channels.
- Data management platform integration:Telstra and Optus mobile network data feeds enable audience measurement precision. Location-based targeting capabilities attract performance advertisers from programmatic display budgets.
Market Restraints
- LED module supply concentration:Australian media owners depend on Chinese and South Korean display component suppliers. Shipping bottlenecks and semiconductor allocation constraints extend deployment timelines.
- Local council planning friction:State environmental planning instruments in New South Wales, Victoria, and Queensland impose illumination caps and setback requirements. Approval processes for new roadside structures extend 18-24 months.
- Static billboard residual value:Legacy paper-and-vinyl infrastructure retains contractual obligations through 2028-2030. Sunk capital in non-digital assets slows network-wide conversion economics.
Strategic Opportunities
- Regional arterial corridor expansion:Queensland and Western Australia highway digitization programs remain underpenetrated. Transport infrastructure budgets in Brisbane and Perth prioritize smart city connectivity.
- Retail media network convergence:Woolworths and Coles in-store screen networks create hybrid grocery-DOOH inventory pools. First-party purchase data integration enables closed-loop attribution.
- TGA regulatory clarity:Therapeutic Goods Administration guidance on pharmaceutical DOOH advertising establishes compliant creative frameworks. Specialist health agencies gain competitive differentiation through certification.
Industry Challenges
- Programmatic talent scarcity:DOOH-specific trading desk expertise remains concentrated in Sydney. Regional media sales teams lack technical fluency in demand-side platform operations.
- Legacy CMS integration:Proprietary content management systems from 2015-2019 hardware generations resist API standardization. Multi-vendor network consolidation requires middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia OOH and DOOH Market |
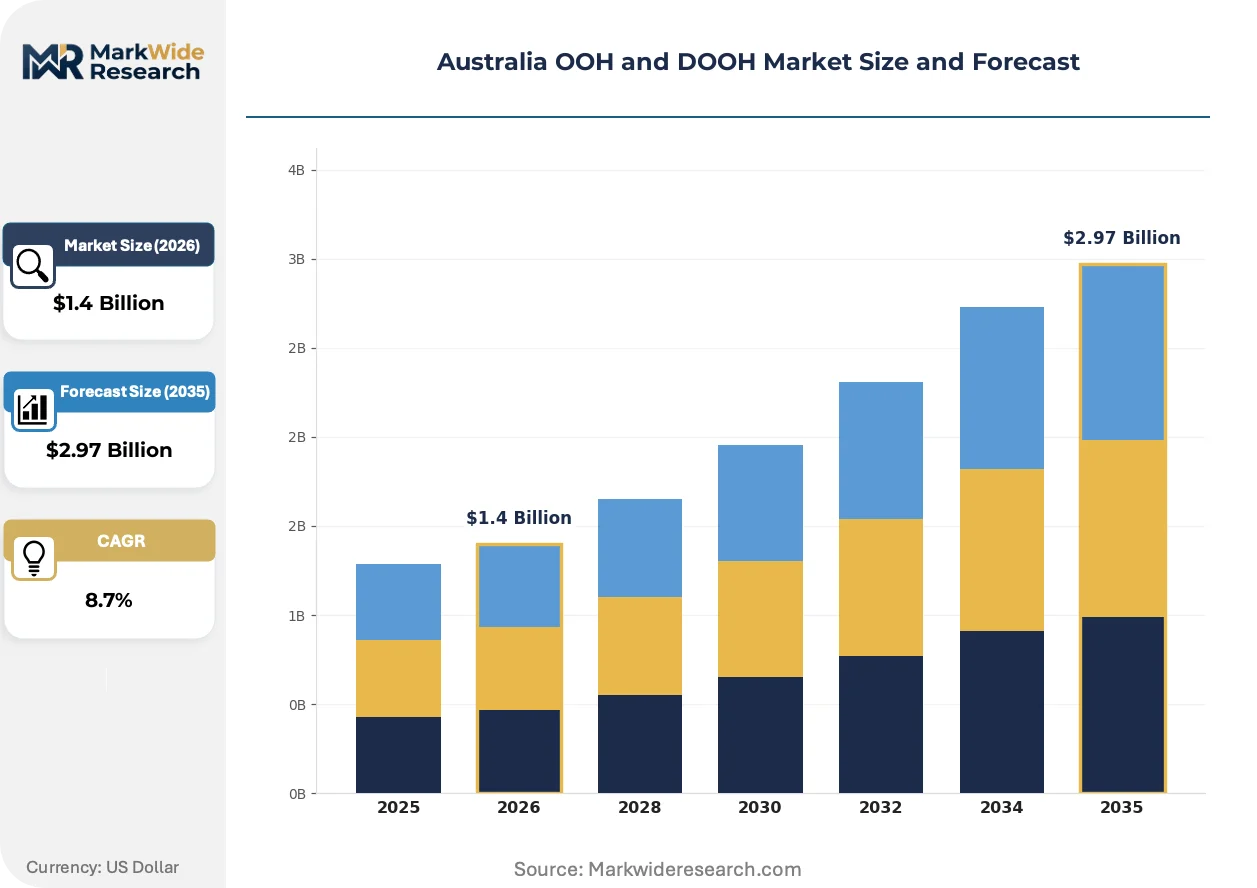
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Format Type: Billboards, Bus Shelters, Digital Screens, Posters Media Channel: Outdoor Advertising, Digital Out-of-Home, Transit Advertising, Street Furniture Target Audience: Commuters, Tourists, Event Attendees, Local Residents Campaign Duration: Short-term, Long-term, Event-based, Seasonal |
| Companies Covered | oOh!media, JCDecaux Australia, QMS Media, VMO, Scentre Group, Tonic Health Media, Shopper Media Group, Bishopp Outdoor, Perion, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia OOH and DOOH Market Trends and Innovations
Dynamic creative optimization and privacy-preserving measurement protocols are restructuring how advertisers evaluate out-of-home effectiveness. Three developments dominate strategic planning.
Dynamic creative adaptation technology is collapsing the production cost barrier between national and localized campaigns. QMS Media and oOh!media deploy frame-by-frame content triggering based on weather, traffic, and sports data feeds. Retail advertisers now execute hundred-variant creative rotations without incremental studio costs.
TGA therapeutic goods advertising codes intersect with Australian Classification Board content guidelines to create layered compliance architecture. Pharmaceutical advertisers face mandatory pre-approval for disease-awareness messaging on public digital displays. Media owners invest in legal review workflows to maintain premium health sector access.
Advertiser buying committees now mandate outcome-based verification for DOOH commitments displacing legacy reach-and-frequency planning. Path-to-purchase attribution models using loyalty card and mobile location data reshape budget allocation between transit and retail formats. FMCG verticals in Sydney and Melbourne pilot sales lift measurement tied to specific screen exposures.
Australia OOH and DOOH Market Segmentation
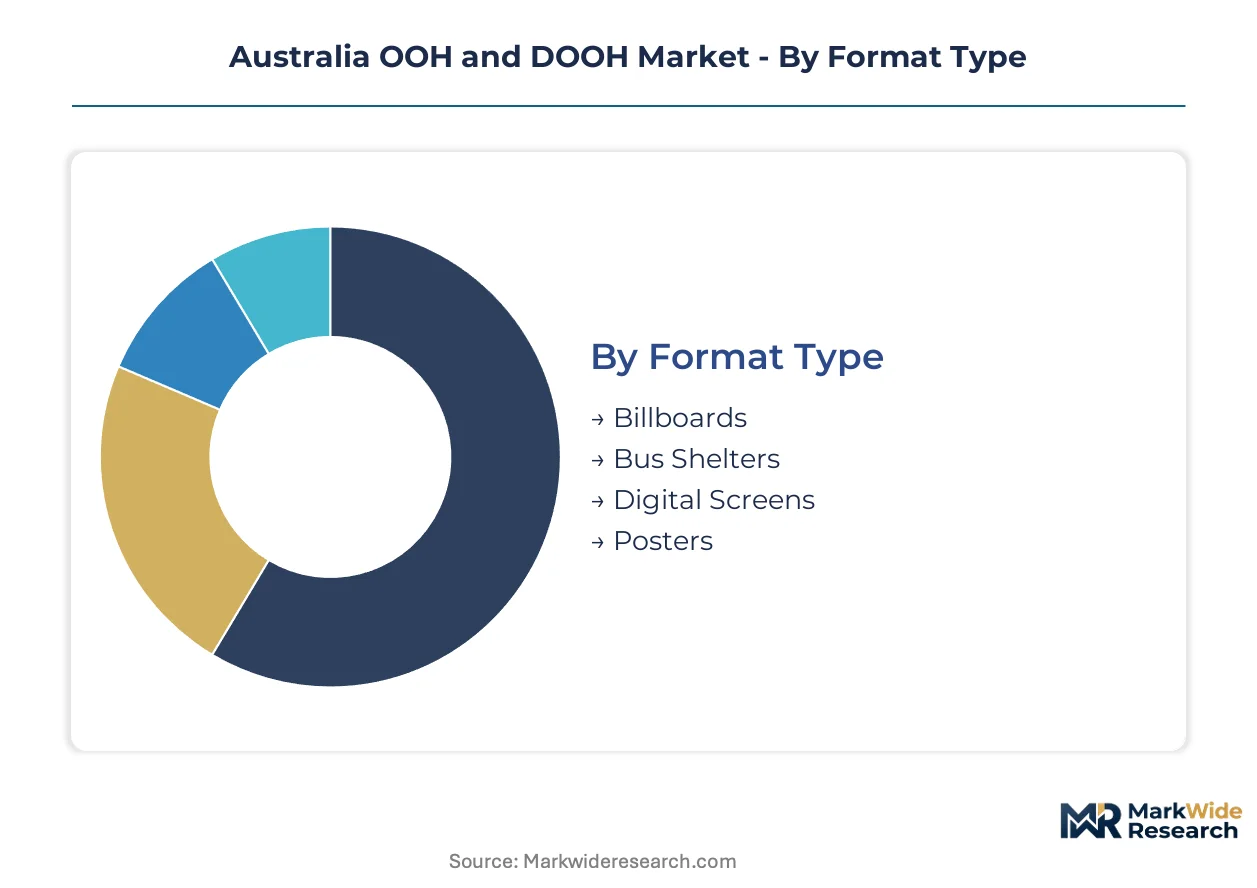
Format differentiation determines capital deployment intensity and yield management complexity across Australian OOH networks. Media owners optimize inventory mix between static legacy assets and programmable digital estates to capture divergent advertiser budgets.
Format Type:
Cost tier stratification separates premium digital installations from standardized static placements across metropolitan and regional markets.
- Billboards:Large-format roadside structures spanning 6x3m to 12x6m dimensions dominate arterial corridor visibility. Demand concentrates along Sydney's M1 motorway and Melbourne's Tullamarine Freeway where traffic density sustains premium rate cards. TGA advertising codes constrain health messaging creative approval timelines.
- Digital Screens:LED and LCD displays operating 1500-5000 nits luminance enable programmatic trading and dynamic creative rotation. Sydney CBD and Melbourne's Bourke Street Mall concentrate advertiser investment due to dwell-time metrics and audience measurement precision.
- Bus Shelters:Street furniture formats integrate illuminated displays with municipal transit infrastructure. Local council planning schemes in New South Wales and Victoria govern placement density and illumination thresholds.
- Posters:Paper-and-vinyl formats retain contractual obligations through legacy media plans. Regional Queensland and Western Australia depend on these assets where digital conversion economics remain unfavorable.
Billboards command the established base. The steepest expansion runs through Digital Screens.
Media Channel:
Application context determines audience mindset and creative effectiveness across transit, roadside, and retail environments.
- Outdoor Advertising:Roadside and highway formats capture attention during commute patterns. Brisbane's Pacific Motorway and Perth's Mitchell Freeway anchor state-level campaign distribution.
- Digital Out-of-Home:Programmatic addressability attracts performance advertisers from online display budgets. ACCC substantiation requirements elevate trust metrics for financial services campaigns.
- Transit Advertising:Rail and bus network digitization accelerates across Sydney Metro and Melbourne's suburban rail loop. Transport for New South Wales procurement frameworks favor connected screen deployments with real-time content management.
- Street Furniture:Council-secured contracts provide revenue stability through exclusive metropolitan agreements. JCDecaux Australia maintains dominant positioning via long-term municipal partnerships.
Street Furniture commands the established base. Transit Advertising is gaining share fastest.
Target Audience:
Customer type segmentation aligns inventory selection with path-to-purchase moments and dwell-time characteristics.
- Commuters:Rail and bus passengers exhibit predictable daily patterns enabling frequency capping and sequential messaging. Sydney's North Shore line and Melbourne's Frankston corridor deliver concentrated white-collar audiences.
- Tourists:International and domestic visitors concentrate in airport precincts and central city accommodation zones. oOh!media's airport network captures this transient demographic with extended dwell intervals.
- Event Attendees:Stadium and exhibition center audiences enable contextual creative around sports and entertainment programming. Melbourne Cricket Ground and Sydney Olympic Park anchor major event inventory.
- Local Residents:Neighborhood-level targeting supports retail and services advertising in suburban shopping precincts. Woolworths and Coles in-store networks intersect with this segment.
Commuters command the established base. Tourists show the steepest expansion trajectory.
Campaign Duration:
Volume commitment structures separate always-on brand building from tactical promotional activation.
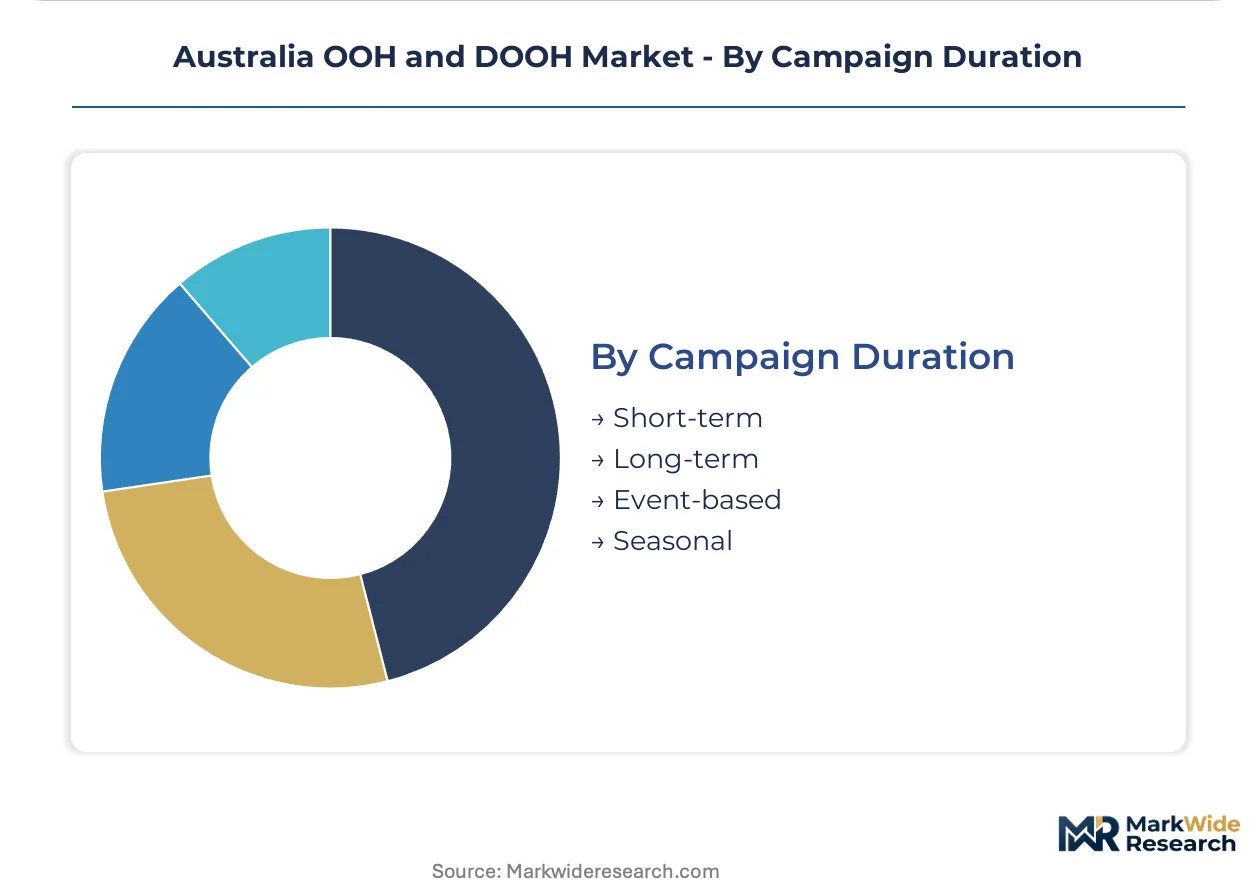
- Short-term:Burst campaigns spanning 1-4 weeks support product launches and competitive response. FMCG verticals in Sydney and Melbourne pilot sales lift measurement for brief exposure windows.
- Long-term:Annual or multi-year contracts secure preferred inventory positions and rate stability. Automotive and telecommunications categories dominate this commitment tier.
- Event-based:Fixed-duration activations align with sports finals, cultural festivals, and political cycles. Australian Open and AFL Grand Final command premium surcharges.
- Seasonal:Retail calendars drive Q4 and mid-year promotional intensity. Christmas and EOFY periods concentrate revenue recognition.
Long-term commitments command the established base. Short-term buying is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TGA therapeutic goods regulations and ACCC consumer protection standards anchor market development across Australia's eastern seaboard. State environmental planning instruments create divergent approval pathways for digital screen deployment.
New South Wales
Sydney's central business district and North Shore rail corridor concentrate premium digital inventory investment. Transport for New South Wales procurement frameworks mandate connected screen specifications with real-time content management capability. Parramatta's western Sydney transformation generates new transit advertising nodes along the Metro West alignment.
Victoria
Melbourne's suburban rail loop and Bourke Street Mall precinct anchor demand for high-dwell-time digital formats. Public Transport Victoria infrastructure budgets prioritize digitized station environments with audience measurement integration. The Frankston corridor and Tullamarine Freeway sustain roadside billboard premiums through traffic density metrics.
Queensland
Brisbane's Pacific Motorway and emerging smart city connectivity programs drive arterial corridor digitization. State planning instruments under the Queensland Development Code impose illumination thresholds for residential zone proximity. Gold Coast and Sunshine Coast tourism corridors attract event-based advertising around seasonal visitor flows.
Western Australia
Perth's Mitchell Freeway and Elizabeth Quay redevelopment anchor metropolitan OOH investment. Western Australian Planning Commission schemes extend approval timelines for new roadside structures through environmental assessment requirements. Regional mining corridor traffic sustains static billboard economics where digital conversion remains unfavorable.
Australia OOH and DOOH Market Competitive Landscape
Vertically integrated national networks and specialist regional operators split the market between premium metropolitan inventory and cost-efficient geographic coverage. The competitive structure consolidates around exclusive municipal contracts and proprietary transit concessions. Three archetypes dominate: airport-retail conglomerates with diversified venue portfolios, street furniture specialists securing long-term council partnerships, and roadside billboard aggregators pursuing regional scale. Dominant competitive moves center on exclusive procurement wins with state transport authorities and backward integration into content management platform development.
Among established national operators, oOh!media, JCDecaux Australia, and QMS Media occupy positions representing distinct strategic archetypes. oOh!media exemplifies the diversified venue model through airport and retail precinct concentration. JCDecaux Australia anchors the street furniture specialist tier via metropolitan council relationships. QMS Media represents the roadside-scale archetype with arterial corridor penetration. These three entities collectively illustrate how contract exclusivity, venue type specialization, and geographic coverage depth define competitive positioning in this regulated procurement environment.
| Leading Market Players |
|---|
| oOh!media |
| JCDecaux Australia |
| QMS Media |
| VMO |
| Scentre Group |
| Tonic Health Media |
| Shopper Media Group |
| Bishopp Outdoor |
| Perion |
| Others |
Pricing and Supply Chain Analysis
Shenzhen and Seoul LED module clusters anchor Australian media owners' procurement economics, with display component lead times stretching deployment schedules and compressing installation margins across Sydney and Melbourne premium inventory tiers.
Pricing Analysis
Sydney CBD digital screen rates command multiples over Perth roadside equivalents, reflecting traffic density and audience measurement precision. Three-tier pricing structure across premium programmatic, standard reserved, and economy static placements separates inventory value pools. Cost compression in regional static assets is intensifying because digital conversion economics remain unfavorable outside eastern seaboard transit corridors. FMCG advertisers in metropolitan markets exhibit lowest price sensitivity due to closed-loop attribution capabilities, while regional retail buyers negotiate aggressively on legacy paper-and-vinyl commitments.
Supply Chain Analysis
Extended payment terms from Chinese and South Korean display manufacturers have become standard procurement practice, with supply-chain finance facilities bridging working capital gaps for Australian media owners. LED module production draws from China, South Korea, and Taiwan, while aluminum extrusion and steel fabrication rest on domestic Australian suppliers. Single-source vulnerability concentrates in semiconductor driver ICs from Taiwanese foundries. Distribution runs through direct manufacturer relationships for major network operators, with regional specialists dependent on distributor intermediaries for spare parts and maintenance inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australian OOH and DOOH market is recovering from cyclical infrastructure investment lows, with Transport for New South Wales and Public Transport Victoria procurement cycles driving replacement demand across digitized transit networks.
For Market Incumbents: Entrench exclusive municipal contracts through proactive smart city connectivity integration, extending JCDecaux Australia's street furniture model into regional Queensland and Western Australia council partnerships. Backward integration into proprietary content management platforms defends against middleware standardization threats from programmatic trading infrastructure. Capacity addition in Brisbane and Perth arterial corridors captures state infrastructure budget allocations before competitive bidding intensifies.
For New Entrants and Emerging Players: Western Australia's mining corridor static inventory represents the most penetrable white-space target, where digital conversion economics have stalled incumbent network-wide upgrades. Retail media network convergence through Woolworths and Coles in-store screen partnerships offers alternative venue access without council procurement friction. Specialist health agency certification under TGA guidance frameworks enables premium sector differentiation without direct billboard asset competition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified venue operators with airport-retail-transit portfolios over pure-play roadside aggregators, as audience measurement precision and programmatic addressability reshape advertiser budget allocation. Long-term viability hinges on exclusive procurement wins with state transport authorities and first-party data integration capabilities. The signal to watch is Transport for New South Wales and Public Transport Victoria connected screen specification changes, which would accelerate hardware replacement cycles and consolidate vendor relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Transit Procurement Wins | Transport for New South Wales frameworks mandate real-time content management, locking in multi-year revenue streams. |
| Proprietary CMS Platform Development | Backward integration overcomes legacy 2015-2019 hardware API standardization barriers. |
| Retail Media Network Convergence | Woolworths and Coles first-party purchase data enables closed-loop attribution for FMCG advertisers. |
| Regional Arterial Corridor Expansion | Queensland and Western Australia highway digitization programs remain underpenetrated by premium operators. |
| TGA Compliance Certification Investment | Therapeutic Goods Administration guidance creates specialist health agency differentiation in pharmaceutical advertising. |
Research Methodology
Desk research of ACCC enforcement records, Transport for New South Wales procurement frameworks, and TGA therapeutic goods advertising codes preceded structured interviews with media owners' yield management directors, programmatic trading desk heads, and state transport authority procurement officers. Secondary validation drew from local council planning scheme databases, Australian Classification Board content guideline publications, and LED display manufacturer technical specifications. Bottom-up inventory counts across Sydney, Melbourne, Brisbane, and Perth transit and roadside networks triangulated against top-down advertiser spend allocation estimates from media agency planning directors.
Assumptions around Transport for New South Wales and Public Transport Victoria digitization timelines, ACCC substantiation requirement enforcement intensity, and Chinese LED module supply availability were held fixed across baseline scenarios, with tariff exposure and semiconductor allocation volatility tested in sensitivity runs. The analytical framework modeled format type, media channel, target audience, and campaign duration segmentation throughout the forecast period. CAGRs derived from network deployment pipeline analysis and advertiser budget shift patterns from programmatic display to DOOH channels, incorporating Telstra and Optus mobile data feed integration timelines as audience measurement precision inputs.
Practitioners should monitor Transport for New South Wales procurement specification revisions and TGA therapeutic goods advertising code updates for early signals of demand inflection or compliance cost escalation. Forecasts reflect assumptions around transit network digitization pace and programmatic trading infrastructure maturity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Multiscreen Advertising Market
Advertising and Marketing Media
Mobile Advertising Market
Advertising and Marketing Media
United States OOH and DOOH Market
Advertising and Marketing Media
Smart Advertising Market
Advertising and Marketing Media
Asia Pacific Programmatic Advertising Market
Advertising and Marketing Media
Germany OOH and DOOH Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
Saudi Arabia OOH and DOOH Market
Advertising and Marketing Media
North America Public Relation Services Market
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
GCC OOH and DOOH Market
Advertising and Marketing Media
Native Video Advertising Market
Advertising and Marketing Media
Singapore OOH and DOOH Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market