
 Digital Media Production Software Market | 2026-2036
Digital Media Production Software Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Media Production Software Market Analysis
The digital media production software landscape is pivoting around a widening capability gap between studio-grade suites and lightweight creator tools. Adobe Inc. leverages its Creative Cloud ecosystem to anchor enterprise post-production workflows across film and broadcast clients. Blackmagic Design Pty Ltd competes through aggressive hardware-software bundling that controls price-sensitive professional segments. Wondershare Technology Co Ltd occupies the independent creator tier with simplified interfaces that lower skill barriers for social media content production.
Digital media production software encompasses applications for nonlinear video editing, multi-track audio processing, motion graphics generation, and composited visual effects, typically operating through GPU-accelerated rendering engines and timeline-based project architectures. The primary commercial purpose is to transform raw captured media into finished content for theatrical release, broadcast transmission, or digital distribution. Video editing and visual effects segments lead current revenue generation due to sustained investment from streaming services and advertising agencies, while cloud-based deployment models represent the fastest-growing structural category as remote collaboration requirements reshape infrastructure procurement. Subscription-based licensing has displaced perpetual licenses as the dominant monetization architecture across both enterprise and independent creator tiers.
The Federal Communications Commission shapes broadcast technical standards that influence software feature requirements for U.S.-based production houses, while the European Union's AI Act imposes transparency obligations on automated content generation tools that vendors must embed. ISO standards for media file interoperability constrain proprietary format strategies and drive API integration priorities. Stakeholders must monitor how emerging export control frameworks on AI training data affect cross-border collaboration features in cloud-native platforms.
Market Dynamics
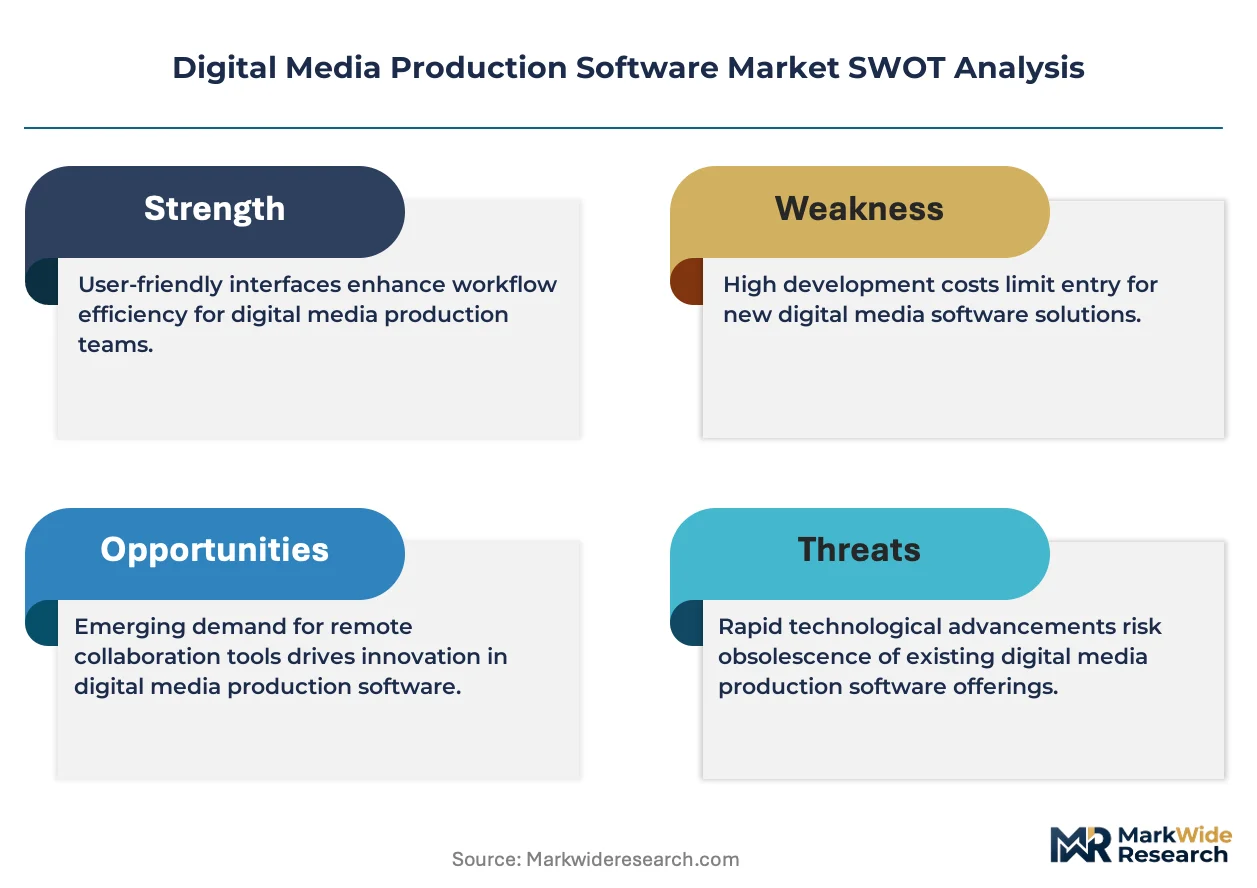
Cloud-native production pipelines are compressing traditional hardware-software bundling advantages while AI-assisted editing tools reshape skill requirements across post-production workflows. The transition from perpetual licenses to subscription architectures is redistributing vendor revenue timing and customer switching costs.
Growth Catalysts
- EU AI Act transparency mandates:Automated content generation tools face disclosure requirements that create compliance software demand from European production houses seeking audit-ready pipelines.
- GPU-accelerated rendering:Real-time ray tracing capabilities in nonlinear editing suites enable independent creators to produce broadcast-quality output without dedicated render farms.
- South Korean content exports:Streaming platform investment in K-drama and K-pop production drives specialized software procurement for multi-language dubbing and localized visual effects.
Market Restraints
- NVIDIA GPU supply concentration:Rendering engine performance depends on single-source graphics hardware, exposing production schedules to semiconductor foundry capacity constraints.
- ISO file format interoperability requirements:Proprietary codec strategies face standardization pressure that limits vendor differentiation and compresses premium pricing power.
- Open-source compositing alternatives:Blender Foundation tools erode entry-level pricing tiers for motion graphics and 3D animation segments.
Strategic Opportunities
- India post-production outsourcing:English-language content localization and VFX compositing services create demand for collaborative cloud platforms with rupee-denominated pricing tiers.
- Spatial audio for immersive formats:Dolby Atmos and Ambisonics workflows converge with game engine pipelines to serve virtual production stages and interactive streaming content.
- FCC broadcast technical standards updates:Next-generation television transmission requirements mandate HDR and wide color gamut support that forces infrastructure refresh cycles.
Industry Challenges
- AI-assisted editing skill displacement:Traditional assistant editor roles face compression as automated rough-cut generation reduces entry-level pipeline positions.
- Cross-platform project portability:Timeline interchange between competing suites requires complex XML translation that fragments collaborative workflows across vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Media Production Software Market |
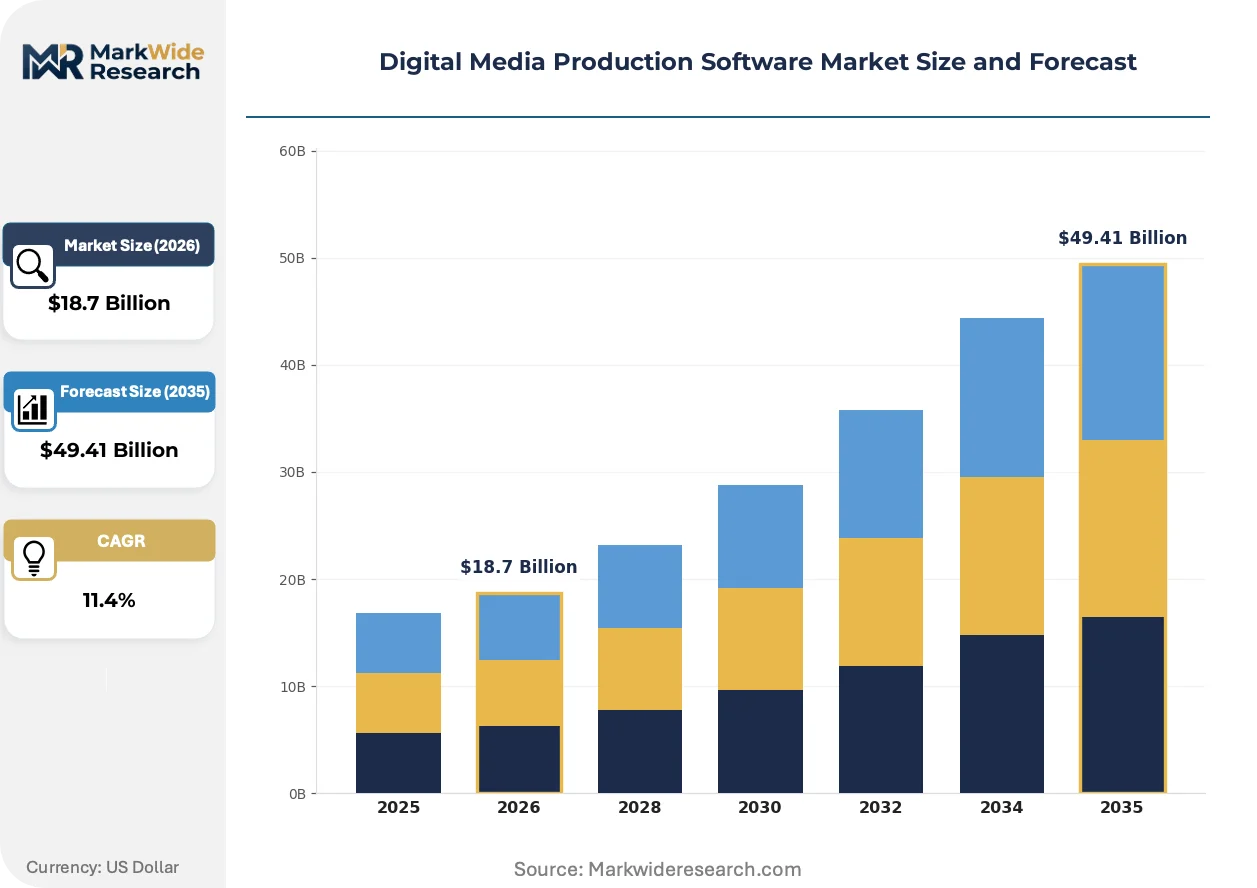
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Editing, Audio Editing, Animation, Visual Effects Deployment Model: On-Premises, Cloud-Based, Hybrid, Subscription-Based End User: Broadcast Industry, Film Production, Advertising Agencies, Independent Creators Integration Level: API Integrations, Standalone Solutions, Plugin Support, Cross-Platform Compatibility |
| Companies Covered | Adobe Inc., Apple Inc., Autodesk Inc., Avid Technology Inc., Blackmagic Design Pty Ltd, CyberLink Corp., Wondershare Technology Co Ltd, Corel Corporation, Maxon Computer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Media Production Software Market Emerging Trajectories
Generative AI capabilities are embedding directly into timeline interfaces, transforming content creation from frame-by-frame manipulation to prompt-driven iteration. This shift compresses production cycles while raising new questions about creative authorship and output consistency.
Neural rendering engines are rewriting the economics of photorealistic visual effects. These systems synthesize imagery from scene descriptions rather than traditional polygon-based computation. Major streaming platforms deploy them for virtual production stages to reduce location shooting costs. The technology is compressing the boundary between pre-visualization and final pixel delivery.
The EU AI Act imposes documentation requirements on automated editing tools that generate or manipulate video content. Vendors must embed provenance tracking and disclosure mechanisms into export workflows. European advertising agencies and broadcasters face the steepest compliance timelines, accelerating procurement of audit-ready platforms over unmodified legacy suites.
Subscription fatigue among independent creators is fragmenting license commitment patterns. Users rotate between monthly plans based on project phases rather than maintaining continuous Creative Cloud-style memberships. This behavior concentrates in the United States and United Kingdom, where creator economy density supports niche tool specialization and price-sensitive switching.
Digital Media Production Software Market Segmentation
Segmentation in digital media production software reveals how vendor architecture choices align with diverging customer technical maturity and infrastructure investment profiles. The four-dimensional structure below maps where integration depth, deployment flexibility, and end-use specialization create distinct competitive arenas.
Product Type:
Integration depth varies sharply across product categories, with some functioning as embedded pipeline components and others operating as standalone creative environments.
- Video Editing:Nonlinear timeline systems with GPU-accelerated playback engines form the core production layer for streaming platforms and broadcast chains. Demand clusters with advertising agencies in the United Kingdom and film production houses in South Korea, where compressed delivery schedules reward real-time collaborative workflows.
- Visual Effects:Node-based compositing and particle simulation tools require render farm integration or cloud burst capacity for final output. Streaming service investment in original content drives procurement from Los Angeles and London VFX clusters, though NVIDIA GPU supply constraints periodically stall facility expansion timelines.
- Audio Editing:Multi-track DAWs with spectral editing and spatial audio mixing capabilities.
- Animation:2D vector-based and 3D rigging systems for character motion and procedural environments.
Volume placements concentrate in Video Editing; the faster expansion belongs to Visual Effects.
Deployment Model:
Cost tier stratification separates enterprise infrastructure commitments from variable-opex approaches favored by project-based studios.
- Cloud-Based:Browser-accessible timelines with centralized asset management enable distributed teams across Mumbai post-production houses and Berlin advertising boutiques. The EU AI Act compliance requirements accelerate European procurement of audit-ready cloud platforms over self-managed infrastructure.
- Subscription-Based:Monthly or annual license tiers with feature-gated access and continuous update streams. Independent creators in the United States rotate between plans based on project phases, fragmenting vendor revenue predictability.
- On-Premises:Perpetual licenses with local hardware dependency for security-sensitive or latency-critical workflows.
- Hybrid:Split architectures combining local editing stations with cloud rendering and archival storage.
Cloud-Based solutions are gaining share fastest; On-Premises retains the largest installed base among legacy broadcast facilities.
End User:
Application intensity differs by end user type, with some segments demanding full pipeline integration and others requiring isolated tool specialization.
- Film Production:Studio tentpole releases require end-to-end color grading, visual effects, and mastering suites with theatrical delivery specifications. Major streaming platform content budgets in Culver City and London Shepperton facilities sustain premium licensing tiers.
- Independent Creators:Solo operators and small collectives prioritize simplified interfaces and social media-optimized export presets. Wondershare and similar vendors capture this tier with rupee-denominated pricing for Indian YouTube networks and pound-sterling plans for UK TikTok creators.
- Broadcast Industry:Real-time news editing and live sports highlight packages with FCC technical standard compliance.
- Advertising Agencies:Rapid-turnaround commercial production with brand guideline enforcement and multi-format delivery.
Film Production commands the highest per-seat licensing values; Independent Creators represent the steepest expansion trajectory in absolute user numbers.
Integration Level:
Customer technical sophistication determines whether standalone tools or deeply embedded solutions dominate procurement decisions.
- API Integrations:REST and GraphQL endpoints connecting editing suites to MAM systems, review platforms, and AI services. Post-production houses in Toronto and Sydney build custom pipeline automation that locks in vendor relationships through integration investment.
- Cross-Platform Compatibility:Project interchange between macOS, Windows, and Linux workstations with timeline XML translation. Fragmented collaborative workflows result when teams split across Adobe, Blackmagic, and Avid ecosystems.
- Standalone Solutions:Self-contained applications without external dependency requirements for isolated workstation deployment.
- Plugin Support:Third-party extension architectures for specialized effects, codecs, and workflow enhancements.
API Integrations dominate enterprise procurement; Cross-Platform Compatibility faces persistent technical friction that constrains multi-vendor deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors the highest concentration of post-production infrastructure, with Culver City and Burbank facilities processing theatrical and streaming content. London, Seoul, and Mumbai follow as specialized clusters with distinct regulatory and demand profiles.
United States
Streaming platform investment in original content drives software procurement from Los Angeles and New York production houses. The FCC mandates HDR and wide color gamut support in broadcast technical standards, forcing infrastructure refresh cycles. Post-production clusters in Culver City and Atlanta sustain premium licensing tiers for studio tentpole releases.
South Korea
K-drama and K-pop exports create specialized demand for multi-language dubbing and localized visual effects tools. The Korea Communications Commission enforces broadcast content standards that influence software feature requirements. Seoul's Gangnam and Sangam-dong districts concentrate post-production facilities serving Netflix and Disney+ original productions.
United Kingdom
Advertising agencies in London and Manchester prioritize rapid-turnaround commercial production with multi-format delivery requirements. The EU AI Act imposes transparency obligations on automated content generation tools used by European production houses. Soho post-production clusters specialize in high-end color grading and finishing for international theatrical releases.
India
English-language content localization and VFX compositing services create demand for collaborative cloud platforms with rupee-denominated pricing. The Telecom Regulatory Authority of India shapes digital content distribution frameworks affecting software deployment models. Mumbai's Andheri and Hyderabad's HITEC City clusters process outsourced post-production for Western streaming platforms.
Germany
Berlin and Munich advertising boutiques drive procurement of audit-ready cloud platforms for EU AI Act compliance. The country's federal media regulator enforces content provenance documentation requirements on automated editing exports. Cologne broadcast technology clusters specialize in real-time sports highlight packages and live event production workflows.
Digital Media Production Software Market Vendor Landscape
Premium-margin players sit above commodity-margin players across integration depth and deployment flexibility. The vendor base organizes into three tiers: ecosystem-anchored suites, hardware-software bundlers, and independent creator tools. Strategic archetypes include full-stack platform providers, specialized workflow integrators, and price-disruptive entrants. Dominant competitive moves encompass cloud-native architecture transitions and AI capability embedding.
Within the ecosystem-anchored tier, Adobe Inc. exemplifies full-stack platform provision through Creative Cloud infrastructure. Blackmagic Design Pty Ltd occupies the hardware-software bundling archetype with aggressive price positioning. Wondershare Technology Co Ltd represents the independent creator tier with simplified interface approaches. These three companies illustrate how vendor architecture choices align with diverging customer technical maturity profiles.
| Leading Market Players |
|---|
| Adobe Inc. |
| Apple Inc. |
| Autodesk Inc. |
| Avid Technology Inc. |
| Blackmagic Design Pty Ltd |
| CyberLink Corp. |
| Wondershare Technology Co Ltd |
| Corel Corporation |
| Maxon Computer Inc. |
| Others |
Supply Flow & Price Mechanics
Enterprise-creator tier divergence separates Adobe Creative Cloud subscriptions from Wondershare's rupee-denominated perpetual licenses, with this bifurcation mapping directly onto NVIDIA GPU dependency for rendering performance and cloud burst capacity for elastic compute. South Korean post-production houses absorb premium pricing for real-time collaborative suites, while Indian localization vendors negotiate volume discounts on cloud-native platforms.
Pricing Analysis
Throughput-based pricing anchors enterprise licensing, where streaming platforms in Los Angeles and London negotiate per-project seats with render farm burst allowances. Subscription tiers stratify across studio-grade, professional, and independent creator levels, with brand premium and ISO 27001 certification status driving differentiation. Pricing pressure stems from Blender Foundation's open-source compositing tools eroding entry-level motion graphics margins. Independent creators exhibit highest price sensitivity, rotating between monthly plans based on production phases rather than maintaining continuous memberships.
Supply Chain Analysis
Skilled GPU kernel engineers cluster in Taiwan, South Korea, and the United States, constraining neural rendering engine development velocity for vendors outside these geographies. Supply chains draw from NVIDIA's foundry partnerships for graphics silicon, cloud hyperscaler data centers for elastic compute, and specialized codec licensing from Dolby and Fraunhofer. Single-source vulnerability concentrates in NVIDIA's CUDA ecosystem dominance for GPU-accelerated playback. Distribution runs through direct vendor portals and value-added resellers serving post-production facility clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native pipelines are displacing on-premises perpetual license infrastructure, with browser-accessible timelines and centralized asset management replacing workstation-bound workflows across advertising and broadcast segments.
For Market Incumbents: Cement ecosystem lock-in through API integration depth with media asset management systems and review platforms used by Toronto and Sydney post-production houses. Invest in backward integration into cloud rendering capacity to offset hyperscaler margin capture. Prioritize EU AI Act compliance documentation as a certification moat against unmodified legacy suites.
For New Entrants and Emerging Players: AI-assisted rough-cut generation offers entry into the compressed assistant editor segment where automated timeline assembly reduces headcount-dependent workflows. Target India's rupee-denominated localization services with collaborative dubbing and VFX compositing tools. Pursue direct-to-creator distribution through social media-optimized export presets and TikTok-integrated publishing pipelines.
For Investors and Strategic Acquirers: Re-rating potential sits with hybrid deployment specialists given FCC HDR mandate refresh cycles and EU AI Act compliance deadlines converging on infrastructure replacement windows. Long-term viability favors vendors with proven cloud burst economics and established MAM system partnerships. Monitor NVIDIA GPU supply allocation announcements as inflection indicators for facility expansion timelines and render farm utilization rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Transition | Browser-accessible timelines enable distributed teams across Mumbai and Berlin facilities. |
| AI Capability Embedding | Prompt-driven iteration compresses production cycles for streaming platform original content. |
| EU AI Act Compliance Integration | Provenance tracking mechanisms lock in European advertising agency procurement decisions. |
| Hardware-Software Bundling | GPU-accelerated playback engines control price-sensitive professional editor segments. |
| Geographic Pricing Localization | Rupee and pound-sterling tiers capture Indian YouTube networks and UK TikTok creators. |
Methodological Framework
Document review covered SEC filings from Adobe and Avid, EU regulatory guidance on AI Act implementation, and FCC broadcast technical standards, complemented by interviews with post-production facility technical directors, streaming platform content operations leads, advertising agency creative technologists, and independent creator economy participants. Secondary validation drew from hyperscaler capex disclosures, NVIDIA supply chain announcements, and ISO media interoperability specifications. Bottom-up segment sizing triangulated against top-down market aggregation.
Cross-referencing historical adoption curves with expert panel input on cloud migration timelines shaped the projection framework. Segmentation dimensions modeled include deployment model, end-user type, integration complexity, and regional regulatory cluster. CAGRs derived from elasticity-adjusted growth trajectories across subscription renewal rates and cloud seat expansion. Neural rendering adoption curves and spatial audio workflow penetration served as technology-specific forecast inputs.
Several conditions sit outside the modeled scope, including export control frameworks on AI training data affecting cross-border collaboration features, and semiconductor foundry capacity constraints beyond NVIDIA's GPU allocation. Forecasts reflect assumptions about streaming platform original content budget sustainability and creator economy density in target geographies. Material deviation in GPU supply availability or EU AI Act enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
China Webtoons Market
Digital Media
Webcomics Market
Digital Media
Video Content Management Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
Asia Pacific Photography Service Market
Digital Media
Europe Professional Audio Video (Proav) Market
Digital Media
Media Coding Service Market
Digital Media
Digital Content Creator Market
Digital Media
Music Rights Management Market
Digital Media
Blockchain in Media and Entertainment Market
Digital Media
Global Location-Based Entertainment Market
Digital Media
Asia-Pacific Webtoons Market
Digital Media
LED Stadium Screens Market
Digital Media
Drone Wedding Photography Market
Digital Media
Digital Content Creation Market
Digital Media
APAC Animation, VFX and Post Production Market