
 Multichannel Network Market | 2026-2036
Multichannel Network Market Size, Share, and Industry Trends Forecast 2026-2036
Multichannel Network Market Foresight
Platform bundling of monetization, analytics, and brand partnership tools is hardening as the default configuration for creator-facing networks. BBTV leverages its proprietary technology stack to manage thousands of channels across multiple genres. Studio71 anchors its competitive position through direct relationships with major entertainment studios and broadcast talent. Jellysmack specializes in cross-platform content optimization, converting YouTube-native formats for Facebook and Instagram distribution.
A multichannel network operates as an intermediary organization that aggregates digital content creators, provides centralized services including audience development, copyright management, ad sales, and brand sponsorship brokering, typically retaining a negotiated revenue share from creator earnings. These networks function on technology platforms processing petabytes of streaming data to match advertiser demand with creator supply in programmatic and direct-sold arrangements. Content Distribution and Monetization Solutions together capture the largest share of service revenue, while Audience Analytics represents the fastest-expanding margin pool as brands demand verified engagement metrics. YouTube dominates platform-type revenue given its mature Partner Program infrastructure, though Instagram and TikTok-competitive features on Facebook are gaining traction among lifestyle and commerce-oriented creators.
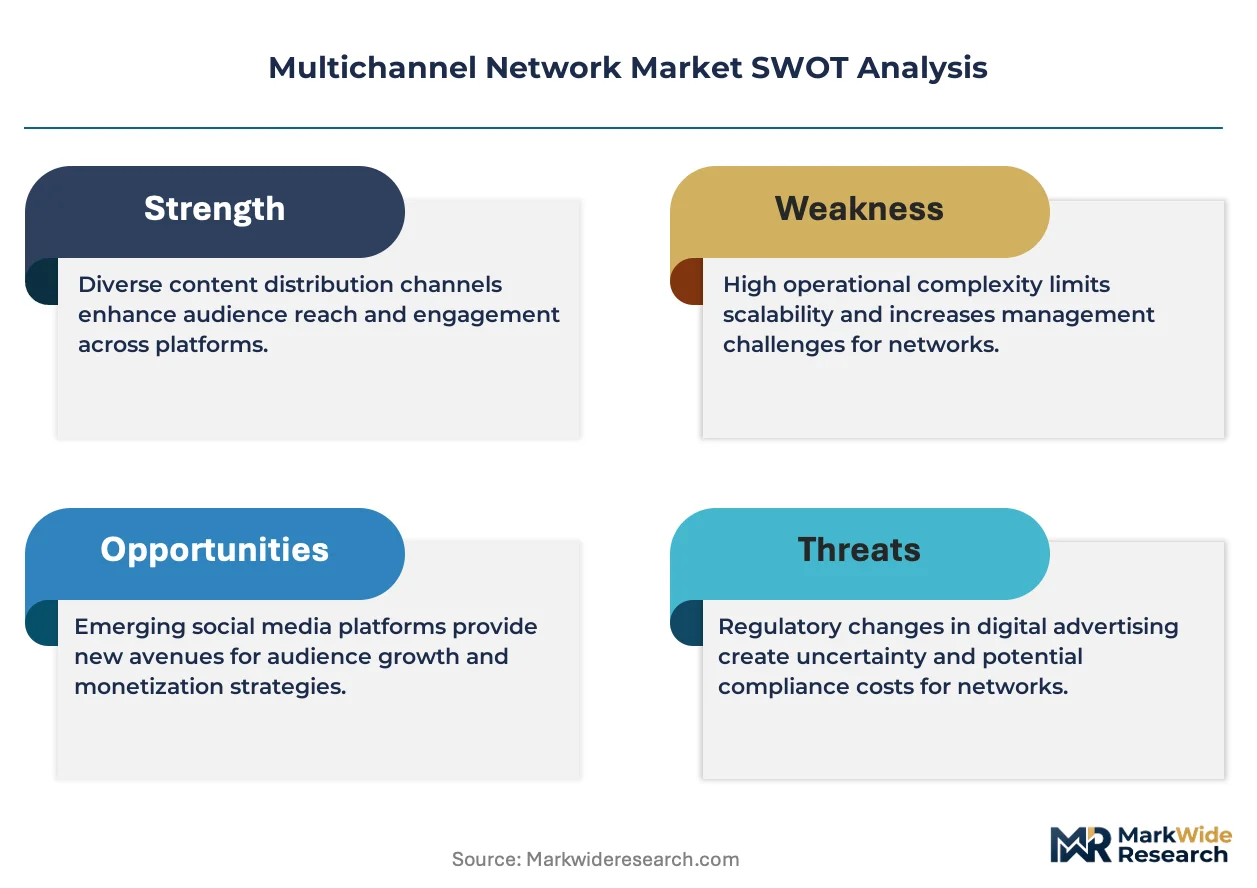
The Federal Trade Commission enforces disclosure requirements for sponsored content across US-based networks, while the EU Digital Services Act imposes systemic transparency obligations on platforms hosting network-affiliated creators. The UK's Competition and Markets Authority has scrutinized exclusivity clauses in creator contracts, pressuring networks toward more flexible terms. Stakeholders must monitor evolving platform algorithm changes and regulatory definitions of employment status for contracted creators, as these forces will determine network cost structures and competitive moats.
Market Dynamics
Platform algorithm volatility and creator employment classification disputes are restructuring network economics. Networks now face simultaneous pressure from TikTok's Creator Fund expansion and California's AB5-style contractor reclassification debates, forcing operational model reinvention.
Growth Catalysts
- Short-form video infrastructure:TikTok's monetization tools and Instagram Reels' revenue-sharing programs pull advertising budgets away from traditional display formats. Lifestyle and commerce creators migrate budgets accordingly.
- EU Digital Services Act transparency mandates:Systemic content moderation obligations force platforms to formalize creator verification standards. Networks with established compliance infrastructure capture displaced independent creators seeking administrative shelter.
- Live commerce integration:Southeast Asian markets demonstrate shoppable livestream viability. Networks with cross-platform streaming technology secure brand partnership premiums unavailable to single-platform operators.
Market Restraints
- Platform dependency concentration:YouTube's Partner Program policy changes determine 60-70% of network revenue exposure. Algorithm adjustments or demonetization waves propagate instantly through aggregated channel portfolios.
- Creator retention cost inflation:Exclusive talent contracts require escalating minimum guarantees and revenue share improvements. California labor classification litigation threatens to reclassify contracted creators as employees with benefit obligations.
- Measurement standard fragmentation:Cross-platform engagement metrics lack third-party verification consensus. Brand advertisers demand ISO-compliant audience measurement that few networks independently provide.
Strategic Opportunities
- Brazilian creator economy formalization:ANVISA and consumer protection frameworks mature for influencer marketing disclosure. Early network entrants establish localized compliance templates before regulatory enforcement intensifies.
- AI-assisted content localization:Automated dubbing and cultural adaptation tools enable YouTube-native creators to penetrate non-English Facebook and Instagram audiences without production cost multiplication.
- Connected TV distribution partnerships:FAST channel proliferation creates inventory demand for repurposed creator content. Networks with studio licensing relationships control premium archival libraries suited to ad-supported streaming.
Industry Challenges
- Cross-functional talent scarcity:Data science, platform policy expertise, and brand sales capabilities rarely coexist in single professionals. Networks compete for hybrid staff against pure-play technology and advertising firms.
- Legacy rights management infrastructure:Music licensing and third-party content claims automation remains technically immature. Manual dispute resolution consumes operational bandwidth that scales linearly with channel count.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multichannel Network Market |
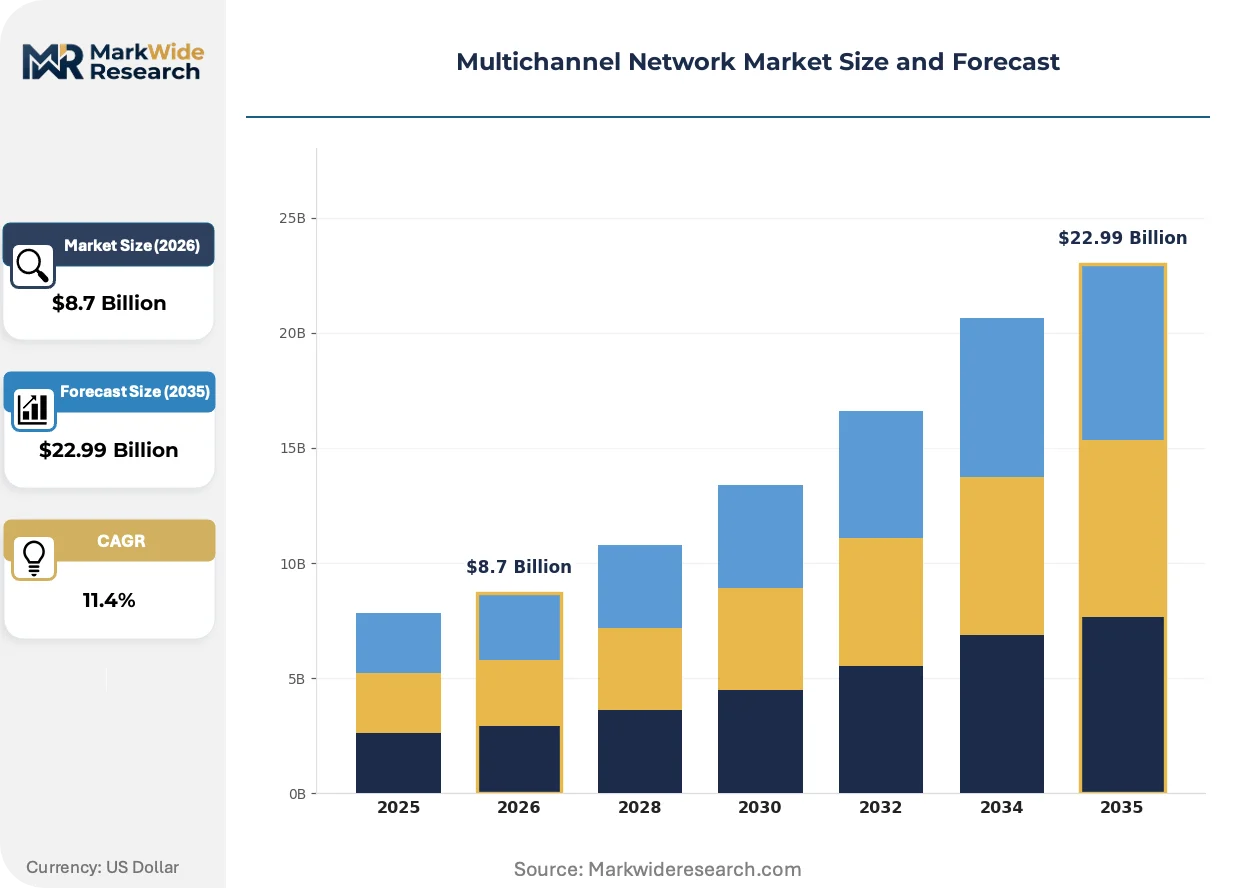
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Content Distribution, Monetization Solutions, Audience Analytics, Influencer Marketing Platform Type: YouTube, Twitch, Facebook, Instagram Customer Type: Creators, Brands, Advertisers, Agencies Content Category: Gaming, Vlogging, Education, Entertainment |
| Companies Covered | BBTV, Studio71, Fullscreen Media, Collab, Channel Frederator Network, Brave Bison, Yogscast Limited, Jellysmack, Gushcloud International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multichannel Network Market Shifts & Advancements
Creator-facing technology stacks are converging toward unified monetization, rights management, and cross-platform distribution platforms. This consolidation compresses vendor fragmentation while elevating technical capability thresholds for competitive participation.
AI-powered content optimization tools are consolidating previously separate functions of thumbnail generation, title A/B testing, and posting schedule optimization into single-dashboard workflows. Mid-tier networks with 500-2,000 channels adopt these suites most aggressively to offset headcount limitations. The technology is consolidating competitive differentiation around proprietary data assets rather than human editorial judgment alone.
The EU Digital Services Act's systemic transparency obligations require platforms to publish recommendation algorithm parameters and content moderation decision rationales. Networks operating across European territories must restructure internal compliance documentation and creator education programs. German and French regulatory authorities have initiated sector-specific guidance consultations affecting how networks structure cross-border talent representation agreements.
Brand procurement departments now mandate verified engagement metrics and brand-safety pre-screening before campaign commitment. Direct-sold sponsorship arrangements displace pure programmatic inventory purchases among Fortune 500 advertisers. This behavioral shift concentrates demand on networks with independent measurement partnerships and established content moderation infrastructure, visible most acutely in US and UK market negotiations.
Multichannel Network Market Segmentation
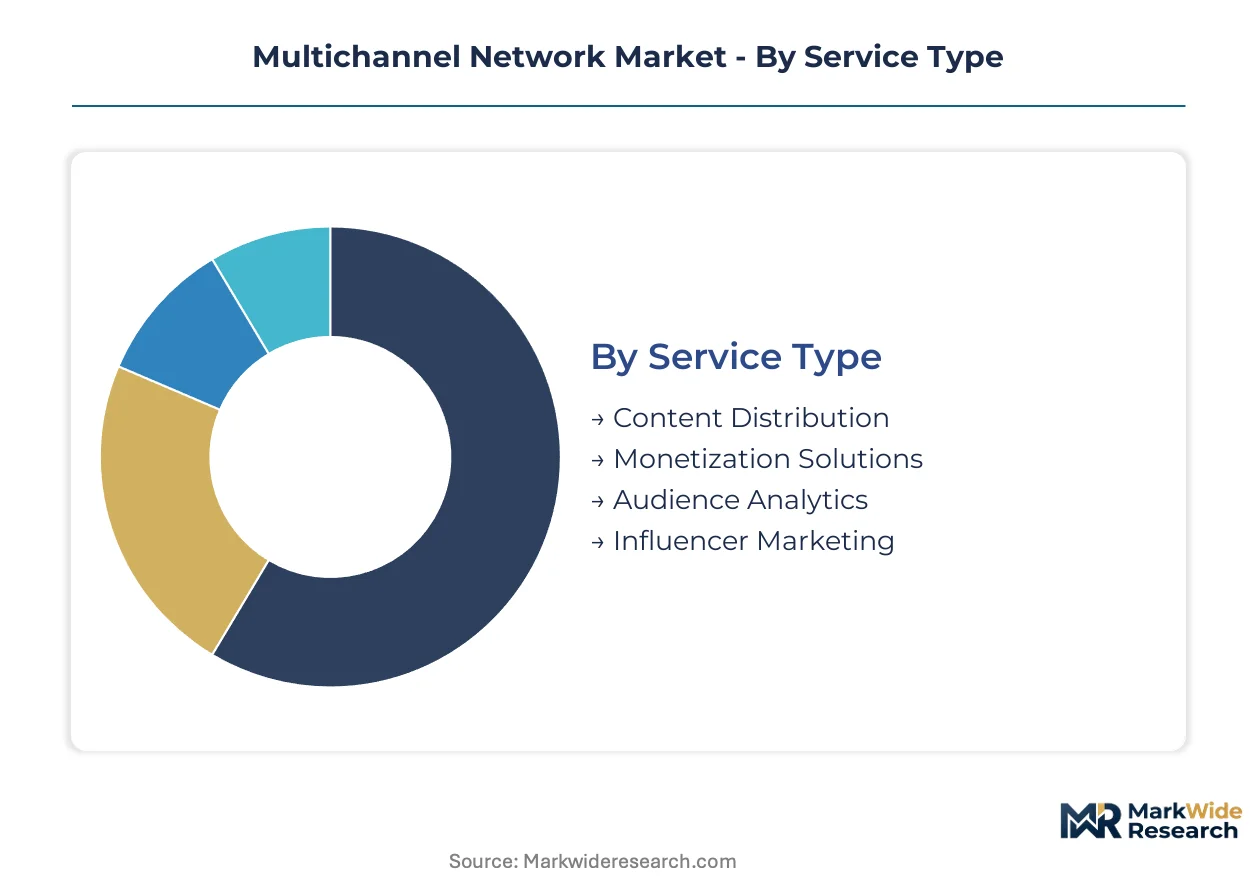
Network revenue concentration varies sharply across service configurations and platform dependencies. Segmentation reveals which bundled offerings command premium retention rates and where algorithmic exposure threatens portfolio stability.
Service Type:
Supply concentrates in bundled monetization and distribution infrastructure, with standalone analytics emerging as a distinct margin layer.
- Content Distribution:Centralized ingestion, encoding, and multi-platform publishing pipelines form the operational backbone of network-scale creator management. Demand clusters among gaming and entertainment creators in the United States where bandwidth costs and platform API access determine competitive viability. YouTube's Content ID integration and TikTok's upload protocols require continuous technical adaptation.
- Monetization Solutions:Ad sales representation, programmatic inventory aggregation, and direct sponsorship brokering generate the majority of contracted revenue share. Brand procurement departments in the United States and United Kingdom now mandate pre-campaign brand-safety screening, elevating networks with established moderation infrastructure. California's FTC disclosure enforcement and the EU Digital Services Act transparency mandates reshape contract structures.
- Audience Analytics:Cross-platform engagement verification and predictive content performance tools represent expanding margin pools as advertisers demand ISO-compliant measurement.
- Influencer Marketing:Campaign orchestration, creator matching, and performance attribution services bridge network-scale talent rosters with brand direct-sold arrangements.
Today's leader: Monetization Solutions. Tomorrow's challenger: Audience Analytics.
Platform Type:
Revenue exposure tilts heavily toward mature Partner Program infrastructure, though short-form alternatives are capturing creator migration.
- YouTube:The dominant revenue platform given its mature monetization infrastructure, Content ID rights management, and established advertiser marketplace. United States-based networks face 60-70% portfolio exposure to Partner Program policy changes, with algorithm adjustments propagating instantly through aggregated channel holdings. Long-form ad inventory and Super Chat livestream monetization anchor creator income stability.
- Instagram:Reels revenue-sharing and shopping integration pull lifestyle and commerce creator budgets from traditional display formats. Brazilian and Southeast Asian markets demonstrate shoppable livestream viability, rewarding networks with cross-platform streaming technology.
- Twitch:Subscription and Bits monetization serve gaming-centric creator bases with higher per-fan revenue but narrower advertiser demand.
- Facebook:Video and Reels distribution retains reach advantages for older demographics, though creator monetization tools lag platform competitors.
YouTube retains revenue dominance. Instagram claims the steepest expansion trajectory among lifestyle creators.
Customer Type:
Contract economics diverge sharply between individual creator representation and enterprise brand procurement.
- Creators:Individual talent seeking audience development, administrative burden reduction, and revenue optimization through network-scale resources. United States and United Kingdom markets show escalating minimum guarantee demands and revenue share renegotiation pressure. California's AB5-style contractor reclassification debates threaten employment cost structures.
- Brands:Direct advertisers procuring verified engagement, brand-safety assurance, and campaign performance attribution. Fortune 500 procurement departments increasingly displace pure programmatic purchases with direct-sold sponsorship arrangements.
- Advertisers:Performance-focused buyers prioritizing conversion metrics and audience targeting precision over content alignment.
- Agencies:Intermediary buyers consolidating network relationships for multi-creator campaign execution and reporting standardization.
Creator contracts supply volume foundation. Brand direct relationships deliver margin expansion.
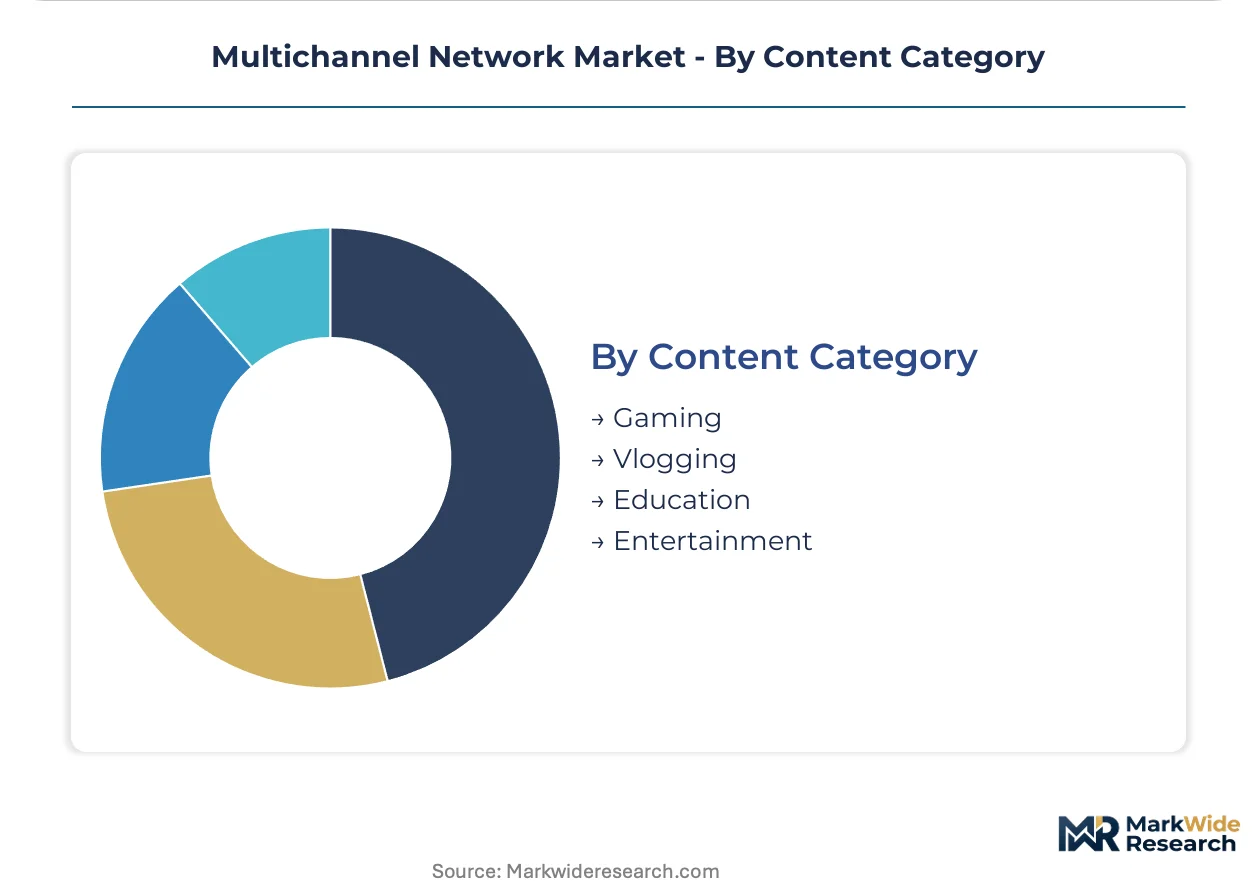
Content Category:
Gaming and entertainment concentrate platform algorithm favorability, while education commands premium brand adjacency pricing.
- Gaming:Livestream and video-on-demand content built around interactive playthroughs, esports competitions, and community engagement. Twitch and YouTube dominate distribution, with Southeast Asian markets showing particular creator density. Music licensing complexity and third-party content claims consume disproportionate operational bandwidth.
- Entertainment:Scripted and unscripted programming leveraging studio partnerships and broadcast talent migration. Studio71 and comparable networks anchor competitive position through direct entertainment studio relationships. Connected TV distribution partnerships create FAST channel inventory demand for repurposed archival content.
- Vlogging:Personal narrative and lifestyle documentation formats optimized for parasocial audience relationships and merchandise conversion.
- Education:Instructional and skill-development content commanding premium advertiser adjacency due to brand-safe context and engaged viewing duration.
Entertainment controls studio-derived leverage. Education offers the cleanest brand-safety positioning for risk-averse advertisers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The multichannel network industry traces its commercial origins to Los Angeles and New York, where early YouTube aggregators established the revenue-sharing templates that now dominate creator representation economics worldwide.
United States
Platform economics and creator monetization infrastructure remain most developed here, with Fortune 500 brand procurement departments mandating verified engagement metrics before campaign commitment. The FTC enforces disclosure requirements for sponsored content, pressuring networks toward standardized contract transparency. Los Angeles and New York anchor the highest concentration of network headquarters and talent representation offices.
United Kingdom
London-based networks benefit from English-language content export advantages and proximity to European brand decision-makers. The Competition and Markets Authority has scrutinized exclusivity clauses in creator contracts, forcing more flexible terms. Manchester and Birmingham host growing creator clusters focused on gaming and lifestyle verticals.
Germany
Strong domestic creator economy meets stringent regulatory oversight under the EU Digital Services Act transparency mandates. German regulatory authorities have initiated sector-specific guidance consultations affecting cross-border talent representation. Berlin and Hamburg concentrate network operations serving DACH-region advertisers.
Brazil
Southeast Asian-style live commerce integration is emerging alongside formalizing influencer marketing frameworks. ANVISA and consumer protection agencies mature disclosure standards for creator-brand relationships. São Paulo anchors network operations targeting Portuguese-language content distribution across Latin America.
South Korea
Shoppable livestream infrastructure demonstrates advanced monetization models transferable to Western markets. The country's content regulation framework shapes platform compliance standards adopted regionally. Seoul hosts technology partnerships enabling cross-platform streaming integration for network clients.
Multichannel Network Market Competitive Landscape
Premium-margin players sit above commodity-margin players across proprietary technology differentiation and direct studio relationship depth. The vendor base organizes into three tiers: technology-stack aggregators managing thousands of channels, studio-affiliated networks leveraging entertainment IP access, and cross-platform optimization specialists converting native formats for multi-territory distribution. Dominant competitive moves include strategic partnerships with connected TV platforms for FAST channel inventory and AI-assisted content localization investments.
Within the technology-aggregator tier, BBTV and Jellysmack occupy positions defined by proprietary platform infrastructure and cross-platform optimization capabilities respectively. Studio71 exemplifies the studio-affiliated archetype through its direct entertainment industry relationships. These three entities represent the primary competitive anchors against which mid-tier networks benchmark service bundling and revenue-share negotiations.
| Leading Market Players |
|---|
| BBTV |
| Studio71 |
| Fullscreen Media |
| Collab |
| Channel Frederator Network |
| Brave Bison |
| Yogscast Limited |
| Jellysmack |
| Gushcloud International |
| Others |
Supply & Pricing Matrix
Platform engineering talent clustering in Los Angeles and New York drives labor-cost differentials that widen pricing-tier spreads between premium networks and commodity aggregators.
Pricing Analysis
Revenue-share percentage tiers separate premium networks with proprietary technology stacks from standard aggregators and economy resellers. Price differentiation hinges on brand-safety certification levels and cross-platform distribution capabilities. Pricing pressure stems from creator retention cost inflation as exclusive talent demands escalating minimum guarantees. Individual creators exhibit highest price sensitivity, while Fortune 500 brand procurement departments prioritize verified engagement metrics over cost.
Supply Chain Analysis
Workforce availability for data science and platform policy expertise concentrates in the United States, the United Kingdom, and Germany. Raw material dependencies include cloud computing infrastructure, music licensing catalogs, and third-party content claim databases. Supply chain risk centers on single-source vulnerability to YouTube Partner Program policy changes. Distribution runs through direct platform API integrations and brand partnership intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multichannel network market operates as a stable compounder. Creator-led advertising budget migration from traditional display formats drives steady growth.
For Market Incumbents: Cement competitive position by deepening proprietary technology investments in AI-assisted content localization and cross-platform optimization. Acquire specialized compliance infrastructure to capture creators displaced by EU Digital Services Act transparency mandates. Prioritize direct studio licensing relationships for connected TV distribution leverage against emerging FAST channel competitors. For New Entrants and Emerging Players: Capture white-space opportunity in Brazilian creator economy formalization before ANVISA enforcement intensifies. Target education content creators in underserved European territories seeking brand-safe positioning. Pursue partnership-first go-to-market angle with regional platforms lacking native monetization infrastructure. For Investors and Strategic Acquirers: Entertainment studios and broadcast conglomerates are the most active acquirers in this space, seeking direct creator channel access. Acquisition target archetype: mid-tier networks with 500-2,000 channels and established cross-platform technology stacks. Watch California AB5-style contractor reclassification litigation as employment cost inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Content Localization | Automated dubbing tools enable YouTube-native creators to penetrate non-English Facebook and Instagram audiences. |
| Connected TV Distribution Partnership | FAST channel proliferation creates inventory demand for repurposed creator content with studio licensing backing. |
| Cross-Platform Technology Integration | Unified monetization and rights management platforms compress vendor fragmentation and elevate competitive thresholds. |
| EU Digital Services Act Compliance Infrastructure | Systemic transparency obligations force platforms to formalize creator verification standards, rewarding prepared networks. |
| Live Commerce Technology Development | Southeast Asian shoppable livestream models demonstrate viability for Western market transfer and brand partnership premiums. |
Research Methodology
Direct dialogue with network operations executives, creator talent managers, brand procurement officers, and platform policy specialists anchored qualitative foundations. Secondary validation drew from FTC enforcement records, EU Digital Services Act regulatory filings, platform Partner Program documentation, and advertising spend databases. Bottom-up channel count and revenue-share modeling triangulated against top-down advertising market sizing.
Bottom-up aggregation of individual network capacity and creator roster economics informed value projections across the analysis window. Segmentation dimensions encompassed service type bundling, platform dependency concentration, customer contract structure, and content category specialization. CAGRs derived from algorithmic trend extrapolation calibrated against historical platform policy change impacts. Forecast inputs incorporated creator migration patterns between short-form and long-form video platforms.
Platform algorithm volatility, creator employment reclassification rulings, and cross-platform measurement standard fragmentation are the dominant revision risks. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and platform monetization tool expansion trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Webtoons Market
Digital Media
Sound Effects Services Market
Digital Media
Digital Effects Services Market
Digital Media
Europe Inflight Entertainment and Connectivity Market
Digital Media
Online Movie Market
Digital Media
South Korea Webtoons Market
Digital Media
Media Gateway Market
Digital Media
Playout Solutions Market
Digital Media
Online Art Market
Digital Media
Manga Market
Digital Media
Anime Streaming Tool Market
Digital Media
Anime Merchandising Market
Digital Media
Europe Animation, VFX and Post Production Market
Digital Media
Digital Video Content Market
Digital Media
Visual Effects (VFX) Market
Digital Media
Naruto Around Market