
 3D Anaglyph Glasses Market | 2026-2036
3D Anaglyph Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
3D Anaglyph Glasses Market Insights
Red-cyan lens filtration is tilting toward precision-molded polycarbonate substrates that reduce chromatic aberration and improve viewing comfort across extended sessions. American Paper Optics leverages vertical integration from lens extrusion to retail packaging, sustaining cost leadership in North American educational supply chains. Shenzhen GetD Technology Co., Ltd anchors high-volume production for Asian cinema retrofit markets, while Rainbow Symphony, Inc. specializes in custom-branded anaglyph sets for museum and planetarium installations.
3D anaglyph glasses employ complementary color filtering—typically red-cyan or red-blue cellulose acetate or polycarbonate lenses—to decode stereoscopic images from single-source displays without active synchronization hardware. The devices serve primarily in low-cost immersive visualization for education, legacy media archives, and diagnostic imaging where polarization or shutter systems prove economically impractical. Plastic lens variants dominate unit economics in consumer and institutional bulk procurement, while polycarbonate grades capture preference in medical imaging applications where optical clarity and impact resistance carry premium weight. Home entertainment applications retain volume leadership despite format competition from polarized and active-shutter alternatives, whereas professional projection segments concentrate margin pools in specialized calibration-certified eyewear.
FDA optical device standards and EU REACH chemical restrictions on lens dyes and frame plastics shape material selection and cross-border market access for anaglyph eyewear manufacturers. China's GB standards for optical products and SAMR quality certification requirements govern export readiness from Shenzhen and Guangzhou production bases. Stakeholders must monitor regulatory divergence between ophthalmic-grade and novelty-classification thresholds, as reclassification would trigger compliance cost step-changes across major supply corridors.
Market Dynamics
Precision-molded polycarbonate substrates are compressing chromatic aberration tolerances and forcing legacy cellulose acetate suppliers into specialty niches, restructuring procurement hierarchies across educational and medical imaging verticals.
Growth Catalysts
- STEM Curriculum Integration:Educational institutions in China and the United States are embedding stereoscopic visualization tools into K-12 and undergraduate science programs, generating institutional procurement pipelines for certified anaglyph eyewear.
- REACH Compliance Premium:EU chemical safety standards for lens dyes and frame plastics are creating certified product tiers that command price premiums in European museum and planetarium supply chains.
- Polycarbonate Optical Clarity:Medical imaging facilities are specifying impact-resistant polycarbonate grades for diagnostic applications where cellulose acetate fails durability benchmarks.
Market Restraints
- Petrochemical Feedstock Volatility:Crude oil price swings directly compress margins on polycarbonate and cellulose acetate lens substrates, squeezing mid-tier manufacturers without captive resin supply.
- Shenzhen-Guangzhou Supply Concentration:Over 70 percent of global anaglyph eyewear volume originates from two adjacent Chinese manufacturing clusters, creating single-point-of-failure exposure for international distributors.
- Polarized Display Substitution:Cinema chains and home entertainment systems are retrofitting polarization-based 3D infrastructure that renders anaglyph filtration obsolete for premium viewing experiences.
Strategic Opportunities
- Indian Educational Procurement:India's National Education Policy implementation is expanding laboratory equipment budgets across state universities, opening bulk anaglyph eyewear tenders previously captured by domestic optical suppliers.
- Legacy Media Archive Digitization:Film preservation institutions are specifying anaglyph glasses for accessing historical stereoscopic photography collections where polarization conversion proves economically prohibitive.
- Dual Carbon Goals Alignment:China's MEE guidelines on manufacturing emissions are incentivizing recycled polycarbonate feedstock adoption, creating sustainability-certified product lines for environmentally screened institutional buyers.
Industry Challenges
- Ophthalmic-Grade Certification Timelines:FDA reclassification reviews for optical devices are extending product launch cycles by 14-18 months for manufacturers seeking medical imaging market entry.
- Chromatography Skill Scarcity:Precision dye-matching for red-cyan filtration specifications requires analytical chemistry expertise that contract manufacturers in Vietnam and Indonesia struggle to source locally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Anaglyph Glasses Market |
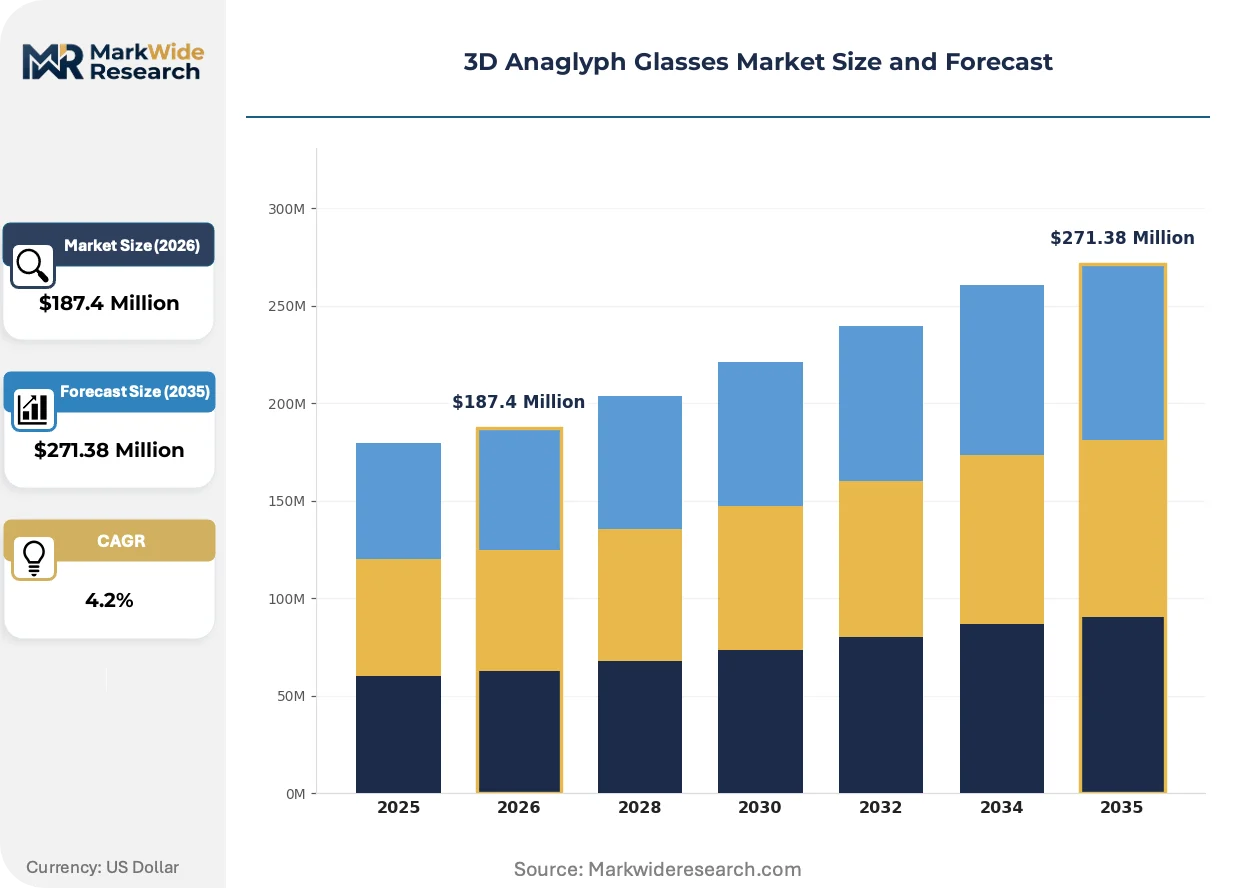
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anaglyph Glasses, Active Shutter Glasses, Passive Polarized Glasses, Clip-On Glasses End User: Consumers, Educational Institutions, Film Industry, Gaming Industry Material: Plastic, Glass, Polycarbonate, Acrylic Application: Home Entertainment, Virtual Reality, Professional Projection, Medical Imaging |
| Companies Covered | American Paper Optics, RealD Inc., Rainbow Symphony, Inc., eDimensional Inc., Shenzhen GetD Technology Co., Ltd, Guangzhou Shixiang Technology Co., Ltd, hcbl3d.com, 3D Glass Solutions, SOFTONIC INTERNATIONAL S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Anaglyph Glasses Market Trends and Innovations
Material science convergence with regulatory chemistry standards is compressing traditional supply hierarchies and enabling new certification-driven product differentiation across institutional procurement channels.
Polycarbonate substrate technology is hybridizing with precision injection-molding processes that achieve sub-micron surface tolerances for chromatic aberration control. Medical imaging departments in Germany and Japan are specifying these grades for extended diagnostic sessions where viewer fatigue degrades diagnostic accuracy. The technology is hybridizing formerly distinct consumer and professional product tiers into a unified certification ladder.
EU REACH restrictions on azo-based lens dyes are forcing reformulation cycles across Asian export manufacturers. Shenzhen and Guangzhou production bases are investing in non-toxic dye chemistry to maintain European market access, elevating compliance costs that smaller contract manufacturers cannot absorb. Museum and planetarium installation segments are responding by consolidating procurement around REACH-certified suppliers with documented supply chain audit trails.
Bulk institutional tenders are displacing retail-oriented packaging configurations as the dominant order format. Educational supply distributors in the United States and China are negotiating direct factory relationships that bypass traditional wholesale intermediaries, compressing margin pools for legacy channel operators. This pattern is most visible in Chinese provincial education bureaus and American school district cooperative purchasing agreements.
3D Anaglyph Glasses Market Segmentation
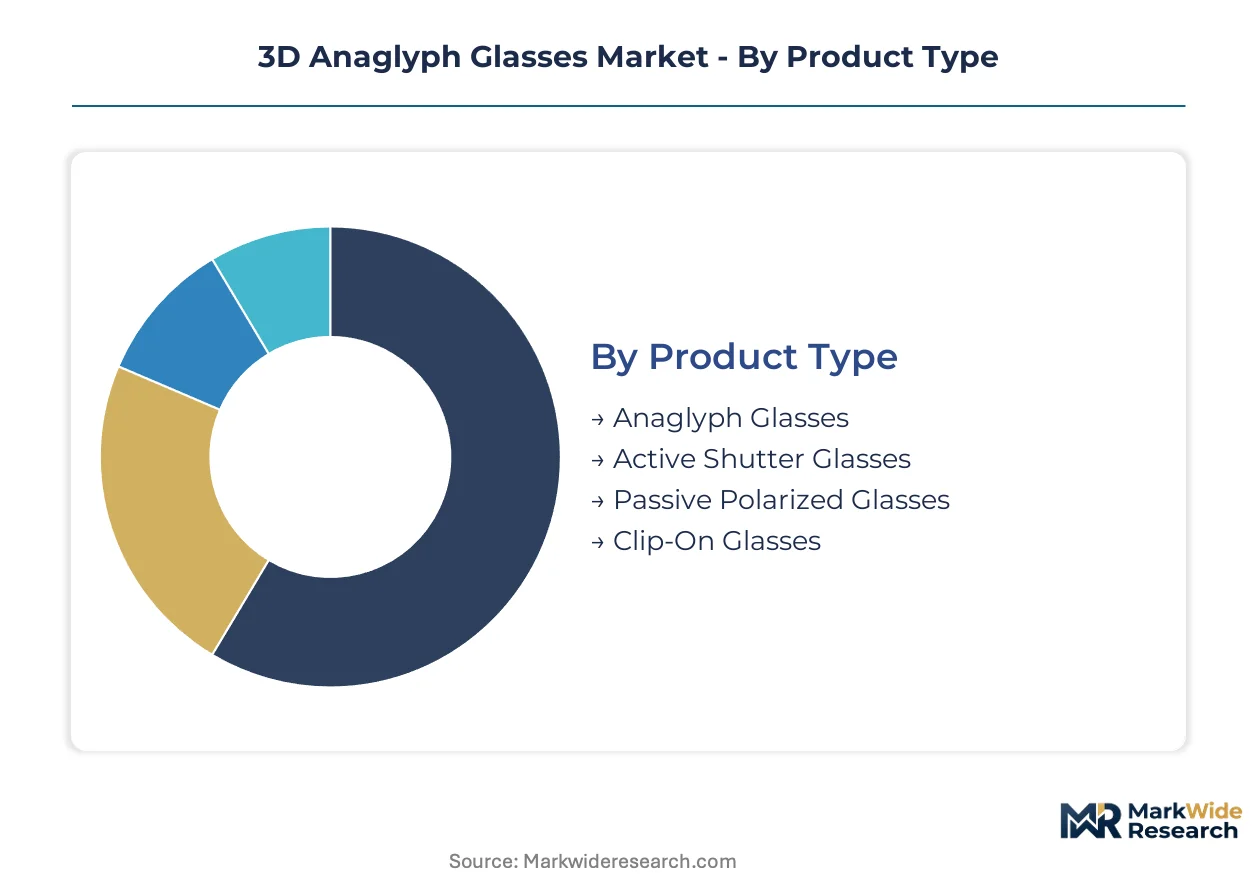
Segmentation in the 3D anaglyph glasses market reveals how procurement hierarchies split between cost-optimized bulk orders and precision-certified specialty lines. Material specifications and end-use durability requirements create distinct margin pools that manufacturers navigate through targeted certification investments.
Product Type:
Cost tier differentiation separates disposable educational supplies from calibration-grade professional equipment, with filtration precision and frame durability as the primary value drivers.
- Anaglyph Glasses:Complementary color filtration systems using red-cyan or red-blue cellulose acetate or polycarbonate substrates decode stereoscopic images without active synchronization. Educational institutions in China and the United States generate institutional procurement pipelines for certified eyewear as STEM curricula expand. FDA and REACH compliance requirements elevate material specifications for medical and museum applications.
- Active Shutter Glasses:Liquid crystal lens assemblies alternate opacity in sync with display refresh rates to deliver full-resolution stereoscopy per eye. Home entertainment systems in Japan and South Korea specify these for premium viewing where anaglyph color compromise is unacceptable. Battery dependency and synchronization hardware costs limit penetration in price-sensitive educational tenders.
- Passive Polarized Glasses:Orthogonal polarization filters separate left and right eye images without electronic components. Cinema chains retrofitting polarization-based infrastructure displace anaglyph filtration for theatrical releases.
- Clip-On Glasses:Auxiliary filtration lenses attach over prescription eyewear for accessibility compliance. Medical imaging facilities specify these for diagnostic staff requiring vision correction.
Anaglyph glasses command the established base. The steepest expansion runs through clip-on variants addressing accessibility mandates in institutional procurement.
End User:
Application context determines durability specifications, with extended-session comfort requirements in medical and educational settings driving material upgrades.
- Consumers:Individual purchasers acquire anaglyph eyewear for legacy media access and occasional home entertainment. E-commerce platforms and retail chains in the United States and Germany distribute cost-optimized cellulose acetate variants. Polarized display substitution in home theater systems erodes repeat purchase frequency.
- Educational Institutions:K-12 and undergraduate science programs embed stereoscopic visualization into STEM curricula. Chinese provincial education bureaus and American school district cooperative purchasing agreements negotiate direct factory relationships. Bulk tenders displace retail packaging configurations as the dominant order format.
- Film Industry:Production and post-production facilities require color-accurate anaglyph filtration for dailies review and archive access. Legacy stereoscopic photography collections in European preservation institutions specify certified eyewear where polarization conversion is economically prohibitive.
- Gaming Industry:Developers and QA laboratories utilize anaglyph glasses for compatibility testing across display configurations. Virtual reality headset manufacturers reference anaglyph fallback modes for hardware-agnostic content distribution.
Educational institutions command the established base. The steepest expansion runs through medical imaging facilities specifying impact-resistant polycarbonate grades.
Material:
Supply concentration in Shenzhen and Guangzhou manufacturing clusters shapes feedstock procurement strategies for export-oriented producers.
- Plastic:General-purpose polymers dominate unit economics in consumer and institutional bulk procurement. REACH restrictions on azo-based dyes force reformulation cycles among smaller contract manufacturers lacking analytical chemistry capabilities.
- Glass:Mineral substrates deliver optical clarity for archival and museum applications where scratch resistance outweighs weight penalties. European planetarium installations specify these for extended public use durability.
- Polycarbonate:Impact-resistant grades with sub-micron surface tolerances achieve chromatic aberration control for extended diagnostic sessions. Medical imaging departments in Germany and Japan specify these where viewer fatigue degrades diagnostic accuracy. China's MEE guidelines on manufacturing emissions incentivize recycled feedstock adoption.
- Acrylic:Lightweight alternatives serve promotional and single-event distribution where unit cost minimization dominates. Trade show and exhibition organizers in India source these for temporary immersive installations.
Plastic commands the established base. The steepest expansion runs through polycarbonate grades capturing medical certification premiums.
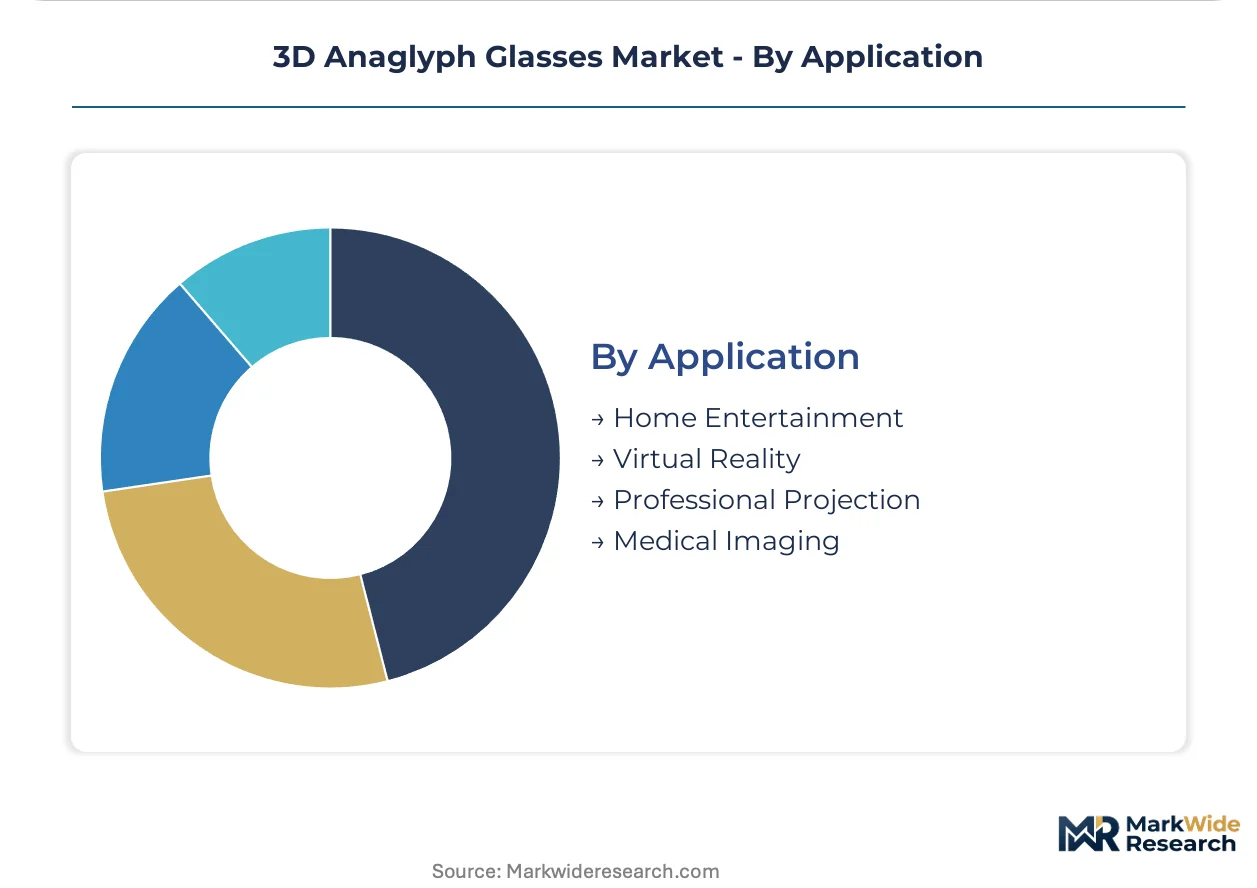
Application:
Volume scale and margin structure diverge between mass-market entertainment and precision-certified professional segments.
- Home Entertainment:Legacy DVD and streaming content libraries maintain anaglyph compatibility for hardware-agnostic distribution. Retail channels in the United States and Brazil stock impulse-purchase multipacks for occasional viewing.
- Virtual Reality:Fallback stereoscopic modes in VR software stacks preserve anaglyph output for display-agnostic accessibility. Developer toolkits reference anaglyph preview for rapid prototyping without specialized hardware.
- Professional Projection:Calibration-certified eyewear serves museum, planetarium, and archival exhibition requirements. REACH-certified suppliers with documented supply chain audit trails consolidate procurement in European installation segments.
- Medical Imaging:Diagnostic departments specify ophthalmic-grade filtration for extended interpretation sessions. FDA reclassification reviews extend product launch cycles for manufacturers seeking market entry.
Home entertainment commands the established base. The steepest expansion runs through medical imaging applications where certification barriers protect margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese manufacturing clusters dominate international supply, while import demand concentrates in education-heavy economies with STEM curriculum mandates. Trade patterns reflect a bifurcation between bulk institutional procurement and specialized medical-grade certification markets.
China
Shenzhen and Guangzhou manufacturing bases supply over seventy percent of global anaglyph eyewear volume through vertically integrated extrusion-to-assembly operations. SAMR quality certification and GB standards for optical products govern export readiness from these Pearl River Delta clusters. MEE guidelines on manufacturing emissions are accelerating recycled polycarbonate feedstock adoption among environmentally screened institutional buyers.
United States
School district cooperative purchasing agreements and K-12 STEM expansion generate institutional procurement pipelines for certified eyewear. FDA optical device standards shape material selection for medical imaging applications, with reclassification reviews extending product launch cycles. American Paper Optics maintains cost leadership through captive lens extrusion and retail packaging integration.
Germany
Medical imaging departments specify REACH-certified polycarbonate grades for extended diagnostic sessions where chromatic aberration degrades accuracy. ECHA chemical safety restrictions on azo-based lens dyes elevate compliance costs for Asian exporters serving museum and planetarium installation segments. Bavaria-based distributors consolidate procurement around suppliers with documented supply chain audit trails.
India
National Education Policy implementation is expanding laboratory equipment budgets across state universities, opening bulk tender opportunities previously captured by domestic optical suppliers. BIS standards for optical products create certification thresholds for imported eyewear. Maharashtra and Karnataka education bureaus are negotiating direct factory relationships that bypass traditional wholesale intermediaries.
Japan
Home entertainment systems and developer QA laboratories sustain demand for hardware-agnostic stereoscopic fallback modes. METI industrial standards and PMDA guidance on optical devices influence procurement specifications for medical and professional applications. Tokyo-based film preservation institutions specify certified anaglyph eyewear for accessing historical stereoscopic photography collections.
3D Anaglyph Glasses Market Competitive Landscape
On the supply side, the industry is bifurcated between high-volume Chinese manufacturing clusters and specialized Western certification-focused suppliers. The competitive terrain splits across three strategic tiers: vertically integrated extrusion-to-retail operators, precision-molded polycarbonate specialists, and contract manufacturers serving private-label educational distributors. Dominant competitive moves include backward integration into captive resin supply and direct factory relationships that disintermediate wholesale channels.
Within the vertically integrated tier, American Paper Optics represents North American supply chain control from lens extrusion through retail packaging. Among Chinese manufacturers, Shenzhen GetD Technology Co., Ltd occupies a position exemplifying high-volume production for Asian cinema retrofit markets, while Rainbow Symphony, Inc. anchors the specialty certification segment serving museum and planetarium installations with custom-branded anaglyph sets. These three archetypes capture the structural divergence between cost-optimized bulk supply and precision-certified professional equipment.
| Leading Market Players |
|---|
| American Paper Optics |
| RealD Inc. |
| Rainbow Symphony, Inc. |
| eDimensional Inc. |
| Shenzhen GetD Technology Co., Ltd |
| Guangzhou Shixiang Technology Co., Ltd |
| hcbl3d.com |
| 3D Glass Solutions |
| SOFTONIC INTERNATIONAL S.A. |
| Others |
Pricing and Supply Chain Analysis
Petrochemical feedstock volatility in polycarbonate and cellulose acetate resins compresses margin buffers across mid-tier manufacturers while simultaneously widening spreads between economy-grade educational supplies and REACH-certified professional tiers. This single-input risk vector forces procurement officers to choose between locking in long-term resin contracts at premium fixed rates or absorbing spot-market exposure that can erase profitability on bulk institutional tenders.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stabilize unit economics against resin price swings. Price differentiation rests on certification grade—FDA ophthalmic tiers command substantial premiums over novelty-classified educational variants—and volume scale, with direct factory relationships for provincial education bureaus stripping out wholesale markups. Pricing pressure stems from polarized display substitution in cinema and home theater retrofit cycles, compressing repeat purchase frequency in consumer channels. K-12 cooperative purchasing agreements exhibit highest price sensitivity, while medical imaging facilities prioritize optical clarity over unit cost.
Supply Chain Analysis
Extended payment terms from 90 to 120 days are becoming standard for European museum and planetarium procurement, squeezing working capital for contract manufacturers without supply-chain finance facilities. Geographic concentration centers on China, South Korea, and Germany, with Shenzhen and Guangzhou clusters feeding over seventy percent of global volume. Raw material dependencies draw from petrochemical-derived polycarbonate granules, cellulose acetate sheet stock, and azo-based dye precursors now restricted under REACH. Single-source vulnerability pervades the Pearl River Delta manufacturing base, where SAMR certification requirements create regulatory chokepoints for export readiness. Distribution runs through educational supply distributors negotiating direct factory relationships that disintermediate traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polarized and active-shutter 3D systems are accelerating substitution pressure across cinema and premium home entertainment segments, forcing anaglyph incumbents to defend position through certification moats and institutional channel lock-in.
For Market Incumbents: Build regulatory certification moats around REACH-compliant dye chemistry and FDA ophthalmic-grade pathways that emerging Asian contract manufacturers cannot replicate without 14-18 month investment cycles. Anchor capacity addition in recycled polycarbonate feedstock lines aligned with China's MEE emissions guidelines, capturing sustainability-screened institutional tenders before competitors secure factory relationships with provincial education bureaus. Channel control through direct procurement portals for American school district cooperatives resists price erosion from wholesale disintermediation. For New Entrants and Emerging Players: Establish a beachhead in India's state university laboratory equipment tenders, where National Education Policy implementation is expanding budgets faster than domestic optical suppliers can scale production capacity. Penetrate the clip-on accessibility segment serving medical imaging facilities requiring prescription eyewear compatibility, a niche where established players have underinvested in ergonomic design. Pursue white-label manufacturing partnerships with European planetarium installation contractors seeking REACH-certified suppliers with documented supply chain audit trails. For Investors and Strategic Acquirers: FDA reclassification reviews for optical devices reshape the acquisition landscape by extending product launch timelines and elevating compliance infrastructure requirements beyond smaller contract manufacturers' capital thresholds. Target vertically integrated extrusion-to-assembly operators with captive resin supply and existing SAMR export certification, as these assets compound in scarcity value against feedstock volatility and regulatory fragmentation. Watch for ECHA expansion of restricted substance lists as the signal indicating which dye chemistry investments will retain market access versus stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Extrusion | Captive polycarbonate supply insulates margins from petrochemical volatility affecting Shenzhen contract manufacturers. |
| REACH Compliance Certification Program | Non-azo dye reformulation secures European museum and planetarium procurement against regulatory exclusion. |
| Direct Factory Relationship Portal | Bypassing wholesale intermediaries captures margin pools in American school district cooperative purchasing agreements. |
| Recycled Feedstock Line Investment | MEE-aligned sustainability credentials attract environmentally screened institutional buyers in China and Germany. |
| Medical Imaging Partnership Development | FDA ophthalmic-grade certification opens diagnostic application margins protected from consumer price erosion. |
Research Methodology
Desk research of customs trade databases, SAMR certification registries, and FDA 510(k) optical device filings preceded structured interviews with procurement managers at educational supply distributors, plant engineers at Shenzhen extrusion facilities, and regulatory affairs leads at REACH-certified European manufacturers. Primary fieldwork with museum installation contractors and medical imaging department heads validated secondary projections around certification-driven demand segmentation. Bottom-up unit shipment estimates from manufacturing clusters were triangulated against top-down procurement budget analysis from state education bureaus.
Assumptions held fixed across the projection horizon include continuation of current REACH dye restrictions and SAMR export certification requirements, while petrochemical feedstock pricing and polarized display adoption rates were modeled as variable stress inputs. The analytical framework segmented volume and value across material grade, end-use application, and regional regulatory cluster, with CAGRs derived from regression against historical procurement cycle patterns and STEM curriculum expansion timelines. Industry-specific forecast inputs incorporated BIS standards implementation progress in India and MEE emissions guideline enforcement intensity in Guangdong province.
Stress conditions across resin price bands, regulatory reclassification thresholds, and substitution technology penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification timeline stability and manufacturing cluster concentration persistence. Macroeconomic contraction in educational procurement budgets, ECHA expansion of restricted substance lists, or breakthroughs in low-cost polarization retrofit technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Digital Effects Services Market
Digital Media
Global ACGN Market
Digital Media
North America Online Gambling Market
Digital Media
Visual Effects (VFX) Market
Digital Media
APAC Media and Entertainment Market
Digital Media
Naruto Around Market
Digital Media
Global Playout Automation and Channel in a Box Market
Digital Media
Japan Webtoons Market
Digital Media
Stock Music Software Market
Digital Media
Stock Photography Market
Digital Media
Webtoons Market
Digital Media
Europe Online Gambling Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
Global Animation Market
Digital Media
Global Digital Painting Market
Digital Media
Digital Video Advertising Market