
 IP in Media and Entertainment Market | 2026-2036
IP in Media and Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
IP in Media and Entertainment Market Insights
Generative artificial intelligence is reconfiguring pre-production pipelines, script development, and automated dubbing workflows across film and television studios. Walt Disney Company leverages its century-old character vault to sustain franchise monetization across theme parks, streaming, and consumer products. Netflix, Inc. anchors its global subscriber base through in-house IP development that reduces licensing dependency. Amazon.com, Inc. competes by integrating original content with its e-commerce and cloud infrastructure ecosystems.
Intellectual property in media and entertainment encompasses legally protected creative assets including copyrighted audiovisual works, trademarked characters, and licensed distribution rights that generate recurring revenue through controlled exploitation. These assets function as capital-light revenue engines where marginal distribution costs approach zero through digital streaming infrastructure, while primary value accrues to owners who control both creation mechanics and platform access. Studio-owned content dominates margin pools through franchise architectures that amortize development costs across theatrical, streaming, merchandise, and experiential channels. Subscription models represent the fastest-growing revenue stream as platforms prioritize recurring customer relationships over transactional licensing. Joint ventures between technology platforms and legacy studios are proliferating as capital requirements for premium content escalate.
The U.S. Copyright Office and the Digital Millennium Copyright Act shape enforcement frameworks for online content distribution, while the EU's Digital Services Act and copyright directive impose platform accountability obligations across European markets. China's National Copyright Administration and MIIT content review standards govern market access for foreign IP holders seeking theatrical or streaming distribution. Stakeholders must monitor evolving generative AI training exemptions and emerging right-of-publicity statutes that could redefine ownership boundaries for synthetic media.
Market Dynamics
Generative artificial intelligence is collapsing production timelines for original content while fragmenting ownership frameworks across streaming platforms and legacy studios. The U.S. Copyright Office grapples with training-data exemptions as synthetic media tools proliferate through pre-production pipelines.
Growth Catalysts
- AI-Driven Content Generation:Synthetic media tools compress script development and automated dubbing workflows. Film studios integrate machine learning into visual effects pipelines, reducing post-production cycles.
- The U.S. Copyright Office Modernization:Evolving registration frameworks for AI-assisted works clarify ownership boundaries. Rights holders gain clearer enforcement pathways for digital distribution.
- Subscription Platform Expansion:Streaming services prioritize proprietary libraries to reduce licensing dependency. Recurring revenue models amortize development costs across theatrical, merchandise, and experiential channels.
Market Restraints
- Generative AI Training Uncertainty:Unresolved fair-use boundaries for copyrighted training data create litigation exposure. Content owners face unpredictable enforcement outcomes.
- Platform Concentration Risk:Distribution control consolidates among three dominant streaming services. Independent producers encounter gatekeeping friction for original IP placement.
- Right-of-Publicity Fragmentation:State-level statutes in the United States create inconsistent synthetic likeness protections. Cross-border talent agreements require jurisdiction-specific legal review.
Strategic Opportunities
- India's OTT Regulatory Tailwind:Ministry of Information and Broadcasting content guidelines favor domestic IP development. Local language originals attract platform investment for subscriber acquisition.
- Virtual Production Convergence:Game engine technology merges with LED volume stages. Real-time rendering collapses location shooting requirements for genre content.
- Theme Park Experiential Licensing:Immersive attractions monetize dormant character archives. Franchise owners extract incremental value from decades-old IP portfolios.
Industry Challenges
- Synthetic Media Attribution Complexity:Provenance tracking for AI-assisted works strains existing copyright registration systems. Rights management databases require structural overhaul.
- Legacy Contract Renegotiation:Talent agreements drafted before generative AI lack synthetic performance clauses. Studios face retroactive compensation disputes.
- Cross-Platform Metadata Standardization:Inconsistent tagging protocols complicate content discovery and rights clearance. Interoperable frameworks remain underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IP in Media and Entertainment Market |
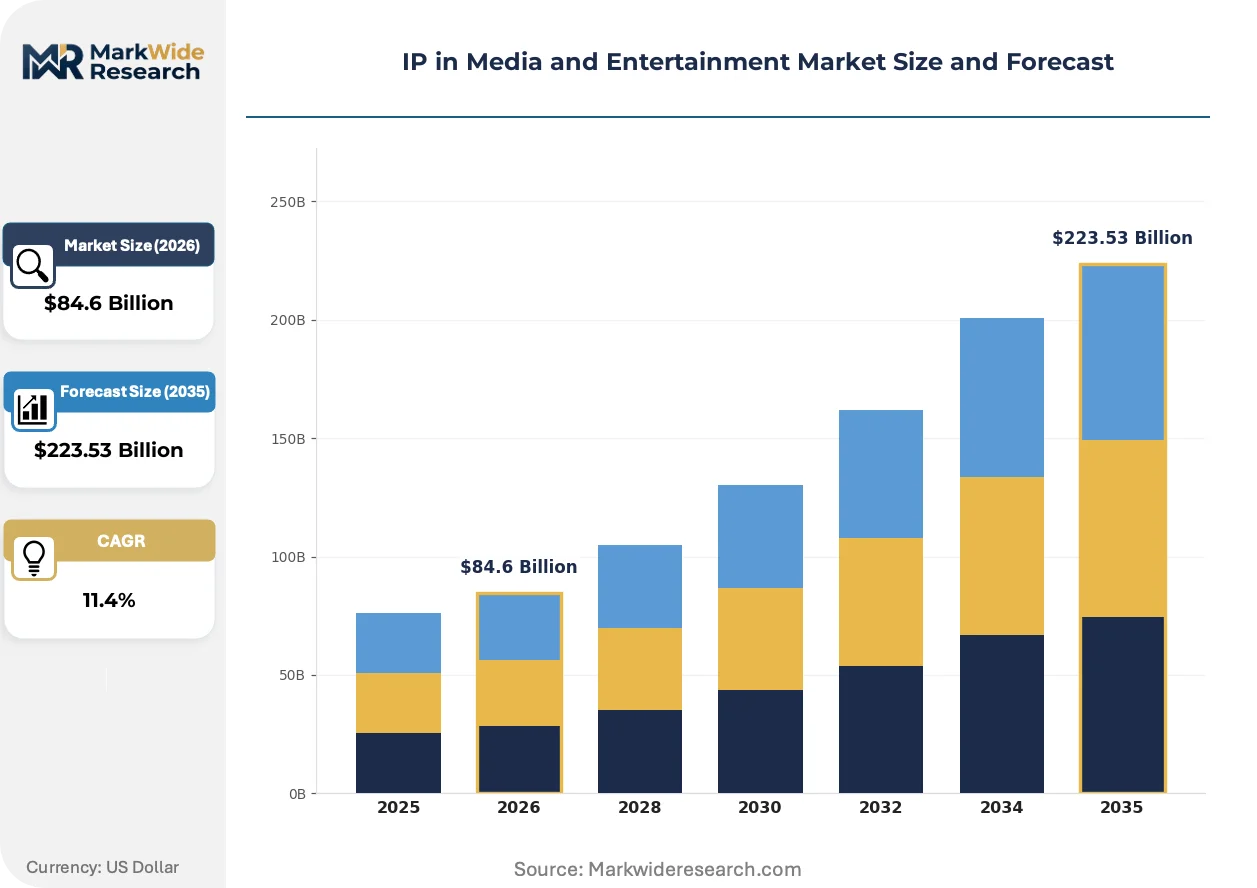
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $223.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Films, Television Shows, Podcasts, Digital Media Revenue Stream: Licensing Fees, Merchandise Sales, Subscription Models, Advertising Distribution Channel: Theatrical, Streaming Platforms, Television, Home Video Ownership Model: Independent, Studio-Owned, Joint Ventures, Franchises |
| Companies Covered | Walt Disney Company, Comcast Corporation, Warner Bros. Discovery, Inc., Paramount Global, News Corporation, Netflix, Inc., Amazon.com, Inc., Alphabet Inc., Sony Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IP in Media and Entertainment Market Trends and Innovations
Production workflows are fragmenting as cloud-based collaboration tools enable distributed creative teams. Rights management infrastructure struggles to keep pace with synthetic media proliferation.
Machine learning-based dubbing and localization is collapsing the cost structure for multi-language content distribution. European streaming platforms deploy neural voice synthesis to accelerate catalog globalization. Marginal per-title localization expense approaches zero for back-catalog titles, compressing competitive moats between regional and global services.
The EU AI Act imposes transparency obligations on generative tools used in commercial content production. Synthetic media outputs must carry detectable provenance markers under the forthcoming enforcement framework. French audiovisual producers anticipate compliance costs for AI disclosure systems, while German public broadcasters pilot automated labeling workflows.
Audience acquisition patterns are rotating toward franchise-agnostic discovery algorithms. Streaming subscribers select titles based on personalized recommendation engines rather than studio brand loyalty. This behavioral shift concentrates commissioning power with platform data science teams, marginalizing traditional development executives in Los Angeles and London.
IP in Media and Entertainment Market Segmentation
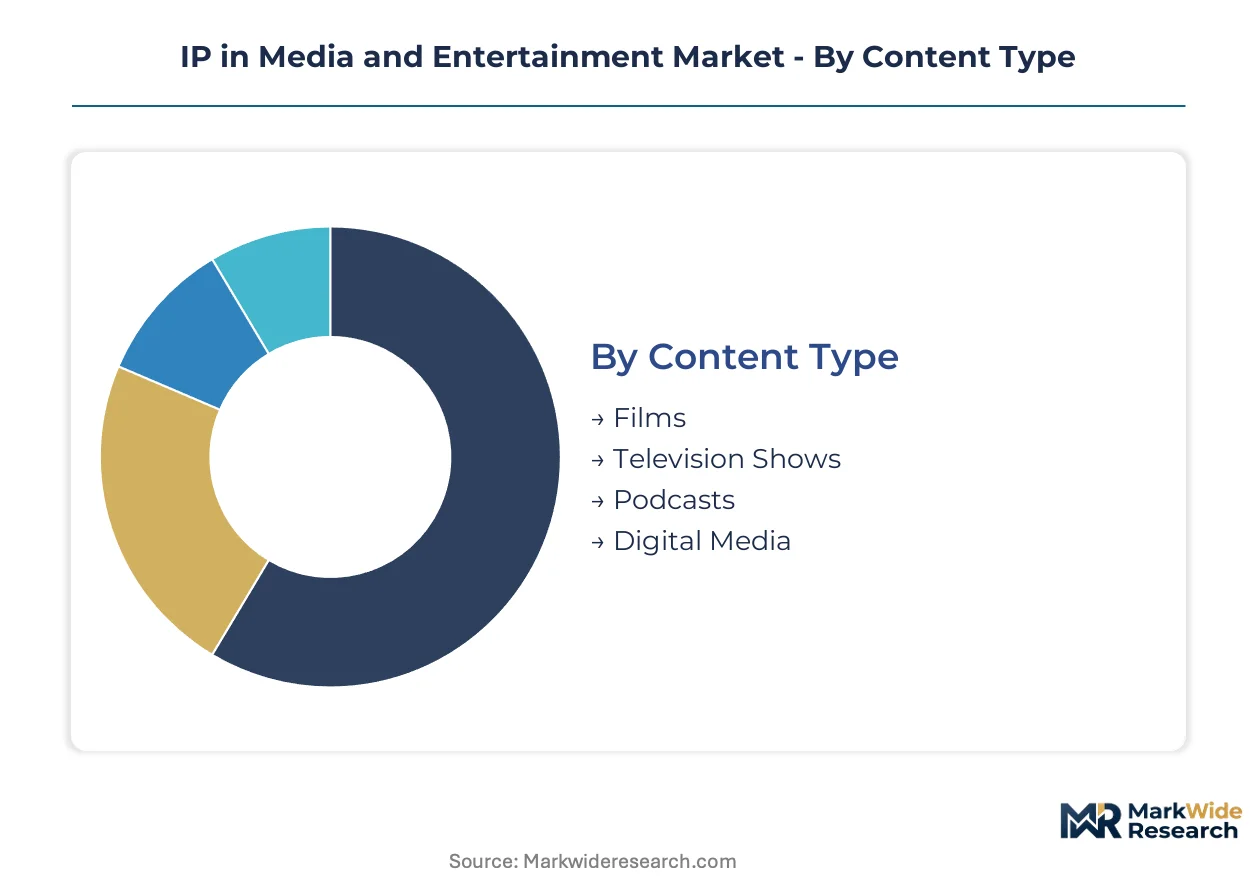
Content creators and rights holders segment intellectual property portfolios to optimize monetization pathways across divergent audience behaviors and platform economics. Each segmentation dimension reveals distinct capital intensity profiles, margin structures, and regulatory exposure that shape strategic resource allocation.
Content Type:
After-sales service intensity varies dramatically across content categories, with episodic formats demanding sustained audience relationship management and live-event properties requiring immediate technical support infrastructure.
- Films:Theatrical releases generate concentrated revenue windows with intensive premiere-week customer service demands. Studio distribution arms prioritize IMAX and premium format partnerships for tentpole releases in the United States and China.
- Television Shows:Episodic production amortizes development costs across multi-season arcs with recurring audience engagement touchpoints. Streaming platforms commission local-language originals for subscriber retention in India and South Korea.
- Podcasts:Audio IP requires minimal post-release infrastructure with advertising insertion as primary monetization. Independent creators dominate production volume through distributed hosting platforms.
- Digital Media:Short-form and user-generated content operates on algorithmic distribution with near-zero marginal delivery cost. Platform-native creators extract value through creator fund participation rather than direct licensing.
By volume, Digital Media leads. By growth pace, Television Shows is ahead.
Revenue Stream:
Cost tier stratification separates capital-light recurring models from transaction-dependent licensing structures with pronounced revenue volatility.
- Licensing Fees:Third-party distribution agreements generate upfront cash flows with limited ongoing service obligations. Sports leagues command premium rates for exclusive windowing across regional broadcasters.
- Merchandise Sales:Physical and digital product extensions require inventory management and fulfillment partnerships. Character-based properties in Japan sustain decades-long retail relationships through limited-edition release cycles.
- Subscription Models:Recurring revenue platforms prioritize proprietary IP to reduce content acquisition costs. Netflix and Disney anchor global subscriber bases through in-house production pipelines.
- Advertising:Ad-supported tiers monetize back-catalog inventory with programmatic insertion technology. European broadcasters deploy addressable advertising to compete with platform-native solutions.
Subscription Models command the highest customer lifetime value. Advertising-supported distribution is expanding most quickly among price-sensitive demographics.
Distribution Channel:
Application context determines technical specification requirements, with theatrical exhibition demanding uncompressed mastering and streaming platforms optimizing for adaptive bitrate delivery.
- Theatrical:Cinema release windows concentrate marketing spend with premium ticket pricing for franchise properties. Chinese exhibitors operate the world's largest screen base with domestic quota requirements.
- Streaming Platforms:Direct-to-consumer distribution eliminates intermediary margins while requiring substantial technology infrastructure. Amazon Web Services and Microsoft Azure compete for studio cloud transcoding contracts.
- Television:Linear broadcast maintains reach for live events and older demographic segments. Indian cable and DTH operators negotiate carriage fees with regional language channels.
- Home Video:Physical media persists for collector editions and markets with limited broadband penetration. Japanese consumers sustain Blu-ray demand through anime packaging strategies.
Streaming Platforms dominate commissioning volume. Theatrical release is climbing the fastest as studios prioritize event-level differentiation.
Ownership Model:
Customer type segmentation separates integrated studio operations from fragmented independent production with divergent financing and distribution capabilities.
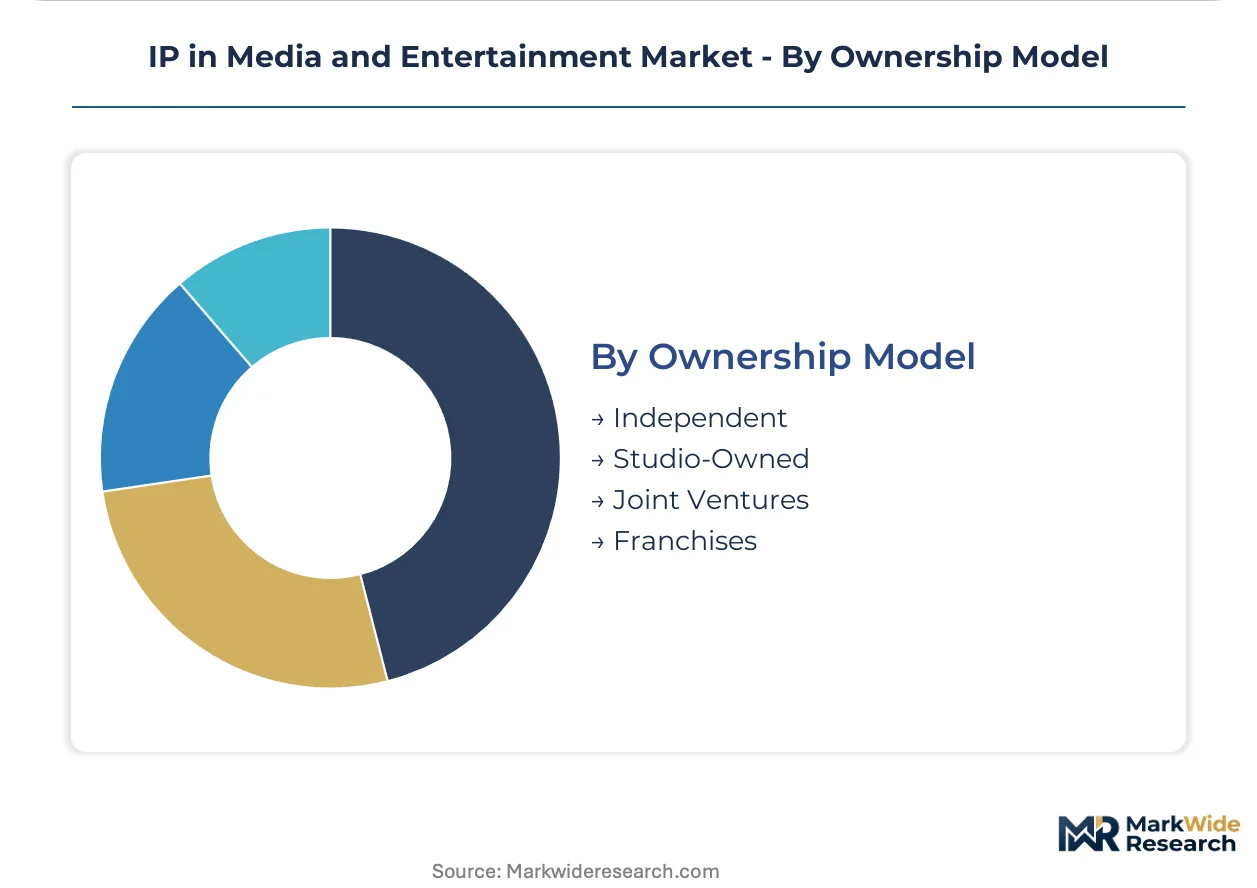
- Independent:Creator-owned properties rely on festival circuits and sales agents for distribution access. Sundance and Toronto selections drive acquisition interest from platform buyers.
- Studio-Owned:Vertically integrated production and distribution controls windowing strategy across theatrical, streaming, and ancillary markets. Warner Bros. Discovery and Paramount Global leverage century-old libraries for franchise extension.
- Joint Ventures:Co-production structures distribute capital requirements and territorial rights across multiple parties. European public broadcasters partner through Eurimages for cross-border financing.
- Franchises:Serialized universe construction amortizes development investment across film, television, gaming, and experiential extensions. Marvel Studios and Lucasfilm operate the most valuable character portfolios under Disney ownership.
Studio-Owned properties lead by revenue concentration. Joint Ventures are gaining share fastest as capital requirements for premium content escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based studios export original content to streaming platforms across India, South Korea, and Brazil, establishing Hollywood as the dominant IP origination corridor for global entertainment consumption.
United States
Major studios in Los Angeles and New York commission franchise properties for theatrical and streaming distribution. The U.S. Copyright Office modernizes registration frameworks for AI-assisted works. Production clusters in Burbank and Manhattan drive proprietary content development for platform-exclusive licensing.
India
Bollywood and regional language producers supply local-language originals to domestic and diaspora streaming audiences. Ministry of Information and Broadcasting guidelines favor domestic IP development through content certification pathways. Mumbai and Hyderabad production hubs attract platform investment for subscriber acquisition in Hindi and Telugu markets.
South Korea
Seoul-based studios export K-drama and K-pop IP through Netflix and domestic platform partnerships. Korea Communications Commission broadcasting standards govern content distribution licensing. The Hongdae and Gangnam districts concentrate talent agencies and production facilities for global format adaptation.
United Kingdom
London production houses develop high-end drama and unscripted formats for international co-production. Ofcom broadcasting codes and the Digital Economy Act shape rights enforcement for streaming distribution. The Soho post-production cluster services global streamers with localization and finishing capabilities.
Japan
Tokyo animation studios license anime IP through merchandise, theatrical, and streaming windows. METI content industry promotion programs support IP globalization initiatives. The Akihabara and Nakano districts sustain decades-long character-based retail relationships through limited-edition release cycles.
IP in Media and Entertainment Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated studios that control both production pipelines and direct-to-consumer distribution platforms. Three archetypes dominate: legacy studios with century-old character libraries, technology platforms funding original content to reduce licensing dependency, and specialist animation houses with franchise extension expertise. Competitive maneuvering concentrates on exclusive IP acquisition and proprietary streaming infrastructure deployment.
Within the legacy studio tier, Walt Disney Company and Warner Bros. Discovery, Inc. exemplify integrated production-distribution models that amortize development costs across theatrical, streaming, and experiential channels. Netflix, Inc. occupies a distinct position as a technology-native platform that has backward integrated into original content creation to reduce third-party licensing exposure. These three entities anchor the competitive structure through divergent capital allocation strategies toward franchise construction versus algorithmic content personalization.
| Leading Market Players |
|---|
| Walt Disney Company |
| Comcast Corporation |
| Warner Bros. Discovery, Inc. |
| Paramount Global |
| News Corporation |
| Netflix, Inc. |
| Amazon.com, Inc. |
| Alphabet Inc. |
| Sony Group Corporation |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on cloud infrastructure hyperscalers compresses margin pools for independent producers while amplifying pricing power for vertically integrated studios. This concentration dynamic stratifies content commissioning rates across premium franchise extensions, mid-tier originals, and economy catalog licensing tiers.
Pricing Analysis
The technology-generation pricing gap separates AI-native production workflows from legacy pipelines and emerging synthetic media platforms. Three-tier pricing structure across premium, standard, and economy levels dominates content licensing, with franchise properties commanding exclusivity premiums and back-catalog titles facing commoditization. Price differentiation rests on talent attachment tier and platform exclusivity window length. Cost compression in mid-tier originals is intensifying because generative tools collapse pre-production labor requirements. Ad-supported tiers exhibit highest price sensitivity among subscriber segments, while theatrical windowing maintains lowest sensitivity for event-level releases.
Supply Chain Analysis
Contract-manufacturing concentration among Amazon Web Services, Microsoft Azure, and Google Cloud Platform holds transcoding and distribution capacity for streaming infrastructure. Geographic supply concentration centers on the United States, Ireland, and Singapore for data center operations. Raw material dependencies include GPU clusters, high-bandwidth fiber, and localized content delivery nodes. Supply chain risk hinges on single-source vulnerability for cloud compute contracts that lock studios into multi-year infrastructure commitments. Distribution runs through direct-to-consumer applications with app store gatekeeping fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Copyright term extensions and platform liability frameworks erect barriers that compound incumbent advantages over multi-decade horizons.
For Market Incumbents: Insulate proprietary character libraries through trademark portfolio expansion into synthetic likeness protections. Deepen backward integration into virtual production stages to capture cost efficiencies from real-time rendering pipelines. The EU AI Act's transparency mandates threaten unlabeled synthetic content distribution, making certification investment a critical lever for platform differentiation.
For New Entrants and Emerging Players: Build out local-language original production in India's regional markets where Ministry of Information and Broadcasting guidelines favor domestic IP certification. The most penetrable segment lies in podcast and audio IP where capital requirements remain minimal and advertising insertion technology enables rapid monetization. A direct-to-creator distribution angle bypasses platform gatekeeping through owned-and-operated streaming applications.
For Investors and Strategic Acquirers: The U.S. Copyright Office's evolving registration frameworks for AI-assisted works reshapes the acquisition landscape by clarifying enforceable ownership boundaries. Long-term viability concentrates on studios with franchise extension expertise and proprietary streaming infrastructure. Target acquisition archetypes include specialist animation houses with dormant character archives. The signal to watch is legislative movement on right-of-publicity federalization that would standardize synthetic likeness protections.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Disclosure Compliance System | The EU AI Act mandates provenance labeling for synthetic media outputs from French and German producers. |
| Virtual Production Stage Deployment | LED volume technology collapses location shooting requirements for genre content in London and Los Angeles. |
| Regional Language Original Commissioning | Hindi and Telugu productions attract Netflix and Disney platform investment for Indian subscriber acquisition. |
| Character Archive Experiential Licensing | Tokyo animation studios monetize decades-old IP through Akihabara limited-edition retail partnerships. |
| Cloud Infrastructure Diversification | Multi-hyperscaler contracts reduce single-source dependency for studio transcoding workloads. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, streaming platform subscriber disclosures, and copyright registration databases. Interviews with content licensing executives, post-production facility operators, and talent agency representatives informed demand-side validation. Customs data on physical media shipments and theatrical box office reporting supplemented supply-side triangulation. Bottom-up title-level revenue modeling and top-down platform aggregate analysis converged on segment sizing.
Forecast inputs incorporate content commissioning volumes, subscriber growth trajectories, and technology adoption curves across the projection horizon. Segmentation dimensions modeled include content type, revenue stream, distribution channel, and ownership model with regional production cluster overlays. CAGRs derive from trend extrapolation of historical commissioning patterns adjusted for synthetic media penetration rates. Industry-specific inputs include virtual production capital expenditure cycles and streaming platform content amortization schedules.
Sensitivities concentrate around unresolved fair-use boundaries for AI training data and platform concentration enforcement actions. Forecasts reflect assumptions on regulatory clarity timelines and talent union negotiation outcomes. Quarterly review of copyright office guidance documents and synthetic media litigation dockets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Entertainment Transcription Market
Digital Media
Music Rights Management Market
Digital Media
Drone Wedding Photography Market
Digital Media
Asia-Pacific Webtoons Market
Digital Media
Animation and VFX Market
Digital Media
Webcomics Market
Digital Media
Digital Media Market
Digital Media
APAC Media and Entertainment Market
Digital Media
Global Stock Video Market
Digital Media
APAC DOOH Market
Digital Media
Wedding Photography Market
Digital Media
VFX Market
Digital Media
Middle East Gaming Market
Digital Media
ACGN Subculture Market
Digital Media
Professional Dubbing Services Market
Digital Media
Europe Inflight Entertainment and Connectivity Market