
 Global Music Video Production Market | 2026-2036
Global Music Video Production Market Size, Share, and Industry Trends Forecast 2026-2036
Global Music Video Production Market Foresight
The gap between blockbuster cinematic productions and low-budget social-native clips is realigning how budgets flow through the industry. Universal Music Group leverages its in-house creative divisions to control production quality across tiered releases. Sony Music Entertainment sustains competitive pressure through specialized visual content labs in multiple territories. Warner Music Group anchors premium output via direct-to-streaming theatrical partnerships that bypass traditional broadcast windows.
Music video production encompasses the end-to-end creation of visual content synchronized to recorded music, spanning pre-production planning, principal photography with cinema-grade cameras operating at 4K to 8K resolution, and post-production workflows involving color grading, VFX compositing, and audio-visual synchronization. Its commercial purpose centers on audience engagement, brand extension for recording artists, and monetization through advertising, subscription, and licensing revenue streams. Live action production dominates budget allocation among major labels, while motion graphics and hybrid formats capture fastest-growing share as short-form platform algorithms reward rapid visual turnover. Distribution through online video platforms and music streaming services now commands the primary margin pool, displacing legacy television network placements.
The U.S. Federal Communications Commission governs broadcast standards for televised music content, while the EU Digital Services Act imposes transparency and accountability requirements on platform-hosted video distribution. China's National Radio and Television Administration enforces content review protocols that shape export-ready production specifications for international artists targeting that market. Stakeholders must monitor evolving platform-specific content moderation frameworks and regional copyright enforcement intensities as determinants of market access and production cost structures.
Market Dynamics
Algorithmic distribution on short-form platforms is compressing production timelines from months to days, forcing labels to restructure creative workflows around real-time content iteration rather than traditional release cycles.
Growth Catalysts
- EU Digital Services Act transparency mandates:Platform accountability requirements are accelerating investment in rights-cleared visual asset libraries and automated content verification systems.
- Short-form platform algorithms:TikTok and YouTube Shorts reward rapid visual turnover, pulling budget allocation toward motion graphics and hybrid formats that iterate faster than live-action shoots.
- South Korea's K-pop export engine:Seoul-based production clusters generate cross-border visual content demand that sustains specialized post-production facilities across the Asia-Pacific rim.
Market Restraints
- Cinema-grade camera sensor shortages:Supply concentration among Japanese and German optical manufacturers creates procurement bottlenecks for 8K principal photography equipment.
- China's NRTA content review protocols:Mandatory pre-publication screening adds 4-6 week delays and reshoot costs for artists targeting mainland distribution.
- VFX labor cost inflation:Skilled compositor wages in London and Los Angeles have outpaced budget growth, squeezing mid-tier production margins.
Strategic Opportunities
- India's untapped regional language markets:Hindi, Tamil, and Telugu music video production remains underpenetrated by international labels despite platform subscriber growth.
- Virtual production stage convergence:LED volume technology combined with real-time game engines enables location-agnostic shooting that collapses travel and set construction costs.
- Direct-to-artist distribution platforms:Bypassing label-controlled release windows allows independent creators to capture platform revenue shares previously absorbed by intermediaries.
Industry Challenges
- Colorist and VFX supervisor talent scarcity:Pipeline bottlenecks emerge as demand for HDR grading and real-time compositing outstocks trained specialists in major production hubs.
- Cross-platform format fragmentation:Aspect ratio, duration, and codec specifications vary across YouTube, Instagram Reels, and TikTok, multiplying deliverable versions per release.
- Content ID false positive disputes:YouTube's automated rights management generates takedown errors that delay monetization and require manual legal intervention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Music Video Production Market |
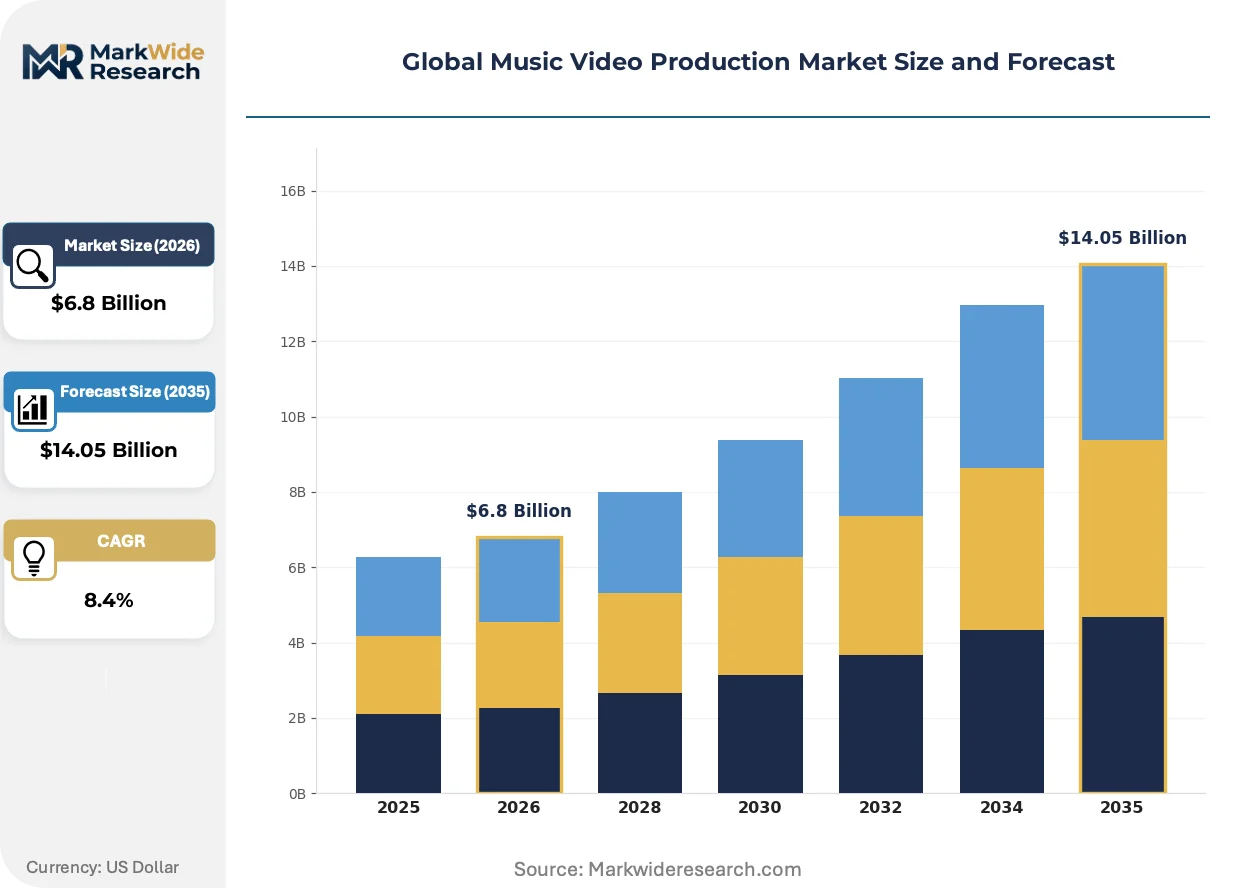
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
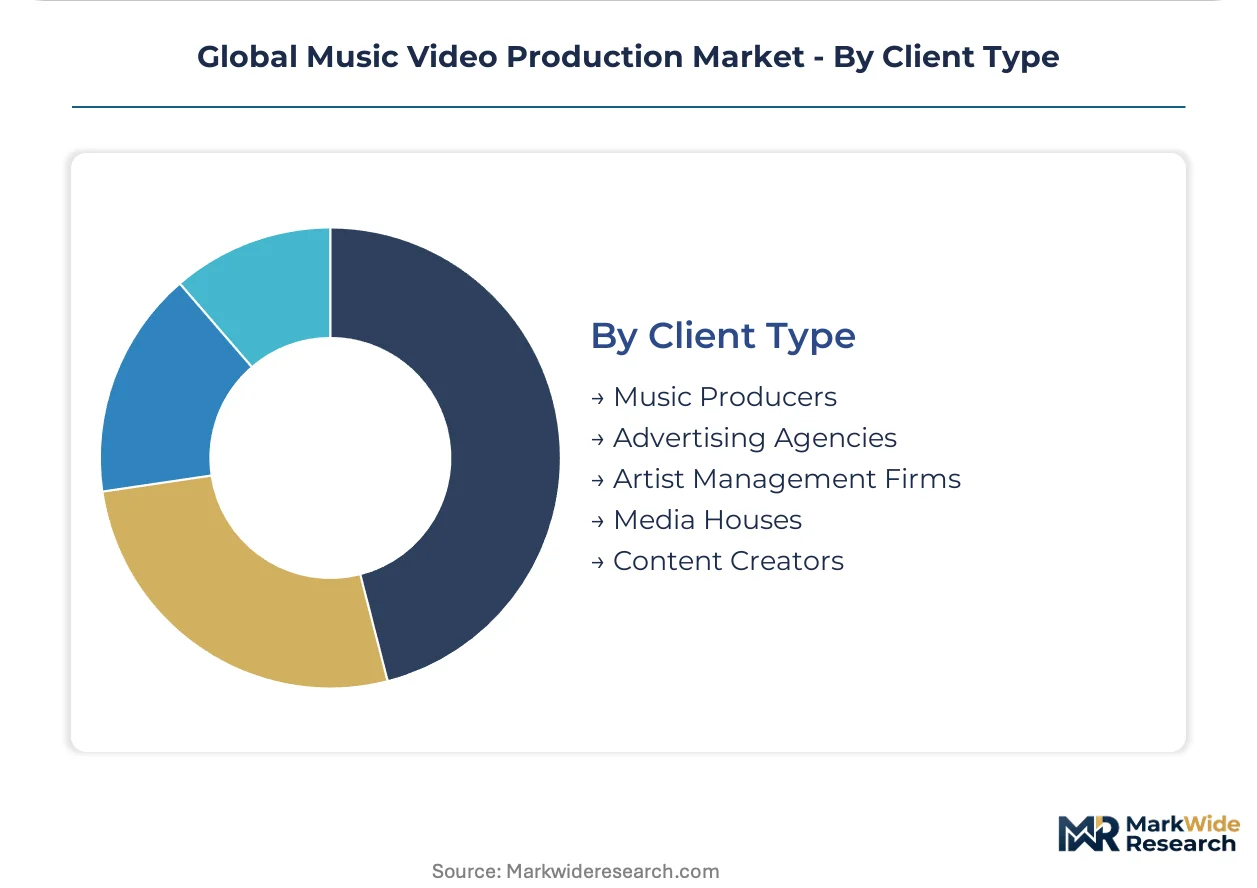
| Segmentation | Production Type: Live Action, Animation, Stop Motion, Motion Graphics, Hybrid Application: Brand Promotion, Independent Artists, Record Labels, Event Marketing, Social Media Campaigns Distribution Channel: Television Networks, Online Video Platforms, Social Networking Sites, Music Streaming Services, Video Sharing Websites Client Type: Music Producers, Advertising Agencies, Artist Management Firms, Media Houses, Content Creators |
| Companies Covered | Universal Music Group, Sony Music Entertainment, Warner Music Group, Vevo, MTV Networks, Roc Nation, Lighthouse Films, Go Big LA, Video Ink, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Music Video Production Market Shifts & Advancements
Real-time rendering and AI-assisted post-production tools are collapsing traditional production hierarchies, enabling smaller crews to deliver broadcast-quality output while regulatory pressure on platform accountability is reshaping rights documentation requirements.
Virtual production LED volumes is electrifying location-heavy music video shoots by replacing green screen compositing with in-camera final-pixel capture. Major labels in Los Angeles and London are retrofitting soundstages with wraparound LED arrays at accelerating pace. This technology is compressing post-production schedules from weeks to days while reducing location travel costs by half.
The EU Digital Services Act's transparency and accountability framework is imposing new documentation burdens on platform-hosted video distribution. Labels must now maintain auditable chains of title for all visual assets used in commissioned content. Productions targeting European platform distribution are responding by embedding rights clearance earlier in pre-production planning.
Artist-controlled release strategies are fragmenting traditional label-dominated distribution channels. Direct upload capabilities on TikTok and YouTube enable musicians to bypass editorial gatekeepers and test visual concepts before full production investment. This pattern is most visible among independent artists in the United Kingdom and United States, where platform-native creators now command subscriber bases rivaling major label rosters.
Global Music Video Production Market Segmentation
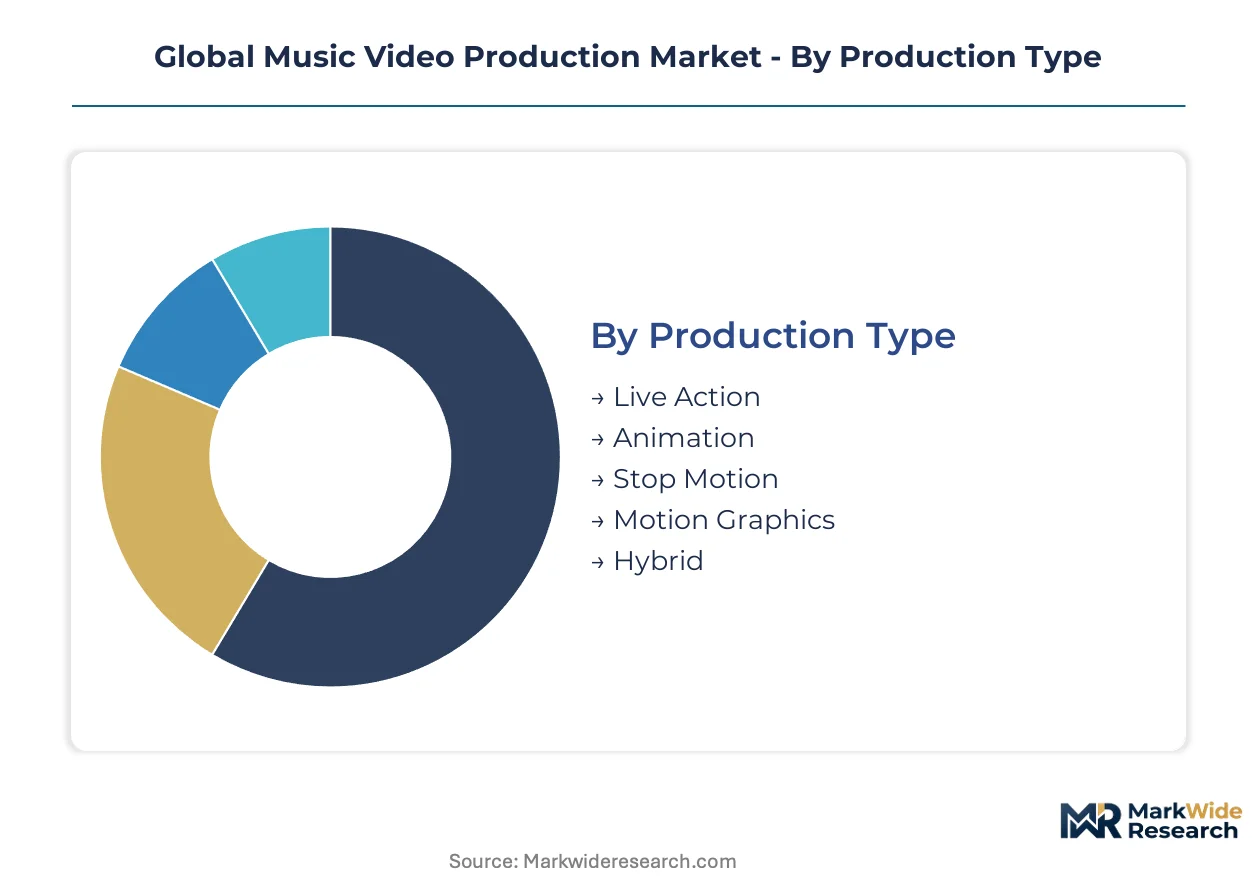
Production type determines crew composition and equipment procurement cycles. Application context shapes creative briefs and platform optimization requirements. Distribution channel selection now dominates post-production deliverable specifications.
Production Type:
Buyer decisions pivot on speed-to-delivery versus visual spectacle tradeoffs.
- Live Action:Principal photography with cinema-grade cameras captures human performance and environmental texture. Budget concentration flows toward Los Angeles and London soundstages where LED volume retrofits are collapsing location costs. Major labels anchor premium release slates here.
- Motion Graphics:Vector-based animation and typographic sequences enable rapid iteration for algorithm-driven platforms. Seoul and Tokyo studios specialize in K-pop and J-pop visual asset libraries that feed short-form content pipelines. TikTok and YouTube Shorts reward this format's production velocity.
- Animation:Frame-by-frame or computer-generated imagery delivers stylized narratives beyond physical production constraints.
- Stop Motion:Physical puppet and miniature photography creates distinctive tactile aesthetics for niche artistic positioning.
- Hybrid:Compositing live footage with graphic elements balances authenticity with cost efficiency for mid-tier releases.
Volume sits with Live Action; growth tilts toward Motion Graphics.
Application:
End-use context restructures creative workflows and rights clearance protocols.
- Record Labels:Commissioned productions for major label rosters demand broadcast-quality deliverables across multiple aspect ratios. Universal Music Group, Sony Music Entertainment, and Warner Music Group maintain in-house creative divisions that control tiered release strategies. Rights documentation requirements intensify under EU Digital Services Act mandates.
- Social Media Campaigns:Platform-native content prioritizes vertical formats and sub-60-second durations optimized for TikTok and Instagram Reels. Independent creators in the United Kingdom and United States bypass traditional gatekeepers through direct upload capabilities. Algorithmic distribution rewards rapid visual turnover over polished production values.
- Brand Promotion:Synchronized visual content extends corporate identity through artist partnerships and licensed music integration.
- Independent Artists:Self-funded productions leverage affordable camera equipment and cloud-based post-production tools.
- Event Marketing:Concert footage and behind-the-scenes documentation supports touring cycles and ticket sales.
Revenue concentrates with Record Labels; expansion accelerates most quickly in Social Media Campaigns.
Distribution Channel:
Platform specifications multiply deliverable versions per release.
- Online Video Platforms:YouTube's Content ID system and monetization infrastructure command the primary margin pool for long-form content. The platform's automated rights management generates false positive disputes that delay revenue recognition. Labels invest in auditable asset chains to preempt takedown errors.
- Music Streaming Services:Spotify and Apple Music are commissioning original visual content to differentiate subscription offerings. These platforms require platform-exclusive windows that fragment traditional release strategies. Cross-border licensing complexity shapes production specifications for international artists.
- Television Networks:FCC broadcast standards govern televised music content in the United States with declining budget allocation.
- Social Networking Sites:Instagram and Facebook prioritize feed-native formats with muted autoplay optimization.
- Video Sharing Websites:Vimeo and niche platforms serve professional creative communities with quality-over-velocity positioning.
Investment flows toward Online Video Platforms; Music Streaming Services are gaining share fastest.
Client Type:
Procurement authority determines budget scale and creative control distribution.
- Artist Management Firms:Representation entities coordinate visual content strategy across touring, merchandise, and digital release cycles. CAA, WME, and independent managers in London and Los Angeles are building in-house production capabilities. Direct-to-artist platform relationships are fragmenting traditional label intermediation.
- Advertising Agencies:Creative shops commission music-synchronized content for brand campaigns requiring rights-cleared assets. WPP and Publicis networks maintain specialized music video divisions in New York and Paris. Compressed timelines from pitch to delivery strain traditional production hierarchies.
- Music Producers:Recording studios and production houses package visual content with audio deliverables.
- Media Houses:Broadcast and publishing conglomerates commission documentary and promotional visual content.
- Content Creators:Individual platform-native creators self-produce with smartphone cameras and AI-assisted editing tools.
Spend aggregates with Artist Management Firms; Advertising Agencies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors global music video production volume through its concentration of soundstages, post-production facilities, and label headquarters. Seoul and London form secondary poles of specialized creative output. Production clusters in these three cities generate the majority of premium-tier visual content commissioned by major recording labels.
United States
FCC broadcast standards govern televised music content while YouTube's Content ID system shapes platform distribution economics. Los Angeles soundstages are retrofitting LED volumes at accelerating pace to collapse location costs for major label productions. New York and Atlanta sustain secondary production hubs serving hip-hop and R&B visual content pipelines.
South Korea
K-pop export demand sustains specialized post-production facilities across the Asia-Pacific rim. The Korea Communications Commission enforces content standards for domestic distribution that shape production specifications for international crossover releases. Seoul's Gangnam and Mapo districts concentrate motion graphics studios feeding short-form platform algorithms.
United Kingdom
Independent artists leverage direct upload capabilities on TikTok and YouTube to bypass traditional gatekeepers. Ofcom regulations govern broadcast content while the EU Digital Services Act imposes transparency requirements on platform-hosted distribution. London's Shoreditch and Soho districts anchor premium post-production houses serving major label rosters.
China
NRTA content review protocols add pre-publication screening delays for artists targeting mainland distribution. Beijing and Shanghai production clusters adapt export-ready specifications to navigate mandatory screening requirements. Shenzhen-based technology firms supply LED volume hardware retrofitted into international soundstages.
India
Hindi, Tamil, and Telugu music video production remains underpenetrated by international labels despite platform subscriber growth. TRAI regulations govern broadcast distribution while platform-native creators build subscriber bases through direct upload strategies. Mumbai's Andheri and Chennai's Kodambakkam districts concentrate regional language production facilities.
Global Music Video Production Market Competitive Landscape
Premium-margin players sit above commodity-margin players across production quality tiers, with major labels controlling broadcast-quality output and independent creators capturing algorithm-driven short-form segments. The market structures around three archetypes: vertically integrated major labels with in-house creative divisions, specialized production boutiques serving tiered release strategies, and platform-native independents leveraging direct distribution. Consolidation pressures intensify as LED volume technology raises capital barriers to premium-tier entry. Competitive moves concentrate on strategic partnerships with streaming platforms and selective acquisition of post-production facilities.
Within the integrated major label tier, Universal Music Group, Sony Music Entertainment, and Warner Music Group anchor premium output through captive creative divisions and direct-to-streaming theatrical partnerships. These entities exemplify the vertically integrated archetype controlling production quality across tiered release slates. Vevo occupies a distinct position as a platform-specific distributor monetizing long-form content through advertising infrastructure. Specialized boutiques including Roc Nation and Lighthouse Films represent the agile mid-tier segment serving artist management firms with compressed timeline deliverables.
| Leading Market Players |
|---|
| Universal Music Group |
| Sony Music Entertainment |
| Warner Music Group |
| Vevo |
| MTV Networks |
| Roc Nation |
| Lighthouse Films |
| Go Big LA |
| Video Ink |
| Others |
Supply & Pricing Matrix
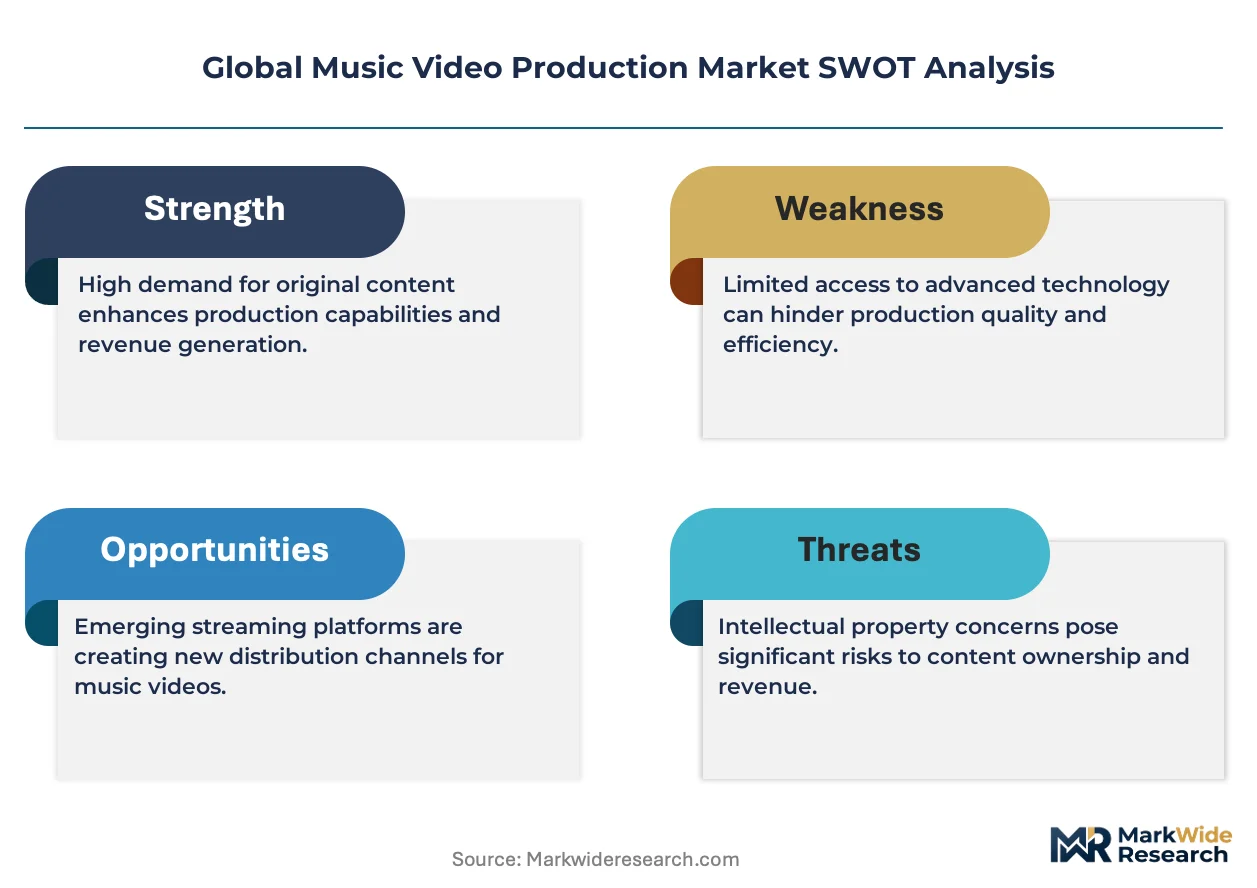
EU Digital Services Act transparency mandates gate qualified supply access and premium-tier pricing power by requiring auditable rights documentation that only capitalized production houses can maintain. This regulatory filter stratifies the market between compliant premium producers and excluded budget operators, concentrating margin capture among entities with embedded legal infrastructure.
Pricing Analysis
Value-based pricing anchored to platform monetization throughput dominates major label commissioning, with Universal Music Group and Sony Music Entertainment negotiating revenue-share structures tied to Content ID performance. Price differentiation rests on resolution tier and cross-platform deliverable breadth, with 8K HDR packages commanding substantial premiums over HD single-format outputs. Cost compression in mid-tier live-action production is intensifying because LED volume technology collapses location budgets and enables faster turnaround. Independent artists and platform-native creators exhibit highest price sensitivity, while streaming services commissioning original content show lowest sensitivity due to subscriber retention value.
Supply Chain Analysis
International freight costs for cinema-grade camera equipment from Germany and Japan amplify procurement expenses for productions outside Los Angeles and London. Supply concentration centers on Japanese optical sensor manufacturers, German camera system integrators, and South Korean LED panel fabricators. Raw material dependencies span precision glass substrates, CMOS sensor wafers, and high-refresh-rate display modules. Single-source vulnerability in 8K sensor fabrication creates procurement bottlenecks when demand spikes. Distribution runs through specialized equipment rental networks that maintain regional inventory pools in Los Angeles, London, and Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virtual production LED volumes are displacing legacy green-screen workflows, forcing stakeholders to recalibrate capital allocation toward real-time rendering infrastructure and game-engine technical crews.
For Market Incumbents: Deploy captive post-production facilities to defend margin position against platform-native competitors and VFX labor cost inflation in London and Los Angeles. Major labels should accelerate LED volume retrofitting of owned soundstages to collapse location dependency and compress delivery timelines. Consolidation of specialized motion graphics boutiques in Seoul and Tokyo secures algorithm-driven content pipeline access. For New Entrants and Emerging Players: Enter via India's Hindi, Tamil, and Telugu regional language markets where international label penetration remains limited despite platform subscriber expansion. Direct-to-artist distribution platforms offer the most penetrable entry vector, bypassing traditional label gatekeepers through TikTok and YouTube upload capabilities. Target social media campaign production for mid-tier artists seeking rapid-turnover content without major label overhead. For Investors and Strategic Acquirers: Warner Music Group's theatrical partnership announcements signal streaming platform appetite for premium direct-to-service content, indicating that exclusive windowing deals are the leading indicator that long-form music video investment viability is strengthening. Acquisition targets should focus on LED volume-equipped production boutiques with established platform relationships. Monitor EU Digital Services Act enforcement intensity as the signal for compliance-cost-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| LED Volume Stage Buildout | Universal Music Group's retrofitting program halves location costs and compresses post-production schedules. |
| Rights-Cleared Asset Library Expansion | Sony Music Entertainment's visual content labs preempt EU Digital Services Act documentation requirements. |
| Direct-to-Streaming Theatrical Partnership | Warner Music Group's platform-exclusive windows bypass traditional broadcast intermediaries. |
| Regional Language Market Entry | Independent producers in Mumbai and Chennai capture underserved Hindi and Tamil platform demand. |
| AI-Assisted Post-Production Integration | Motion graphics studios in Seoul deploy real-time rendering to feed TikTok algorithmic velocity requirements. |
Research Methodology
Multi-period observation of platform commissioning volumes, LED volume adoption rates, and rights management dispute frequencies anchored the trend analysis, supplemented by interviews with label creative directors, post-production facility operators, artist management representatives, and streaming platform content acquisition leads. Secondary validation drew from FCC broadcast standards filings, EU Digital Services Act implementation guidance, Korea Communications Commission content regulations, and China NRTA screening protocols. Bottom-up production volume estimates triangulated against top-down platform advertising revenue attribution.
Input-output matrices modeled production type, application context, distribution channel specifications, and client procurement authority across the projection horizon. Segmentation dimensions included live-action versus motion graphics format split, major label versus independent artist commissioning source, and long-form versus short-form platform optimization. CAGRs derived from regression analysis against streaming subscriber growth curves and platform content investment disclosures. Forecast inputs incorporated LED volume cost depreciation trajectories and VFX labor wage indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU regulatory enforcement or extended China content review delays. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Anime Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Europe Animation, VFX and Post Production Market
Digital Media
Digital Music Content Market
Digital Media
Latin America Inflight Entertainment and Connectivity Market
Digital Media
Stock Music Software Market
Digital Media
APAC Animation, VFX and Post Production Market
Digital Media
Germany Animation, VFX and Post Production Market
Digital Media
India Webtoons Market
Digital Media
US Automatic Content Recognition Market
Digital Media
US Animation, Vfx and Post Production Market
Digital Media
Pro AV Market
Digital Media
Photography Services Market
Digital Media
Media and Entertainment Market
Digital Media
Asia-Pacific Animation Market
Digital Media
Sound Effects Services Market