
 Information Short Video Market | 2026-2036
Information Short Video Market Size, Share, and Industry Trends Forecast 2026-2036
Information Short Video Market Insights
Creator economy talent pools are rotating toward platform-native production skills, reshaping how content studios staff their operations. ByteDance Ltd. leverages its proprietary recommendation engine to sustain engagement loops across TikTok and Douyin ecosystems. Kuaishou Technology anchors its position through deep penetration into lower-tier Chinese cities and live-streaming commerce integration. Tencent Holdings Ltd. competes by weaving short video into WeChat's super-app infrastructure, blurring distribution boundaries.
Information short video denotes audiovisual content typically under five minutes, encoded for adaptive bitrate streaming across variable network conditions, designed to deliver concise knowledge or narrative payloads. These assets serve commercial purposes ranging from brand awareness to direct-response conversion, with production workflows increasingly automated through AI-assisted editing and templated asset generation. Educational and tutorial content types command disproportionate attention from platform recommendation systems due to higher completion rates and repeat viewing behavior. User-generated production quality segments attract the largest volume base, though corporate-grade output captures concentrated advertising expenditure and premium placement access.
FDA guidelines on health-related content claims, EU AI Act transparency mandates for algorithmic curation, and China's SAMR provisions on data privacy and antitrust enforcement collectively elevate operational compliance thresholds for cross-border platform operators. India's IT Rules and China's Cyberspace Administration standards further fragment the regulatory landscape, forcing localized content governance investments. Stakeholders must weigh jurisdictional compliance burdens against audience scale when prioritizing geographic expansion sequencing and platform feature deployment.
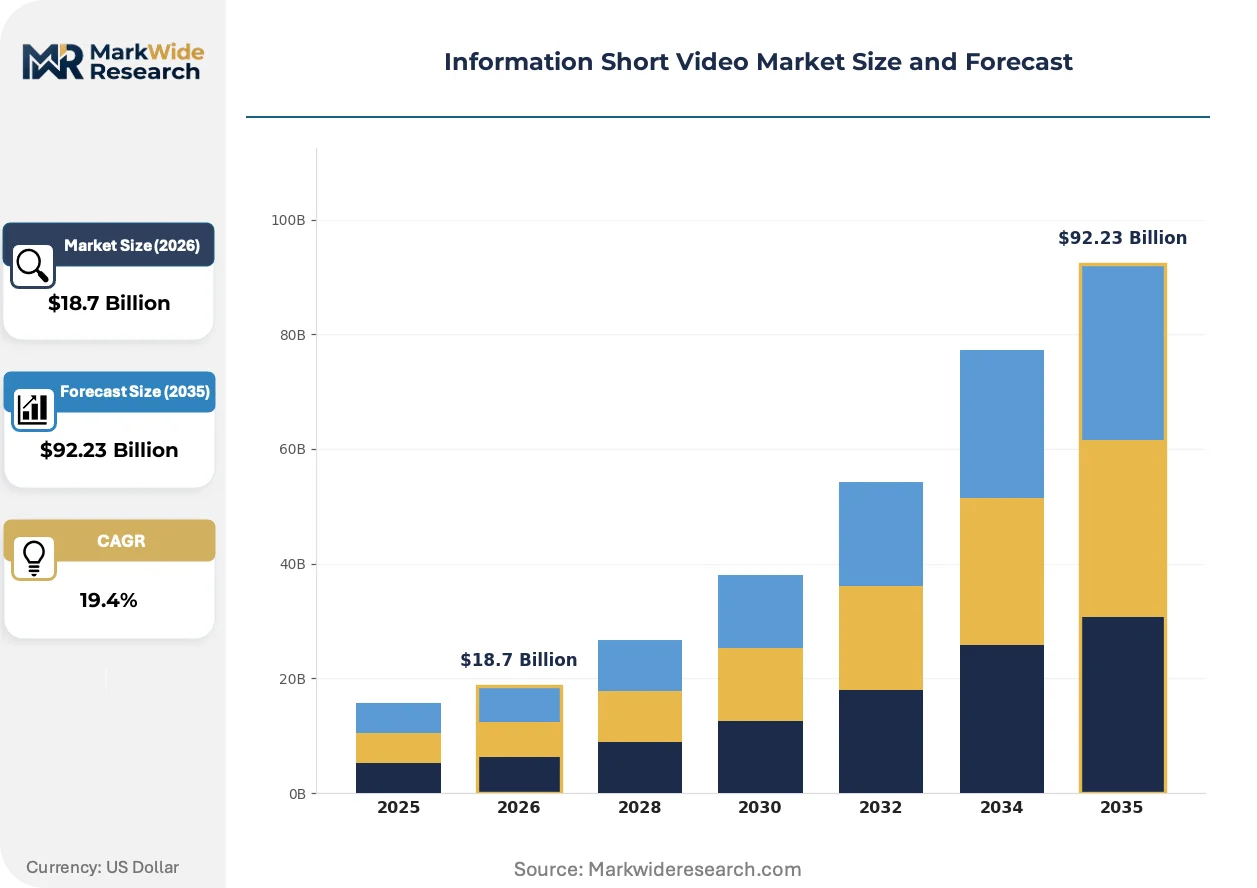
Market Dynamics
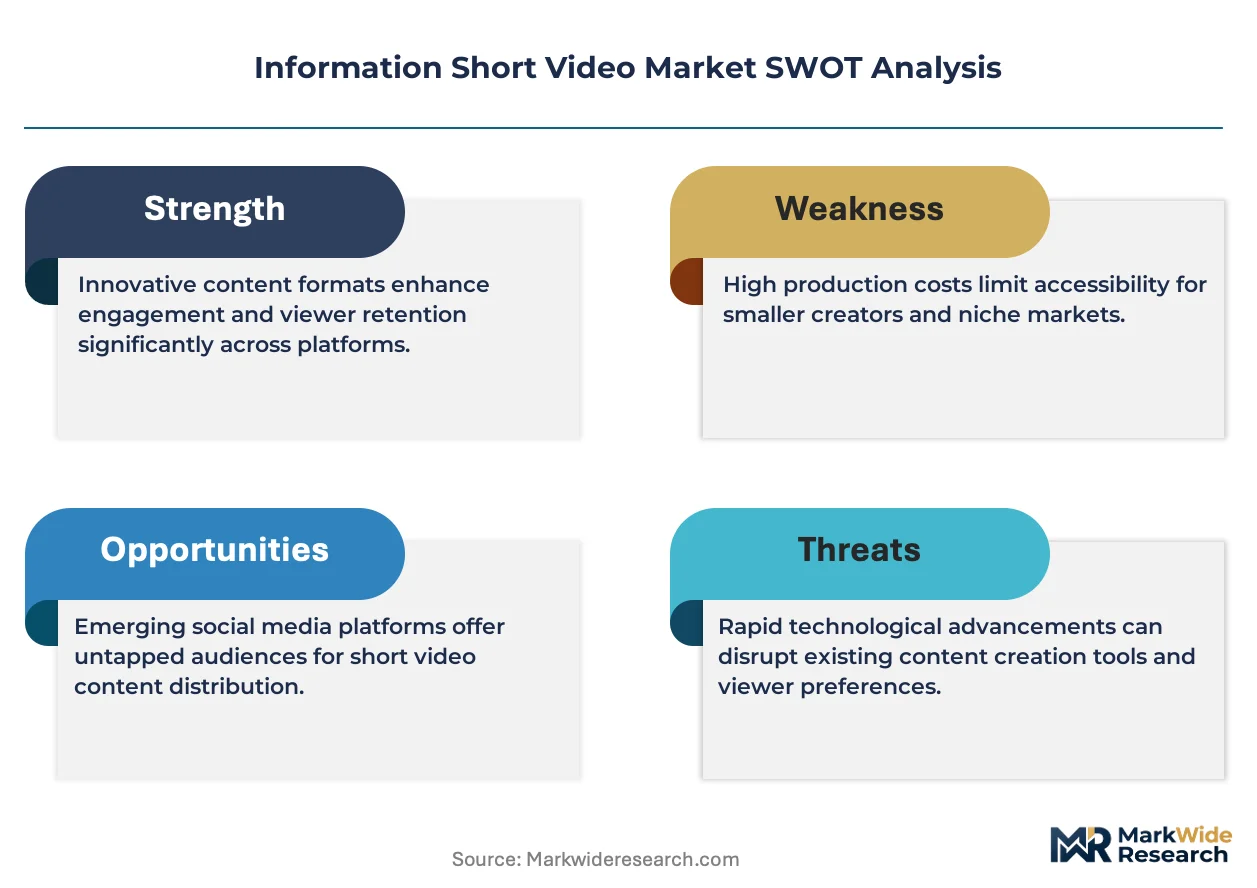
Algorithmic recommendation engines are compressing content discovery timelines, forcing creators and platforms to optimize for completion-rate signals rather than production budget alone. This shift rewards behavioral data infrastructure over traditional media buying power.
Growth Catalysts
- Live-streaming commerce integration:Chinese platforms demonstrate that real-time product demonstration within short video formats converts viewers at rates unattainable through static e-commerce listings.
- EU AI Act transparency mandates:European algorithmic disclosure requirements paradoxically accelerate investment in explainable recommendation systems that improve content-audience matching precision.
- Regional language content creation:India's 22 scheduled languages drive platform localization that unlocks previously unreachable user segments in tier-2 and tier-3 cities.
Market Restraints
- Compute cost volatility:Training and inference workloads for generative video tools depend on GPU supply concentrated among Taiwan Semiconductor Manufacturing and NVIDIA, exposing production economics to geopolitical friction.
- SAMR data localization:China's State Administration for Market Regulation requires domestic storage of user behavioral data, raising infrastructure costs for foreign platform operators seeking market access.
- Technical limitation in real-time rendering:Adaptive bitrate streaming for sub-5-minute formats still struggles with network handoff reliability in emerging market mobile environments.
Strategic Opportunities
- Underpenetrated creator tooling in Southeast Asia:Indonesia and Vietnam lack localized AI-assisted editing platforms, creating white space for template-driven production suites.
- Educational content certification:India's BIS framework for digital learning materials offers first-mover advantage to platforms aligning content with formal credentialing pathways.
- Convergence of computer vision and natural language processing:Automated scene segmentation combined with script generation compresses post-production timelines from hours to minutes.
Industry Challenges
- Platform-native production talent scarcity:Traditional video editors lack fluency in vertical-format composition and hook-rate optimization, forcing expensive reskilling programs.
- Cross-border content moderation complexity:India's IT Rules 2021 and EU Digital Services Act impose conflicting takedown timelines and appeal procedures on the same content asset.
- Legacy advertising measurement integration:Brand safety tools designed for display and television fail to capture context in rapidly shifting short-form feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Information Short Video Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Educational, Promotional, Entertainment, Tutorial Distribution Channel: Social Media, Streaming Platforms, Email Marketing, Websites Target Audience: Students, Professionals, General Public, Businesses Production Quality: Low Budget, High Quality, User-Generated, Corporate |
| Companies Covered | ByteDance Ltd., Kuaishou Technology, Tencent Holdings Ltd., Meta Platforms, Inc., Beijing Weiran Network Technology Co., Ltd., Google, Snap Inc., Yixia Technology, Shenzhen Big Head Brothers Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Information Short Video Market Trends and Innovations
Production workflows are fragmenting into specialized micro-services, with AI handling discrete tasks previously requiring human editorial judgment. This decomposition redistributes value toward data infrastructure and away from conventional studio assets.
Generative adversarial networks for automated B-roll insertion are decomposing the traditional editor role into prompt engineering and quality assurance functions. Mid-sized content studios in South Korea and Brazil adopt these tools fastest, cutting per-asset labor hours by half. The technology is decomposing established pricing for post-production services as software substitutes for junior editing staff.
EU AI Act algorithmic audit requirements are forcing platforms to document recommendation logic for regulatory review. Operators must now maintain technical documentation trails that were previously proprietary trade secrets. Educational and news content categories face the heaviest documentation burden, slowing feature deployment cycles in European markets.
Brand procurement of short-form inventory is consolidating through self-serve platforms that disintermediate media agencies. Direct platform buying tools now handle campaign setup, targeting, and reporting without third-party intermediation. This shift concentrates most visibly in North American consumer packaged goods verticals, where marketing teams build in-house trading desks.
Information Short Video Market Segmentation
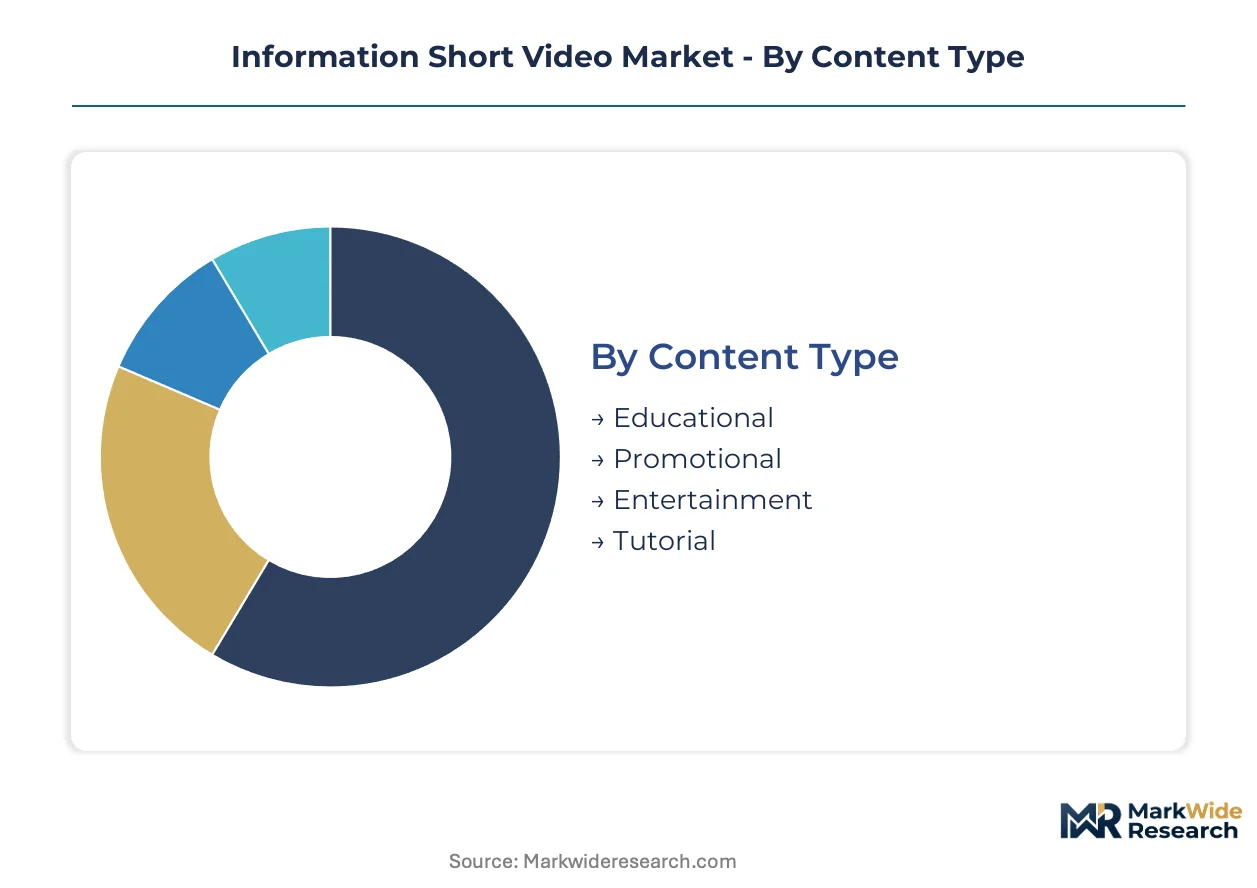
Segmentation in the Information Short Video Market reveals how production economics and distribution infrastructure allocate value across content categories. Distinct technical requirements and audience behaviors within each segment dictate platform investment priorities and creator monetization pathways.
Content Type:
Educational and tutorial formats face intensifying substitution pressure from interactive learning platforms and AI chat interfaces that deliver comparable knowledge payloads without video production overhead.
- Educational:Structured knowledge delivery encoded for adaptive streaming, typically 90-180 seconds, optimized for completion-rate signals. Demand concentrates in India's tier-2 and tier-3 cities where regional language content unlocks previously unreachable student segments constrained by English-medium platform defaults.
- Tutorial:Step-by-step procedural demonstration with high replay value and pause-rewind interaction patterns. Professionals in South Korea and Brazil adopt AI-assisted editing tools fastest here, compressing post-production timelines from hours to minutes while maintaining instructional clarity.
- Promotional:Brand-sponsored content designed for direct-response conversion through embedded product demonstration.
- Entertainment:Narrative or spectacle-driven formats prioritizing emotional engagement over information density.
Educational content anchors the volume base while Tutorial gains share at the steepest rate.
Distribution Channel:
Cost tier differentiation separates infrastructure-heavy streaming deployments from lightweight social distribution, with email and owned websites occupying intermediate positions on customer acquisition economics.
- Social Media:Algorithmic curation platforms with proprietary recommendation engines optimizing for dwell time and share velocity. ByteDance's TikTok and Douyin ecosystems sustain engagement loops through behavioral data infrastructure that traditional media buying power cannot replicate.
- Streaming Platforms:Subscription or ad-supported services with higher production quality thresholds and longer-form content adjacencies. China's SAMR data localization requirements raise infrastructure costs for foreign operators seeking market access through this channel.
- Email Marketing:Direct distribution with measurable open-rate and click-through attribution, favored by B2B software verticals.
- Websites:Owned-channel deployment with full data sovereignty and custom player implementations.
Social Media captures the largest audience aggregate while Streaming Platforms expand most quickly in markets with improving broadband penetration.
Target Audience:
Volume concentration varies sharply by audience type, with professional segments commanding premium advertising rates despite smaller absolute reach.
- Professionals:Time-constrained viewers seeking actionable insights applicable to workplace performance. India's BIS framework for digital learning materials offers first-mover advantage to platforms aligning content with formal credentialing pathways for this segment.
- Businesses:Organizational procurement of training and internal communication assets with compliance documentation requirements. EU AI Act transparency mandates for algorithmic curation elevate operational thresholds for vendors serving enterprise accounts.
- Students:Price-sensitive learners with high completion rates for structured curricula and repeat viewing behavior.
- General Public:Broadest reach with lowest per-viewer monetization and highest content moderation exposure.
Students anchor the volume base while Businesses climb the fastest on revenue per thousand impressions.
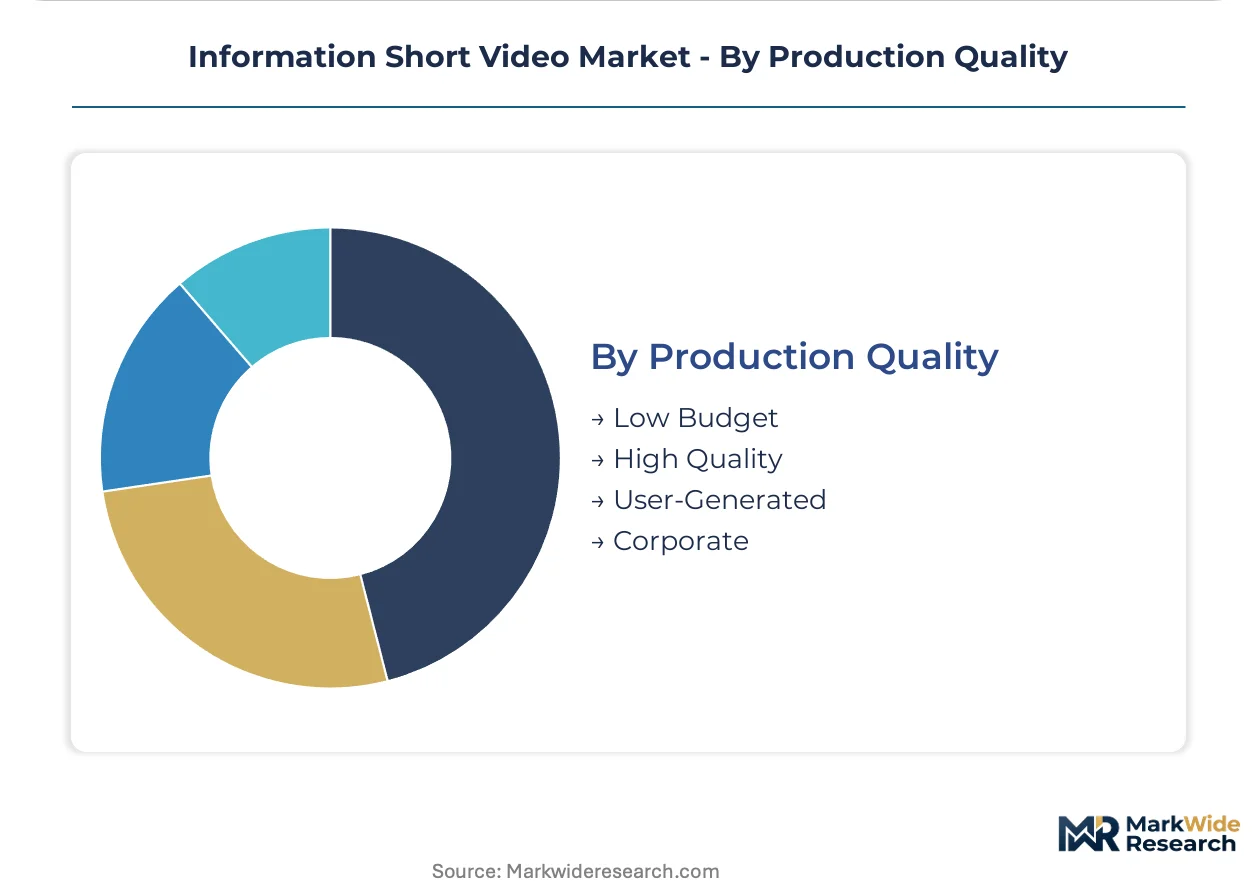
Production Quality:
Supply concentration in generative video tooling is decomposing the traditional editor role and redistributing value toward data infrastructure and prompt engineering capabilities.
- User-Generated:Creator-produced content using mobile-native tools and platform-supplied templates. Indonesia and Vietnam lack localized AI-assisted editing platforms, creating white space for template-driven production suites to capture this segment.
- Corporate:Brand-safeguarded output with legal review, accessibility compliance, and multi-language localization. FDA guidelines on health-related content claims and EU AI Act transparency mandates impose the heaviest documentation burden here.
- Low Budget:Minimal production infrastructure with raw footage and basic cuts, dominant in emerging market mobile-first environments.
- High Quality:Cinema-grade equipment and specialized crew with location shooting and custom scoring.
User-Generated anchors the volume base while Corporate shows the steepest expansion trajectory as brand safety requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes short-form video primarily through mobile-first, regional-language interfaces, while the United States and China diverge toward creator monetization infrastructure and live-streaming commerce respectively. This consumption-mix differential shapes platform investment priorities across geographies.
United States
Professional creators and brand advertisers drive demand for corporate-grade production tools and self-serve media buying platforms. The FTC scrutinizes influencer disclosure practices and native advertising transparency, elevating compliance documentation requirements. Los Angeles and New York anchor creator economy clusters where talent agencies negotiate platform-native content deals.
China
Live-streaming commerce integration and super-app distribution dominate consumption patterns distinct from Western markets. SAMR enforces data localization mandates and antitrust provisions that raise infrastructure costs for cross-border operators. Shenzhen and Hangzhou concentrate platform engineering talent and recommendation algorithm development.
India
Tier-2 and tier-3 city audiences propel regional language content creation at scale unmatched elsewhere. The IT Rules 2021 impose content takedown timelines and grievance redressal obligations on platform operators. Mumbai and Bangalore host creator studios localizing production workflows for Hindi, Tamil, Telugu, and Marathi segments.
South Korea
AI-assisted editing tool adoption accelerates fastest among mid-sized studios seeking post-production compression. The country's national broadcasting regulator maintains content classification standards for platform-distributed material. Seoul's Gangnam district clusters entertainment technology ventures integrating computer vision with short-form workflows.
Brazil
User-generated content volume expands through mobile-native creator tools lacking localized AI editing alternatives. ANVISA guidelines on health-related claims extend to wellness content distributed via short video formats. São Paulo anchors brand safety and advertising technology investments serving Latin American market expansion.
Information Short Video Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with ByteDance Ltd. and Tencent Holdings Ltd. commanding proprietary distribution infrastructure that smaller creators cannot replicate. The market structure rewards behavioral data infrastructure over production budget alone, compressing traditional media buying advantages. Three archetypes dominate: algorithm-native platform operators, super-app integrators, and specialized creator tooling vendors. Competitive moves concentrate on vertical integration into recommendation engine development and geographic expansion through localized content governance investments.
Within the integrated platform tier, ByteDance Ltd. exemplifies the algorithm-native archetype through its TikTok and Douyin ecosystems, while Tencent Holdings Ltd. represents super-app distribution strategy. Kuaishou Technology occupies a distinct position emphasizing live-streaming commerce penetration in lower-tier Chinese markets. These three entities anchor competitive dynamics through proprietary engagement loops that resist straightforward feature replication.
| Leading Market Players |
|---|
| ByteDance Ltd. |
| Kuaishou Technology |
| Tencent Holdings Ltd. |
| Meta Platforms, Inc. |
| Beijing Weiran Network Technology Co., Ltd. |
| Snap Inc. |
| Yixia Technology |
| Shenzhen Big Head Brothers Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
EU AI Act transparency mandates gate both platform qualification and price differentiation simultaneously, forcing vendors serving enterprise accounts to absorb compliance documentation costs that separate certified from uncertified supply tiers. This regulatory filter compresses margins at the mid-market while concentrating pricing power with operators possessing in-house algorithm audit capabilities.
Pricing Analysis
Long-term offtake contracts dominate enterprise procurement of creator tooling and platform infrastructure, though spot purchasing persists for campaign-based promotional content. Three-tier pricing structure across premium, standard, and economy levels separates corporate-grade output with legal review and accessibility compliance from user-generated mobile-native production. Pricing pressure stems from GPU supply concentration among Taiwan Semiconductor Manufacturing and NVIDIA exposing inference workloads to geopolitical friction. Brand advertisers show least price sensitivity for brand-safeguarded inventory, while individual creators in emerging markets resist subscription fees for editing tools.
Supply Chain Analysis
Inventory lead times for NVIDIA H100 and A100 accelerators now stretch 40-52 weeks, forcing content studios to pre-commit compute capacity twelve months ahead of production cycles. Taiwan, South Korea, and the United States anchor GPU and advanced semiconductor supply, while China concentrates rare earth processing for display components. The supply chain draws from lithium-ion battery cells for mobile capture equipment and optical sensors for cinema-grade cameras. Single-source vulnerability around TSMC's 3nm fabrication exposes generative video tool vendors to allocation rationing. Distribution runs through hyperscaler cloud marketplaces and direct platform API integrations rather than traditional media supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative adversarial networks for automated B-roll insertion are disrupting established post-production economics, compressing timelines from hours to minutes and rendering traditional editor staffing models obsolete. This technological inflection creates asymmetric opportunity for operators with captive AI infrastructure against legacy studios dependent on human labor.
For Market Incumbents: Compound algorithmic recommendation advantages by deepening proprietary behavioral data infrastructure that emerging entrants cannot replicate. Prioritize backward integration into GPU allocation agreements with NVIDIA to secure inference capacity ahead of supply-constrained competitors. Defensive moves must address substitution pressure from interactive learning platforms delivering comparable knowledge payloads without video production overhead. For New Entrants and Emerging Players: Differentiate on localized AI-assisted editing platforms for Indonesia and Vietnam, where template-driven production suites face minimal incumbent penetration. Target India's tier-2 and tier-3 cities with regional language content creation tools that unlock student and professional segments constrained by English-medium defaults. Go-to-market should leverage direct platform buying tools that disintermediate media agency relationships in North American consumer packaged goods verticals. For Investors and Strategic Acquirers: EU AI Act algorithmic audit requirements reshape the acquisition landscape toward platforms with documented recommendation logic and technical documentation trails. Long-term viability favors operators with compliance infrastructure spanning multiple jurisdictions rather than single-market pure-plays. Target acquisition archetypes include mid-sized studios in South Korea and Brazil with demonstrated AI-assisted editing adoption compressing per-asset labor hours. Watch for FDA guidance expansion on health-related content claims as signal for health-tech content platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | WeChat's super-app infrastructure demonstrates how short video blurs distribution boundaries for Tencent Holdings. |
| Geographic Expansion | ByteDance leverages Douyin's lower-tier city penetration to replicate live-streaming commerce models in Southeast Asian markets. |
| Acquisition of Specialist Firm | Computer vision ventures in Seoul's Gangnam district compress post-production timelines through automated scene segmentation. |
| Product Launch | Self-serve media buying tools disintermediate agencies in North American consumer packaged goods procurement. |
| Strategic Partnership | Cloud marketplace distribution agreements with hyperscalers secure GPU allocation for generative video inference workloads. |
Research Methodology
The analysis maps educational content certification, tutorial format production, promotional brand inventory, and entertainment narrative formats, each validated through platform engineering directors, creator studio heads, brand procurement officers, and regulatory compliance leads. Primary interviews with these stakeholders combined with secondary validation from SEC filings of listed platform operators, EU AI Act implementation guidance, India's IT Rules 2021 compliance disclosures, and China's SAMR antitrust enforcement records. Bottom-up content volume estimates triangulated against top-down advertising expenditure data across the projection horizon.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures for GPU infrastructure, platform-reported creator monetization metrics, and regional advertising technology investment flows. Segmentation dimensions modeled include content type, distribution channel, target audience archetype, and production quality tier alongside regional regulatory framework clusters. CAGRs derived from fitted growth curves incorporating mobile-first internet penetration trajectories, regional language content creation velocity, and live-streaming commerce conversion rate benchmarks. Forecast inputs include algorithmic recommendation engine deployment cycles and creator economy talent pool rotation timelines.
Material uncertainties — regulatory enforcement intensity variations across EU AI Act, India's IT Rules, and China's SAMR provisions — sit outside the modeled envelope. Forecasts reflect assumptions regarding GPU supply normalization, network infrastructure reliability in emerging market mobile environments, and cross-border content moderation harmonization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Digital Music Content Market
Digital Media
India Webtoons Market
Digital Media
Webcomics Market
Digital Media
Playout Solutions Market
Digital Media
Animation Services Market
Digital Media
Asia Pacific Photography Service Market
Digital Media
United States Sports Betting Market
Digital Media
VFX Market
Digital Media
Sound Effects Services Market
Digital Media
Online Art Market
Digital Media
Stock Photography Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Global Location-Based Entertainment Market
Digital Media
APAC Animation, VFX and Post Production Market
Digital Media
Africa Animation Market
Digital Media
Social TV Market