
 Europe Anime Merchandising Market | 2026-2036
Europe Anime Merchandising Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Anime Merchandising Market Insights
The buyer base for anime merchandise across Europe is broadening beyond traditional collectors toward casual fans and gift purchasers entering through streaming-driven discovery. Bandai Namco Entertainment Co., Ltd. leverages its vertical integration across animation production and toy manufacturing to control supply timelines for premium figure lines. Good Smile Company, Inc. sustains its competitive edge through intensive R&D in poseable joint engineering and limited-edition sculpting techniques. Kotobukiya Co., Ltd. specializes in high-detail scale statues targeting adult collectors with disposable income across Western European markets.
Anime merchandising encompasses the commercial production and distribution of licensed consumer goods derived from Japanese animation intellectual property, spanning PVC and ABS injection-molded figures, screen-printed textiles, and die-cast metal accessories. The manufacturing pipeline typically involves licensor approval cycles, prototype sculpting, and mass production through contracted facilities in East Asia before EU importation. Figures and limited-edition collectibles command the deepest margin pools due to scarcity engineering and premium positioning, while online retail channels capture the fastest volume growth through direct-to-consumer platforms and subscription box services. Apparel and accessories maintain steadier demand curves among casual fans who prioritize wearable brand expression over display-oriented collecting.
REACH regulation through ECHA governs chemical composition thresholds in imported PVC and painted resin goods, compelling distributors to maintain detailed substance documentation for customs clearance across EU member states. The EU's General Product Safety Directive mandates traceable supply chains for toys and collectibles marketed toward younger demographics, affecting labeling and age-grading requirements. CE marking obligations apply to electronic-integrated merchandise such as light-up displays and Bluetooth-enabled figures. Stakeholders must monitor evolving CSRD disclosure requirements that will extend sustainability reporting obligations through licensed supply networks into East Asian manufacturing partners.
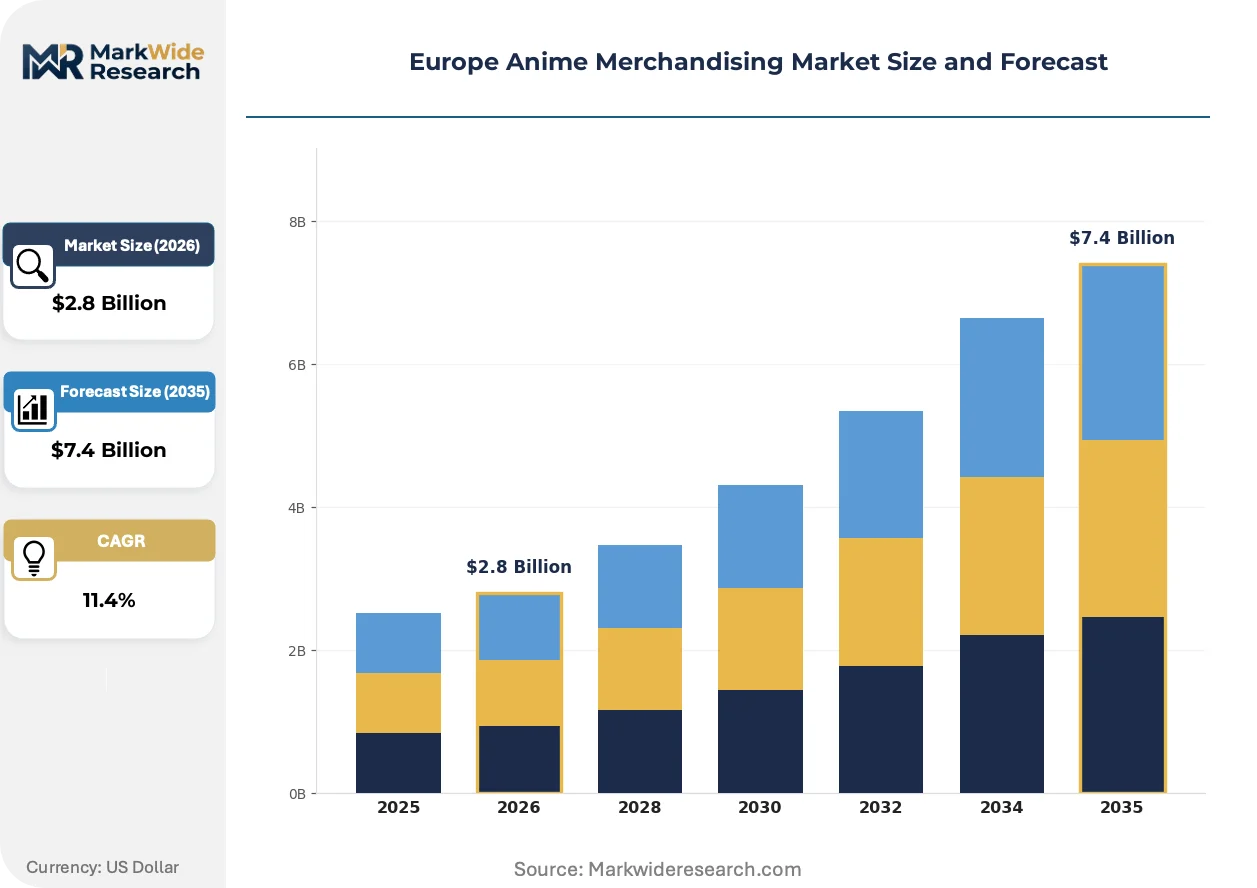
Market Dynamics
Streaming platform penetration across France, Germany, and the United Kingdom is converting passive viewers into merchandise-active collectors, restructuring demand generation away from traditional fan club channels toward algorithm-driven discovery.
Growth Catalysts
- REACH compliance standardization:ECHA-mandated chemical documentation for PVC and resin imports is filtering out non-compliant suppliers, consolidating shelf space for certified distributors across EU member states.
- Convention circuit expansion:Dedicated anime events in Paris, Berlin, and London concentrate purchasing velocity and create scarcity-driven release windows for limited-edition collectibles.
- ABS injection-molded engineering advances:Improved poseable joint tolerances in scale figures are broadening appeal from static-display collectors to interactive hobbyists seeking articulation.
Market Restraints
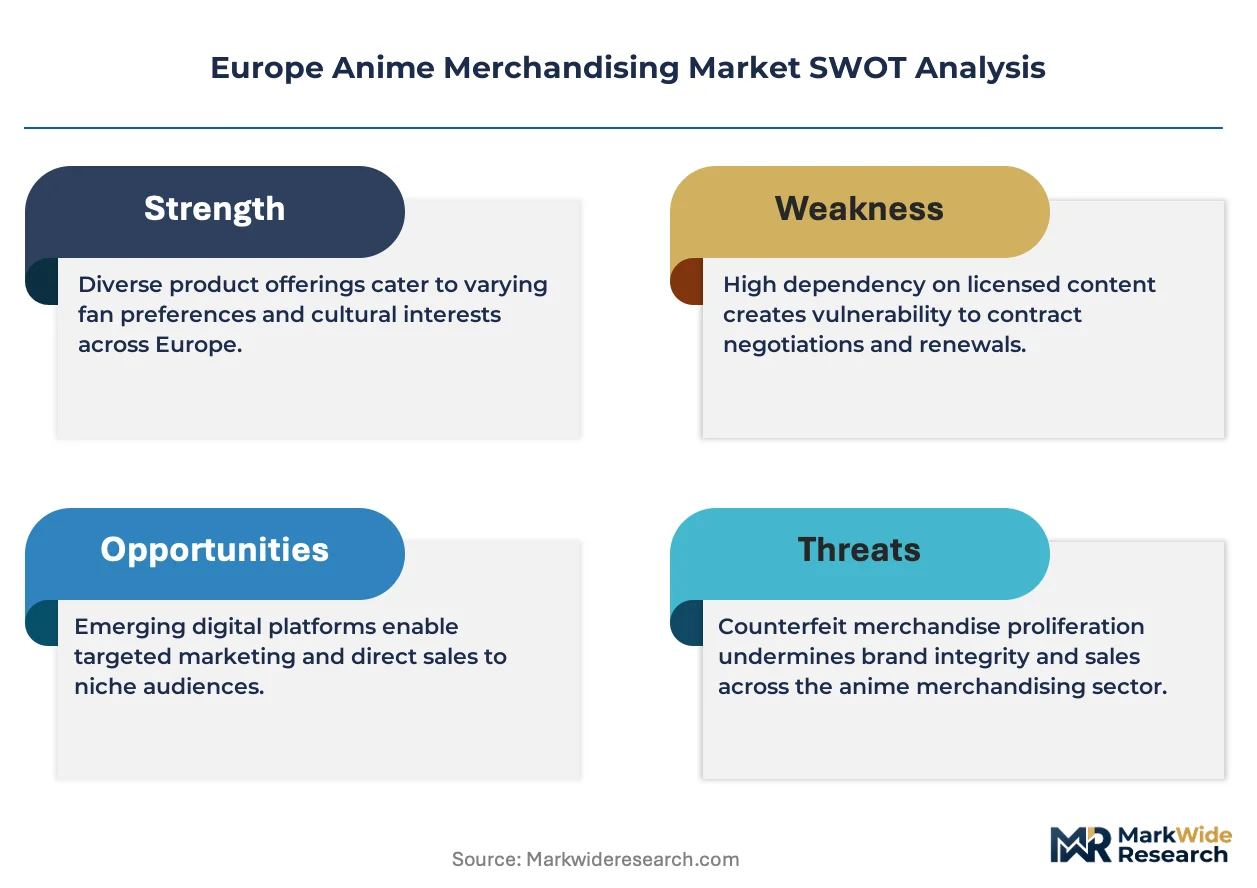
- East Asian production concentration:Over 85 percent of PVC figure manufacturing concentrates in contracted Guangdong and Zhejiang facilities, exposing EU importers to shipping disruption and currency fluctuation.
- REACH substance documentation burden:ECHA requires granular chemical composition records for painted resin goods, extending customs clearance timelines and elevating administrative overhead for distributors.
- Digital substitute encroachment:NFT-based collectibles and virtual display environments compete for discretionary spending among digitally-native demographics entering through streaming platforms.
Strategic Opportunities
- Spain and Italy market underpenetration:Madrid, Barcelona, Milan, and Rome exhibit rising anime viewership metrics but lack dedicated specialty retail infrastructure comparable to Paris or Berlin.
- CSRD supply chain disclosure requirements:The EU's Corporate Sustainability Reporting Directive creates competitive differentiation for distributors with traceable East Asian manufacturing partnerships and carbon-accounted logistics.
- Subscription box channel innovation:Curated monthly figure deliveries bypass conventional retail markups while capturing recurring revenue from collectors seeking discovery without convention attendance.
Industry Challenges
- Master sculptor talent scarcity:Limited-edition figure production depends on specialized artisans capable of translating 2D animation reference into precise 3D prototypes, with training pipelines failing to match demand expansion.
- Licensing approval cycle compression:Japanese licensors maintain multi-month prototype review protocols that conflict with European convention release calendars and seasonal purchasing peaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Anime Merchandising Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Figures, Apparel, Accessories, Home Décor Distribution Channel: Online Retail, Specialty Stores, Conventions, Mass Retailers Customer Type: Collectors, Casual Fans, Cosplayers, Gift Buyers Licensing Model: Official Merchandise, Third-Party Products, Limited Editions, Fan-Created Items |
| Companies Covered | Good Smile Company, Inc., Bandai Namco Entertainment Co., Ltd., Crunchyroll, Kotobukiya Co., Ltd., Max Factory, Inc., Anime Limited, Toei Animation Co., Ltd., Studio Ghibli, Inc., MegaHouse, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Anime Merchandising Market Trends and Innovations
Merchandise production and distribution across Europe is absorbing three concurrent pressures: material compliance escalation, digital-native buyer expectation, and supply chain transparency mandate. These forces are compressing traditional release cycles while elevating quality thresholds.
Photopolymer resin formulations with reduced volatile organic compound emissions are absorbing REACH-mandated reformulation requirements without sacrificing surface detail fidelity. German and French distributors are adopting these materials fastest, driven by domestic environmental enforcement intensity. The technology is absorbing compliance cost increases that would otherwise compress margin structures on mid-tier figure lines.
ECHA's 2023 expansion of SVHC candidate list screening obligations is compelling distributors to maintain substance documentation across entire PVC supply chains. The regulation is forcing inventory holding pattern adjustments as customs authorities extend inspection protocols for painted collectibles. Premium figure importers in the United Kingdom and Netherlands are responding by consolidating supplier relationships to reduce documentation multiplicity.
Collector purchasing is fragmenting across direct-to-consumer web storefronts, convention floor exclusives, and subscription-curated discovery channels. Traditional brick-and-mortar anime specialty retailers in Paris and Berlin are losing traffic to Bandai Namco and Good Smile Company-owned e-commerce portals with faster restock cycles. This behavioral shift is most visible among 18-29 year old demographics entering the hobby through Netflix and Crunchyroll streaming subscriptions.
Europe Anime Merchandising Market Segmentation
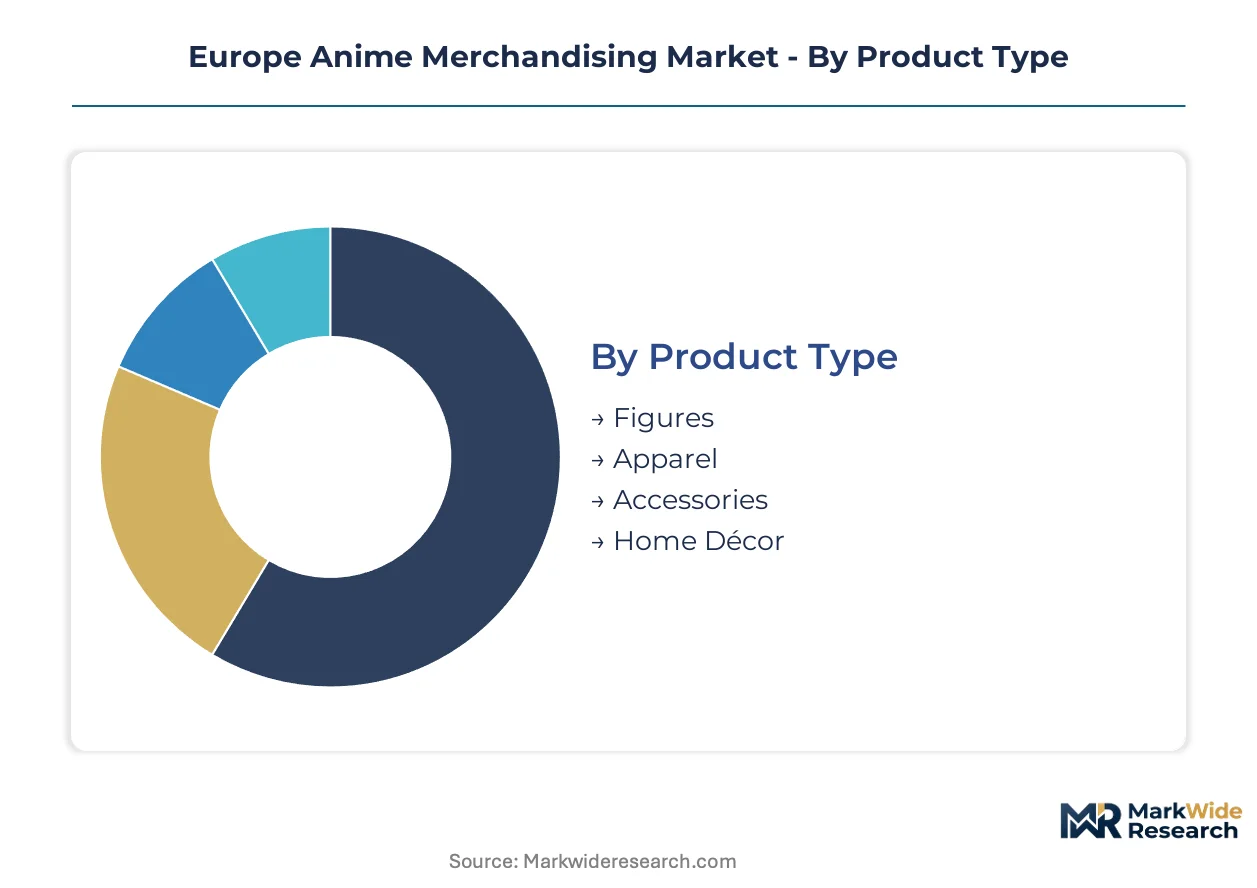
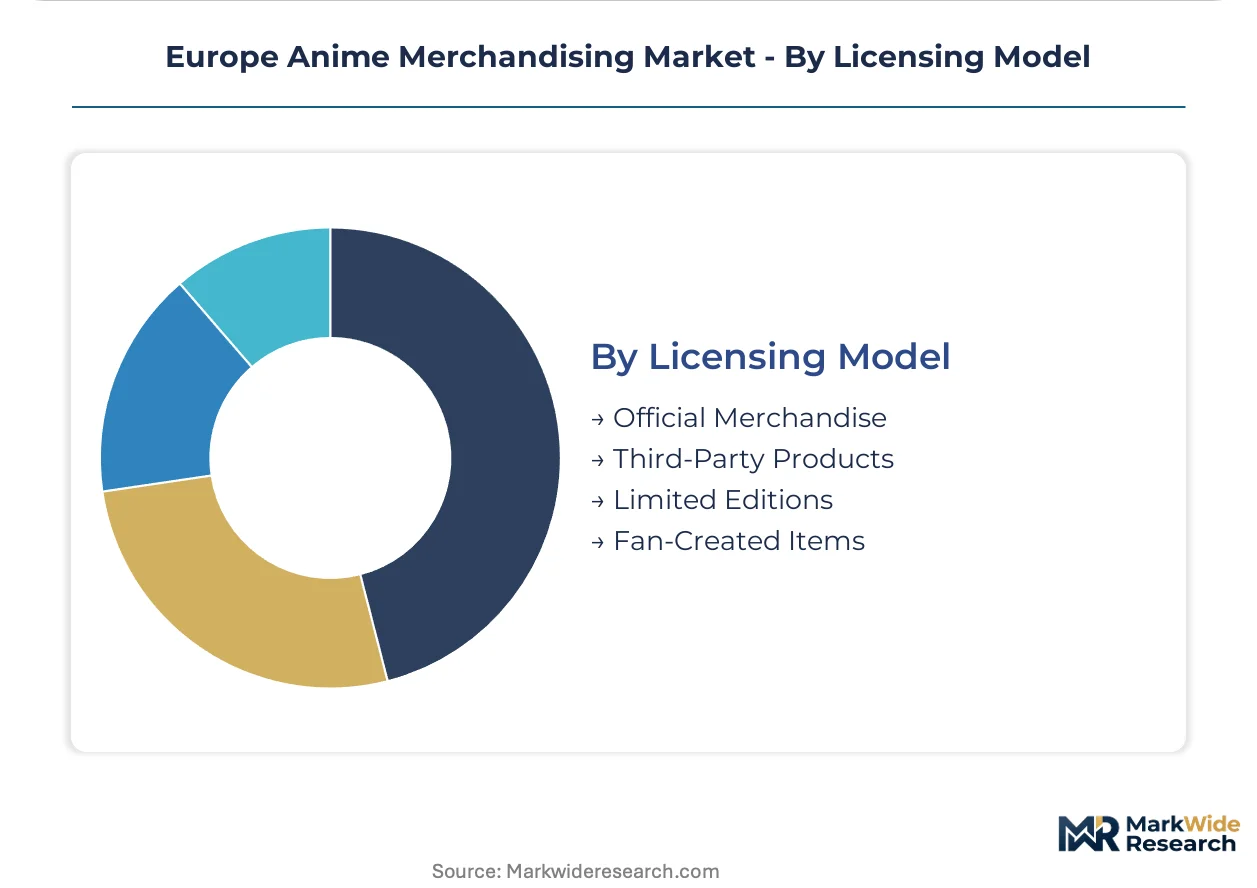
Europe's anime merchandising market fragments across four distinct dimensions that govern margin capture and channel strategy. Product type determines manufacturing complexity and REACH compliance burden. Distribution channel shapes customer acquisition cost and inventory velocity. Customer type calibrates pricing tolerance and purchase frequency. Licensing model controls scarcity engineering and legal risk exposure.
Product Type:
Customization intensity varies sharply across this category, from mass-produced apparel to individually sculpted collector pieces requiring artisan labor.
- Figures:PVC and ABS injection-molded collectibles with poseable joints or fixed poses command premium positioning through limited production runs. France, Germany, and the United Kingdom concentrate demand for scale statues targeting adult collectors with substantial disposable income.
- Apparel:Screen-printed textiles and embroidered garments carry lower per-unit margins but achieve faster inventory turns through seasonal collection drops. Casual fans across Paris and Berlin drive volume through wearable brand expression rather than display-oriented collecting.
- Accessories:Die-cast metal jewelry, enamel pins, and phone cases occupy mid-tier price positioning with broad demographic appeal.
- Home Décor:Wall scrolls, LED displays, and themed furnishings extend merchandise presence into living spaces.
Leading the category by volume: Apparel. Expanding most quickly: Figures.
Distribution Channel:
Channel selection directly determines margin retention and customer relationship depth, with owned platforms capturing data advantages over third-party intermediaries.
- Online Retail:Direct-to-consumer web portals and marketplace storefronts eliminate retail markups while enabling global inventory access. Subscription box services embedded within this channel capture recurring revenue from collectors seeking discovery without convention travel.
- Specialty Stores:Dedicated anime retailers in Paris, Berlin, and London provide tactile inspection opportunities and community gathering functions that digital channels cannot replicate.
- Conventions:Event-based sales concentrate purchasing velocity through scarcity-driven release windows and exclusive variant offerings.
- Mass Retailers:General merchandise chains extend reach toward gift buyers and casual fans with lower category awareness.
Capturing the deepest margins: Online Retail. Gaining share fastest: Conventions.
Customer Type:
Behavioral segmentation separates display-oriented collectors from experiential participants and transactional purchasers with divergent loyalty profiles.
- Collectors:Dedicated hobbyists pursuing completionist acquisition of specific intellectual property lines, with substantial tolerance for pre-order timelines and premium pricing.
- Casual Fans:Streaming-driven entrants prioritizing impulse purchases and lower-commitment price points, often making single-item buys tied to current viewing habits.
- Cosplayers:Costume construction enthusiasts requiring specialized materials, wigs, and prop components with accuracy demands exceeding standard merchandise specifications.
- Gift Buyers:Transactors purchasing for others with limited category knowledge, favoring recognizable characters and safe price points.
Highest lifetime value concentration: Collectors. Broadening fastest: Casual Fans.
Licensing Model:
Legal provenance tiers create quality signaling and enforcement risk gradients that distributors must navigate across EU member states.
- Official Merchandise:Licensor-authorized production with verified supply chain documentation satisfies ECHA substance reporting requirements and CE marking obligations for electronic-integrated goods.
- Third-Party Products:Non-exclusive licensed manufacturing occupies mid-market positioning with reduced scarcity value but broader availability.
- Limited Editions:Numerically capped production runs with certificate authentication command auction-market premiums in secondary trading.
- Fan-Created Items:Unlicensed derivative works operate in legal gray zones with elevated customs seizure risk at EU entry points.
Dominating shelf space: Official Merchandise. Steepest expansion trajectory: Limited Editions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France, Germany, and the United Kingdom concentrate purchasing velocity for premium anime collectibles, with specialty retail infrastructure and convention circuits generating disproportionate sales density relative to regional population.
France
Paris hosts the densest specialty retail cluster in continental Europe, with dedicated anime boutiques in the 11th and 13th arrondissements serving collectors from across the Île-de-France region. ANSM enforces strict labeling requirements for PVC imports marketed toward minors, compelling distributors to maintain French-language safety documentation. Japan Expo in Paris-Nord Villepinte anchors the European convention calendar, with exclusive figure releases driving pre-order volumes that exceed standard retail channels.
Germany
Berlin and Munich sustain the highest per-capita spending on scale statues among EU member states, with adult collectors driving demand for high-detail resin pieces. KBA-aligned product safety standards for imported toys extend clearance timelines at Hamburg and Bremerhaven ports. The Frankfurt Book Fair's anime pavilion has emerged as a secondary distribution node, connecting German distributors directly with Japanese licensors for limited-edition allocation rights.
United Kingdom
London's Camden and Soho districts retain the UK's deepest concentration of physical anime retail, though online channels now capture the majority of transaction volume. Trading Standards enforcement of the General Product Safety Regulations creates compliance friction for independent importers without dedicated regulatory staff. MCM Comic Con and Hyper Japan concentrate quarterly purchasing spikes, with exclusive variant figures commanding secondary market premiums within hours of floor release.
Italy
Milan and Rome exhibit accelerating anime viewership metrics through Netflix and Crunchyroll penetration, yet lack dedicated specialty retail infrastructure comparable to Paris or Berlin. REACH substance documentation requirements filter through Italian customs at Milan Malpensa and Rome Fiumicino, extending lead times for PVC figure shipments. Lucca Comics & Games has emerged as the southern European convention anchor, with 2024 attendance figures suggesting underserved merchandise capacity relative to visitor density.
Spain
Madrid and Barcelona demonstrate the fastest-growing streaming-driven fan conversion rates in Western Europe, with younger demographics entering the hobby through subscription platforms rather than traditional fan clubs. Spanish customs authorities apply heightened scrutiny to painted resin imports under EU-wide SVHC screening protocols. Salón del Manga de Barcelona provides the peninsula's primary scarcity-driven release window, though distributor booth allocation remains constrained relative to French and German events.
Europe Anime Merchandising Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue streaming-integrated direct-to-consumer channels and subscription-curated discovery models. The vendor base stratifies across three functional tiers: integrated licensors with captive animation studios, specialized figure fabricators with proprietary sculpting pipelines, and platform-native distributors leveraging algorithmic recommendation engines. Competitive positioning hinges on licensing exclusivity windows, supply chain documentation completeness for REACH compliance, and convention floor presence density. Primary competitive moves include vertical integration into animation production, strategic consolidation of East Asian manufacturing partnerships, and direct-to-consumer platform development.
Within the integrated licensor-manufacturer tier, Bandai Namco Entertainment Co., Ltd. and Toei Animation Co., Ltd. occupy positions defined by captive intellectual property pipelines and controlled distribution timelines. Among specialized figure fabricators, Good Smile Company, Inc., Kotobukiya Co., Ltd., and Max Factory, Inc. exemplify engineering-led differentiation through poseable joint tolerances and limited-edition sculpting techniques. These entities represent the competitive core around which European distribution strategies must align, as their production allocation decisions determine shelf availability across Paris, Berlin, and London retail nodes.
| Leading Market Players |
|---|
| Good Smile Company, Inc. |
| Bandai Namco Entertainment Co., Ltd. |
| Crunchyroll |
| Kotobukiya Co., Ltd. |
| Max Factory, Inc. |
| Anime Limited |
| Toei Animation Co., Ltd. |
| Studio Ghibli, Inc. |
| MegaHouse |
| Others |
Pricing and Supply Chain Analysis
Photopolymer resin formulations absorb REACH-mandated compliance costs as they flow through Guangdong injection-molding facilities into premium figure pricing tiers across Paris and Berlin retail nodes.
Pricing Analysis
Volume concentrates in apparel through fast-fashion drops while margins pool in limited-edition resin statues. Price differentiation hinges on scarcity engineering and ECHA documentation completeness. Pricing pressure stems from master sculptor talent scarcity extending pre-order timelines. Casual fans entering via streaming platforms exhibit highest price sensitivity; completionist collectors demonstrate lowest.
Supply Chain Analysis
Reverse logistics for defective PVC figures flows through distributor consolidation points in Rotterdam and Hamburg before East Asian refurbishment. Manufacturing concentrates in China, Japan, and South Korea. Raw material dependencies span petroleum-derived PVC, ABS pellets, and photopolymer resins. Single-source vulnerability concentrates in Guangdong and Zhejiang molding facilities. Distribution runs through direct-to-consumer web portals, convention floor exclusives, and subscription-curated channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance documentation functions as a cost-of-compliance moat, with ECHA substance reporting requirements filtering out undercapitalized competitors from EU market entry.
For Market Incumbents: Cement allocation rights with Japanese licensors through early prototype pipeline investment. Deepen captive supply relationships with certified Guangdong facilities to preempt competitor access. Digital substitute encroachment from NFT collectibles demands defensive direct-to-consumer platform development.
For New Entrants and Emerging Players: Enter via Spain and Italy's underpenetrated specialty retail infrastructure where streaming-driven fan conversion outpaces dedicated merchandise supply. Target Madrid and Barcelona's 18-29 demographic through subscription box discovery channels bypassing convention travel requirements.
For Investors and Strategic Acquirers: CSRD disclosure readiness among East Asian manufacturing partners is the leading indicator that sustainability-linked capital will flow toward traceable supply chain operators. Five-to-ten year viability favors distributors with carbon-accounted logistics and documented substance chains. Monitor ECHA SVHC list expansions for compliance cost inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Documentation Consolidation | ECHA compliance completeness unlocks shelf space across ANSM and KBA enforcement jurisdictions. |
| Direct-to-Consumer Platform Launch | Owned e-commerce portals capture data advantages over Paris and Berlin brick-and-mortar intermediaries. |
| Subscription Box Channel Development | Curated monthly deliveries convert streaming-driven casual fans into recurring revenue collectors. |
| East Asian Manufacturing Partnership Certification | CSRD-ready supply chains attract sustainability-mandated institutional capital allocations. |
| Convention Floor Exclusivity Negotiation | Scarcity-driven release windows at Japan Expo and MCM Comic Con generate secondary market premiums. |
Research Methodology
Independent corroboration across distributor procurement leads, convention organizer sales data, and licensor allocation managers underwrites the qualitative findings. Primary fieldwork engaged specialty retail buyers in Paris and Berlin, customs clearance specialists at Rotterdam and Hamburg, and streaming platform merchandise partnership directors. Secondary validation drew from ECHA substance database filings, EU customs import records, and SEC disclosures from publicly traded animation studios. Bottom-up volume estimates triangulate against top-down market sizing across product type and distribution channel dimensions.
Comparable-period anchoring calibrated the projection horizon against historical convention attendance trajectories and streaming subscriber conversion metrics. The analytical framework models figures, apparel, accessories, and home décor segments across online retail, specialty stores, conventions, and mass merchant channels. CAGRs derive from trend extrapolation adjusted for regulatory compliance cost absorption rates and master sculptor pipeline constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA SVHC list acceleration or East Asian shipping disruption scenarios. Practitioners should monitor streaming platform merchandise partnership announcements and CSRD disclosure adoption curves among East Asian suppliers for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Drone Wedding Photography Market
Digital Media
Entertainment Transcription Market
Digital Media
North America Photographic Services Market
Digital Media
Digital Effects Services Market
Digital Media
Social TV Market
Digital Media
Middle East Gaming Market
Digital Media
Europe Online Gambling Market
Digital Media
Sports Graphics Market
Digital Media
South Korea Webtoons Market
Digital Media
Europe Online Video Platform Market
Digital Media
Visual Effects (VFX) Market
Digital Media
Secondary Ticket Market
Digital Media
APAC DOOH Market
Digital Media
Entertainment Market
Digital Media
Global Music Video Production Market
Digital Media
Europe Professional Audio Video (Proav) Market