
 Digital Audio Workstation (DAW) Market | 2026-2036
Digital Audio Workstation (DAW) Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Audio Workstation (DAW) Market Intelligence
German audio engineering heritage is repositioning European DAW development toward professional-grade mixing environments. Ableton leverages its Berlin-rooted electronic music ecosystem to dominate live performance workflows. Avid Technology sustains Hollywood post-production loyalty through Pro Tools HDX hardware integration. Native Instruments anchors Berlin's virtual instrument sector with deep sample library ecosystems.
A digital audio workstation constitutes software, hardware, or hybrid systems enabling multi-track recording, MIDI sequencing, non-linear editing, and real-time signal processing at latencies below 10 milliseconds for professional monitoring. These platforms serve music production, film scoring, broadcast, and interactive media creation through integrated virtual instruments and automation engines. Software DAW captures the broadest user base through subscription pricing and cross-platform compatibility, while hardware DAW retains premium positioning in broadcast stations requiring dedicated DSP acceleration. Cloud-based DAW represents the fastest-expanding architecture as latency-tolerant collaboration tools attract distributed production teams across indie artist segments.
FCC equipment authorization governs hardware DAW interfaces sold in the United States, while CE marking under EU Radio Equipment Directive shapes European import compliance for audio interfaces with wireless connectivity. Germany's KBA has no direct DAW jurisdiction, though German Federal Network Agency (BNetzA) EMC standards influence hardware certification cycles for studio equipment manufacturers. Stakeholders must monitor how EU AI Act transparency requirements will apply to generative composition plugins integrated into European-developed DAW platforms.
Market Dynamics
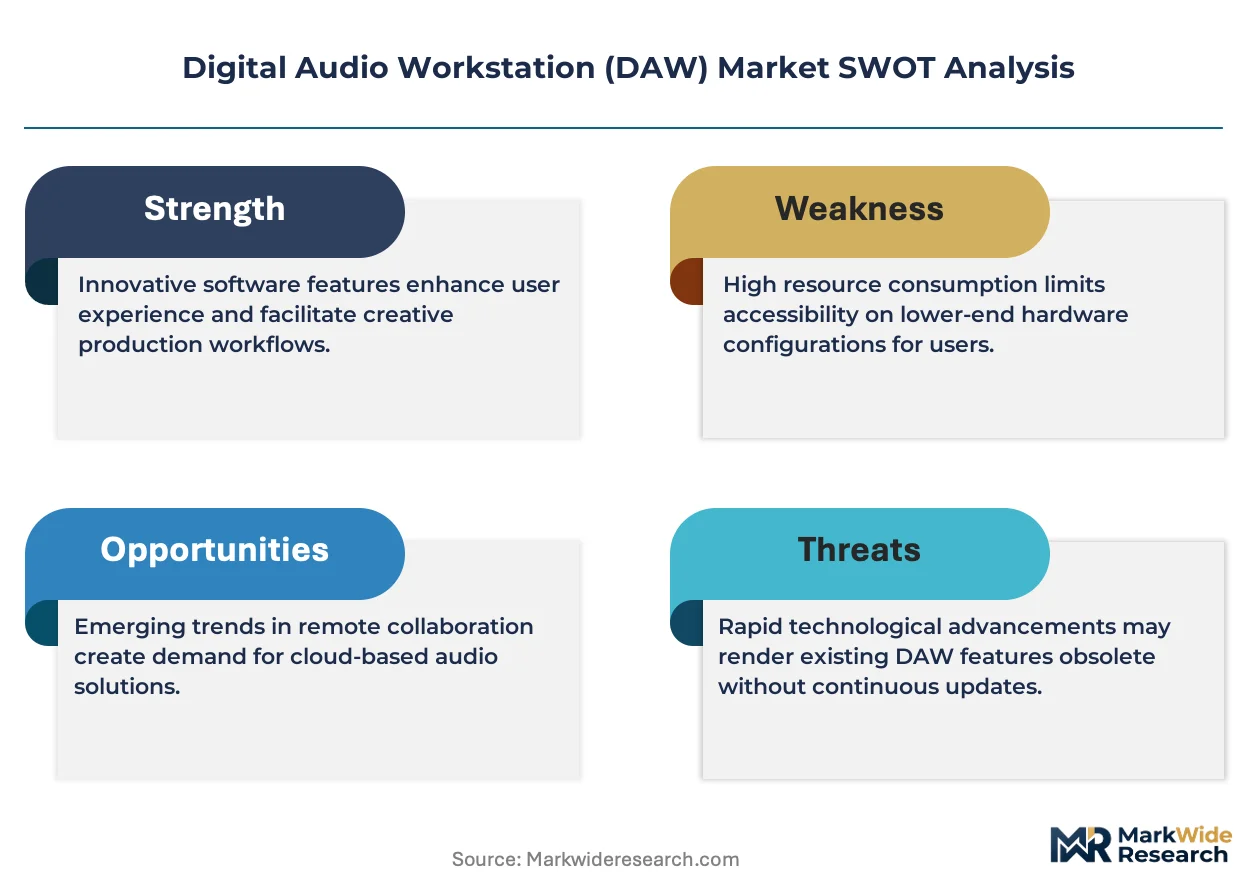
Cloud-native architectures and AI-assisted mastering tools are compressing production timelines and redistributing competitive advantage toward developers with machine-learning pipelines and low-latency infrastructure.
Growth Catalysts
- EU AI Act transparency mandates:Generative composition plugins face new disclosure requirements that favor established European developers with compliance infrastructure already in place.
- Bedroom producer segment expansion:Independent musicians in the United States and Germany drive subscription-based software DAW adoption through affordable monthly pricing tiers.
- Live performance workflow integration:Electronic music ecosystems in Berlin and Los Angeles demand seamless hardware-software hybrid environments for real-time stage use.
Market Restraints
- DSP chip supply concentration:Hardware DAW manufacturers depend on Taiwanese foundry capacity for dedicated acceleration cards, creating vulnerability to geopolitical disruption.
- FCC equipment authorization timelines:Hardware DAW interfaces with wireless connectivity face extended certification cycles that delay product launches in the United States market.
- Latency floor in browser-based architectures:Cloud DAW platforms cannot achieve sub-10 millisecond monitoring required for professional tracking sessions, limiting high-end displacement.
Strategic Opportunities
- South Korea content creator economy:K-pop production houses and independent streamers represent underpenetrated demand for collaborative cloud DAW tools with Korean-language localization.
- Film scoring workflow convergence:Integration between MIDI sequencing and immersive audio formats creates white space for DAW platforms serving Los Angeles and London post-production facilities.
- CE marking under EU Radio Equipment Directive:Streamlined compliance pathways for audio interfaces with Bluetooth connectivity reduce European market entry friction relative to FCC processes.
Industry Challenges
- Audio engineering talent scarcity:Mixing and mastering expertise concentrates in legacy studio environments, creating recruitment bottlenecks for software vendors building automated alternatives.
- Legacy hardware integration complexity:Professional users maintain substantial investments in Pro Tools HDX and comparable DSP systems that resist full cloud migration.
- Generative training data licensing:AI-assisted composition tools face unresolved disputes over sample library rights and derivative work classification across German and United States jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Audio Workstation (DAW) Market |
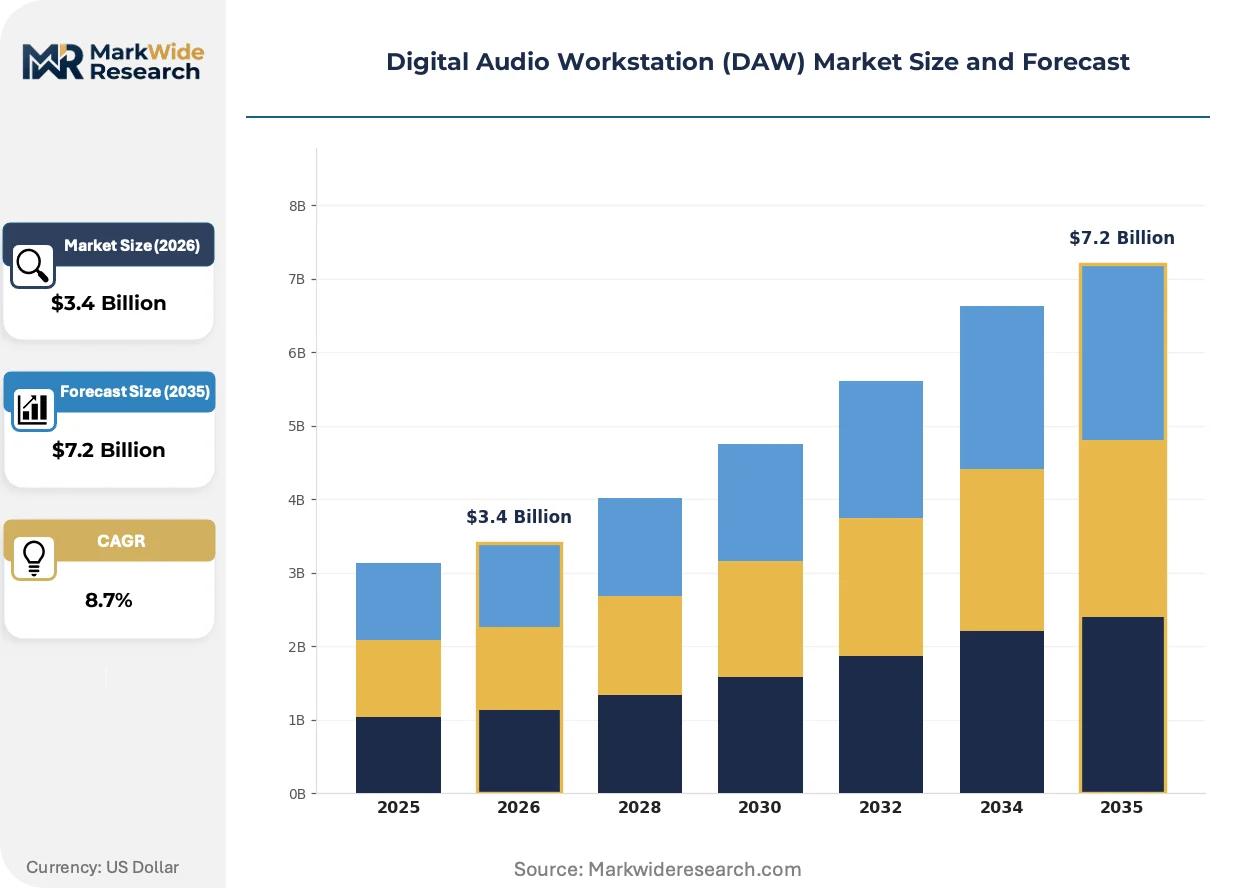
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software DAW, Hardware DAW, Hybrid DAW, Cloud-based DAW Technology: MIDI Sequencing, Audio Recording, Mixing, Virtual Instruments, Sound Editing Application: Music Production, Film Scoring, Podcasting, Live Sound Engineering, Game Audio Design End User: Music Producers, Sound Engineers, Composers, Broadcast Stations, Indie Artists |
| Companies Covered | Ableton, PreSonus Audio Electronics, Avid Technology, Image-Line, Native Instruments, Apple, Adobe, Cockos, Steinberg Media Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Audio Workstation (DAW) Market Strategic Shifts & Innovations
Real-time collaboration infrastructure and machine-learning signal processing are redrawing how production teams assemble, iterate, and finalize audio projects across distributed geographic locations.
Neural audio processing is absorbing conventional equalization and dynamics workflows into automated mastering chains. Bedroom producers and mid-tier project studios adopt these tools at accelerating velocity. The technology is absorbing hours of manual adjustment into seconds of algorithmic processing, compressing the value of traditional engineering expertise while expanding addressable user bases.
CE marking requirements under the EU Radio Equipment Directive now explicitly cover audio interfaces with wireless connectivity. German manufacturers face extended EMC validation cycles that delay product launches by four to six months relative to wired-only counterparts. Studio equipment vendors with Berlin and Hamburg headquarters are restructuring hardware roadmaps to front-load radio module certification.
Subscription fatigue among semi-professional users is fragmenting purchasing patterns across perpetual-license holdouts and tiered SaaS adopters. The indie artist segment in the United States and Germany increasingly unbundles advanced features, purchasing only specific plugin categories rather than full DAW suites. This behavioral shift pressures developers to modularize pricing architectures without cannibalizing premium-tier revenue.
Digital Audio Workstation (DAW) Market Segmentation
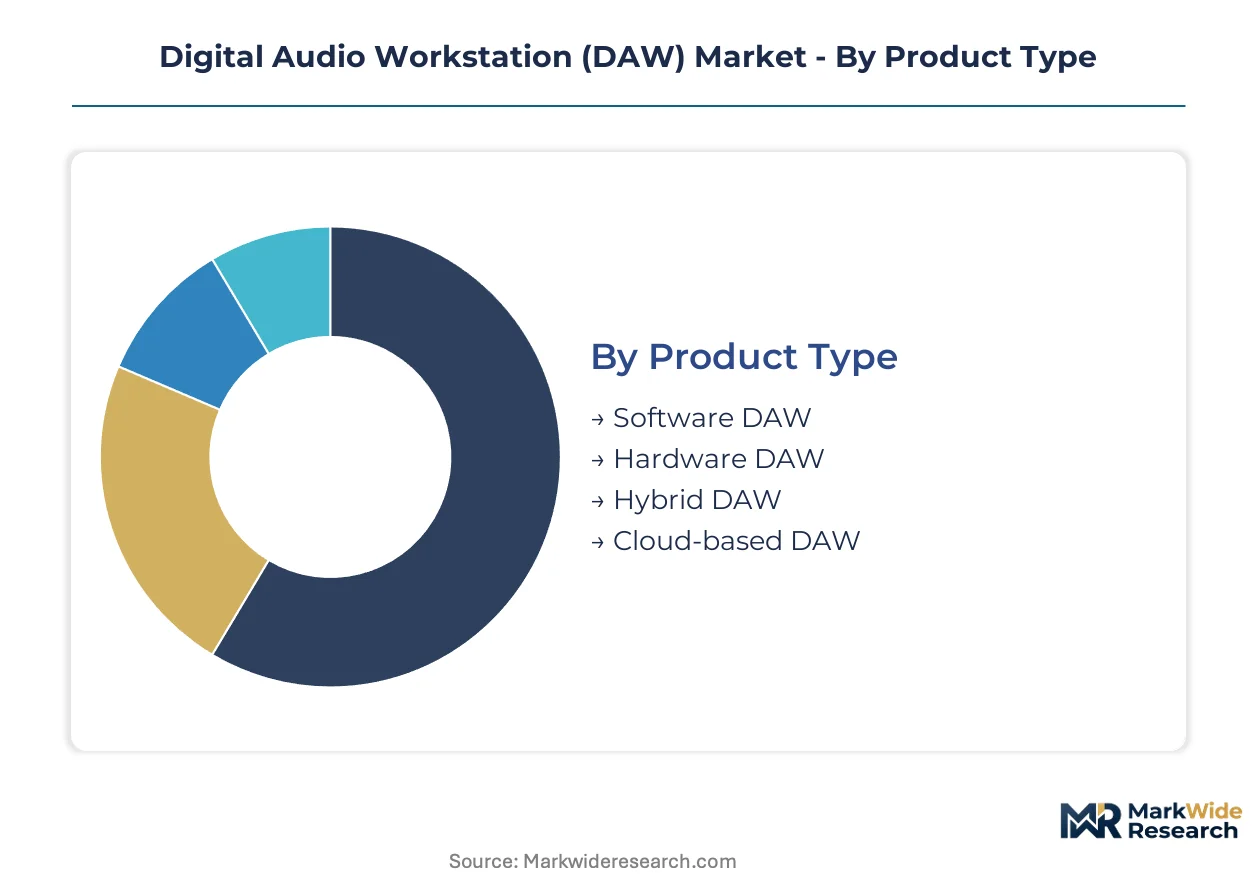
DAW purchasing decisions split across workflow permanence, technical performance floors, and collaboration requirements. Segmentation reveals how subscription software, dedicated hardware, and browser-native platforms serve divergent user archetypes with incompatible latency and mobility priorities.
Product Type:
Customization spans from fully configurable software stacks to fixed-function hardware appliances, with hybrid and cloud architectures occupying intermediate positions on the flexibility spectrum.
- Software DAW:Code-based platforms deploy across macOS, Windows, and Linux environments with plugin extensibility. Demand concentrates among indie artists in Germany and the United States seeking affordable monthly subscriptions without hardware lock-in.
- Hardware DAW:Dedicated DSP appliances with proprietary operating systems deliver sub-3-millisecond latency for tracking. Broadcast stations in Los Angeles and London maintain installed bases despite higher capital intensity.
- Hybrid DAW:Software cores paired with external DSP accelerators bridge latency requirements and upgrade flexibility. Post-production houses in London favor these configurations for immersive audio workflows.
- Cloud-based DAW:Browser-native architectures enable real-time collaboration across distributed teams. Expansion is steepest in South Korea's K-pop production ecosystem where remote session work has normalized.
Most installed capacity flows through Software DAW. Expansion is steepest in Cloud-based DAW.
Technology:
Cost tiers separate foundational recording layers from premium processing modules, with virtual instruments commanding disproportionate margin contribution relative to their deployment complexity.
- MIDI Sequencing:Digital note data manipulation with quantization, velocity curves, and automation lanes. Electronic music producers in Berlin rely on tight timing precision for live performance rigs.
- Audio Recording:Multi-track waveform capture with non-destructive editing and comping. Bedroom producers across the United States drive volume through USB interface bundles.
- Mixing:Signal routing, bussing, and summing with real-time plugin processing. Professional studios in Nashville and Stockholm maintain premium pricing power around analog-emulated console workflows.
- Virtual Instruments:Sample-based and synthesized sound generators with articulation mapping. Native Instruments and Vienna Symphonic Library anchor demand in German-speaking markets.
- Sound Editing:Destructive waveform manipulation for restoration and design. Film scoring facilities in Los Angeles integrate these tools with picture editorial departments.
Virtual Instruments capture the highest per-seat revenue. MIDI Sequencing maintains the broadest user penetration.
Application:
Customer maturity separates hobbyist entry points from professional revenue centers, with music production and film scoring representing opposite poles on the commercial sophistication spectrum.
- Music Production:Songwriting, arrangement, and release-ready mastering for commercial distribution. Independent musicians in Germany and the United States dominate subscription uptake.
- Film Scoring:Synchronized composition with picture lock, stem delivery, and immersive format support. Los Angeles and London facilities require Avid Pro Tools HDX integration for dub stage compatibility.
- Podcasting:Voice-centric recording with noise reduction, loudness normalization, and chapter marking. Solo creators across the United States favor Descript and Hindenburg for editorial speed.
- Live Sound Engineering:Real-time playback and processing for stage performance. Ableton Live anchors Berlin's electronic music circuit with clip-launching workflows.
- Game Audio Design:Interactive music systems, spatial audio implementation, and middleware integration. Sound designers in Tokyo and Montreal drive middleware-agnostic DAW adoption.
Music Production accounts for the largest seat count. Film Scoring commands the highest per-project spend.
End User:
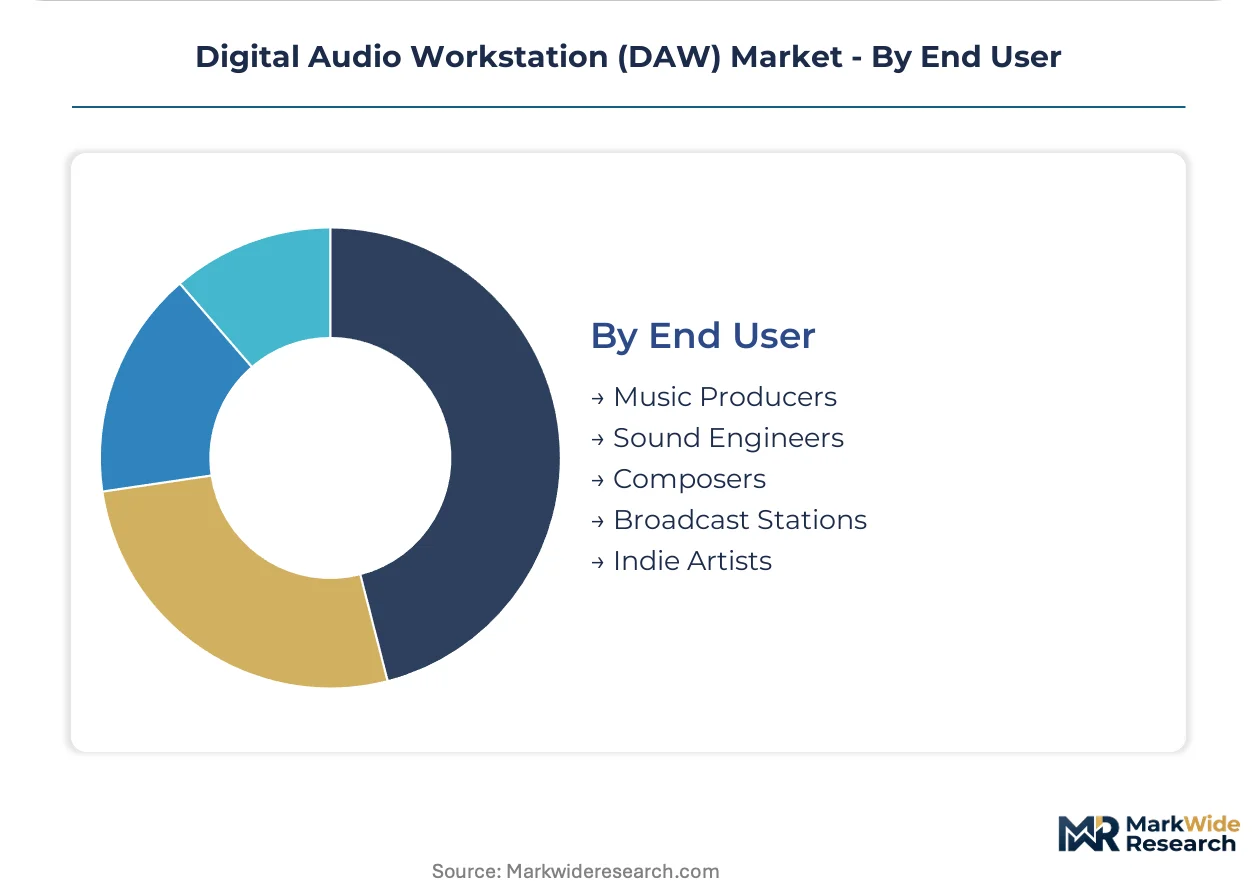
Volume concentration sits with individual creators, while margin extraction depends on institutional procurement cycles with extended support and training requirements.
- Music Producers:Multi-role creators handling composition, recording, and mixing. Beatmakers in Atlanta and Seoul favor FL Studio and Logic Pro for rapid loop-based workflows.
- Sound Engineers:Technical specialists focused on capture quality, signal flow optimization, and delivery standards. Mixing rooms in London and Stockholm maintain perpetual licenses for stability.
- Composers:Notation-integrated creators serving film, television, and game clients. Hans Zimmer's Remote Control Productions in Santa Monica drives large orchestral template demand.
- Broadcast Stations:Regulatory-compliant facilities with redundant systems and 24/7 support contracts. NPR affiliates across the United States standardize on Adobe Audition for editorial consistency.
- Indie Artists:Self-funded creators with budget constraints and DIY production requirements. Bandcamp-releasing musicians in Portland and Manchester gravitate toward Reaper and Studio One for cost efficiency.
Indie Artists represent the fastest-expanding user base. Broadcast Stations generate the most predictable recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's audio engineering heritage contrasts with South Korea's content creator economy, each driving distinct DAW adoption patterns. The United States maintains Hollywood post-production dominance while Japan and the United Kingdom anchor specialized workflow segments.
United States
Independent musicians and bedroom producers in Los Angeles, Nashville, and Atlanta drive subscription-based software DAW adoption through affordable monthly pricing tiers. FCC equipment authorization governs hardware DAW interfaces with wireless connectivity, creating extended certification timelines. Hollywood post-production facilities in Los Angeles sustain Avid Pro Tools HDX loyalty through hardware integration requirements for dub stage compatibility.
Germany
Berlin's electronic music ecosystem and Hamburg's studio equipment manufacturers anchor European professional-grade mixing environment development. CE marking under EU Radio Equipment Directive shapes compliance for audio interfaces with Bluetooth connectivity, with EMC validation extending hardware roadmaps by four to six months. Native Instruments and Ableton leverage deep sample library ecosystems and live performance workflows from Berlin headquarters.
South Korea
K-pop production houses and independent streamers in Seoul generate underpenetrated demand for collaborative cloud DAW tools with Korean-language localization. The country's national broadcasting regulator influences content production standards for streaming platforms. Seoul-based production teams have normalized remote session work, accelerating browser-native architecture expansion.
Japan
Game audio designers in Tokyo and sound designers serving interactive media drive middleware-agnostic DAW adoption for spatial audio implementation. METI industrial standards influence professional audio equipment certification cycles. Tokyo's concentration of game development studios creates specialized demand for interactive music systems integration.
United Kingdom
Post-production houses in London favor hybrid DAW configurations with external DSP accelerators for immersive audio workflows. The country's national media regulator shapes broadcast compliance requirements for redundant systems. London facilities maintain perpetual licenses for mixing room stability amid subscription fatigue fragmentation.
Digital Audio Workstation (DAW) Market Key Industry Players
Berlin-based producers anchor one tier; California specialists hold Hollywood-centric post-production integration. The vendor base concentrates around three strategic poles: live performance workflow innovators, professional-grade mixing environment developers, and cloud-native collaboration platform builders. Consolidation pressures emerge from AI-assisted mastering tool proliferation and latency-tolerant infrastructure investments. Dominant competitive moves include strategic partnerships with DSP hardware manufacturers and geographic expansion into South Korea's content creator economy.
Within the live performance workflow tier, Ableton exemplifies Berlin-rooted electronic music ecosystem dominance. Avid Technology occupies a position representing Hollywood post-production hardware-software integration requirements. Native Instruments anchors the virtual instrument and sample library specialization segment from German headquarters. These three entities represent distinct competitive archetypes: real-time stage environment innovators, broadcast-standard facility enablers, and deep sound design resource curators.
| Leading Market Players |
|---|
| Ableton |
| PreSonus Audio Electronics |
| Avid Technology |
| Image-Line |
| Native Instruments |
| Apple |
| Adobe |
| Cockos |
| Steinberg Media Technologies |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up specialists in the professional audio software sector have consolidated Berlin and Los Angeles development studios, tightening pricing discipline through subscription bundling while concentrating DSP hardware sourcing decisions in fewer procurement hands.
Pricing Analysis
Capacity additions in cloud-native DAW infrastructure are reshaping price floors for browser-based collaboration tiers. Three-tier pricing structure across premium, standard, and economy levels separates Hollywood post-production suites from bedroom producer subscriptions. Price differentiation rests on latency performance certification and plugin ecosystem depth. Pricing pressure stems from subscription fatigue among semi-professional users in Germany and the United States. Indie artists exhibit highest price sensitivity, while broadcast stations accept premium perpetual licenses for regulatory compliance.
Supply Chain Analysis
Domestic-content mandates in South Korea and emerging local-data-residency requirements in Germany are reshaping sourcing patterns for cloud DAW server infrastructure. Manufacturing concentrates in Taiwan for DSP acceleration chips, Germany for precision audio interfaces, and China for consumer-grade USB hardware. Component dependencies include analog-to-digital converters, FPGA processing modules, and rare-earth magnet transducers. Single-source vulnerability runs through Taiwanese foundry capacity for professional-grade DSP cards. Distribution runs through direct-to-creator digital storefronts and authorized reseller networks serving institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DAW market offers geographic-arbitrage value through South Korea's content creator economy, where regulatory standardization outpaces Western compliance costs while K-pop production demand accelerates faster than localized supply.
For Market Incumbents: Deepen vertical control over sample library licensing to deflect generative AI training data disputes. Anchor Berlin and Los Angeles development talent through equity participation. Cloud-native entrants threaten hardware-integrated revenue streams; counter through hybrid architecture R&D investment. For New Entrants and Emerging Players: Launch via freemium cloud collaboration tools targeting Seoul-based K-pop production houses. Korean-language localization and real-time session sharing represent the most penetrable white space. Partner with domestic streaming platforms for bundled distribution. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier plugin developers with established user bases but limited platform integration. Five-to-ten-year viability favors specialists with proprietary neural processing IP. Watch for inflection when EU AI Act enforcement clarifies generative composition disclosure requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pro Tools HDX compatibility secures Hollywood dub stage procurement decisions. |
| Geographic Expansion | Seoul office establishment captures K-pop remote collaboration workflow demand. |
| Acquisition of Specialist Firm | Neural mastering algorithm shops compress development timelines for SaaS tiers. |
| Strategic Partnership | DSP hardware manufacturers extend latency performance guarantees to cloud architectures. |
| Product Launch | Korean-language cloud DAW interfaces unlock underpenetrated content creator segments. |
Research Approach
Bottom-up bedroom producer and broadcast station modeling reconciled against top-down DSP hardware shipment tracking forms the analytical core. Primary interviews with DAW product managers, audio interface procurement leads, post-production facility technical directors, and indie artist workflow consultants combined with secondary validation from FCC equipment authorization filings, EU CE marking registries, SEC 10-K software revenue disclosures, and App Annie creative application download data. Triangulation between subscription revenue recognition patterns and hardware unit economics ensures segmentation integrity.
Input-output matrices map deployment model, end-user archetype, and regional adoption velocity against technology tier and application workflow. CAGRs derive from modeled seat expansion in cloud-native segments and perpetual license erosion rates across professional studios. Forecast inputs incorporate latency tolerance thresholds for tracking applications and AI-assisted mastering adoption curves among semi-professional users. Volume and value outputs reflect reconciliation between developer-reported subscriber metrics and distributor channel inventory movements across the projection horizon.
Several conditions sit outside the modeled scope, including unlicensed software penetration rates and gray-market plugin distribution. Forecasts reflect assumptions regarding sustained semiconductor foundry capacity and stable content creator economy monetization. Generative AI copyright litigation outcomes and Taiwan Strait logistics disruptions represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
APAC Animation, VFX and Post Production Market
Digital Media
Video Content Management Market
Digital Media
Online Entertainment Market
Digital Media
Digital Content Creator Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
Indonesia Digital Media Market
Digital Media
APAC Media and Entertainment Market
Digital Media
In Flight Entertainment Market
Digital Media
Secondary Ticket Market
Digital Media
Digital Content Locker Market
Digital Media
Africa Animation Market
Digital Media
Entertainment Transcription Market
Digital Media
Anime Derivatives Market
Digital Media
Stock Music Software Market
Digital Media
Asia Pacific Photography Service Market
Digital Media
Manga Market