
 United Kingdom Webtoons Market | 2026-2036
United Kingdom Webtoons Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Webtoons Market Insights
Competitive Dynamics
ISO 27001 certification for data security is collapsing as a baseline requirement for platform operators seeking UK market access. NAVER Webtoon leverages its proprietary Canvas creator ecosystem to sustain a pipeline of original British content. Kakao Webtoon anchors its position through exclusive licensing partnerships with Korean studios, while Tapas Media differentiates via community-driven discovery tools that prioritize emerging domestic artists.
Market Structure
Webtoons are digital-native, vertically-scrolling comic narratives optimized for smartphone consumption, rendered in infinite canvas formats with embedded audio and animation layers that distinguish them from paginated print comics. The romance and fantasy genres dominate UK reader engagement, with freemium monetization capturing the largest user base while subscription models concentrate among young adults seeking ad-free binge access. Platform type segmentation shows mobile apps commanding primary consumption, though smart TV integrations represent an emerging distribution channel for serialized drama content.
Regulatory Environment
Ofcom's Online Safety Bill and the UK Age-Appropriate Design Code shape content moderation obligations and data handling practices for webtoon platforms serving minors. The Competition and Markets Authority scrutinizes in-app purchase mechanics and creator revenue-sharing terms under evolving digital markets rules. Stakeholders must monitor forthcoming amendments to the Digital Services Act's UK implementation, as these will determine liability frameworks for user-generated narrative content and algorithmic recommendation systems.
Market Dynamics
Mobile-first content delivery is compressing production cycles and fragmenting audience attention across shorter-form vertical narratives, forcing platforms to rebuild monetization architectures around micro-transaction psychology rather than traditional subscription loyalty.
Growth Catalysts
- Ofcom's Online Safety Bill:The regulatory framework is accelerating platform investment in age-verification infrastructure and parental control tools, creating competitive differentiation for compliant operators serving minors.
- Smart TV distribution channels:Living-room consumption of serialized drama webtoons is expanding total addressable audience beyond mobile-native demographics into household co-viewing segments.
- Canvas creator ecosystems:Proprietary self-publishing tools are democratizing production access, enabling Manchester and London-based artists to bypass traditional gatekeeping and build direct reader relationships.
Market Restraints
- Creator revenue-share concentration:Platform economics heavily favor established operators with scale, squeezing independent artists and limiting sustainable career pathways for emerging British talent.
- Korean studio supply dominance:Exclusive licensing agreements with Seoul-based production houses create content pipeline dependencies that constrain domestic original programming ratios.
- Digital Services Act implementation friction:Evolving liability frameworks for algorithmic recommendation systems are forcing costly compliance redesigns ahead of final regulatory guidance.
Strategic Opportunities
- Audio-visual convergence:Embedded sound design and limited animation layers are creating hybrid formats that bridge podcast, music streaming, and visual narrative consumption patterns.
- Edinburgh-Glasgow creative corridor:Scotland's emerging media production infrastructure offers lower operational costs than London while maintaining access to UK distribution networks.
- Competition and Markets Authority scrutiny:Regulatory pressure on in-app purchase mechanics is creating openings for alternative monetization models including direct creator tipping and merchandise integration.
Industry Challenges
- ISO 27001 certification timelines:Data security baseline requirements are extending platform launch schedules and elevating infrastructure costs for new market entrants.
- Algorithmic content moderation expertise:Scarcity of bilingual Korean-English technical talent capable of training culturally-sensitive recommendation engines is bottlenecking localization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Webtoons Market |
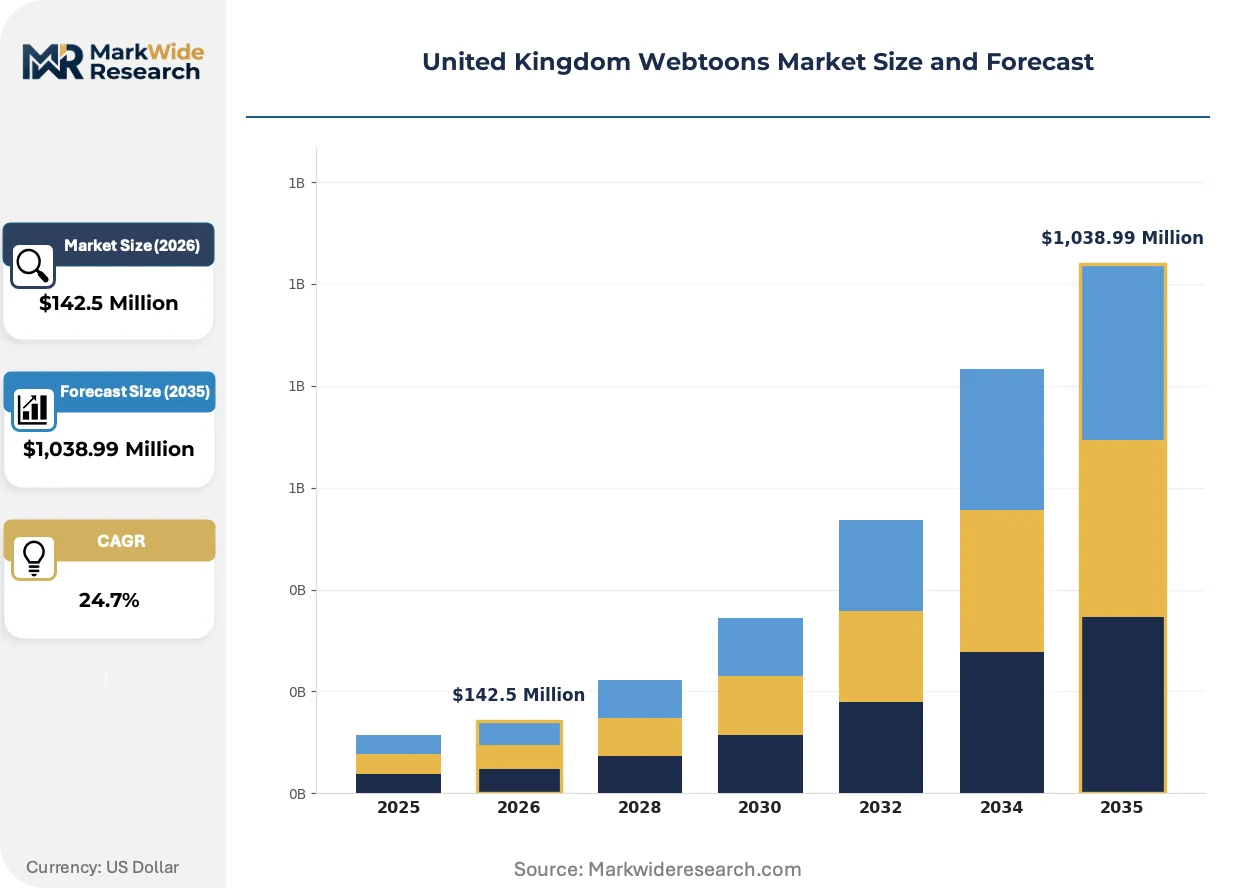
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $1,038.99 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Genre: Romance, Fantasy, Action, Comedy, Drama, Thriller Platform Type: Mobile Apps, Websites, Social Media, E-Readers, Desktop Applications, Smart TVs User Age Group: Teens, Young Adults, Adults, Middle-aged, Seniors Monetization Model: Freemium, Subscription, Pay-per-episode, Advertising, Merchandise Sales, Crowdfunding |
| Companies Covered | NAVER Webtoon, Kakao Webtoon, Lezhin Entertainment, Marvel Unlimited, Tapas Media, Tappytoon, Toomics Global, Sidewalk Group, Bomtoon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Webtoons Market Trends and Innovations
Generative production tools and immersive format experimentation are redefining creator economics and reader engagement mechanics across the UK digital comics ecosystem.
Infinite canvas rendering engines with dynamic panel transitions are miniaturizing the technical barrier between amateur creators and professional-grade output. Manchester-based animation graduates are adopting these tools at twice the rate of traditional illustration software. The compression of production skill requirements is enabling faster content iteration cycles and reducing dependency on studio infrastructure.
Ofcom's Age-Appropriate Design Code is mandating granular data collection limitations for platforms serving users under 18. The industrial consequence is a forced pivot toward contextual advertising and content-based rather than behavioral recommendation systems. Romance and fantasy segments targeting young adults are responding with explicit content labeling and opt-in personalization frameworks.
Co-viewing behavior on smart TV integrations is fragmenting the historically solitary mobile consumption model. Family-oriented drama webtoons are displacing individual binge sessions as the primary engagement pattern. This shift is most visible in London metropolitan households where multi-device subscription stacking already exceeds national averages.
United Kingdom Webtoons Market Segmentation
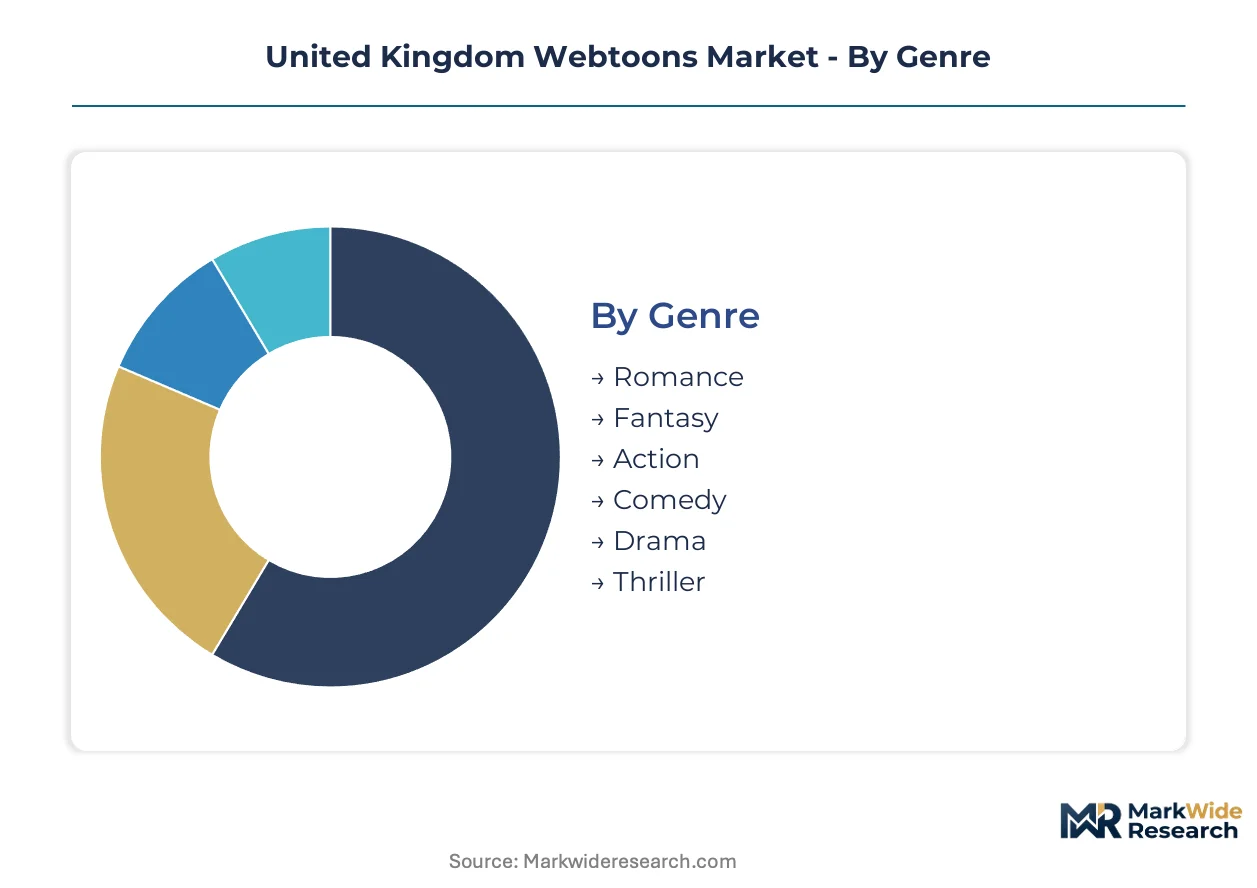
Segmentation reveals how UK webtoon consumption fragments across distinct reader behaviors and platform preferences. Publishers calibrate content investment and distribution partnerships by mapping these divides.
Genre:
Romance and Fantasy command the deepest monetization pools through young adult subscription retention, while Action and Thriller segments monetize through advertising volume.
- Romance:Vertical-scroll intimacy formats with episodic cliffhangers optimize for mobile binge sessions. London-based young adults drive subscription conversion through character-driven serials with embedded audio layers.
- Fantasy:Infinite canvas world-building with dynamic panel transitions supports complex visual lore. Manchester's creative technology corridor supplies original British IP as Korean studio licensing costs escalate.
- Action:Fast-paced panel pacing suits commuter consumption patterns on mobile apps.
- Comedy:Short-form vertical strips dominate social media discovery channels.
- Drama:Serialized narrative arcs perform strongest on smart TV household co-viewing integrations.
- Thriller:Sound design integration creates podcast-adjacent immersive formats for audio-visual convergence.
Romance holds the dominant share, while Drama is expanding most quickly through living-room distribution channels.
Platform Type:
Mobile Apps concentrate reader attention and transaction frequency, though Smart TVs are fragmenting consumption contexts toward household settings.
- Mobile Apps:Native vertical-scroll rendering with offline caching dominates UK commute patterns. Ofcom's Age-Appropriate Design Code forces contextual advertising pivots for teen segments.
- Smart TVs:HDMI-integrated webtoon browsers enable serialized drama co-viewing. London metropolitan households with multi-device stacking exceed national average adoption rates.
- Websites:Browser-based access supports creator ecosystem onboarding through Canvas-style tools.
- Social Media:Discovery-first snippets drive funnel conversion toward platform-native apps.
- E-Readers:E-ink limitations constrain animation layers to static panel formats.
- Desktop Applications:Production-grade tools serve Manchester and Edinburgh-Glasgow creator corridors.
Mobile Apps retain the largest user base, yet Smart TVs show the steepest expansion trajectory among emerging channels.
User Age Group:
Young Adults generate the highest revenue per user through subscription stacking, while Teens drive advertising volume despite data collection restrictions.
- Young Adults:Ad-free binge subscriptions concentrate in London's creative technology corridor. Romance and Fantasy genre loyalty sustains platform retention metrics.
- Teens:Freemium conversion with parental oversight tools dominates this segment. Ofcom's Online Safety Bill mandates age-verification infrastructure investment.
- Adults:Pay-per-episode models suit irregular consumption patterns.
- Middle-aged:Smart TV drama co-viewing represents primary entry point.
- Seniors:Accessibility features and simplified navigation drive nascent adoption.
Young Adults command the dominant share, with Teens gaining share fastest through social media discovery mechanics.
Monetization Model:
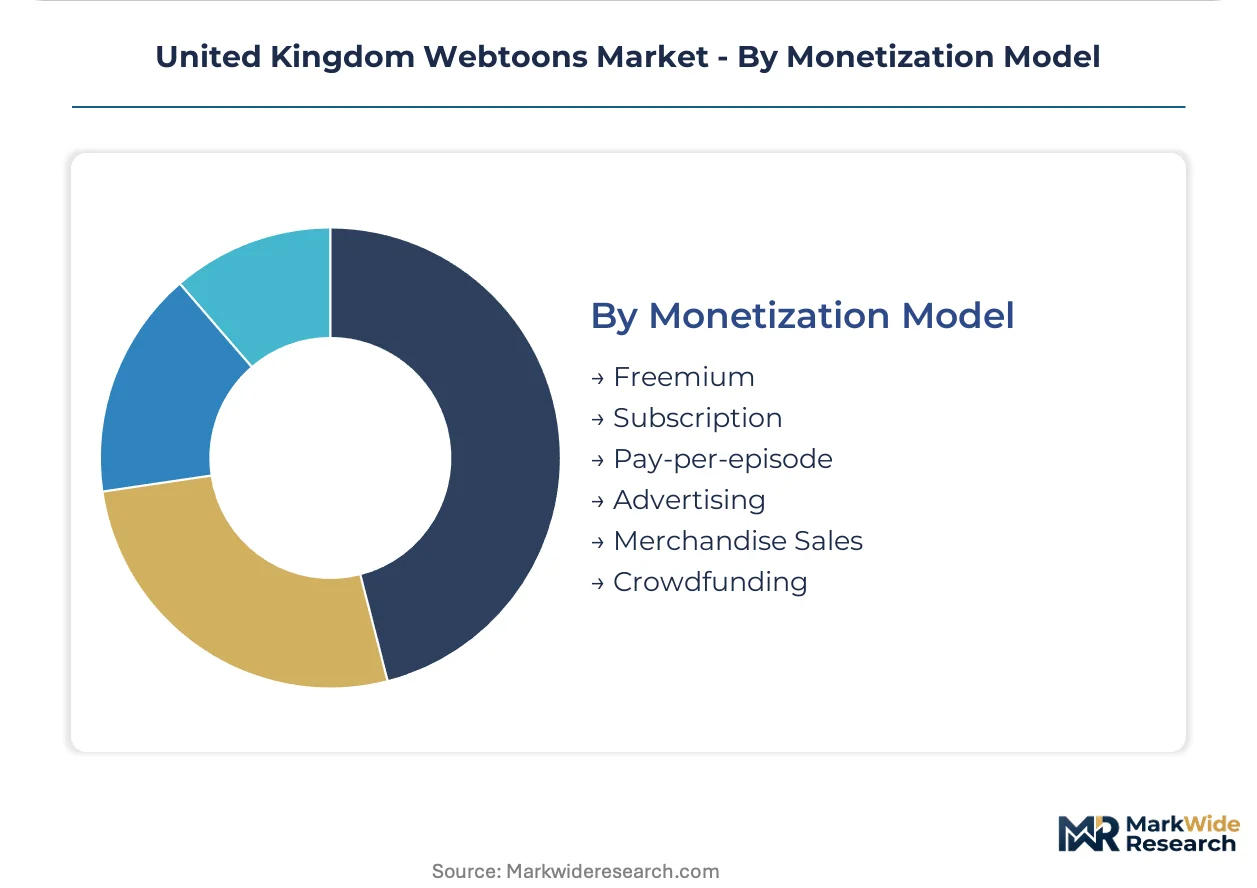
Freemium architectures capture volume, while Subscription models concentrate value among committed young adult readers.
- Freemium:Ad-supported early episodes with paywalled premium content sustain UK market entry. Competition and Markets Authority scrutiny of in-app purchase mechanics pressures conversion funnel design.
- Subscription:Unlimited ad-free access with early-release privileges retains London-based young adult cohorts. Romance and Fantasy content libraries differentiate platform positioning.
- Pay-per-episode:Micro-transaction psychology targets irregular readers.
- Advertising:Contextual placement replaces behavioral targeting under Age-Appropriate Design Code constraints.
- Merchandise Sales:Direct creator tipping integrations bypass platform revenue-share concentration.
- Crowdfunding:Canvas ecosystem tools enable Manchester-based artists to fund original production.
Freemium maintains the dominant share, though Subscription is climbing the fastest as ad-free preferences harden among core demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ofcom's Online Safety Bill and the UK Age-Appropriate Design Code are reshaping platform compliance investments across British sub-regions, concentrating operational expansion in creative clusters with established media infrastructure and regulatory familiarity.
London and the Southeast
Young adult subscription stacking drives revenue concentration in the capital's creative technology corridor. The Online Safety Bill mandates age-verification infrastructure that platforms must deploy before serving minors. Shoreditch and King's Cross house the densest concentration of webtoon production studios and platform regional headquarters.
North England
Manchester's media production cluster supplies original British fantasy IP as Korean studio licensing costs escalate. The Competition and Markets Authority scrutinizes in-app purchase mechanics affecting freemium conversion rates. Salford's MediaCityUK anchors domestic creator ecosystem development with lower operational costs than London.
Scotland
The Edinburgh-Glasgow creative corridor offers production infrastructure at rates below southern England while maintaining UK distribution access. Scottish Enterprise innovation funding supports digital content startups navigating ISO 27001 certification timelines. Leith and the Merchant City emerge as secondary production hubs for audio-visual convergence formats.
Wales
Cardiff's screen industries cluster extends into webtoon production through animation graduate pipelines from University of South Wales. Welsh Government creative sector investment targets post-pandemic digital content expansion. The capital's co-working infrastructure supports Manchester and London-based creators seeking cost arbitrage.
United Kingdom Webtoons Market Competitive Landscape
Player mix skews toward Korean-origin platform operators with proprietary creator ecosystems and British-registered distribution arms. Market structure concentrates around three strategic tiers: vertically integrated content studios with exclusive IP pipelines, self-publishing platforms democratizing production access, and legacy comics publishers adapting print franchises for vertical-scroll formats. Dominant competitive moves include exclusive licensing partnerships with Seoul-based production houses and ISO 27001 certification races to satisfy UK data security baselines.
Within the Korean-origin platform tier, NAVER Webtoon and Kakao Webtoon exemplify vertically integrated operators leveraging proprietary creator ecosystems and exclusive studio relationships to sustain British content pipelines. Tapas Media occupies a differentiated position among community-driven discovery specialists prioritizing emerging domestic artists through direct reader relationship tools. These three anchors represent distinct competitive vectors: scale-driven licensing power, integrated production control, and creator-economy democratization.
| Leading Market Players |
|---|
| NAVER Webtoon |
| Kakao Webtoon |
| Lezhin Entertainment |
| Marvel Unlimited |
| Tapas Media |
| Tappytoon |
| Toomics Global |
| Sidewalk Group |
| Bomtoon |
| Others |
Pricing and Supply Chain Analysis
Platform scale economies in user acquisition and content licensing compress marginal distribution costs while elevating price floors for smaller competitors. Manchester and London-based creator ecosystems face margin pressure as Korean studio supply concentration shapes licensing terms across the UK market.
Pricing Analysis
Certification level for ISO 27001 data security compliance creates the primary spread between premium platform tiers and budget entrants. Subscription models stratify across ad-free binge access, freemium conversion funnels, and pay-per-episode micro-transactions, with young adult readers in London showing lowest price sensitivity due to multi-device stacking behavior. Pricing pressure stems from Competition and Markets Authority scrutiny of in-app purchase mechanics, forcing redesigns of conversion architectures. Independent artists and emerging British talent face highest price sensitivity as platform revenue-share concentration squeezes sustainable career pathways.
Supply Chain Analysis
Content inventory lead times from Korean studios stretch to 18-24 months for exclusive licensing deals, constraining UK platform release schedules. Supply concentrates in South Korea for original IP production, with Manchester and London supplying secondary domestic content pipelines. Raw material dependencies include proprietary Canvas creator tools, infinite canvas rendering engines, and bilingual Korean-English technical talent for algorithmic moderation. Single-source vulnerability runs through Seoul-based production house exclusivity. Distribution runs through mobile app stores, smart TV integrations, and direct creator-reader channels via self-publishing ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK webtoon platforms operate in a substitution defense posture against short-form video platforms and podcast-audio narratives that fragment mobile attention. TikTok and YouTube Shorts represent the most acute substitute threat as they capture young adult screen time with lower production barriers.
For Market Incumbents: Secure exclusive licensing pipelines with Manchester and Edinburgh-Glasgow creator corridors before Korean studio cost escalation accelerates. Lock ISO 27001 certification advantages into long-term data security positioning against emerging entrants. Build smart TV distribution partnerships to defend against short-form video substitution in household co-viewing contexts.
For New Entrants and Emerging Players: Differentiate on audio-visual convergence formats that bridge podcast and visual narrative consumption patterns. Target Scotland's lower-cost production infrastructure with Edinburgh-Glasgow corridor access. Pursue direct creator tipping and merchandise integration as alternative monetization angles bypassing in-app purchase scrutiny.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with proprietary creator ecosystems and regulatory compliance infrastructure already deployed. Long-term viability over a 5-10 year window rests on domestic original programming ratios and Ofcom regulatory familiarity. Watch for inflection when Competition and Markets Authority rulings force structural changes to platform revenue-share terms.
| Strategic Initiative | Industry Significance |
|---|---|
| Canvas Ecosystem Expansion | Proprietary self-publishing tools in Manchester reduce dependency on Korean studio licensing. |
| Smart TV Distribution Partnership | Living-room co-viewing opens household segments beyond mobile-native demographics. |
| ISO 27001 Certification Investment | Data security baseline creates competitive moat as regulatory scrutiny intensifies. |
| Audio-Visual Format Development | Embedded sound design bridges podcast and visual narrative consumption patterns. |
| Creator Revenue-Share Restructuring | Alternative monetization models preempt Competition and Markets Authority intervention. |
Research Methodology
Cross-validation between platform operator disclosures and creator ecosystem surveys anchors the qualitative findings in this study. Primary interviews with webtoon platform executives, Manchester and London-based content creators, Ofcom regulatory affairs specialists, and smart TV distribution partners combined with secondary validation from App Annie mobile analytics, SEC filings of Korean parent companies, Ofcom regulatory guidance documents, and UK creative industry trade association reports. Bottom-up content pipeline modeling and top-down addressable audience estimation provided triangulation across the analysis window.
Sensitivity analysis around user acquisition cost assumptions and Korean studio licensing inflation rates stress-tested projection robustness. The analytical framework segments by genre, platform type, user age group, and monetization model across the modeling period. CAGRs derived from cohort retention curves and subscription conversion benchmarks. Industry-specific inputs included Canvas creator adoption rates in Manchester and Edinburgh-Glasgow corridors, and smart TV integration penetration in London metropolitan households.
The analysis sits within stated boundaries; outcomes outside sustained young adult subscription retention or stable Korean studio supply relationships would require recalibration. Forecasts reflect documented assumptions regarding Ofcom regulatory implementation timelines and platform compliance cost trajectories. Revision becomes warranted when Competition and Markets Authority rulings on in-app purchase mechanics cross enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Webtoons Market
Digital Media
Europe Inflight Entertainment and Connectivity Market
Digital Media
Digital Effects Services Market
Digital Media
Multichannel Network Market
Digital Media
Europe Animation, VFX and Post Production Market
Digital Media
Europe Location-Based Entertainment Market
Digital Media
Music Rights Management Market
Digital Media
Middle East Gaming Market
Digital Media
North America Webtoons Market
Digital Media
Anime Merchandising Market
Digital Media
Anime Derivatives Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Middle East Media and Entertainment Market
Digital Media
Video Content Management Market
Digital Media
4K Content Market
Digital Media
Digital Rights Management in Media and Entertainment Market