
 Global Animation Market | 2026-2036
Global Animation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animation Market Analysis
Enterprise streaming buyers is rotating budget share away from traditional broadcast networks toward direct-to-consumer platforms. Walt Disney Animation Studios leverages its vertically integrated content pipeline across theatrical and streaming windows. Pixar Animation Studios sustains premium positioning through proprietary RenderMan technology and selective output. DreamWorks Animation anchors volume production through its multi-year distribution partnership with Netflix, while Illumination competes on cost-efficient franchise development.
Animation encompasses the sequential manipulation of static images, digital models, or physical puppets to create perceived motion, typically rendered at 24 frames per second for cinematic output and leveraging raster or vector-based compositing pipelines. Its primary commercial purpose spans entertainment content, brand communication, interactive media, and instructional design. 3D animation occupies the largest revenue pool due to universal theatrical and streaming applicability, while motion graphics commands premium pricing in advertising and brand identity work. Streaming services represent the fastest-growing distribution channel as platform exclusivity reshapes commissioning structures.
The US FCC governs broadcast content standards affecting animation syndication, while the EU's Audiovisual Media Services Directive shapes cross-border streaming obligations and youth protection mandates for platform-hosted animated content. Japan's METI promotes animation exports through content industry subsidies and co-production treaties. Stakeholders must monitor how fragmented national content quotas alter global distribution economics and production location decisions.
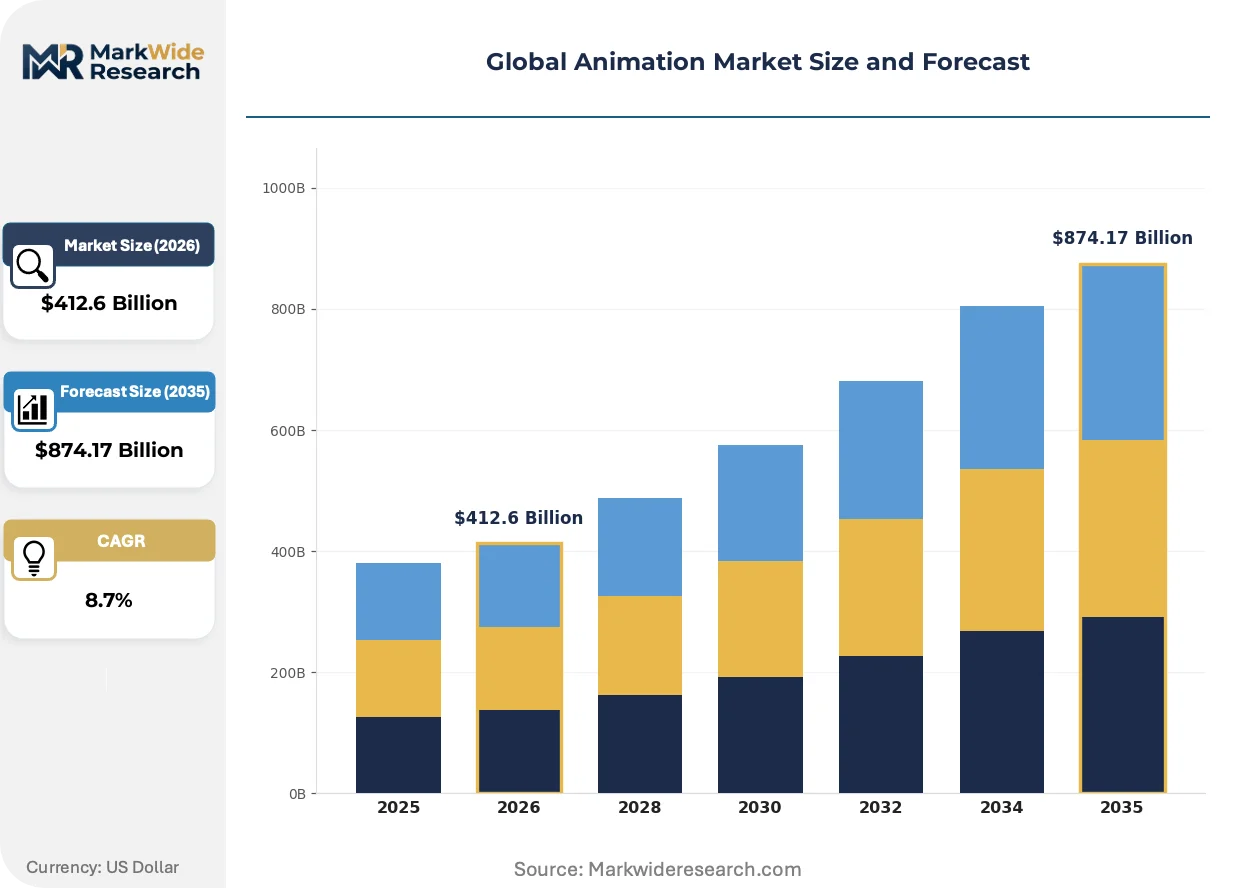
Market Dynamics
Streaming platform commissioning power is compressing traditional theatrical windows and redistributing capital toward episodic production cycles, forcing studios to restructure talent contracts and pipeline investments around binge-release economics rather than box-office performance.
Growth Catalysts
- AI-Assisted Rendering:Machine learning inference tools accelerate frame completion and reduce compute farm hours for mid-budget productions. Studios deploy neural denoising and motion interpolation to compress delivery timelines.
- Japan's METI Content Export Subsidies:Co-production treaties and soft loans incentivize domestic studios to partner with foreign platforms. Funding flows toward series with cross-border licensing potential.
- Interactive Media Expansion:Real-time engines from game developers now power previsualization and final-pixel rendering for linear content. Convergence between gaming and animation pipelines opens new revenue pools.
Market Restraints
- Compute Cost Volatility:Cloud rendering pricing fluctuates with energy markets and semiconductor availability. Studios face margin pressure when farm utilization rates drop below contracted baselines.
- Talent Concentration in Los Angeles and Tokyo:Senior animators and technical directors cluster in high-cost metropolitan hubs. Wage arbitrage remains limited for premium creative roles.
- EU Audiovisual Media Services Directive:Cross-border youth protection mandates and content quota obligations add compliance overhead for platform-hosted animation. Localization costs rise for catalog distribution.
Strategic Opportunities
- Underpenetrated Indian Streaming Subscribers:Regional language animation consumption accelerates as domestic platforms expand original commissioning. Price-sensitive production models suit cost-efficient studios.
- Virtual Production Convergence:LED volume stages and real-time compositing merge live-action and animated workflows. Hybrid productions reduce location shooting expenses.
- South Korea's Content Industry Tax Incentives:Government credits for animation production attract foreign co-investment. Seoul-based studios expand capacity to serve platform demand.
Industry Challenges
- Pipeline Integration Complexity:Legacy asset management systems resist cloud-native collaboration tools. Studios face downtime during platform migrations.
- Intellectual Property Licensing Friction:Character rights fragmentation across merchandise, gaming, and sequel territories slows franchise expansion. Rights holders demand escalating minimum guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animation Market |
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $874.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Technique: 2D Animation, 3D Animation, Stop Motion, Motion Graphics Distribution Channel: Theatrical Release, Streaming Services, TV Broadcasting, Home Video End User: Entertainment, Education, Advertising, Video Games Market Type: Feature Films, Short Films, TV Series, Online Content |
| Companies Covered | Sony Pictures Animation, Digital Domain, Walt Disney Animation Studios, Blur Studio, Animal Logic, Pixar Animation Studios, Illumination, Titmouse, DreamWorks Animation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animation Market Emerging Trajectories
Generative tools are redistributing creative labor from intermediate production roles toward prompt engineering and final polish, while real-time engines compress the gap between previsualization and delivered pixels.
Neural rendering is fragmenting the traditional compositing pipeline. Diffusion-based inpainting and style transfer tools now handle background generation and crowd simulation tasks previously assigned to junior artists. Mid-tier studios adopt these tools to maintain output volume without proportional headcount expansion. The technology is fragmenting established career ladders and compressing entry-level hiring.
The EU AI Act establishes transparency obligations for synthetic media deployed in platform-hosted content. Studios must document training data provenance and disclose AI-assisted sequences to viewers. Children's animation faces heightened scrutiny under youth protection annexes, prompting platforms to demand compliance certifications before greenlighting productions.
Platform exclusivity is reshaping commissioning relationships. Streamers now acquire full rights packages upfront rather than licensing windows, eliminating syndication residuals for creators. This model concentrates in the United States and United Kingdom where subscription penetration supports premium original spending. Independent studios respond by forming equity partnerships to retain backend participation.
Global Animation Market Segmentation
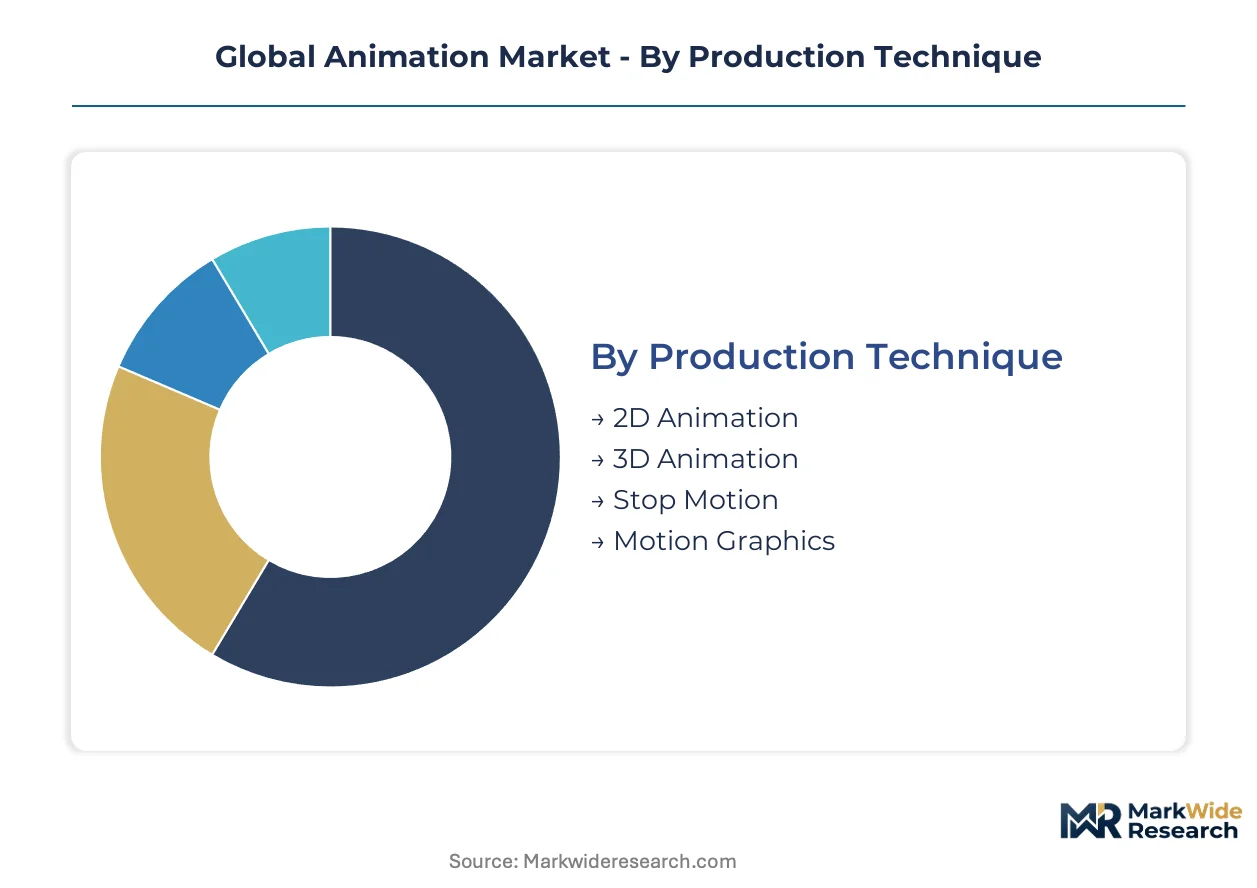
Production technique and distribution channel segmentation reveals where platform economics are reshaping investment allocation. Studios restructure pipelines around the segments where streaming commissioning power concentrates capital most intensely.
Production Technique:
3D animation faces intensifying substitution pressure from AI-assisted rendering tools that compress frame completion timelines, while motion graphics confronts generative design platforms automating brand asset creation.
- 3D Animation:Polygon-based modeling and rigging pipelines deliver universal theatrical and streaming applicability. Demand concentrates in Los Angeles and Tokyo as Disney and Pixar anchor premium franchise development, though cloud rendering cost volatility pressures mid-budget studios.
- Motion Graphics:Vector and raster compositing drives brand identity work, advertising spots, and title sequences. Advertising agencies in New York and London command premium pricing for campaign-ready deliverables with compressed turnaround requirements.
- 2D Animation:Traditional frame-by-frame and digital cutout methods persist in Japanese anime production and adult-oriented streaming series.
- Stop Motion:Physical puppet manipulation retains niche theatrical positioning through Laika Entertainment and Aardman Animations productions.
3D animation retains volume leadership; motion graphics holds the steepest expansion curve as brand content volumes accelerate.
Distribution Channel:
Cost tier stratification separates premium theatrical windows from mass-market streaming access, with customer willingness-to-pay diverging sharply across exhibition formats.
- Streaming Services:Platform exclusivity reshapes commissioning structures as Netflix, Disney+, and Amazon Prime Video acquire full rights packages upfront. Binge-release economics compress traditional syndication windows and eliminate residual participation for independent creators.
- Theatrical Release:Event-driven tentpole positioning sustains premium pricing for franchise installments and Pixar original features. Domestic box-office concentration in the United States and Japan supports 90-day windows before streaming migration.
- TV Broadcasting:Linear syndication contracts face declining renewal rates as cable subscriptions erode and advertising shifts to connected TV platforms.
- Home Video:Physical media sales concentrate in collector editions and franchise box sets as streaming catalog depth reduces purchase intent.
Streaming services command the dominant share of commissioning volume; theatrical release maintains the highest per-unit revenue extraction.
End User:
Application maturity varies sharply, with entertainment exhibiting saturated platform penetration while education and advertising show divergent technology adoption curves.
- Entertainment:Feature films, series, and short-form content absorb the majority of production capital. Platform competition between Disney+, Netflix, and Max drives original commissioning volumes in Burbank, Culver City, and London.
- Video Games:Real-time engine convergence enables previsualization and final-pixel rendering crossover. Epic Games' Unreal Engine and Unity power cinematic sequences for AAA titles and streaming adaptations.
- Advertising:Brand communication and product visualization demand rapid iteration cycles. Motion graphics studios in Chicago and Amsterdam serve campaign timelines measured in days rather than months.
- Education:Instructional design and e-learning modules accelerate as corporate training budgets shift to animated explainer content.
Entertainment dominates production employment; video games demonstrates the most rapid pipeline technology migration.
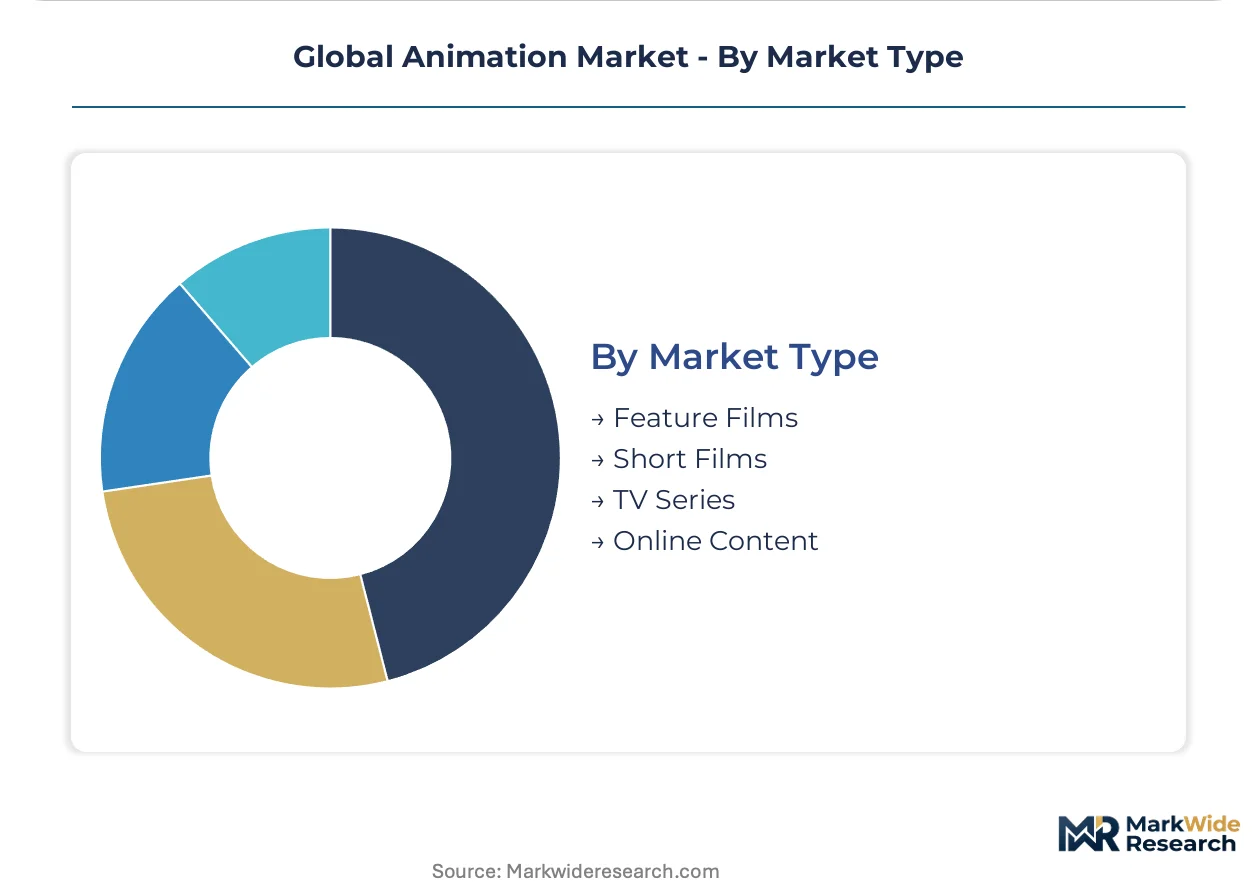
Market Type:
Supply concentration clusters in episodic formats where streaming volume commitments justify dedicated pipeline investment, while short films face funding fragmentation.
- TV Series:Episodic production cycles align with platform binge-release strategies and annual franchise refresh requirements. DreamWorks Animation's Netflix partnership exemplifies volume-oriented commissioning structures.
- Feature Films:Theatrical tentpoles and streaming originals command the highest per-project budgets. Walt Disney Animation Studios leverages vertical integration across production, distribution, and merchandise licensing.
- Online Content:Short-form and user-generated platforms expand addressable inventory. YouTube and TikTok creator economies lower barrier to entry for independent animators.
- Short Films:Festival circuits and anthology platforms provide showcase opportunities with limited commercial scale.
TV series absorbs the largest capital deployment; online content gains share fastest as platform algorithms prioritize volume velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform commissioning power concentrates in territories with mature streaming infrastructure and established studio ecosystems. Buyers in the United States, Japan, and South Korea absorb disproportionate original production volumes, while emerging markets present volume opportunities at compressed price points.
United States
Los Angeles and Burbank anchor theatrical and streaming production for Disney, Pixar, and DreamWorks. The FCC governs broadcast content standards affecting syndication windows. Senior animator wage premiums in California metro areas exceed national averages by substantial margins.
Japan
Tokyo and Osaka studios supply global anime demand through Netflix and Crunchyroll licensing. METI content export subsidies and co-production treaties incentivize cross-border partnerships. Production committees in Suginami Ward coordinate funding for series with international distribution potential.
South Korea
Seoul-based studios expand capacity to serve platform volume commitments from Netflix and Disney+. Government tax credits for animation production attract foreign co-investment. The Bucheon cluster specializes in 2D and hybrid 3D pipelines for episodic series.
United Kingdom
London houses advertising-focused motion graphics studios serving campaign timelines measured in days. The EU AI Act's transparency obligations for synthetic media apply to platform-hosted content distributed across member states. Manchester and Bristol clusters develop children's programming for BBC and Channel 4.
India
Mumbai and Bengaluru studios produce regional-language animation for domestic streaming platforms. Price-sensitive commissioning models suit cost-efficient production structures. The country's national broadcasting regulator shapes content standards for platform-hosted children's programming.
Global Animation Market Vendor Landscape
Player mix skews toward vertically integrated entertainment conglomerates with captive distribution infrastructure. Consolidation around theatrical-streaming hybrid models produces tiered competitive positioning. Three archetypes dominate: premium franchise developers with proprietary technology, volume-oriented episodic producers with platform partnerships, and specialized shops serving advertising and previsualization niches. M&A activity targets pipeline technology assets, while strategic partnerships secure exclusive platform commissioning relationships.
Within the premium franchise tier, Walt Disney Animation Studios and Pixar Animation Studios exemplify vertically integrated production-distribution models. DreamWorks Animation occupies a position bridging volume and prestige through its multi-year Netflix partnership. Among specialized production services, Animal Logic and Blur Studio represent the high-end visual effects and previsualization segment where real-time engine adoption accelerates delivery timelines.
| Leading Market Players |
|---|
| Sony Pictures Animation |
| Digital Domain |
| Walt Disney Animation Studios |
| Blur Studio |
| Animal Logic |
| Pixar Animation Studios |
| Illumination |
| Titmouse |
| DreamWorks Animation |
| Others |
Supply Flow & Price Mechanics
The EU AI Act's transparency obligations for synthetic media simultaneously gate supply qualification for platform-hosted animation and stratify price differentiation across compliance tiers. Studios must document training data provenance and disclose AI-assisted sequences, creating cost premiums for certified productions while compressing margins for non-compliant catalog.
Pricing Analysis
Next-generation AI-assisted rendering tools command 40-60% premiums over legacy pipeline pricing, while prior-generation manual compositing faces accelerating price erosion. Three-tier pricing structure across premium theatrical, standard streaming, and economy online content segments dominates commissioning. Price differentiation rests on certification grade for youth protection compliance and volume scale for episodic commitments. Cost compression in mid-budget streaming tiers intensifies because cloud rendering farm utilization fluctuates with energy markets. Advertising agencies in New York and London exhibit lowest price sensitivity; regional Indian platforms demonstrate highest.
Supply Chain Analysis
Los Angeles-Tokyo-Seoul talent corridors constitute the primary chokepoint constraining premium animation output expansion. Geographic supply concentration clusters in the United States, Japan, and South Korea as content export hubs with captive distribution infrastructure. Raw material dependencies encompass GPU compute cycles, proprietary rendering software licenses, and senior animator labor pools. Single-source vulnerability runs through concentrated cloud rendering providers and specialized technical director talent. Distribution runs through vertically integrated streaming platforms acquiring full rights packages upfront rather than windowed licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Senior technical director scarcity in Los Angeles and Tokyo metro areas constrains output expansion regardless of capital availability, making talent pipeline development the decisive competitive variable.
For Market Incumbents: Fortify proprietary rendering technology moats through accelerated Unreal Engine and neural denoising integration before generative tools commoditize intermediate production roles. Defend against Netflix-Disney volume partnerships squeezing independent studio margins by locking multi-year platform exclusivity with escalating minimum guarantees. Prioritize backward integration into cloud rendering infrastructure to neutralize compute cost volatility. For New Entrants and Emerging Players: EU AI Act compliance fast-tracks unlock platform commissioning access as streamers demand youth protection certifications before greenlighting. White-space concentrates in regional Indian language animation and corporate e-learning explainer modules where price-sensitive production models suit lean cost structures. Go-to-market positioning should emphasize rapid-turnaround motion graphics for advertising agencies facing compressed campaign timelines. For Investors and Strategic Acquirers: The EU AI Act's transparency mandate reshapes the acquisition landscape by elevating studios with documented training data provenance and established compliance workflows. Long-term viability favors targets with captive distribution relationships or proprietary pipeline technology rather than pure production capacity. Signal to watch: platform exclusivity terms shifting from windowed licensing to full rights acquisition, eliminating syndication residual streams.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Rendering Integration | Neural denoising and motion interpolation compress DreamWorks-Netflix episodic delivery timelines substantially. |
| Platform Exclusivity Partnership | Multi-year Disney+ and Netflix volume commitments anchor Illumination's cost-efficient franchise development pipeline. |
| Regional Language Content Expansion | Mumbai and Bengaluru studios capture underpenetrated Indian streaming subscriber growth with localized commissioning. |
| Virtual Production Convergence | LED volume stages merge live-action and animated workflows for hybrid productions reducing location expenses. |
| Tax Credit Arbitrage Positioning | South Korean government incentives attract foreign co-investment into Seoul-based episodic capacity expansion. |
Methodological Framework
Initial hypotheses were tested against primary input from animation studio executives, streaming platform commissioning officers, technical directors, and advertising agency producers and refined through secondary validation. Primary fieldwork encompassed structured interviews across Los Angeles, Tokyo, Seoul, and London production clusters. Secondary sources included FCC broadcast standards filings, EU Audiovisual Media Services Directive implementation guidance, METI content export subsidy documentation, and platform subscriber disclosure data. Bottom-up project pipeline enumeration was triangulated against top-down streaming content spend estimates.
Variance decomposition across production technique, distribution channel, end-use application, and regional regulatory clusters shaped the analytical framework. Segmentation dimensions modeled encompassed 2D/3D/motion graphics technique, theatrical/streaming/broadcast channel, entertainment/gaming/advertising end-use, and US/Japan/South Korea/India/UK geographic concentration. CAGRs were derived from production volume trajectories and per-unit budget evolution across the projection horizon. Industry-specific forecast inputs incorporated cloud rendering farm utilization rates and platform original commissioning commitment disclosures.
Underlying assumptions cover sustained streaming subscriber growth, stable co-production treaty frameworks, and gradual AI tool adoption curves, with deviation risk concentrated in talent wage inflation and compute cost volatility. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and platform exclusivity terms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Middle East Gaming Market
Digital Media
Pro AV Market
Digital Media
Blockchain in Media and Entertainment Market
Digital Media
Media Coding Service Market
Digital Media
Webtoons Market
Digital Media
Digital Video Advertising Market
Digital Media
Video Production Market
Digital Media
Global Location-Based Entertainment Market
Digital Media
Media Gateway Market
Digital Media
3D Animation Market
Digital Media
Europe Location-Based Entertainment Market
Digital Media
Social TV Market
Digital Media
Media and Entertainment Market
Digital Media
Digital Video Content Market
Digital Media
Stock Music Software Market
Digital Media
Digital Content Creator Market