
 Art App Market | 2026-2036
Art App Market Size, Share, and Industry Trends Forecast 2026-2036
Art App Market Outlook
Subscription-based feature tiers is expanding the addressable base for professional-grade art tools by lowering entry costs while locking in recurring revenue. Adobe leverages its Creative Cloud ecosystem to sustain cross-selling across photography, video, and illustration workflows. Procreate specializes in iPad-optimized raster graphics, dominating the mobile illustration segment among freelance professionals. NightCafe anchors its position in AI-assisted image generation, competing on speed and style diversity rather than manual tool depth.
An art app constitutes software that enables digital drawing, painting, image manipulation, or generative creation through stylus, touch, or algorithmic input, typically supporting layers, brush engines, color management, and export to industry formats such as PSD, TIFF, or PNG for print and screen workflows. The primary commercial purpose centers on replacing or augmenting physical media for professional output, educational instruction, and social content production. Art Creation applications command the deepest engagement minutes and highest willingness to pay among professional users, while Freemium monetization models capture the broadest hobbyist base though with thinner conversion to paid tiers. Mobile platforms now lead download volume globally, yet Desktop retains the premium pricing power for complex production pipelines.
FCC guidelines on digital platform transparency and COPPA compliance shape how art apps collect user data and age-gate social features in the United States. The EU AI Act imposes disclosure obligations on generative tools, directly affecting Artbreeder and NightCafe's European deployment strategies. California's CCPA amplifies data governance costs for any app serving creators in that state. Stakeholders must monitor how divergent AI training data regulations across Washington, Brussels, and Beijing fragment product development roadmaps and compliance budgets.
Market Dynamics
Generative AI integration is compressing feature development cycles across art applications while forcing traditional tool vendors to defend their installed base against algorithmic creation workflows.
Growth Catalysts
- EU AI Act disclosure mandates:European deployment requirements for generative tools are accelerating transparency features that build user trust and differentiate compliant platforms from opaque competitors.
- Mobile-first creative workflows:Freelance illustrators and independent artists now complete entire production pipelines on tablets, expanding addressable hours beyond desktop-bound professionals.
- Stylus hardware proliferation:Apple Pencil, Samsung S Pen, and third-party active stylus adoption across education and enterprise segments is normalizing precision input as a standard expectation.
Market Restraints
- Compute cost volatility:Cloud-based AI inference for real-time style transfer and generative fill features faces GPU scarcity and energy price fluctuations that compress margin on freemium tiers.
- Training data licensing friction:Copyright ambiguity around scraped visual content creates legal exposure for generative features, particularly in jurisdictions with strong moral rights protections like France and Germany.
- Feature commoditization:Core brush engines and layer management tools have reached functional parity across mid-tier applications, eroding differentiation and pressuring pricing power.
Strategic Opportunities
- India's creator economy infrastructure:Platform payment systems and regional language support remain underdeveloped for vernacular illustration markets, creating first-mover advantages for localized art tools.
- K-12 computational art curricula:National education standards in South Korea and Japan are mandating digital creativity modules that require district-wide software licensing at scale.
- Blockchain provenance integration:NFT minting and on-chain attribution features are converging with traditional export workflows, enabling new revenue streams for artist-facing platforms.
Industry Challenges
- MLops talent scarcity:Deploying and optimizing on-device neural networks for brush prediction and style transfer requires specialized engineers that command premium compensation against constrained budgets.
- Cross-platform rendering fidelity:Maintaining color accuracy and layer behavior consistency across iOS, Android, Windows, and macOS codebases demands disproportionate QA resources relative to user base fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Art App Market |
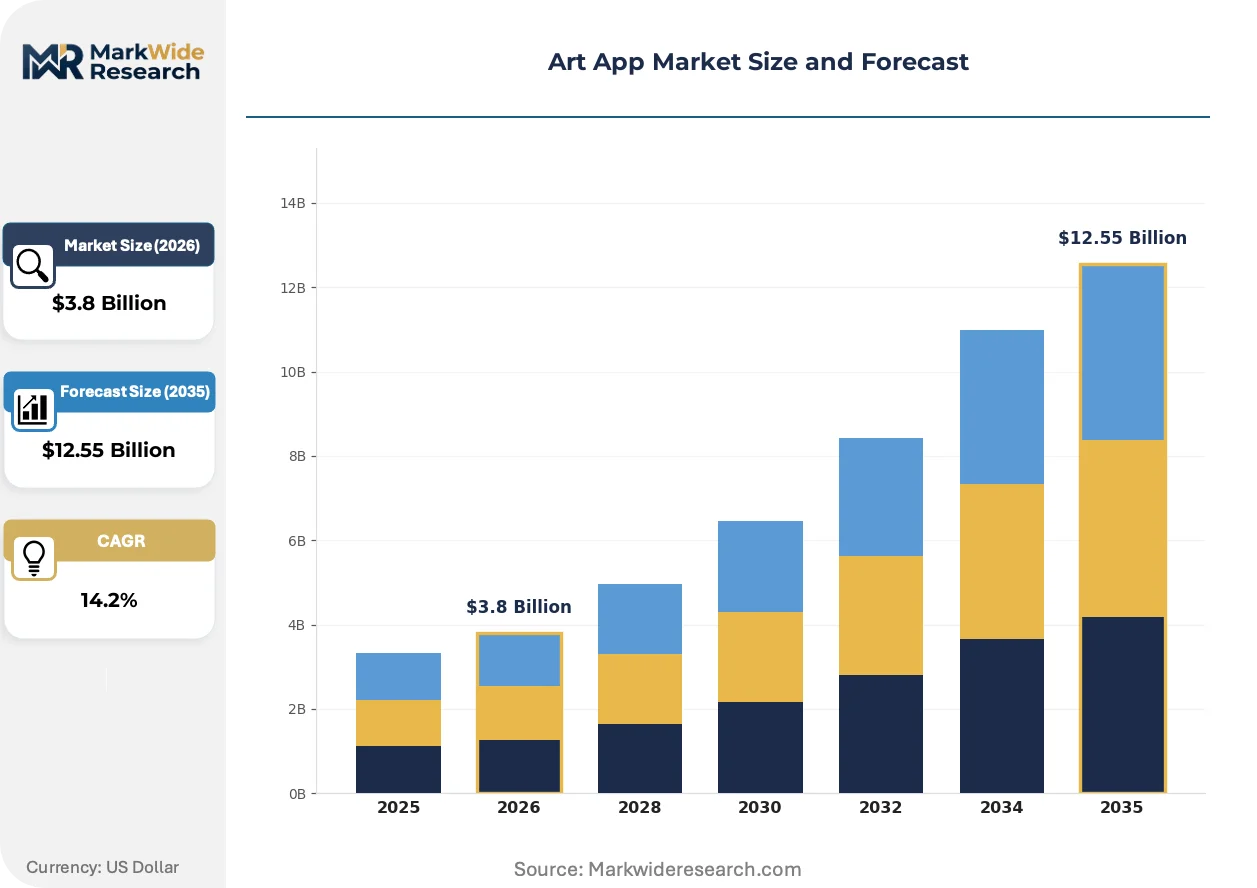
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Art Creation, Art Sharing, Art Education, Art Selling Target User: Professionals, Hobbyists, Students, Institutions Monetization Model: Subscription, In-App Purchase, Freemium, One-Time Purchase Platform Type: Mobile, Web, Desktop, Hybrid |
| Companies Covered | Affinity, NightCafe, Adobe, Prisma, ArtRage, Procreate, Clip Studio Paint, Artbreeder, Corel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Art App Market Strategic Shifts
Art applications are pivoting from tool vendors to creative infrastructure providers, embedding AI assistance, collaborative workflows, and commerce integration directly into the canvas environment.
Diffusion-based image generation is converging with traditional raster workflows. Professional illustrators now expect inpainting, outpainting, and style transfer as native layer types rather than external utilities. Adobe's Firefly integration and NightCafe's API partnerships demonstrate how generative features are becoming table stakes for retention. This convergence is compressing the boundary between manual and algorithmic creation, forcing vendors to retrain user expectations around authorship and control.
The EU AI Act's disclosure obligations are reshaping product roadmaps for generative art tools. Developers must now implement provenance tracking and synthetic content labeling that satisfies Brussels enforcement timelines. European deployment strategies for Artbreeder and similar platforms prioritize transparency dashboards over raw capability expansion. This regulatory pressure is accelerating industry-wide standardization around C2PA metadata embedding.
Subscription fatigue among hobbyist users is fragmenting monetization models. One-time purchase options and credit-based generative usage are displacing pure recurring plans in emerging markets where payment infrastructure favors microtransactions. Procreate's perpetual license success and Clip Studio Paint's dual model demonstrate viable alternatives to Creative Cloud dependency. Southeast Asian and Latin American creator communities show strongest preference for ownership-based access.
Art App Market Segmentation
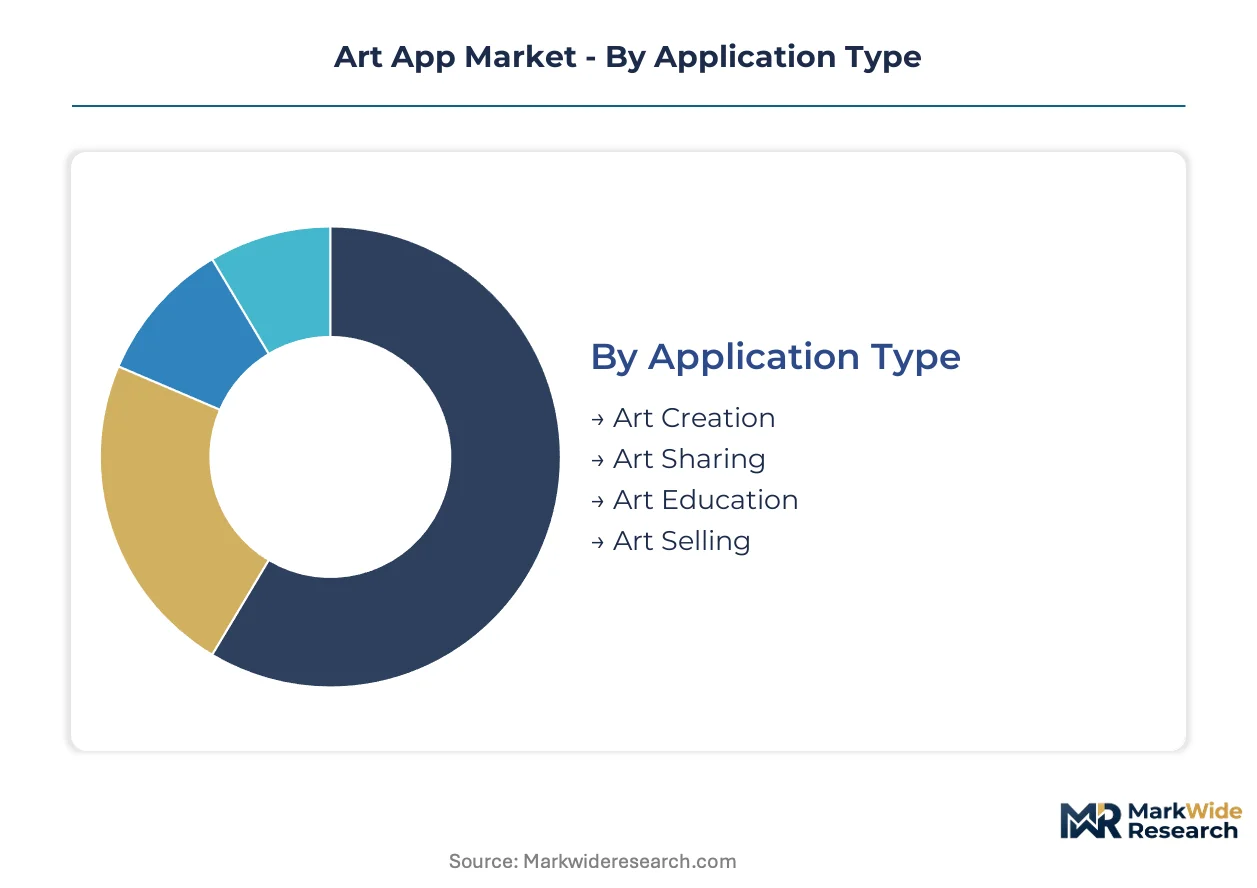
Art applications serve divergent creative workflows that demand fundamentally different feature architectures, pricing tolerance, and platform performance. Segmentation reveals where professional-grade tool investment concentrates versus where mass-market adoption scales through lowered friction.
Application Type:
Customization intensity varies sharply across this spectrum, from open-ended creation environments to transaction-optimized selling platforms.
- Art Creation:Raster and vector editing tools with layer management, brush engines, and color spaces form the technical core. Professional illustrators in the United States drive premium subscription retention through integration with Adobe Creative Cloud pipelines. GPU-accelerated rendering and stylus latency optimization differentiate competing offerings.
- Art Sharing:Social distribution layers with portfolio hosting, follower mechanics, and algorithmic discovery define this segment. Independent artists seeking audience building in South Korea and Japan concentrate engagement minutes here, though monetization remains advertising-dependent with thin conversion to paid tiers.
- Art Education:Structured curricula with skill progression tracking and instructor feedback loops serve K-12 districts and self-directed learners.
- Art Selling:Commerce-integrated platforms with print-on-demand fulfillment and commission structures enable direct artist revenue.
Most installed capacity flows through Art Creation. Expansion is steepest in Art Sharing.
Target User:
Volume concentration sits with low-ARPU segments, while margin capture concentrates among users with workflow integration requirements.
- Professionals:Freelance illustrators, concept artists, and production designers require PSD interoperability, CMYK color management, and pipeline automation. Mobile-first workflows among independent professionals in the United States are displacing desktop dependency for initial sketching and client review stages.
- Hobbyists:Casual creators prioritize low learning curves and community features over technical depth. Freemium conversion rates in this segment trail professional tiers by significant margins, though absolute user volume supports advertising and marketplace revenue models.
- Students:Educational licensing programs and verification-dependent discounts build long-term brand preference.
- Institutions:District-wide deployments and enterprise agreements with centralized billing and administrative controls serve university and corporate training environments.
Professionals generate the highest revenue per user. Hobbyists deliver the steepest expansion trajectory in emerging markets.
Monetization Model:
Payment infrastructure maturity and cultural preferences toward ownership versus access shape regional model viability.
- Subscription:Recurring revenue models with tiered feature access dominate professional segments where continuous updates justify ongoing payment. Adobe's Creative Cloud ecosystem demonstrates cross-selling potential across photography, video, and illustration workflows.
- Freemium:Base functionality with paywalled advanced features captures the broadest addressable market. Conversion optimization and generative credit packs represent the primary growth vectors for this model.
- In-App Purchase:Microtransaction-based brush packs, asset libraries, and generative credits align with payment infrastructure preferences in Southeast Asia and Latin America.
- One-Time Purchase:Perpetual licenses retain strong preference among hobbyists averse to ongoing commitments, with Procreate's iPad success illustrating viable alternative to subscription dependency.
Subscription models capture the majority of professional-grade revenue. One-Time Purchase is expanding most quickly in payment-infrastructure-constrained markets.
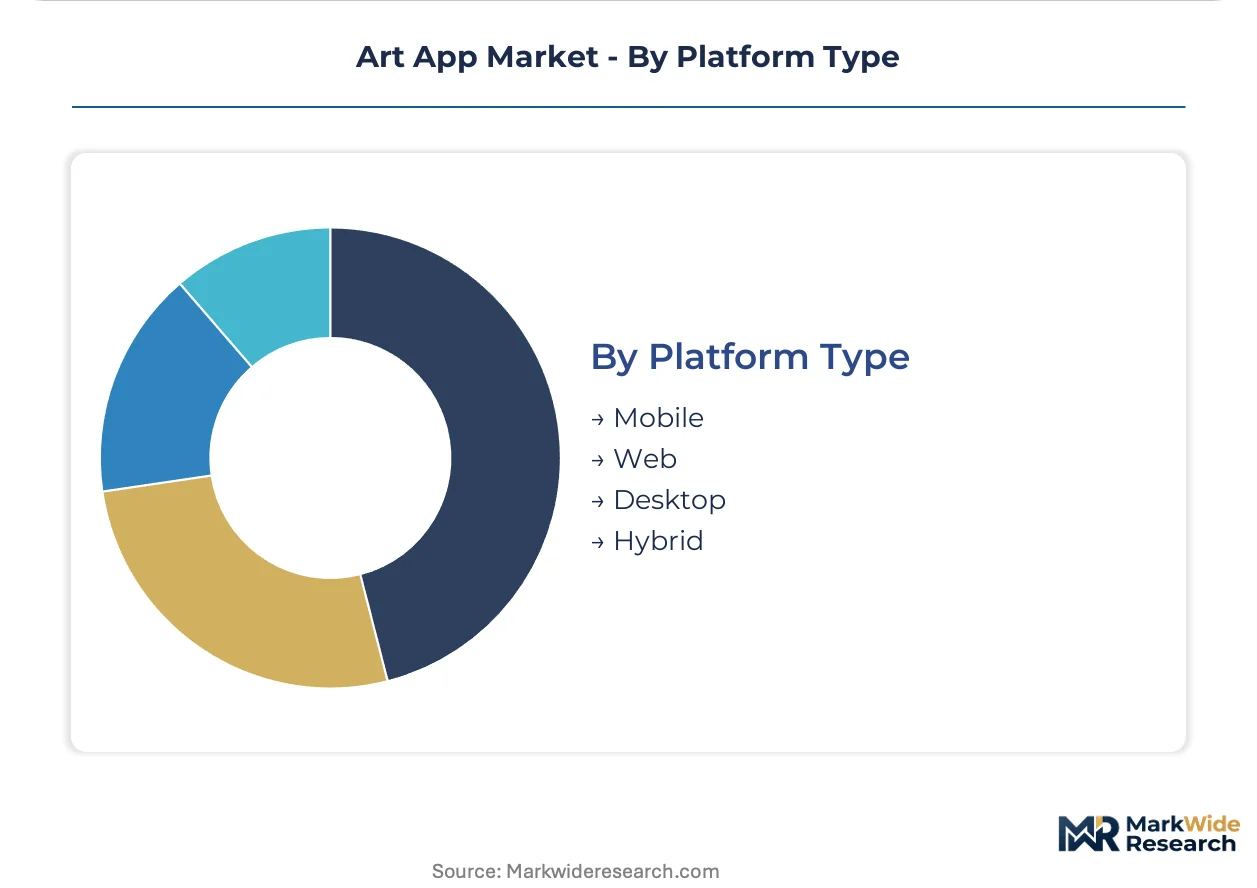
Platform Type:
Hardware-software integration depth and input precision requirements segment platform selection across use cases.
- Mobile:iOS and Android tablets with active stylus support enable complete production pipelines for freelance illustrators. Apple Pencil and Samsung S Pen proliferation across education and enterprise segments normalizes precision input expectations.
- Desktop:macOS and Windows retain premium pricing power for complex production pipelines requiring extensive RAM, GPU acceleration, and multi-monitor workflows. Color-critical output for print and broadcast maintains desktop centrality.
- Web:Browser-based tools lower installation friction and enable cross-device continuity, though feature depth lags native applications.
- Hybrid:Cloud-synced project files with seamless handoff between mobile sketching and desktop refinement serve professionals with variable work environments.
Mobile platforms lead download volume globally. Hybrid architectures are gaining share fastest among professionals seeking workflow flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Divergent AI disclosure mandates across Washington, Brussels, and Beijing are fragmenting compliance budgets and pushing art app developers toward jurisdictions with clearer regulatory cost structures. The United States retains the deepest creator economy infrastructure, while Asian markets scale mobile-first adoption fastest.
United States
Freelance illustrators and independent artists in California and New York drive premium subscription retention through mobile-first workflows that displace desktop dependency. FCC guidelines on digital platform transparency and COPPA compliance shape data collection practices and age-gating requirements for social features. Los Angeles and Austin clusters concentrate venture-backed generative AI startups racing to integrate diffusion models into creative pipelines.
Germany
Strong moral rights protections and copyright clarity around scraped visual content create legal exposure that slows generative feature deployment compared to other European markets. The EU AI Act imposes disclosure obligations that accelerate transparency dashboard development for compliant platforms. Berlin's creative technology sector anchors regional headquarters for art app vendors seeking German-speaking market penetration.
Japan
National education standards mandating digital creativity modules generate district-wide software licensing demand at scale across K-12 institutions. METI oversight of technology standards influences stylus latency benchmarks and GPU acceleration requirements for professional-grade tools. Tokyo and Osaka metropolitan areas concentrate the highest density of manga and anime production studios requiring pipeline-integrated illustration software.
South Korea
Computational art curricula adoption in public schools creates institutional procurement opportunities for vendors with localized language support and administrative controls. Webtoon production workflows drive demand for mobile-optimized raster tools with cloud-synced project files. Seoul's creator economy infrastructure supports the fastest-growing freelance illustrator base in Northeast Asia.
India
Vernacular illustration markets remain underdeveloped in platform payment systems and regional language support, creating first-mover advantages for localized art tools. The PLI scheme for electronics manufacturing indirectly supports stylus hardware proliferation across education and enterprise segments. Bengaluru and Mumbai clusters concentrate independent artists completing entire production pipelines on tablets.
Art App Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with ecosystem-integrated suites commanding professional workflows and standalone tools capturing mobile-first freelancers. The vendor base concentrates around three strategic archetypes: cloud-anchored creative suites, device-optimized native applications, and generative AI-first platforms. M&A activity targets on-device neural network capabilities and cross-platform rendering engines. Technology licensing partnerships accelerate feature parity in brush engines and layer management.
Within the ecosystem-integrated tier, Adobe represents the recurring-revenue archetype through Creative Cloud cross-selling across photography, video, and illustration workflows. Procreate exemplifies the device-optimized specialist position with perpetual license success on iPad hardware. NightCafe occupies a generative AI-native position competing on speed and style diversity rather than manual tool depth. These three anchors illustrate how divergent monetization philosophies—subscription, ownership, and credit-based—coexist by serving distinct creator workflow preferences.
| Leading Market Players |
|---|
| Affinity |
| NightCafe |
| Adobe |
| Prisma |
| ArtRage |
| Procreate |
| Clip Studio Paint |
| Artbreeder |
| Corel |
| Others |
Value Chain & Pricing Dynamics
Subscription-perpetual license divergence between Adobe's recurring SaaS tiers and Procreate's one-time purchase model manifests in divergent margin structures and cloud infrastructure dependencies. Premium subscription vendors absorb GPU inference costs for generative features within recurring fees, while perpetual license developers face compressed upgrade cycles to fund neural network R&D.
Pricing Analysis
Direct-to-creator sales bypass distributor markups entirely, compressing channel costs to payment processing fees alone. Subscription tiers stratify across professional, student, and hobbyist levels with feature gating tied to cloud storage allocation and generative credit budgets. Pricing pressure stems from compute cost volatility for real-time AI inference, particularly affecting freemium vendors subsidizing GPU-heavy features. Hobbyist segments exhibit highest price sensitivity, driving demand for perpetual licenses and credit-based microtransactions in emerging markets.
Supply Chain Analysis
Returns and refund flows remain minimal given digital delivery, though chargeback processing for subscription disputes creates administrative overhead concentrated in United States and European payment processors. Core supply dependencies center on Taiwan and South Korea for GPU semiconductor fabrication, China for rare earth magnet components in active stylus hardware, and Ireland and Singapore for cloud infrastructure hosting. Single-source vulnerability concentrates in NVIDIA's data center GPU allocation, with allocation rationing forcing vendors to tier generative feature access. Distribution runs through platform-native app stores with 15-30% revenue share extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between Brussels' EU AI Act disclosure mandates and Washington's lighter-touch FCC guidelines creates cost-differential opportunities for vendors structuring European compliance as premium transparency features while deploying stripped-down versions elsewhere.
For Market Incumbents: Anticipate generative AI-native entrants eroding manual tool differentiation by embedding diffusion models as default layer types. Defend installed base through vertical integration into stylus hardware partnerships and exclusive GPU allocation agreements with cloud providers. Prioritize C2PA metadata embedding to convert EU AI Act compliance into competitive moat against opaque competitors. For New Entrants and Emerging Players: Education procurement channels in South Korea and Japan offer lowest competitive density against established vendors. Target vernacular illustration markets in India with regional language UI layers and local payment gateway integration. Pursue white-label licensing to hardware OEMs seeking bundled creative software for tablet launches. For Investors and Strategic Acquirers: Consolidation pressure builds where on-device neural network optimization talent concentrates in San Francisco and Tel Aviv clusters. Long-term viability favors vendors with hybrid monetization flexibility across subscription, perpetual, and credit-based models. Monitor GPU allocation contract renewals as inflection signal for generative feature scalability.| Strategic Initiative | Industry Significance |
|---|---|
| On-Device Neural Network Optimization | Reduces cloud inference costs for real-time brush prediction on Apple Silicon and Snapdragon platforms. |
| Regional Language Localization | Unlocks vernacular creator markets in India and Southeast Asia with payment infrastructure integration. |
| Stylus Hardware Partnership | Secures latency-optimized input precision through exclusive Apple Pencil and Samsung S Pen calibration. |
| C2PA Metadata Embedding | Satisfies EU AI Act provenance requirements while differentiating against non-compliant generative competitors. |
| Educational Institution Licensing | Captures district-wide deployments in South Korea and Japan with administrative control dashboards. |
Study Parameters
Direct dialogue with product managers at creative software vendors, procurement leads at K-12 district technology offices, and freelance illustrator community organizers grounded qualitative findings in workflow-specific pain points. Secondary validation drew from App Store and Google Play revenue estimates, SEC 10-K filings for publicly traded creative software parents, and EU regulatory disclosure databases. Bottom-up triangulation across individual app revenue models converged with top-down market sizing from platform ecosystem reports.
Top-down demand modeling assessed installed base expansion across mobile and desktop platforms, while bottom-up analysis aggregated pricing tier distributions and conversion rate assumptions. Segmentation dimensions included application type, target user archetype, monetization model, and platform deployment pattern. CAGRs derived from fitted growth curves against historical download velocity and professional user retention benchmarks. Forecast inputs incorporated stylus hardware shipment projections and GPU availability constraints for generative feature scaling.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to training data licensing litigation outcomes and divergent AI disclosure regulations across Washington, Brussels, and Beijing. Practitioners should monitor GPU allocation contract renewals and C2PA standard adoption rates for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Global Virtual Goods Market
Digital Media
Global Streaming Media Device Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Digital Media Production Software Market
Digital Media
Information Short Video Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
Playout Solutions Market
Digital Media
Africa Animation Market
Digital Media
Video Content Management Market
Digital Media
Europe Anime Merchandising Market
Digital Media
Video Production Market
Digital Media
Media Coding Service Market
Digital Media
Photography Services Market
Digital Media
Middle East Media and Entertainment Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market