
 Digital Music Content Market | 2026-2036
Digital Music Content Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Music Content Market Intelligence
The unbundling of albums into single-track streams, followed by the re-bundling of access into all-you-can-eat subscriptions, is restructuring consumer purchasing behavior. Spotify leverages its powerful recommendation algorithms to maintain user engagement and drive discovery. Apple Music differentiates through deep integration with its hardware ecosystem, creating a seamless user experience. Meanwhile, QQ Music dominates the Chinese market by embedding social features and securing exclusive content rights from popular artists.
Digital music content comprises audio files, typically encoded in compressed formats like AAC or lossless ones such as FLAC, for network-based distribution. Its primary purpose is to grant users on-demand access to a vast library of sound recordings for personal listening. While the subscription business model now generates the bulk of revenue, the advertising-supported freemium tier remains critical for user acquisition. Smartphones continue to be the principal user device, but the adoption of smart speakers is creating new listening contexts within home environments.
Regulatory frameworks such as the EU's GDPR impose strict rules on user data processing for personalization, impacting platform operations. In parallel, content licensing and censorship rules enforced by bodies like China's SAMR dictate market access and library availability. Navigating the evolving debate around artist royalty payments from streaming platforms will be a defining challenge for all stakeholders.
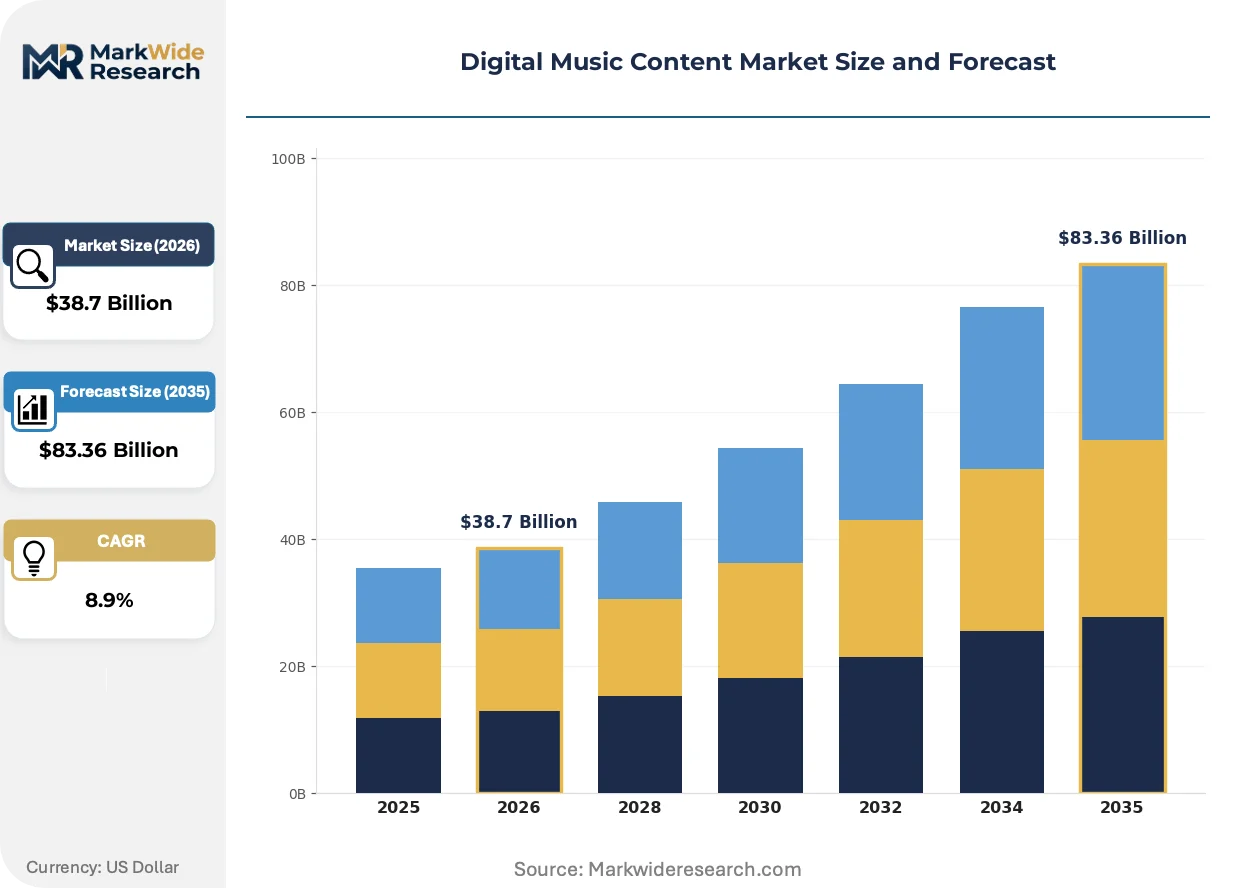
Market Dynamics
The fundamental market dynamic is the architectural shift from content ownership to on-demand access, governed by algorithmic curation. This transition redefines value away from the individual music track and towards the platform's ability to successfully predict and influence user listening habits within vast, licensed libraries.
Growth Catalysts
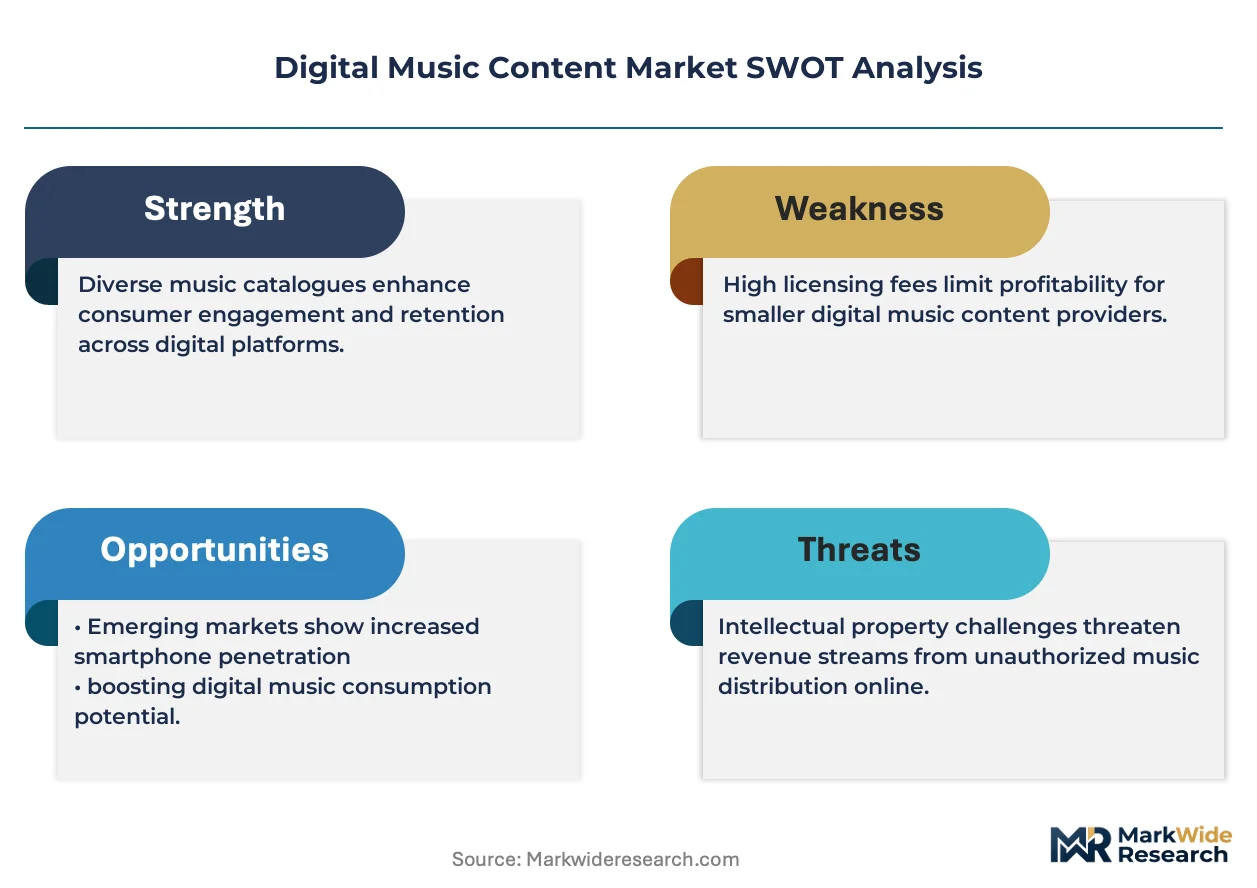
- AI-Driven Personalization:Advanced machine learning algorithms that analyze user behavior are enhancing content discovery and increasing engagement time, which directly supports subscriber retention and ad-based revenue models.
- Mobile Internet Expansion in India:The rapid proliferation of affordable mobile data and smartphones across India's large, young population creates a massive new addressable audience for streaming services.
- Connected Car Integration:The embedding of music streaming applications directly into vehicle infotainment systems provides a seamless, high-engagement listening context, opening a new frontier for subscription growth.
Market Restraints
- Data Privacy Regulation:Frameworks like the EU's GDPR impose significant compliance costs and limit the ways platforms can use personal data for the recommendation algorithms that are core to their business model.
- Complex Licensing Landscape:Securing global rights for music catalogs is exceptionally complex and costly, with rights often fragmented across numerous publishers, labels, and collecting societies, creating high barriers to entry.
- Content Censorship and Control:Government bodies, such as China's SAMR, enforce strict content regulations and censorship rules that can limit library availability and dictate operational terms for platforms in key markets.
Strategic Opportunities
- Interactive and Immersive Formats:The convergence of digital music with augmented reality and virtual reality technologies opens opportunities for creating interactive music videos, virtual concerts, and immersive fan experiences.
- Wellness and Functional Audio:There is a significant opportunity in developing curated audio content for non-entertainment purposes, such as focus, meditation, and sleep, targeting the corporate wellness and personal health markets.
- Expansion in Sub-Saharan Africa:As mobile connectivity and payment infrastructure improve, markets across Sub-Saharan Africa represent a substantial, underpenetrated region for future user acquisition and growth.
Industry Challenges
- Equitable Royalty Distribution:Devising and implementing a transparent and fair royalty payment system that equitably compensates artists, songwriters, and rights holders in the streaming era remains a persistent and contentious industry challenge. *Combating Digital Piracy: Despite the dominance of legal streaming, the unauthorized distribution and downloading of copyrighted music continues to siphon revenue and requires constant investment in anti-piracy technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Music Content Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $83.36 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Streaming, Downloads, Podcasts, Audiobooks Business Model: Subscription, Freemium, Advertising-Supported, Pay-Per-Download User Device: Smartphones, PCs, Tablets, Smart Speakers, Wearables Listener Demographic: Teens, Young Adults, Adults, Seniors |
| Companies Covered | YouTube Music, Deezer, Spotify, SoundCloud, QQ Music, Apple Music, TIDAL, TuneCore, Amazon Music, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Music Content Market Strategic Shifts & Innovations
The digital music landscape is being redefined by the dual forces of AI-driven content creation and tightening regulatory oversight on algorithmic systems. These trends are creating a more complex operational environment where technological innovation must be balanced with new compliance and transparency demands.
Generative AI for music composition is a notable technological evolution. This technology creates novel audio tracks and soundscapes for use in advertising, social media content, and as functional background music. Content platforms and independent creators are adopting it to produce royalty-free audio at scale. This development is automating the creation of generic and mood-based audio, which compresses the value proposition of traditional stock music libraries.
Regulatory scrutiny of algorithmic transparency is intensifying, exemplified by the EU AI Act. The regulation mandates that high-risk AI systems, including those used for content personalization on major platforms, adhere to strict transparency and risk management protocols. Digital music services operating within the European Union are most affected, as they must now audit their recommendation engines and potentially alter how they surface content to users to ensure compliance.
A significant behavioral shift is occurring as listeners move from solitary consumption to socially connected music experiences. This disrupts the traditional on-demand model, compelling platforms to integrate features like collaborative playlists, shared listening sessions, and artist-fan interactions. This trend is most pronounced in markets with high social media engagement, particularly among younger user segments in Asia-Pacific and North America.
Digital Music Content Market Segmentation
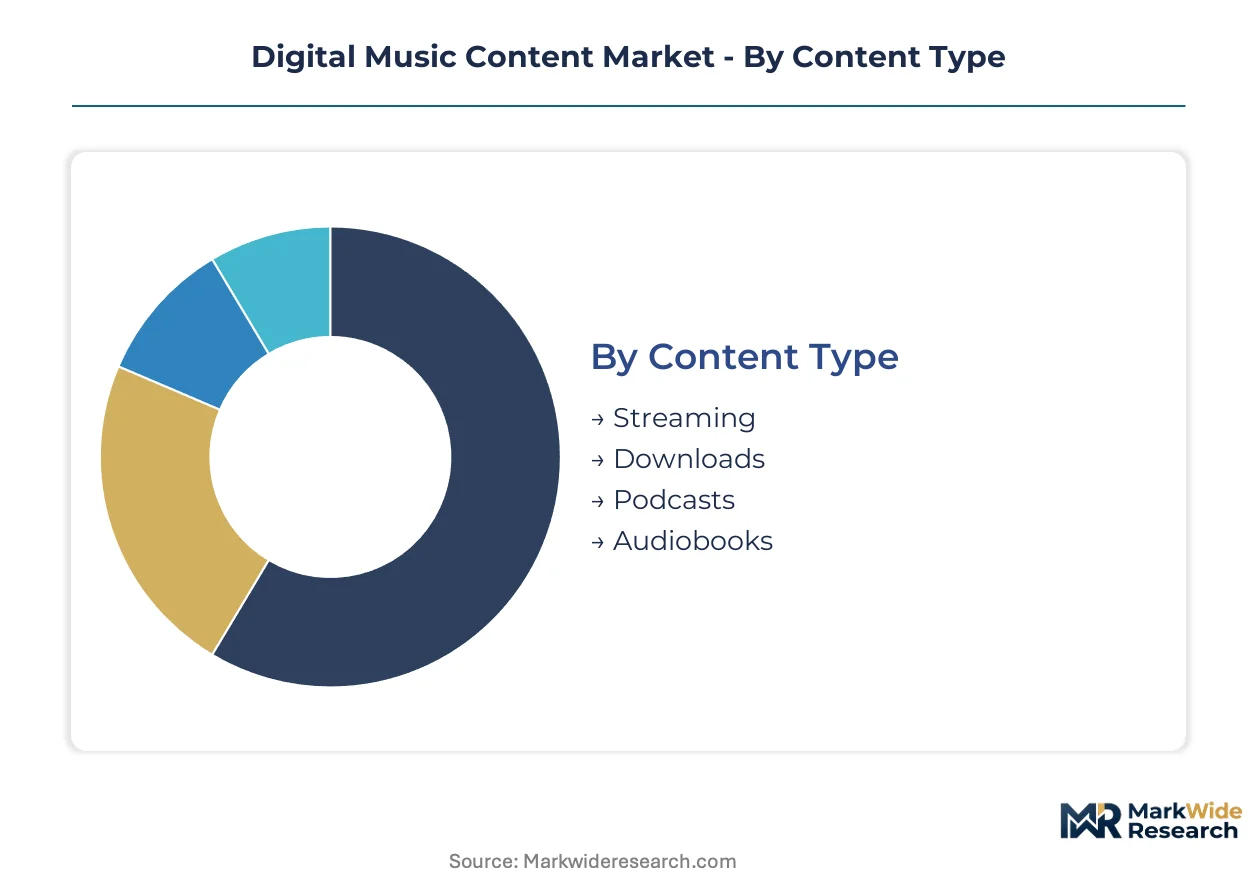
The digital music content market segments across multiple dimensions, reflecting diverse consumption habits, revenue generation strategies, and technological interfaces. Understanding these distinct segments allows platforms to tailor content offerings and monetization models effectively for specific user groups.
Content Type:
The customization versus standardization spectrum defines content type segmentation, ranging from highly personalized playlists to widely distributed album releases.
- Streaming:This segment encompasses on-demand access to vast music libraries, typically delivered via internet connection, offering convenience and broad selection. Demand concentrates in India, driven by expanding mobile internet access and a large youth demographic.
- Downloads:This segment involves purchasing and owning digital audio files, allowing for offline access without ongoing subscription fees. Demand remains significant in markets where internet connectivity is inconsistent or data costs are high, such as parts of Sub-Saharan Africa.
- Podcasts:This category includes episodic audio programs, often conversational or narrative, available for subscription and download.
- Audiobooks:This segment comprises spoken-word recordings of books, providing an alternative format for literary consumption.
Leading the category by volume: Streaming. Growing fastest: Podcasts.
Business Model:
The cost tiering of access characterizes the business model segmentation, from free ad-supported tiers to premium, ad-free subscriptions.
- Subscription:Users pay a recurring fee for unlimited, ad-free access to a platform's entire music catalog, forming the bulk of current market revenue. This model thrives in developed economies like the United States and European Union, where consumers prioritize convenience and ad-free listening.
- Freemium:This model offers basic services for free, typically ad-supported with limited features, while charging a premium for enhanced functionalities. It serves as a critical user acquisition funnel, particularly in emerging markets such as Brazil and Indonesia.
- Advertising-Supported:This segment generates revenue through advertisements played before or during content, providing free access to users.
- Pay-Per-Download:Consumers purchase individual tracks or albums outright, retaining permanent ownership of the digital files.
Subscription models currently capture the largest revenue share. Freemium models are gaining share fastest.
User Device:
Device integration and user experience differentiate the user device segment, influencing content delivery and interaction modes.
- Smartphones:These mobile devices remain the primary conduit for digital music consumption globally, offering portability and integrated internet access. Their widespread adoption across China and India underpins significant user bases.
- Smart Speakers:Voice-activated devices provide convenient, hands-free music playback, primarily within home environments, integrating seamlessly into smart home ecosystems. Adoption is climbing the fastest in Western Europe and North America.
- PCs:Personal computers provide robust platforms for music management and consumption, often preferred for high-fidelity listening setups.
- Tablets:These portable devices offer a larger screen interface for music applications and are popular for casual home listening.
- Wearables:Smartwatches and other wearable technologies facilitate on-the-go music access, often synchronized with smartphones for playback.
Smartphones account for the highest volume of listening hours. Smart speakers are expanding most quickly.
Listener Demographic:
The distinct content preferences and engagement patterns of various age groups define listener demographic segmentation.
- Young Adults:This demographic (typically 18-34) drives trends in new music discovery and social sharing, heavily utilizing streaming services and interactive features. This group dominates user engagement across North America and Asia-Pacific.
- Adults:This segment (typically 35-54) often seeks curated playlists and high-fidelity audio, valuing convenience and established artists. This demographic contributes significantly to subscription revenues in markets like Germany and Japan.
- Teens:This demographic (13-17) exhibits high engagement with social media-integrated music experiences and short-form content.
- Seniors:This segment (55+) typically prefers familiar music and often accesses content through simpler interfaces or smart speakers.
Young Adults lead in content discovery and social engagement. Adults demonstrate the steepest expansion trajectory in subscription uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The digital music content market exhibits a clear divide between established consumption hubs and rapidly expanding user bases. While mature economies drive subscription revenue, emerging markets contribute significantly to user acquisition. This dynamic shapes investment and localization strategies across the industry.
India
Mobile internet expansion across India fuels significant demand for streaming services, particularly among the large youth demographic. The Telecom Regulatory Authority of India (TRAI) policies support affordable data access, fostering widespread smartphone use. Mumbai's vibrant entertainment industry serves as a major content creation and consumption hub for regional music.
China
Demand in China concentrates around socially integrated music experiences and exclusive content rights, primarily through local platforms. The State Administration for Market Regulation (SAMR) enforces strict content censorship and licensing rules, dictating market access. Beijing's technology sector drives innovation in social features and platform development for local services.
United States
Established subscription models underpin robust demand for premium digital music access in the United States, driven by consumer preference for ad-free listening. The Federal Trade Commission (FTC) oversees data privacy and consumer protection, influencing platform operations and user data usage. Los Angeles remains a global center for music production and artist management, shaping content trends.
Germany
High-fidelity audio preferences and strong purchasing power characterize digital music demand in Germany, supporting a mature subscription market. European Union's General Data Protection Regulation (GDPR) mandates strict data processing rules for personalization algorithms, impacting platform operations. Berlin's thriving creative tech scene fosters new music startups and platform innovations.
Brazil
Freemium models drive user acquisition and engagement among Brazil's large, young population, offering accessible entry points to digital music. The Lei Geral de Proteção de Dados (LGPD) governs personal data use, impacting recommendation systems and platform compliance. São Paulo, as a major economic and cultural hub, concentrates both content creators and digital music consumers.
Digital Music Content Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered market structure. This landscape includes large technology companies leveraging existing hardware and software ecosystems, alongside dedicated music streaming platforms. Strategic archetypes span ecosystem integrators, content aggregators emphasizing vast libraries, and social engagement specialists driving interactive features. Geographic expansion into emerging markets and portfolio diversification through new audio formats represent dominant competitive moves.
Ecosystem integrators like Apple Music exemplify platforms that differentiate through deep hardware and software synergy, providing a seamless user experience within their proprietary environments. Streaming pure-plays such as Spotify anchor the market with powerful recommendation algorithms and extensive content catalogs, driving global user engagement and discovery. Meanwhile, QQ Music, a Tencent-owned entity, occupies a strong position in the Chinese market by emphasizing social features, exclusive local content rights, and integration with broader social media platforms. These players continually adapt their strategies to evolving user preferences and regional regulatory landscapes.
| Leading Market Players |
|---|
| YouTube Music |
| Deezer |
| Spotify |
| SoundCloud |
| QQ Music |
| Apple Music |
| TIDAL |
| TuneCore |
| Amazon Music |
| Others |
Cost & Logistics Intelligence
Connected car manufacturers increasingly integrate streaming services, influencing long-term licensing agreements and tiered subscription pricing structures. This concentration of demand shapes how platforms negotiate content access and user experience.
Pricing Analysis
Pricing pressure intensifies on subscription models as freemium tiers expand user acquisition in emerging markets. The dominant pricing structure remains subscription-based, offering ad-free access and superior audio quality. Price differentiation stems from content exclusivity, such as early album releases, and deep hardware integration. Young adults often exhibit higher price sensitivity compared to adults in developed economies who prioritize convenience and ad-free listening.
Supply Chain Analysis
Reverse logistics in digital music primarily involves content removal due to expired licenses or regulatory mandates, requiring platforms to manage vast digital libraries. Content supply concentrates in major music production hubs like the United States and global rights holders. The chain relies on licensed sound recordings and robust data infrastructure. A key risk is the complex global licensing landscape, which creates high barriers to entry. Distribution runs through direct-to-consumer streaming applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital music content market is a vertical-integration race, with platforms pursuing direct artist relationships and exclusive content rights. This strategy aims to control content supply and differentiate offerings in a competitive landscape.
For Market Incumbents:Anchor existing user bases by continuously enhancing AI-driven personalization algorithms and expanding into adjacent audio formats like podcasts. Incumbents face threats from generative AI content reducing reliance on traditional music and intensifying regulatory scrutiny from bodies like the EU AI Act. Deepening hardware ecosystem integration and fostering unique social features provide crucial differentiation. This ensures continued user engagement.
For New Entrants and Emerging Players:Enter via niche content segments like wellness audio or interactive immersive formats leveraging AR/VR technologies. Sub-Saharan Africa represents a penetrable geography due to improving mobile connectivity and payment infrastructure. A creator-centric platform model, emphasizing direct artist compensation and unique fan engagement, offers a distinct go-to-market angle. This approach circumvents established licensing complexities.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers targeting technology providers specializing in AI-driven audio processing or platforms with strong regional content rights. Digital consumption is projected for continued growth over the next decade, making this market attractive. Acquisition targets include developers of interactive music experiences. Practitioners should monitor shifts in content licensing models and new data privacy regulations for early signals of market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Recommendation Engine Development | Enhances user engagement and content discovery for streaming platforms. |
| Exclusive Content Licensing | Differentiates platforms and attracts subscribers in competitive markets like China. |
| Connected Car Integration | Expands listening contexts and secures new subscription growth channels. |
| Wellness Audio Portfolio Expansion | Captures new market segments beyond entertainment, such as corporate wellness. |
| AR/VR Immersive Experience Creation | Attracts younger demographics and creates interactive fan engagement. |
Research Approach
Document review covered regulatory filings from TRAI, SAMR, and FTC, complemented by interviews with platform executives, content rights holders, and music industry analysts. This primary research was triangulated with secondary sources such as industry association reports and academic research on AI algorithms. A bottom-up approach validated market sizing against top-down industry trends.
Volume and value outputs were generated through a multi-variable regression analysis and scenario modeling across the analysis window. The model segmented by content type, business model, user device, listener demographic, and regional market maturity. Compound annual growth rates were derived from historical performance and projected forward based on identified catalysts. Key forecast inputs included mobile internet penetration rates and smartphone adoption figures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical events or rapid consumer shifts. The forecasts reflect assumptions regarding technological innovation and regulatory stability. Practitioners should monitor content licensing and AI regulation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Anime Merchandising Market
Digital Media
Video Wall Market
Digital Media
Digital Video Advertising Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
Latin America Inflight Entertainment and Connectivity Market
Digital Media
Secondary Ticket Market
Digital Media
Wedding Photography Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Digital Effects Services Market
Digital Media
US Automatic Content Recognition Market
Digital Media
Art App Market
Digital Media
Global Stock Video Market
Digital Media
Blockchain in Media and Entertainment Market
Digital Media
Digital Content Locker Market
Digital Media
North America Online Gambling Market
Digital Media
United Kingdom Webtoons Market