
 Electric Motorcycles and Scooters Market | 2026-2036
Electric Motorcycles and Scooters Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Motorcycles and Scooters Market Analysis
Chinese battery pack production is consolidating around vertically integrated suppliers serving the electric two-wheeler value chain. Yadea leverages captive lithium-ion cell sourcing to sustain cost leadership across mass-market scooter segments. Hero MotoCorp anchors its position through deep distribution networks spanning tier-two and tier-three Indian cities. NIU Technologies differentiates via IoT-enabled fleet management platforms that appeal to European delivery operators.
Electric motorcycles and scooters are battery-powered two-wheel vehicles utilizing brushless DC hub motors or mid-drive configurations, with energy densities typically ranging from 40 to 70 watt-hours per kilogram in mainstream lithium-ion packs, designed primarily for urban commuting and last-mile logistics. The product type dimension shows scooters occupying dominant volume share due to lower price points and urban maneuverability, while motorcycles capture disproportionate margin pools through premium positioning and higher motor outputs. Battery type segmentation reveals lithium-ion chemistry leading across all major markets as lead acid faces phase-out pressure from energy density regulations and total cost-of-ownership calculations.
FAME II directives from India's Ministry of Heavy Industries mandate localized battery assembly, reshaping supplier qualification requirements for OEMs targeting subsidy eligibility. EMA type-approval frameworks and EU CO2 fleet standards constrain powertrain specifications for models sold across member states, effectively filtering non-compliant imports from price-sensitive entrants. Stakeholders must monitor evolving battery passport requirements and charging interoperability mandates that will determine market access thresholds before the decade closes.
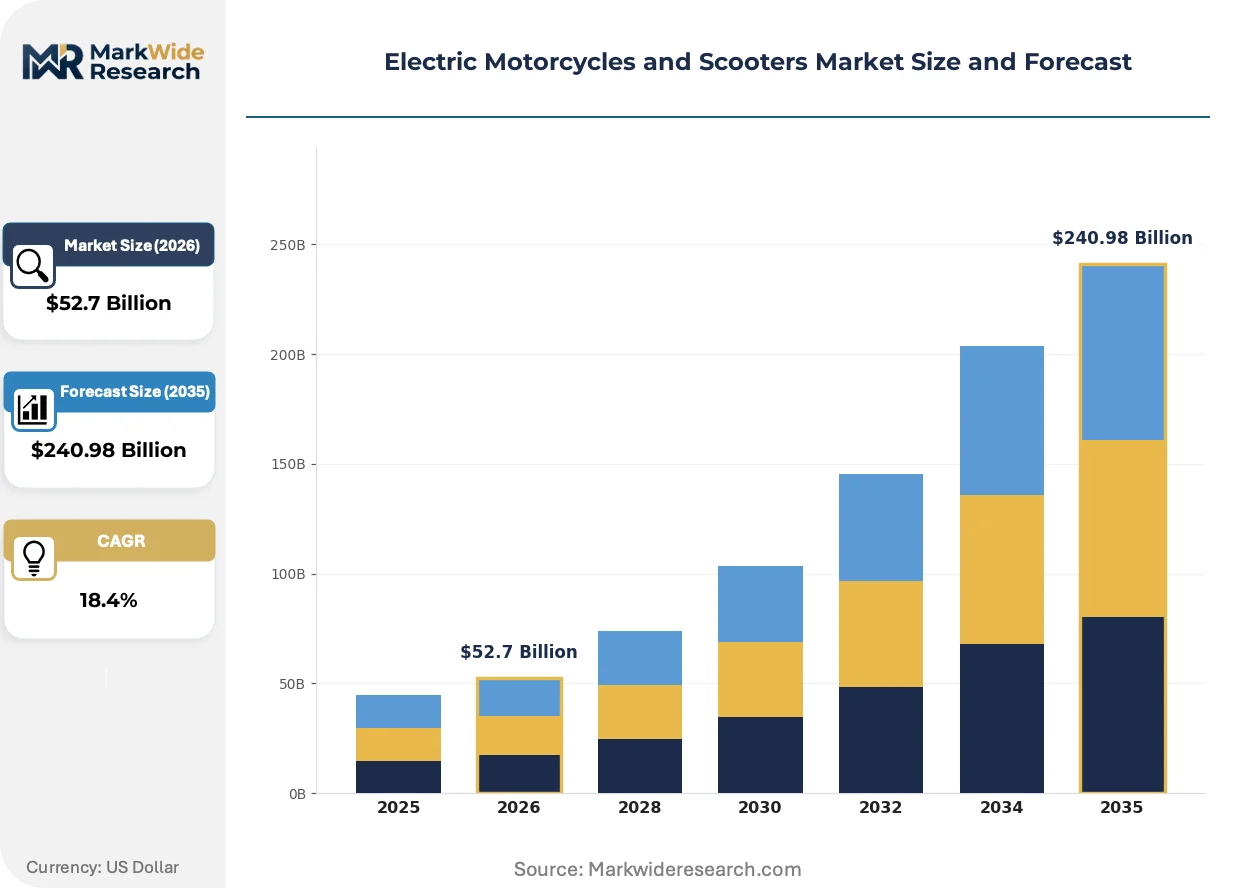
Market Dynamics
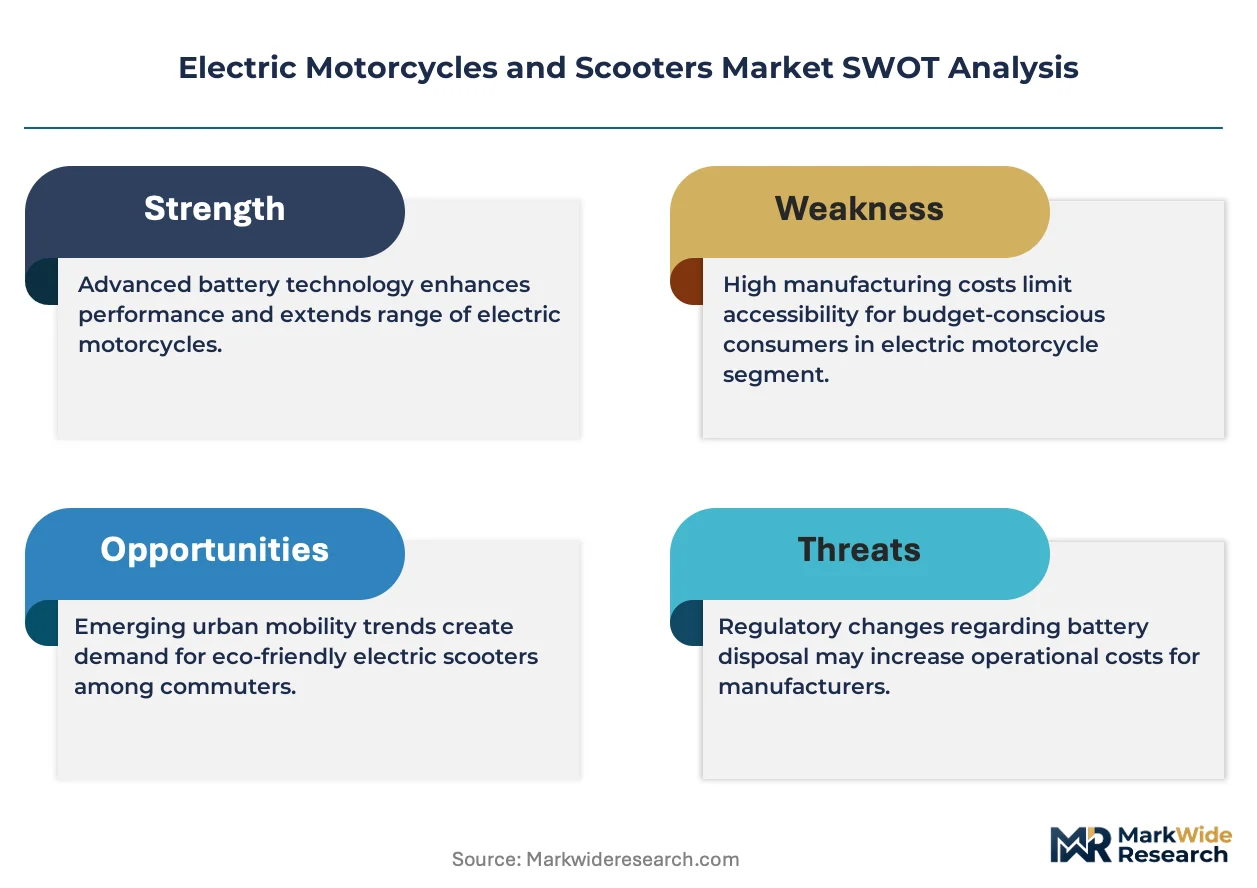
Battery chemistry standardization around lithium-ion phosphate and nickel-manganese-cobalt variants is compressing cost curves faster than motor efficiency gains, forcing incumbent OEMs to requalify supplier bases or lose subsidy access in key procurement markets.
Growth Catalysts
- FAME II localization mandates:India's Ministry of Heavy Industries requires domestic battery assembly for incentive eligibility, redirecting OEM sourcing toward qualified domestic pack producers.
- Last-mile fleet electrification:Southeast Asian logistics operators are replacing petrol two-wheelers with electric scooters to reduce fuel volatility exposure and meet corporate carbon commitments.
- EU CO2 fleet standards:Tightening emissions ceilings for light vehicles are compelling European manufacturers to accelerate electric motorcycle development or face penalty structures.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings in cathode precursor markets destabilize cell pricing forecasts and compress OEM margin visibility across production cycles.
- Charging infrastructure gap:Urban density constraints in Indonesian and Vietnamese megacities limit residential charging penetration, constraining addressable demand for pure-electric models.
- Lead-acid residual supply chains:Established recycling networks and replacement part ecosystems for legacy chemistries create friction against full lithium-ion transition in price-sensitive segments.
Strategic Opportunities
- Philippines archipelago logistics:Island-hopping delivery networks present untapped demand for swappable-battery scooter configurations with modular charging infrastructure.
- Battery passport compliance:Upcoming EU traceability requirements will favor early-adopter OEMs with digitized supply chain documentation and cell provenance systems.
- Interoperable charging protocols:Standardized connector and communication specifications across ASEAN markets would unlock cross-border fleet operations and reduce operator switching costs.
Industry Challenges
- Power electronics engineering shortage:Brushless DC motor controller design and thermal management expertise remains concentrated among tier-one automotive suppliers, limiting in-house development capabilities for emerging OEMs.
- EMA type-approval timelines:European certification procedures for electric two-wheelers extend product launch cycles by 12-18 months, delaying revenue recognition for new market entrants.
- Pack thermal runaway testing:Expanded UN 38.3 and UL 2271 validation requirements for lithium-ion systems add capital intensity to product development programs without differentiation value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Motorcycles and Scooters Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $240.98 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorcycles, Scooters, E-bikes, Mopeds End User: Individual Consumers, Fleet Operators, Delivery Services, Rentals Battery Type: Lithium-Ion, Lead Acid, Nickel Metal Hydride, Solid-State Charging Infrastructure: Home Charging, Public Charging Stations, Fast Chargers, Wireless Charging |
| Companies Covered | Ola Electric, Yadea, Hero MotoCorp, NIU Technologies, Zero Motorcycles, BMW Motorrad, Honda Motor, Gogoro, Ather Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Motorcycles and Scooters Market Emerging Trajectories
Intelligent connectivity layers are transforming electric two-wheelers from commodity hardware into data-generating fleet assets, rewiring competitive advantage toward software-defined functionality and predictive maintenance capabilities.
Solid-state battery research is converging with electric motorcycle applications as energy density targets exceed 300 watt-hours per kilogram. Premium European manufacturers are piloting sulfide-electrolyte cells for 2027 model year releases. This chemistry transition is converging with existing thermal management investments to enable faster charging protocols without pack degradation penalties.
EU battery passport regulations under the Ecodesign for Sustainable Products Framework will mandate digital product documentation from 2027. Cell origin tracking and carbon footprint disclosure requirements will filter non-compliant imports from Southeast Asian supply chains. Motorcycle OEMs targeting European distribution are pre-emptively restructuring supplier qualification procedures to capture first-mover certification status.
Fleet operators are consolidating procurement around total-cost-of-ownership metrics rather than upfront vehicle pricing. Leasing and battery-as-a-service models are displacing traditional ownership in Indian and Vietnamese urban delivery segments. This shift is most pronounced in Bangalore and Ho Chi Minh City, where logistics platforms negotiate multi-year service contracts bundling vehicles, energy, and maintenance into per-kilometer rates.
Electric Motorcycles and Scooters Market Segmentation
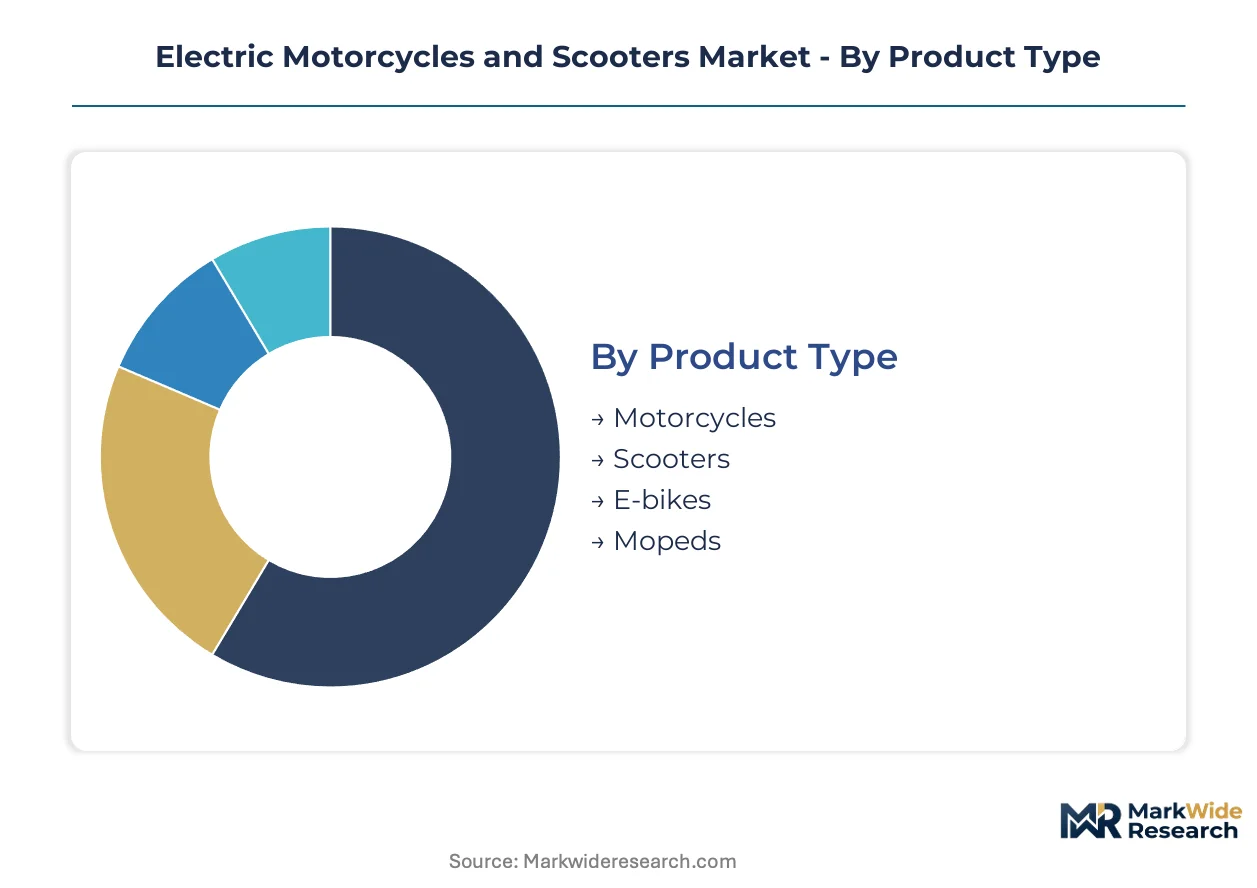
Segmentation in electric two-wheelers reveals how technical specifications, use patterns, and energy infrastructure create distinct competitive arenas. Each axis carries different margin structures and regulatory exposure.
Product Type:
Hub motor placement, frame geometry, and power output specifications define four distinct vehicle architectures with divergent cost curves and certification requirements.
- Scooters:Step-through frames with brushless DC hub motors rated 1-4kW dominate urban density corridors. Vietnam and Indonesia concentrate volume demand for sub-1500 USD models where maneuverability trumps range.
- Motorcycles:Mid-drive motor configurations with 5-15kW outputs target premium positioning through higher top speeds and highway capability. European EMA type-approval compliance adds certification overhead that filters mass-market entrants.
- E-bikes:Pedal-assist systems with 250-750W motors face lighter regulatory burdens in most jurisdictions. Last-mile delivery platforms in Indian tier-two cities favor these for license-exempt operation.
- Mopeds:Restricted-speed variants with 50cc-equivalent performance thresholds capture residual demand from legacy internal combustion transition markets.
Scooters lead on scale; motorcycles lead on momentum.
End User:
Purchase behavior, utilization intensity, and total-cost-of-ownership calculation methods diverge sharply across customer categories.
- Fleet Operators:Logistics platforms negotiating multi-year service contracts in Ho Chi Minh City and Bangalore prioritize per-kilometer operating cost over capital expenditure. Battery-as-a-service bundling is displacing outright ownership.
- Individual Consumers:Residential charging access and subsidy eligibility drive purchase decisions in Indian and Southeast Asian urban corridors. FAME II incentive structures redirect demand toward qualified domestic assembly models.
- Delivery Services:Food and parcel platforms with 200-300km daily duty cycles require swappable-battery configurations. Philippines archipelago operations present untapped demand for modular charging infrastructure.
- Rentals:Short-term mobility providers in European city centers emphasize IoT-enabled fleet management and predictive maintenance capabilities.
Fleet operators lead on scale; delivery services lead on momentum.
Battery Type:
Cell chemistry determines energy density, thermal management requirements, and regulatory compliance pathways across production cycles.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate variants at 40-70 watt-hours per kilogram dominate mainstream production. India's FAME II localization mandates are redirecting OEM sourcing toward qualified domestic pack producers.
- Solid-State:Sulfide-electrolyte research targets 300+ watt-hours per kilogram for premium European motorcycle releases. Thermal management investments converge with faster charging protocols.
- Lead Acid:Legacy chemistry faces phase-out pressure from energy density regulations and total cost-of-ownership calculations. Established recycling networks create friction against full transition in price-sensitive segments.
- Nickel Metal Hydride:Intermediate chemistry retains niche applications where temperature stability outweighs energy density priorities.
Lithium-Ion leads on scale; solid-state leads on momentum.
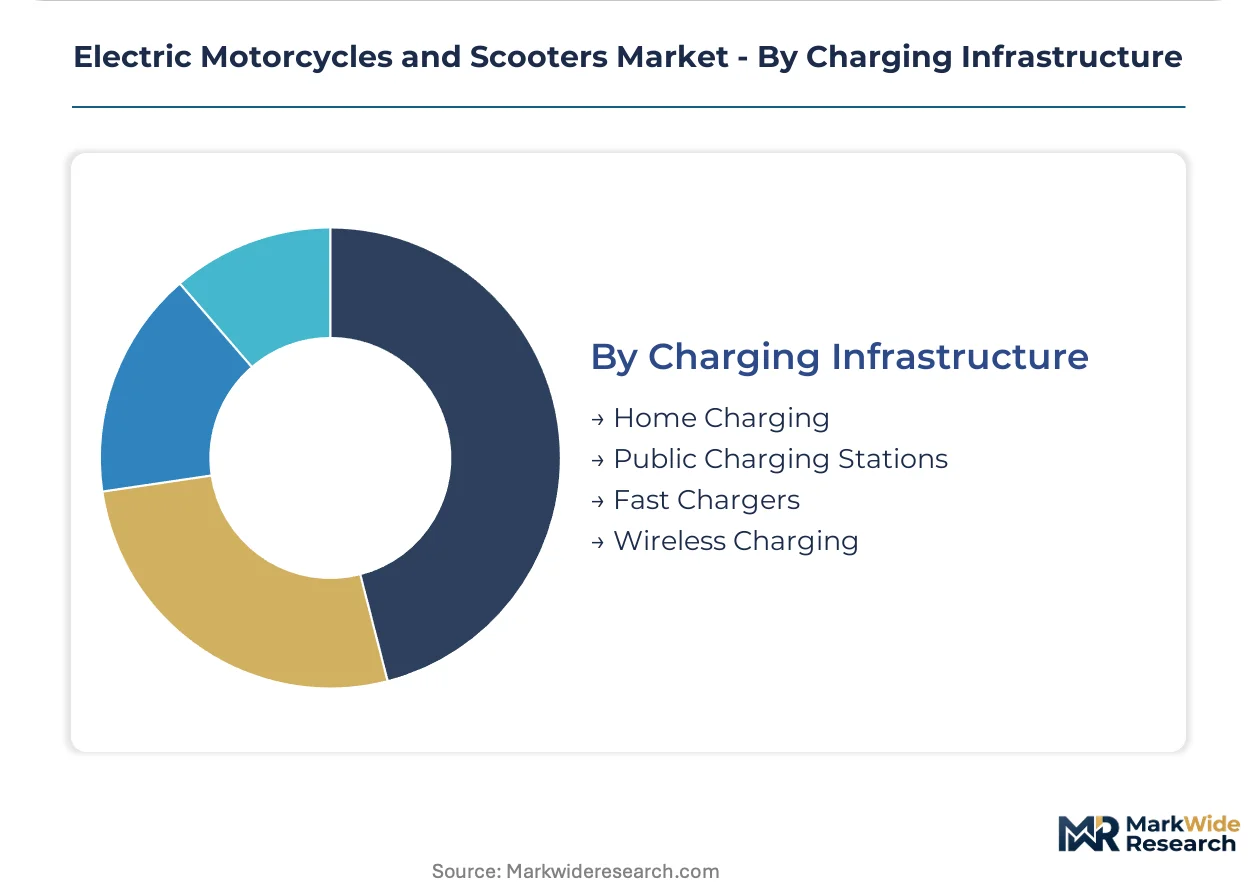
Charging Infrastructure:
Power delivery speed, installation capital, and grid interaction requirements segment the energy replenishment landscape.
- Home Charging:Level 1 and Level 2 residential outlets serve individual consumers with overnight dwell time. Urban density constraints in Indonesian and Vietnamese megacities limit penetration rates.
- Public Charging Stations:Curbside and parking-integrated infrastructure targets fleet operators and rental users with predictable route patterns. EU interoperability mandates will determine market access thresholds.
- Fast Chargers:DC rapid charging at 50-150kW enables commercial fleet turnaround but requires substantial grid upgrade investment and thermal management in battery packs.
- Wireless Charging:Inductive pad systems pilot in premium European deployments where connector wear and vandalism risk offset capital cost premiums.
Home charging leads on scale; fast chargers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting battery pack assembly toward jurisdictions with localized subsidy qualification, while OEMs absorb compliance costs in markets with stringent type-approval frameworks. Production migration patterns track divergence between India's domestic content mandates and Europe's emissions ceilings.
India
FAME II localization requirements from the Ministry of Heavy Industries mandate domestic battery assembly for incentive eligibility, redirecting OEM procurement toward qualified pack producers. Bangalore and Delhi-NCR concentrate fleet operator demand where battery-as-a-service models displace outright ownership. Tier-two and tier-three cities anchor Hero MotoCorp's distribution density for mass-market scooter penetration.
Vietnam
Urban density corridors in Ho Chi Minh City and Hanoi drive demand for sub-1500 USD scooters where maneuverability trumps range specifications. The country's national transport regulator maintains 50cc-equivalent performance thresholds for license-exempt operation. VinFast's domestic manufacturing cluster in Haiphong supplies regional export demand with vertically integrated cell sourcing.
Indonesia
Jakarta's metropolitan congestion pricing trials accelerate fleet electrification commitments from last-mile logistics operators. The Ministry of Industry's electric vehicle roadmap targets two-wheeler conversion rates through import duty restructuring. Surabaya and Bandung emerging as secondary demand centers where residential charging penetration remains constrained by urban density limits.
Germany
EMA type-approval frameworks and EU CO2 fleet standards constrain powertrain specifications for models sold across member states, filtering non-compliant imports from price-sensitive entrants. BMW Motorrad anchors premium motorcycle development from Munich engineering centers. KBA certification timelines extend product launch cycles by 12-18 months, delaying revenue recognition for new market entrants.
United States
NHTSA safety standards and state-level ZEV mandates create bifurcated compliance pathways for motorcycle versus scooter classifications. California's Air Resources Board regulations influence national product planning for premium electric motorcycle releases. Zero Motorcycles occupies the performance-oriented segment from Santa Cruz engineering facilities targeting 2027 solid-state pilot programs.
Electric Motorcycles and Scooters Market Vendor Landscape
Chinese producers anchor the mass-market tier through captive lithium-ion supply and cost-optimized hub motor configurations; European and Japanese specialists hold premium positioning via EMA-compliant engineering and brand heritage. Market structure fragments across three strategic tiers: vertically integrated battery producers, distribution-heavy domestic champions, and connectivity-focused fleet solution providers. Dominant competitive moves include backward integration into cell sourcing and strategic partnerships for charging infrastructure deployment.
Among scale-driven fabricators, Yadea exemplifies captive supply chain control through in-house lithium-ion cell production. Hero MotoCorp represents distribution-density archetypes with tier-two and tier-three network penetration. NIU Technologies occupies the fleet-management tier through IoT-enabled platform differentiation for European delivery operators.
| Leading Market Players |
|---|
| Ola Electric |
| Yadea |
| Hero MotoCorp |
| NIU Technologies |
| Zero Motorcycles |
| BMW Motorrad |
| Honda Motor |
| Gogoro |
| Ather Energy |
| Others |
Supply Flow & Price Mechanics
Fleet operators in Southeast Asian logistics corridors anchor volume procurement through battery-as-a-service contracts, compressing upfront vehicle pricing into per-kilometer operating cost structures that reshape manufacturer margin capture.
Pricing Analysis
Distributor margins in tier-two Indian cities absorb FAME II subsidy pass-through obligations, while direct-to-fleet negotiations in Vietnam bypass traditional retail markups entirely. Pricing stratifies across premium EMA-compliant motorcycles, standard lithium-ion scooters, and economy lead-acid residual models. Cost compression in the economy tier stems from cathode precursor volatility, squeezing OEMs without captive cell sourcing. Individual consumers in Indonesian residential markets exhibit highest price sensitivity; European fleet operators demonstrate lowest sensitivity due to total-cost-of-ownership contracting.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cathode active material producers supplying NMC formulations for premium motorcycle packs. Cell assembly concentrates in China, South Korea, and India following FAME II localization mandates. Raw material dependencies span lithium carbonate from South American brine operations, nickel laterite from Indonesian smelters, and refined cobalt from Central African processing hubs. Tariff exposure on battery component imports into India threatens non-qualified OEM subsidy eligibility. Distribution runs through Hero MotoCorp's tier-three network density and NIU Technologies' direct fleet contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's FAME II localization mandates and EU battery passport requirements create compounding compliance barriers that filter marginal competitors and concentrate share among prepared incumbents.
For Market Incumbents: To counter emerging Chinese producers with captive lithium supply, anchor position through backward integration into domestic cell assembly qualifying for Indian subsidy access, while accelerating EMA type-approval pre-certification to capture European fleet procurement windows before passport mandates activate. For New Entrants and Emerging Players: Swappable-battery platform architecture offers the most penetrable wedge for Philippines archipelago logistics operators underserved by fixed-charging infrastructure, with go-to-market execution through island-hopping delivery consortiums negotiating modular energy service contracts. For Investors and Strategic Acquirers: Battery-as-a-service platform operators are the most active acquirer in this space, consolidating fleet management software with charging infrastructure assets. Long-term viability favors targets with digitized supply chain documentation enabling EU traceability compliance. Watch for solid-state pilot program announcements from European motorcycle OEMs as inflection signal for chemistry transition capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive lithium-ion cell sourcing insulates Yadea from cathode price volatility in mass-market segments. |
| Charging Infrastructure Partnership | Gogoro's swappable network deployment in Philippines archipelago unlocks island-hopping fleet operations. |
| Software-Defined Vehicle Investment | NIU Technologies' IoT platform differentiation commands premium positioning among European delivery operators. |
| Geographic Manufacturing Footprint | VinFast's Haiphong cluster qualifies for FAME II subsidy access while serving regional export demand. |
| Platform Standardization | Interoperable ASEAN charging protocols would reduce operator switching costs and unlock cross-border fleet procurement. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, fleet procurement managers at Southeast Asian logistics operators, battery pack assembly plant managers, and regulatory affairs leads at type-approval consultancies with secondary validation against UN 38.3 testing registries, EMA homologation databases, FAME II subsidy disbursement records, and customs trade data for lithium-ion cell imports. Bottom-up vehicle production estimates and top-down energy density deployment calculations were triangulated against regional registration databases.
Segment-weighting applied product type, battery chemistry, end-user category, and charging infrastructure access as primary dimensions across the projection horizon. CAGRs were derived from fitted growth curves incorporating FAME II subsidy phase-out schedules, EU CO2 fleet standard penalty structures, and solid-state battery pilot program timelines. Forecast inputs included lithium carbonate price trajectory assumptions and urban residential charging penetration limits in Indonesian and Vietnamese megacities.
The model holds under continued subsidy eligibility for domestic battery assembly; deviation in FAME II localization enforcement strictness or EU battery passport implementation timing would shift manufacturer competitive positioning and fleet procurement acceleration curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Mobility Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
Electric Vehicle (EV) Coating Market
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
Poland E-Bike Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
Electric Vehicle HVAC Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
Peer-To-Peer Electric Vehicle Charging Market
Electric Vehicles
Silicone in Electric Vehicles Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Electric Vehicle Reducer Market
Electric Vehicles
Electric Light Commercial Vehicle Lithium-Ion Battery Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Middle-East and Africa E-Bike Market